
Market Overview
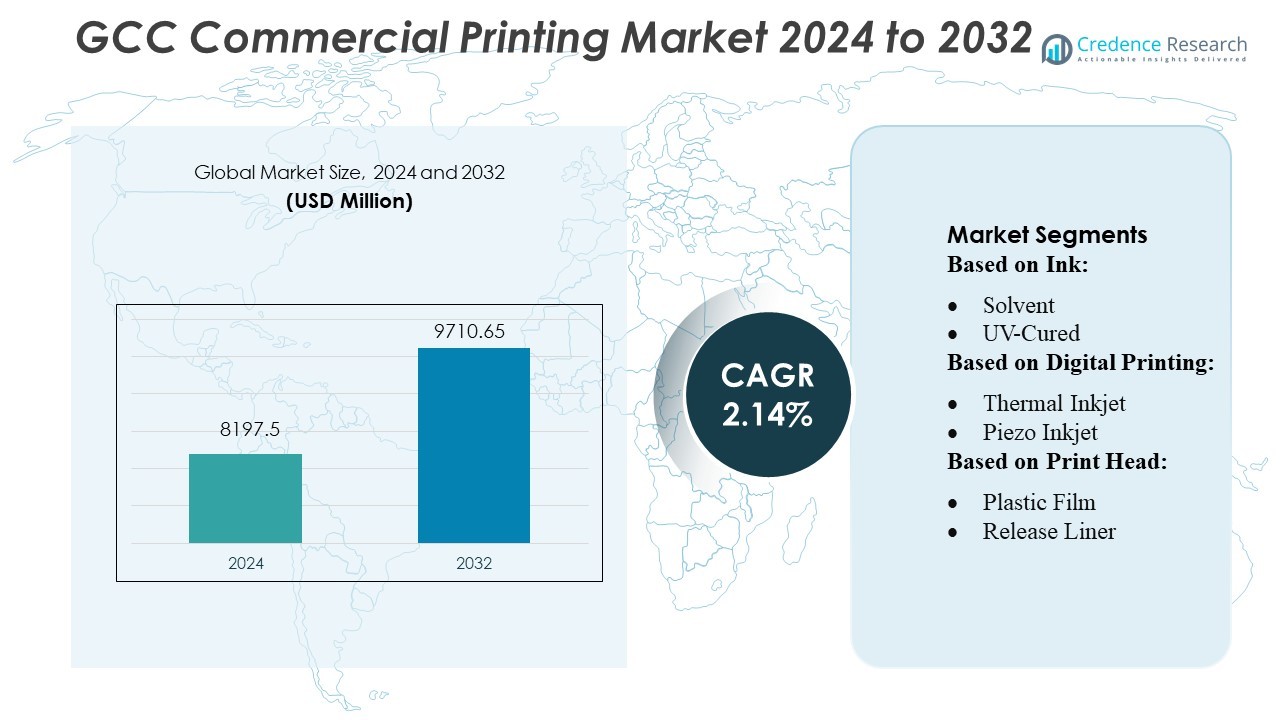
GCC Commercial Printing Market size was valued USD 8197.5 million in 2024 and is anticipated to reach USD 9710.65 million by 2032, at a CAGR of 2.14% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| GCC Commercial Printing Market Size 2024 | USD 8197.5 Million |
| GCC Commercial Printing Market, CAGR | 2.14% |
| GCC Commercial Printing Market Size 2032 | USD 9710.65 Million |
The GCC commercial printing market features strong participation from international and regional players such as Mixam UK Limited, Gorham Printing, Inc., Transcontinental Inc., Quad.com, Dai Nippon Printing Co., Ltd., Cimpres, R.R. Donnelley & Sons Company, Cenveo Worldwide Limited, LSC Communications LLC, and Acme Printing, all of which contribute to technology adoption and quality advancement across the region. Saudi Arabia emerges as the leading regional market, holding an estimated 45% share driven by its large industrial base, expanding retail sector, and sustained investments in high-quality packaging and digital printing solutions. The competitive landscape continues to evolve as companies enhance capabilities, pursue automation, and prioritize faster, more customized print services.
Market Insights
- The GCC Commercial Printing Market was valued at USD 8197.5 million in 2024 and is projected to reach USD 9710.65 million by 2032, registering a CAGR of 2.14% during the forecast period.
- Market growth is driven by rising demand for high-quality packaging, increasing retail and e-commerce activity, and strong adoption of digital printing technologies across key industries.
- Trends such as automation, sustainable materials, and short-run customized printing continue to reshape operational capabilities and improve efficiency among leading players.
- The competitive environment remains dynamic as major international and regional companies enhance their technological portfolios, though high initial investment costs and pricing pressure act as restraints.
- Saudi Arabia leads the regional landscape with 45% market share, while the packaging segment continues to dominate overall demand, supported by rapid industrial expansion across GCC countries.
Market Segmentation Analysis:
By Ink
Solvent inks dominate the GCC commercial printing market, holding the largest share due to their strong adhesion on diverse substrates and suitability for high-durability outdoor applications. Their ability to withstand extreme temperatures and UV exposure aligns well with GCC climatic conditions, driving broad adoption across signage, billboards, and industrial labels. UV-cured inks follow as a high-growth segment supported by faster curing times and reduced VOC emissions. Latex and dye-sublimation inks continue expanding in textile and décor applications, while other specialty inks gain traction in value-added printing solutions.
- For instance, Screen (part of Dainippon Screen) offers the Truepress Jet L350UV label press series for high-throughput label production, utilizing piezo single-pass printheads and UV-curable inks. While the original Truepress Jet L350UV ran at a maximum speed of 50 meters per minute, subsequent models like the Truepress Jet L350UV+ and the Truepress LABEL 350UV SAI S achieve faster web speeds of 60 meters per minute or more, enabling even higher productivity.
By Digital Printing
Digital printers represent the leading sub-segment within the digital printing category, capturing the largest market share driven by rapid turnaround capabilities and the growing shift toward short-run, variable-data printing across retail, packaging, and promotional sectors. Increasing demand for on-demand production and reduced setup costs supports the continued dominance of digital printers. Digital printing inks and printheads follow as essential complementary components, with rising investment in high-resolution printheads and advanced ink formulations that enable improved color accuracy, faster job completion, and enhanced operational efficiency for commercial print service providers.
- For instance, Gorham Printing, Inc. operates its digital book-printing business out of a 7,500-square-foot facility in Centralia, Washington, where the digital pressroom handles custom print runs from 25 up to 5,000 copies per job, according to their official website and guidebook.
By Print Head
Inkjet printheads maintain the dominant share in the GCC market due to their versatility, high-speed performance, and compatibility with multiple ink types used in commercial and wide-format printing. Thermal and piezo inkjet technologies further strengthen adoption, supported by their fine droplet control and ability to deliver sharp image quality. Electrostatic and MEMS inkjet printheads remain niche but gain relevance in high-precision industrial applications. Overall market growth is driven by increasing investment in high-resolution printing, demand for flexible substrates, and the rising need for energy-efficient, low-maintenance printhead technologies.
Key Growth Drivers
1. Rising Demand for Short-Run and On-Demand Printing
The GCC commercial printing market grows significantly as businesses shift toward short-run, customized, and on-demand printing models. Retailers, hospitality brands, and e-commerce platforms increasingly require personalized packaging, promotional materials, and variable-data prints to enhance customer engagement. Digital printing technologies enable faster production cycles and cost efficiency for low-volume jobs, driving operational advantages for print service providers. The expansion of SMEs and start-ups further accelerates demand for flexible printing solutions that support frequent design changes, rapid prototyping, and localized marketing campaigns across GCC countries.
- For instance, Quad integrated the Landa S10P Nanographic Printing Press into its in-store production operations; this press prints at 6,500 sheets per hour, supports full variable-data printing on every sheet regardless of run length, and reproduces 96% of Pantone colors.
2. Expansion of the Advertising and Branding Ecosystem
Large-scale investments across retail, real estate, aviation, and tourism sectors boost printing requirements for signage, outdoor displays, exhibition graphics, and brand activation materials. Mega projects such as new shopping malls, hospitality developments, and entertainment venues significantly increase demand for high-quality wide-format prints. Government-driven economic diversification initiatives encourage businesses to expand their branding footprint, supporting continuous demand for print collateral. As brands focus on premium visual communication and consistent identity across touchpoints, commercial printers benefit from recurring orders and opportunities for long-term service partnerships.
- For instance, DNP added a second wide-range coating device at its Mihara plant capable of handling optical film up to 2,500 mm in width, boosting its production area capacity by more than 15%.
3. Growing Adoption of Digital and Automated Printing Technologies
Digital printing adoption accelerates due to its efficiency, automation potential, and compatibility with diverse substrates. GCC print service providers increasingly invest in high-speed digital presses, UV-curable systems, and advanced workflow automation tools to reduce labor costs and minimize wastage. Automated color calibration, inline finishing, and cloud-enabled print management improve turnaround times and consistency. These capabilities align with the region’s fast-paced retail and commercial environment, supporting high-volume, deadline-driven projects. The shift from analog to digital platforms strengthens operational scalability and drives modernization across the printing ecosystem.
Key Trends & Opportunities
1. Growth of Eco-Friendly and Sustainable Printing Solutions
Sustainability emerges as a major trend as brands and regulatory bodies encourage environmentally responsible printing. The market sees rising adoption of water-based, latex, and low-VOC inks, along with recyclable substrates for packaging and signage. Print service providers increasingly adopt energy-efficient printers and waste-minimization processes to meet green compliance requirements. Eco-certifications create differentiation opportunities for market players, especially in retail and hospitality sectors prioritizing sustainability goals. This shift enables printers to attract premium clients while supporting regional environmental commitments and long-term resource efficiency.
- For instance, R.R. Donnelley & Sons has committed to reducing its greenhouse gas emissions by more than 43,000 metric tons of CO₂e over the next decade, per its 10-year roadmap.
2. Expansion of Packaging and Label Printing Applications
Packaging becomes a high-opportunity segment as consumer goods, food & beverage, pharmaceuticals, and cosmetics industries expand across the GCC. Growth in e-commerce and home-delivery services amplifies demand for corrugated packaging, product labels, and custom-branded boxes. Digital and hybrid printing systems enable shorter runs, faster changeovers, and high-quality graphics tailored to promotional cycles. Value-added features such as anti-counterfeit printing, variable QR codes, and personalization further strengthen opportunities. The shift toward premium and visually appealing packaging enhances market potential for high-resolution, multi-color commercial printing solutions.
- For instance, LSC invested in HP PageWide Web Press T490 HD technology for digital book production and upgraded existing PageWide presses with HDNA (High Definition Nozzle Architecture), enabling higher print quality and improved productivity.
3. Increasing Use of Wide-Format and Large-Format Printing
Large-format printing continues to grow due to increasing requirements for outdoor advertising, fleet graphics, building wraps, and event branding. GCC’s active construction and retail development projects create strong demand for façade banners, directional signage, and interior décor prints. Advancements in UV-cured and latex printing technologies enable faster production, higher durability, and better weather resistance-critical for harsh regional climates. The growing popularity of fabric-based soft signage and backlit displays provides additional avenues for innovation. This segment offers profitable expansion opportunities for commercial print service providers.
Key Challenges
1. Volatility in Raw Material and Equipment Costs
Fluctuations in the cost of inks, substrates, printing chemicals, and imported equipment challenge profitability for print service providers. Dependence on international supply chains exposes the market to currency variations, shipping delays, and geopolitical disruptions. High upfront investment in advanced digital presses and printhead technologies becomes a barrier for smaller firms. Rising operational costs, including energy and skilled labor, further pressure margins. Printers must adopt efficient procurement strategies and automation to maintain cost competitiveness while ensuring consistent production quality.
2. Competition from Digital Media and Declining Traditional Print Demand
The growing shift toward digital marketing, online advertising, and electronic communication threatens traditional print categories such as brochures, magazines, and corporate documents. Businesses increasingly reduce spending on conventional print materials, redirecting budgets to digital channels with measurable audience reach. This shift forces commercial printers to adapt their offerings, diversify into packaging or large-format printing, and invest in value-added services. Companies unable to modernize face declining demand and reduced profitability. Continuous innovation and service differentiation are essential to remain competitive in a digitally evolving landscape.
Regional Analysis
North America
North America holds about 30% of the global commercial printing market and remains one of the most technologically advanced regions. The United States drives the majority of demand due to its strong presence in packaging, publishing, retail marketing, and corporate communication materials. The region benefits from widespread adoption of digital printing, variable-data printing, and automated workflow systems that enhance speed and efficiency. Growth is further supported by sustained investments in sustainable substrates, energy-efficient presses, and premium print services. Although traditional offset printing remains relevant, the shift toward short-run, on-demand printing continues to strengthen the region’s competitive position.
Asia-Pacific
Asia-Pacific accounts for approximately 35% of the global commercial printing market, making it the largest and fastest-expanding regional contributor. The region’s growth is driven by strong industrialization, rapid urbanization, and rising consumption across China, India, Southeast Asia, and Japan. Demand is fueled by booming e-commerce, large-scale manufacturing, and high requirements for labels, packaging, and promotional prints. Print service providers in Asia-Pacific increasingly invest in digital presses, flexographic systems, and high-volume packaging equipment to meet fast-turnaround expectations. Cost-efficient production capabilities, a massive customer base, and continuous technological upgrades solidify the region’s dominant position.
Europe
Europe represents roughly 25% of the global commercial printing market and is known for its advanced production capabilities and strong emphasis on quality and sustainability. Countries such as Germany, the UK, France, and Italy lead adoption of eco-friendly inks, recyclable materials, and digital automation to meet strict environmental regulations. The region benefits from stable demand in luxury packaging, premium promotional materials, specialty publishing, and corporate branding. Although the market is mature, European printers continue to innovate in high-precision printing, variable-data output, and specialty finishing techniques. These strengths ensure Europe maintains a solid and competitive market presence.
Latin America
Latin America holds close to 8% of the global commercial printing market, supported by growing retail activity, expanding consumer goods production, and increased investment in advertising materials. Brazil and Mexico dominate the regional landscape with rising needs for packaging, labels, brochures, and promotional prints. While offset printing still accounts for much of the volume, digital printing adoption is increasing as businesses seek cost-efficient, short-run, high-quality output. Urbanization and expanding middle-class consumption continue to generate steady demand, even as economic variability presents challenges. Overall, the region shows healthy long-term growth potential driven by modernization and diversification.
Middle East & Africa
The Middle East & Africa region contributes about 7% of the global commercial printing market and demonstrates gradual but steady expansion. The UAE and Saudi Arabia lead the market with strong demand for high-end packaging, signage, promotional prints, and large-format advertising materials. Rapid growth in tourism, retail, and infrastructure stimulates continuous print requirements across commercial sectors. Meanwhile, African markets such as South Africa and Nigeria show increasing demand in education, FMCG packaging, and government communication materials. Printers across MEA are investing in digital technologies, sustainable materials, and workflow automation, supporting the region’s ongoing modernization and upward momentum.
Market Segmentations:
By Ink:
- Solvent
- UV-Cured
By Digital Printing:
- Thermal Inkjet
- Piezo Inkjet
By Print Head:
- Plastic Film
- Release Liner
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the GCC commercial printing market features a mix of global and regional players, with leading international companies such as Mixam UK Limited, Gorham Printing, Inc., Transcontinental Inc., Quad.com, Dai Nippon Printing Co., Ltd., Cimpres, R.R. Donnelley & Sons Company, Cenveo Worldwide Limited, LSC Communications LLC, and Acme Printing. The GCC commercial printing market is characterized by rising digital adoption, expanding service portfolios, and increasing investments in high-quality, technology-driven printing solutions. Companies across the region focus on modernizing their production environments through automated workflows, advanced digital and large-format presses, and environmentally sustainable materials to meet evolving customer expectations. Competition intensifies as firms differentiate through faster turnaround times, enhanced print precision, and customizable short-run jobs tailored to retail, packaging, corporate, and advertising clients. Regional printers also benefit from growing demand in e-commerce packaging, event marketing, and tourism-driven promotional prints, prompting continuous upgrades in capability, efficiency, and service innovation.
Key Player Analysis
- Mixam UK Limited
- Gorham Printing, Inc.
- Transcontinental Inc.
- Dai Nippon Printing Co., Ltd.
- Cimpres
- R. Donnelley & Sons Company
- Cenveo Worldwide Limited
- LSC Communications LLC
- Acme Printing
Recent Developments
- In September 2024, Artisan Colour acquired MarComm, a digital marketing agency, to offer an integrated print and digital marketing solution. This move combines Artisan Colour's commercial printing and color management expertise with MarComm's digital marketing and cross-channel strategy skills, aiming to provide a single partner for a unified marketing ecosystem.
- In May 2024, Canon and Heidelberg collaborated to integrate inkjet printing solutions into the commercial printing industry. Heidelberg will integrate Canon's B2 and B3 sheetfed inkjet presses into their Prinect workflow.
- In March 2024, Mimaki Engineering Co., Ltd. announced the launch of TRAPIS, an environmentally next-generation textile printing system. The TRAPIS system utilizes a heat transfer machine to transfer a design printed on special paper onto fabric, resulting in a textile printing process that generates minimal wastewater.
Report Coverage
The research report offers an in-depth analysis based on Ink, Digital Printing, Print Head and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to shift further toward digital printing as businesses demand faster turnaround times and greater customization.
- Packaging printing is likely to grow steadily due to expanding retail, FMCG, and e-commerce sectors across the GCC.
- Print service providers are expected to invest more in automation to reduce operational costs and improve workflow efficiency.
- Demand for sustainable inks, recyclable substrates, and eco-friendly production methods will continue to rise.
- Large-format and signage printing will gain momentum as tourism, events, and infrastructure projects expand.
- Variable-data printing is set to increase as brands focus on personalized marketing campaigns.
- Hybrid printing solutions integrating digital and offset technologies will become more common across commercial facilities.
- Regional printers are expected to diversify into value-added services such as finishing, specialty coatings, and premium packaging.
- Cross-border printing partnerships may grow as GCC countries strengthen trade links and regional logistics networks.
- Market competitiveness will intensify as both local and international players enhance capabilities to meet evolving quality and speed requirements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Short-Run and On-Demand Printing
Businesses in the GCC increasingly require customized, short-run, and on-demand print jobs for packaging, promotional materials, and variable-data marketing, driving adoption of digital printing technologies that enable rapid turnaround and cost-effective production for low-volume orders.
Expansion of Retail, E-Commerce, and Packaging Needs
The growth of retail and e-commerce sectors in the GCC fuels demand for high-quality packaging, labels, and branded materials, making packaging the dominant application and spurring investment in advanced printing solutions tailored to fast-moving consumer goods and logistics.
Adoption of Digital and Automated Printing Technologies
Print service providers are investing in high-speed digital presses, UV-curable systems, and workflow automation to improve efficiency, reduce labor costs, and meet the region’s demand for faster, more flexible, and higher-quality print services.
Sustainability and Eco-Friendly Printing Solutions
Rising regulatory and consumer focus on sustainability is driving the adoption of water-based, latex, and low-VOC inks, as well as recyclable substrates and energy-efficient production methods, enabling printers to differentiate and attract environmentally conscious clients.
Growth in Large-Format and Signage Printing
Ongoing infrastructure, tourism, and retail development projects across the GCC are increasing demand for wide-format and large-format prints such as signage, building wraps, and event graphics, supporting market expansion in these high-value segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the GCC Commercial Printing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the GCC Commercial Printing Market projected to grow between 2025 and 2032?
Which GCC Commercial Printing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the GCC Commercial Printing Market?
Who are the leading companies in the GCC Commercial Printing Market?
Which region commanded the largest share of the GCC Commercial Printing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Ink
- 1.2.1 Solvent
- 1.2.2 UV-Cured
- 1.2.3 Latex
- 1.2.4 Dye-Sublimation
- 1.2.5 Other Specialty Inks
- 1.3 By Print Head
- 1.3.1 Inkjet Printheads
- 1.3.2 Thermal Inkjet
- 1.3.3 Piezo Inkjet
- 1.3.4 Electrostatic/MEMS
- 1.4 By Application
- 1.4.1 Packaging
- 1.4.2 Signage & Outdoor Advertising
- 1.4.3 Promotional Materials
- 1.4.4 Publishing
- 1.4.5 Textiles & Décor
- 1.5 By Digital Printing
- 1.5.1 Digital Printers
- 1.5.2 Digital Printing Inks
- 1.5.3 Printheads
- 1.5.4 Workflow Automation Tools
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8197.5 million → 2032: USD 9710.65 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 GCC Commercial Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 GCC Commercial Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 GCC Commercial Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 GCC Commercial Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 GCC Commercial Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 GCC Commercial Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 GCC Commercial Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 GCC Commercial Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8197.5 million → 2032: USD 9710.65 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 GCC Commercial Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Ink - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solvent
- 12.3.7.2 UV-Cured
- 12.3.7.3 Latex
- 12.3.7.4 Dye-Sublimation
- 12.3.7.5 Other Specialty Inks
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Print Head - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Inkjet Printheads
- 12.4.7.2 Thermal Inkjet
- 12.4.7.3 Piezo Inkjet
- 12.4.7.4 Electrostatic/MEMS
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Packaging
- 12.5.7.2 Signage & Outdoor Advertising
- 12.5.7.3 Promotional Materials
- 12.5.7.4 Publishing
- 12.5.7.5 Textiles & Décor
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Digital Printing - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Digital Printers
- 12.6.7.2 Digital Printing Inks
- 12.6.7.3 Printheads
- 12.6.7.4 Workflow Automation Tools
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 GCC Commercial Printing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 GCC Commercial Printing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 GCC Commercial Printing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 GCC Commercial Printing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mixam UK Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Gorham Printing, Inc.
- 18.4 Transcontinental Inc.
- 18.5 Quad.com
- 18.6 Dai Nippon Printing Co., Ltd.
- 18.7 Cimpres
- 18.8 R.R. Donnelley & Sons Company
- 18.9 Cenveo Worldwide Limited
- 18.10 LSC Communications LLC
- 18.11 Acme Printing
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

