
Market Overview
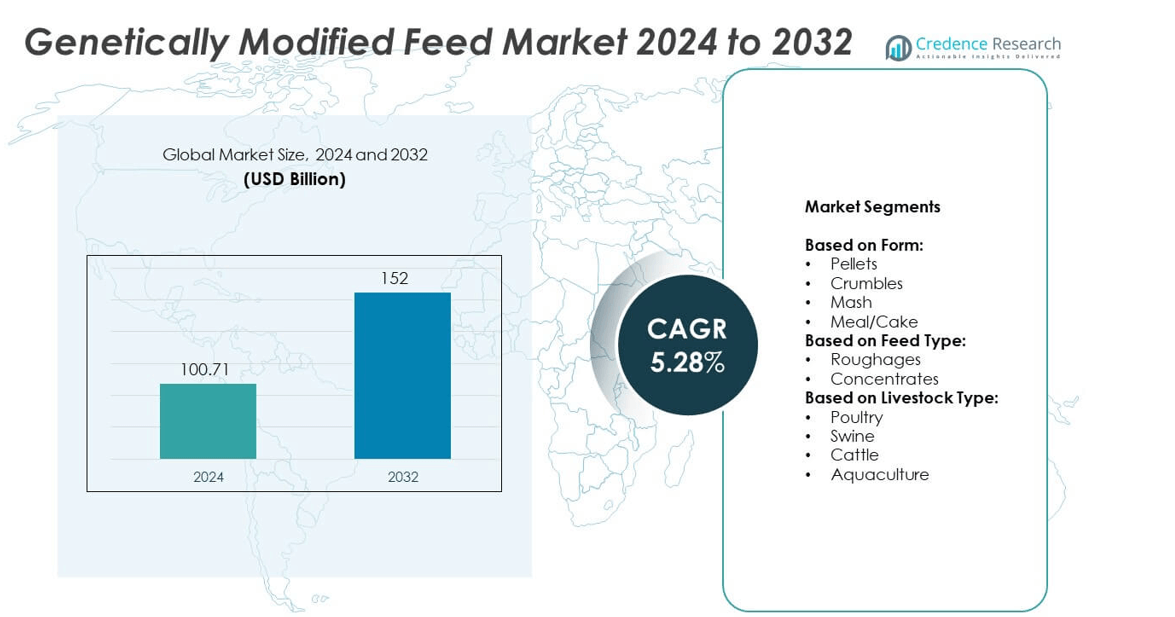
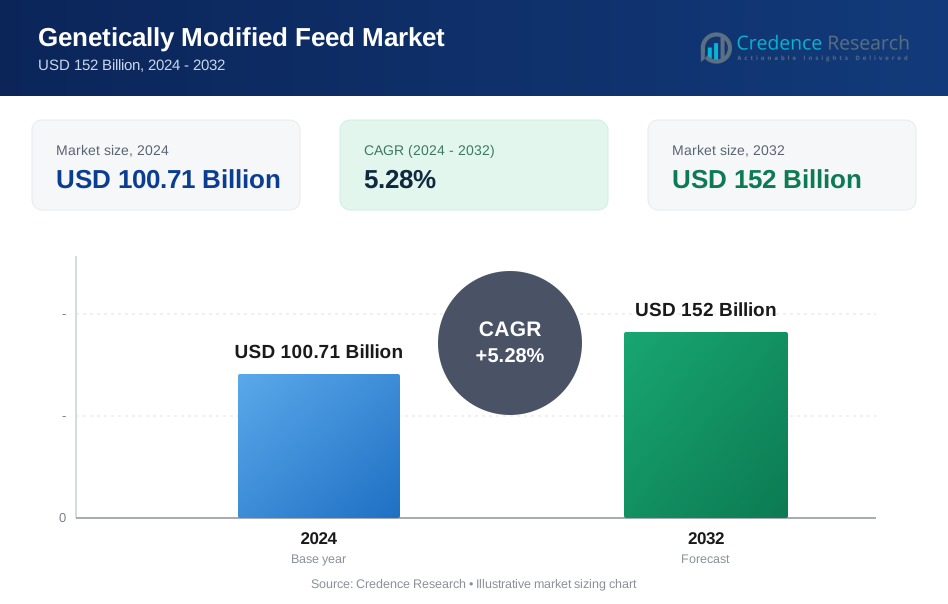
Genetically Modified Feed Market size was valued at USD 100.71 Billion in 2024 and is anticipated to reach USD 152 Billion by 2032, at a CAGR of 5.28% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Genetically Modified Feed Market Size 2024 | USD 100.71 Billion |
| Genetically Modified Feed Market , CAGR | 5.28% |
| Genetically Modified Feed Market Size 2032 | USD 152 Billion |
The Genetically Modified Feed market grows due to rising livestock production, increasing demand for protein-rich diets, and the need for efficient feed solutions. Farmers adopt genetically modified crops for higher yields, pest resistance, and consistent nutrient content. Biotechnology integration with precision farming improves productivity and sustainability. Expanding global trade networks ensure reliable feed supply across regions. The market benefits from regulatory support in key countries and evolving consumer demand for affordable, high-quality meat, dairy, and aquaculture products.
North America leads the Genetically Modified Feed market with advanced biotechnology adoption and strong livestock demand, while Asia Pacific shows rapid growth driven by expanding poultry and aquaculture industries. Europe relies on imports to meet protein needs under strict regulatory frameworks, whereas Latin America plays a dual role as both a producer and exporter of soybean and maize feed. Key players shaping the market landscape include Bayer AG, BASF SE, Corteva Agriscience, and Syngenta Crop Protection AG.
Market Insights
- The Genetically Modified Feed market was valued at USD 100.71 Billion in 2024 and is projected to reach USD 152 Billion by 2032, growing at a CAGR of 5.28%.
- Rising demand for protein-rich diets and increasing livestock production are driving adoption of genetically modified feed worldwide.
- Growing use of herbicide-tolerant and pest-resistant crops reflects a major trend, ensuring stable yields and reliable feed supply.
- Competitive dynamics are shaped by innovation in crop traits, partnerships with feed processors, and global distribution networks.
- Strict regulatory frameworks, public perception issues, and trade restrictions act as restraints limiting faster expansion of genetically modified feed.
- North America leads due to large-scale adoption of modified crops, Europe depends on imports under tight regulations, Asia Pacific shows strong growth from poultry and aquaculture demand, Latin America plays a key role in exports, and the Middle East and Africa rely on trade for supply security.
- Continuous advancements in biotechnology and increasing global trade integration provide long-term opportunities, strengthening feed security across emerging and developed markets.
Market Drivers
Rising Demand for High-Yield Livestock Production
The Genetically Modified Feed market benefits from growing livestock production to meet global protein needs. Farmers adopt genetically modified feed to enhance animal growth rates and optimize feed conversion. It supports consistent weight gain in poultry, cattle, and swine. Consumers expect stable meat, milk, and egg supplies, driving reliance on high-performance feed. Increasing population in developing nations strengthens demand for efficient feed solutions. Genetic traits in modified crops ensure reliable nutrient content for intensive farming systems.
- For instance, Studies on broiler birds supplemented with Diamond V XPC have shown mixed results regarding feed intake. While a study found a reduction in feed intake and improved feed efficiency with XPC added at 1.25% to 2% of the feed, other research has yielded different conclusions, with some studies finding an increase in feed intake and others reporting no significant impact
Improved Resistance Against Crop Diseases and Pests
The market grows due to genetically modified feed crops offering resistance to pests and diseases. It reduces losses in corn, soybean, and canola production, ensuring stable feed supplies. Lower dependency on chemical pesticides aligns with farm sustainability goals. Farmers achieve higher output per acre, securing long-term feed availability. Improved resistance lowers risks of supply shortages during unfavorable seasons. The consistent quality of modified crops supports large-scale commercial feed operations.
- For instance, field-evolved resistance to the Cry1F protein was documented in ECB populations in Canada as of 2018. A report submitted to the EU in November 2024 detailed the cultivation of MON 810 Bt maize in Europe for the 2023 growing season, covering approximately 48,225 hectares (roughly 119,166 acres) in Spain and Portugal.
Enhanced Nutritional Content for Animal Health
The Genetically Modified Feed market advances through crops engineered with superior nutrient levels. It improves protein, amino acids, and oil content in feed ingredients. Livestock health benefits from balanced nutrition, reducing veterinary costs for farmers. Modified soybean and maize strains deliver optimized energy and digestibility. Consistent nutrient profiles enhance animal productivity and product quality. Nutritionally enriched feed supports commercial farms targeting premium output standards.
Support from Global Regulatory and Trade Policies
The market gains momentum from favorable policies and acceptance of genetically modified feed in global trade. It ensures steady cross-border supply of corn and soymeal. Governments recognize its role in reducing agricultural pressure on land and resources. Trade agreements increasingly include provisions for modified crops. International demand for cost-effective feed imports continues to rise. Regulatory frameworks create a stable foundation for long-term industry adoption.
Market Trends
Growing Adoption of Herbicide-Tolerant and Insect-Resistant Crops
The Genetically Modified Feed market shows strong adoption of herbicide-tolerant and insect-resistant crops. Farmers prefer soybean, maize, and cotton varieties with proven field performance. It reduces input costs by minimizing crop loss from weeds and pests. Stable harvests improve feed supply reliability for intensive livestock farming. Adoption expands in emerging economies with rising agricultural mechanization. These crop traits continue to drive large-scale feed production efficiency.
- For instance, a study on improved maize hybrids with introgressed genes reported lysine content of 0.367% in flour compared to 0.150-0.250% in standard maize.
Integration of Biotechnology with Precision Farming Practices
The market reflects integration of biotechnology with precision agriculture for higher productivity. It enables accurate use of modified seeds with GPS, sensors, and smart irrigation. Farmers achieve higher yield per acre with optimized resource use. Precision tools help measure feed crop output with greater accuracy. It enhances sustainability while reducing environmental impact in commercial farming. The trend accelerates with digital agriculture investments in key producing regions.
- For instance, Brazil is a major global exporter of corn, with exports to Asia, particularly China, significantly increasing since 2022 due to a trade agreement. Brazil's total corn exports were around 55.35 million metric tons in 2023.
Focus on Sustainable and Low-Input Farming Systems
The Genetically Modified Feed market aligns with sustainability goals in global agriculture. Crops engineered for drought tolerance and low fertilizer needs gain attention. It supports farming practices that conserve water and reduce chemical reliance. Sustainability certifications strengthen acceptance among global buyers. Farmers adapt these systems to meet rising consumer demand for eco-friendly products. Long-term adoption of such crops secures resilient feed supply chains.
Expansion of International Trade in GM Feed Crops
The market expands with strong international trade of genetically modified corn and soybean meal. Exporters secure competitive advantage with large-scale production capabilities. It ensures steady imports for countries with limited agricultural resources. Trade partnerships strengthen supply networks across Asia, Europe, and the Middle East. Regulatory approvals across regions increase acceptance of modified crops. Expanding global trade reinforces growth in feed manufacturing hubs.
Market Challenges Analysis
Regulatory Barriers and Public Perception Issues
The Genetically Modified Feed market faces obstacles from strict regulatory frameworks in several regions. Governments impose rigorous approval processes that delay crop adoption. It creates uncertainty for farmers and feed producers planning large-scale use. Public perception remains divided, with consumer groups opposing genetically modified ingredients. Concerns over food safety and environmental risks limit acceptance in key markets. Such barriers restrict smooth expansion despite technological progress and proven benefits.
Supply Chain Disruptions and Trade Restrictions
The market experiences challenges from global supply chain disruptions and trade restrictions. Weather extremes, transport delays, and geopolitical conflicts interrupt steady feed crop movement. It raises costs for producers reliant on imported soybean and maize. Export bans and regional trade disputes further strain supply availability. Feed manufacturers must balance volatile costs while meeting livestock sector demand. These challenges pressure margins and reduce predictability in long-term feed planning.
Market Opportunities
Rising Demand for Protein-Rich Diets in Emerging Economies
The Genetically Modified Feed market offers opportunities from increasing meat and dairy consumption in developing nations. Expanding middle-class populations in Asia and Latin America drive demand for protein-rich diets. It creates strong need for efficient feed solutions to support livestock growth. Genetically modified crops with higher yields and stable nutrition address this demand effectively. Governments in these regions invest in agricultural modernization to secure food supply. Expanding livestock farming opens new revenue streams for feed producers.
Advancements in Crop Engineering and Trait Development
Opportunities emerge from advancements in crop engineering that improve feed crop efficiency. It allows the development of varieties with drought tolerance, higher nutrient density, and lower resource requirements. These innovations meet sustainability goals while improving farm profitability. Feed producers gain advantage by offering consistent quality inputs for animal health. International trade potential grows with wider acceptance of genetically modified crops. Expanding trait innovations create long-term opportunities for global feed supply networks.
Market Segmentation Analysis:
By Form:
The Genetically Modified Feed market includes pellets, crumbles, mash, and meal or cake. Pellets dominate due to ease of storage, transportation, and controlled nutrient delivery. Crumbles are widely used in poultry production for young birds requiring smaller feed sizes. Mash remains important in traditional farming setups where low processing costs matter. Meal or cake derived from soybean and canola supports protein-rich diets for livestock. It ensures flexibility for farmers to choose feed formats based on efficiency and cost-effectiveness.
- For instance, According to Corteva's 2023 Sustainability Report, the company's focus on sustainable innovation includes developing new technologies for genetic gain, such as enhanced seed varieties. The report states that from 2021 to 2023, Corteva supported 4.2 million acres with biodiversity and outcomes aligned with regenerative agriculture
By Feed Type:
The market is divided into roughages and concentrates. Concentrates hold the largest share because of their nutrient density and contribution to faster growth cycles. Roughages are still necessary for ruminants, particularly cattle, where fiber intake is vital. It provides balance in livestock nutrition by complementing high-energy concentrates. Farmers rely on genetically modified crops such as corn and soymeal to produce efficient concentrate feeds. This segment benefits from large-scale production capabilities in major agricultural regions.
- For instance, John Deere manufactures precision planting systems, such as the ExactEmerge planter, which uses electric drives for precise seed placement even at fast planting speeds. The company also offers the ExactShot planting technology, introduced at CES 2023, which reduces starter fertilizer usage by more than 60% by precisely applying fertilizer onto each seed as it is planted
By Livestock Type:
The Genetically Modified Feed market serves poultry, swine, cattle, and aquaculture. Poultry dominates due to rising global consumption of chicken meat and eggs. Swine production relies on energy-dense feed to improve feed-to-meat conversion rates. Cattle segment benefits from protein-rich soybean meal that supports milk and beef productivity. Aquaculture shows rapid growth with genetically modified soybean meal replacing traditional fishmeal. It ensures sustainable alternatives for the seafood industry facing supply constraints. This diverse livestock adoption strengthens demand for genetically modified feed across global markets.
Segments:
Based on Form:
- Pellets
- Crumbles
- Mash
- Meal/Cake
Based on Feed Type:
- Roughages
- Concentrates
Based on Livestock Type:
- Poultry
- Swine
- Cattle
- Aquaculture
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Genetically Modified Feed market with 38%. The region leads due to extensive cultivation of genetically modified corn and soybean used in feed formulations. Farmers in the United States and Canada benefit from advanced biotechnology adoption and favorable regulations supporting genetically modified crops. It ensures consistent feed supply for a highly developed livestock and poultry industry. Strong presence of agribusiness giants and established trade networks further reinforces market leadership. The demand for protein-rich meat and dairy products continues to expand, driving long-term feed adoption across commercial farming systems.
Europe
Europe accounts for 22% of the Genetically Modified Feed market, supported by imports of soybean and maize from North and South America. The European Union enforces strict approval processes, but consistent demand for animal protein sustains feed imports. It reflects the region’s reliance on genetically modified raw materials despite cautious regulatory frameworks. Countries like Spain and the Netherlands play a vital role in feed processing and distribution. Rising livestock production in these nations strengthens regional consumption. The feed sector adapts to sustainability goals while balancing consumer concerns about genetically modified inputs.
Asia Pacific
Asia Pacific represents 28% of the Genetically Modified Feed market, driven by rapid expansion of livestock farming in China, India, and Southeast Asia. Poultry and aquaculture industries experience strong growth due to increasing protein consumption across urban populations. It secures higher feed demand supported by large-scale soybean and maize imports from the Americas. Domestic production of genetically modified crops in countries like China also contributes to regional growth. Farmers adopt feed solutions that enhance efficiency and reduce input costs. Expanding middle-class income levels create steady opportunities for global feed suppliers targeting the region.
Latin America
Latin America contributes 8% to the Genetically Modified Feed market, with Brazil and Argentina leading in soybean and maize production. The region not only consumes but also exports large volumes of feed crops worldwide. It holds competitive advantage due to large-scale cultivation of genetically modified seeds and favorable climatic conditions. Domestic livestock industries in Brazil and Argentina expand rapidly, fueling local feed usage. Trade policies encourage strong international partnerships, boosting exports to Asia and Europe. Rising investments in feed processing facilities strengthen the region’s role in the global supply chain.
Middle East and Africa
Middle East and Africa hold 4% share of the Genetically Modified Feed market, relying heavily on imports to meet feed requirements. Limited arable land and water scarcity restrict large-scale crop cultivation. It increases dependency on global suppliers for soybean meal and maize feed. Poultry and dairy farming sectors grow steadily to meet urban consumer demand for protein. Governments focus on securing food supplies through long-term trade agreements with exporting nations. Investments in aquaculture projects further support gradual expansion of genetically modified feed in the region.
Key Player Analysis
- Stine Seed Company
- Bayer AG
- Tyson Foods
- Anderson Exports
- KWS SAAT SE & Co. KGaA
- R. Simplot Company
- BASF SE
- Okanagan Specialty Fruits Inc.
- Groupe Limagrain Holding
- Syngenta Crop Protection AG
- Corteva Agriscience
Competitive Analysis
The leading players in the Genetically Modified Feed market include Stine Seed Company, Bayer AG, Tyson Foods, Anderson Exports, KWS SAAT SE & Co. KGaA, J.R. Simplot Company, BASF SE, Okanagan Specialty Fruits Inc., Groupe Limagrain Holding, Syngenta Crop Protection AG, and Corteva Agriscience. These companies play a central role in shaping the competitive environment through advanced seed technologies, feed innovations, and strong global distribution networks. Their strategies emphasize high-yield crop development, enhanced nutritional value, and sustainable farming practices to meet the rising global protein demand. Competition in the market is defined by continuous investment in biotechnology and trait development. Companies strengthen their portfolios with herbicide-tolerant and pest-resistant crops that improve farm efficiency and feed reliability. Expansion into emerging economies provides further opportunities as livestock production grows rapidly. Strategic partnerships with distributors and feed processors enhance market presence across key regions. Players also prioritize regulatory compliance and sustainability, aligning with government policies and international trade requirements. The market remains highly competitive, with firms leveraging innovation, scale, and supply chain strength to maintain leadership. Continuous improvements in genetically modified crop performance and tailored feed solutions will sustain competitive momentum across global markets.
Recent Developments
- In 2025, BASF signed a trait licensing agreement with Corteva Agriscience and M.S. Technologies, L.L.C. to bring a novel nematode-resistant soybean trait (NRS) combined with Enlist E3® and Conkesta E3® soybeans to market in Brazil
- In 2025, Corteva partnered with BASF and M.S. Technologies to license and commercialize the nematode-resistant soybean trait incorporated into its Enlist E3® and Conkesta E3® soybean technologies for Brazilian markets
- In 2024, Bayer licensed gene-edited mustard greens (CRISPR-developed) from Pairwise for grocery store distribution across the US, targeting consumer-friendly traits with improved taste and nutritio
Report Coverage
The research report offers an in-depth analysis based on Form, Feed Type, Livestock Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Genetically Modified Feed market will expand with rising global protein demand.
- Adoption of high-yield genetically modified crops will strengthen livestock feed supply.
- It will benefit from advances in crop engineering for drought and pest resistance.
- Regulatory approvals in new regions will support broader market acceptance.
- Livestock producers will prefer nutritionally enhanced feed for better productivity.
- International trade of soybean and maize will remain central to feed availability.
- Growing aquaculture industries will drive demand for sustainable feed alternatives.
- It will align with sustainability goals by reducing reliance on chemicals and water.
- Investments in precision agriculture will optimize genetically modified feed production.
- Expansion in emerging economies will create significant long-term growth opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Genetically Modified Feed market, and what is its projected size in 2032?
Which Genetically Modified Feed market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Genetically Modified Feed market?
Who are the leading companies in the Genetically Modified Feed Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Genetically Modified Feed Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Genetically Modified Feed Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 100.71 Billion → 2032: USD 152 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Genetically Modified Feed Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Genetically Modified Feed Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Genetically Modified Feed Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Genetically Modified Feed Market Drivers
- 3.3 Genetically Modified Feed Market Restraints & Challenges
- 3.4 Genetically Modified Feed Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Genetically Modified Feed Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Genetically Modified Feed Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Genetically Modified Feed category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Genetically Modified Feed Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Genetically Modified Feed Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Genetically Modified Feed market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Genetically Modified Feed Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Genetically Modified Feed Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Genetically Modified Feed Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Genetically Modified Feed (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Genetically Modified Feed Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Genetically Modified Feed Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Genetically Modified Feed Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Genetically Modified Feed Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Genetically Modified Feed Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Genetically Modified Feed Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Genetically Modified Feed Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Genetically Modified Feed Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Genetically Modified Feed Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
