
Market Overview
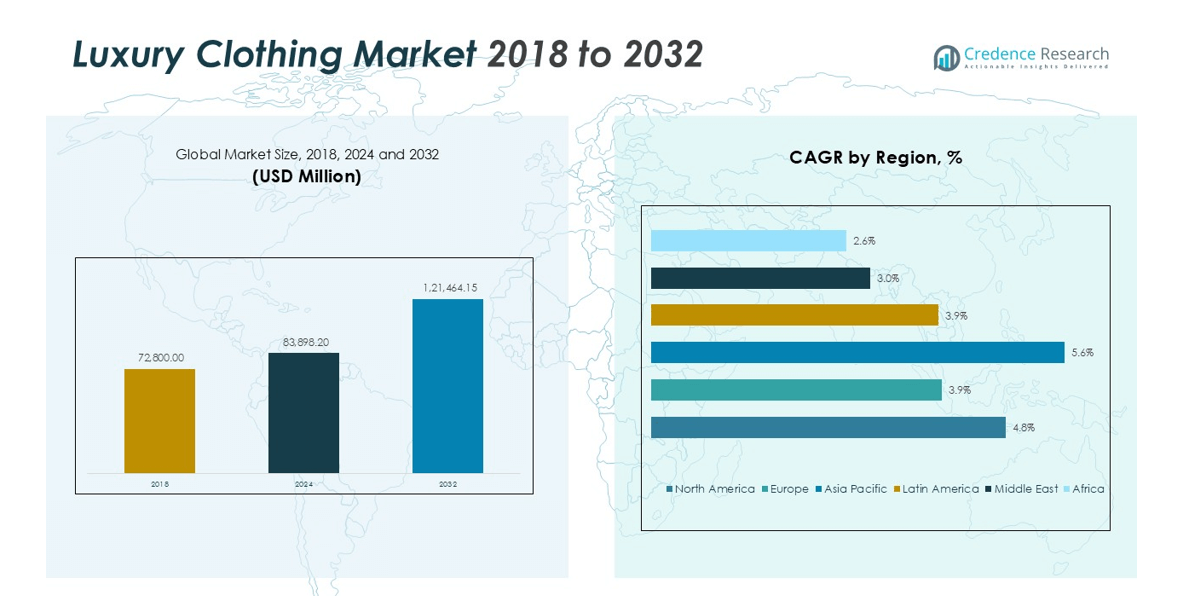
The Global Luxury Clothing Market size was valued at USD 72,800.00 million in 2018 and increased to USD 83,898.20 million in 2024. It is anticipated to reach USD 121,464.15 million by 2032, growing at a CAGR of 4.79% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Clothing Market Size 2024 | USD 83,898.20 million |
| Luxury Clothing Market, CAGR | 4.79% |
| Luxury Clothing Market Size 2032 | USD 121,464.15 million |
The global Luxury Clothing Market is dominated by leading brands such as Gucci, Prada, Burberry, Dolce & Gabbana, Giorgio Armani, Calvin Klein, Valentino, Kate Spade, and Phillip Lim. These companies maintain their competitive edge through strong brand heritage, innovation in design, and global retail expansion. They continually invest in digital transformation, sustainability initiatives, and limited-edition collections to strengthen exclusivity and appeal to younger consumers. Among all regions, Europe leads the market with a 34.8% share in 2024, driven by its legacy fashion houses, high tourism inflows, and established luxury retail hubs in Paris, Milan, and London.
Market Insights
- The global Luxury Clothing Market was valued at USD 83,898.20 million in 2024 and is projected to reach USD 121,464.15 million by 2032, growing at a CAGR of 4.79% during the forecast period.
- The market growth is driven by increasing disposable incomes, rising fashion consciousness, and the expanding influence of celebrity endorsements and social media platforms that boost premium apparel demand.
- Key trends include the growing shift toward sustainable luxury fashion, digital transformation, and personalization through made-to-order collections catering to individual preferences.
- The market is highly competitive, with major players such as Gucci, Prada, Burberry, Dolce & Gabbana, and Valentino dominating through innovation, product exclusivity, and global retail presence.
- Asia Pacific leads the market with a 6% share, supported by heritage fashion houses and strong retail networks, while the women’s segment accounts for 62.4% of total revenue due to continuous demand for premium designer wear.
Market Segmentation Analysis:
By End Use:
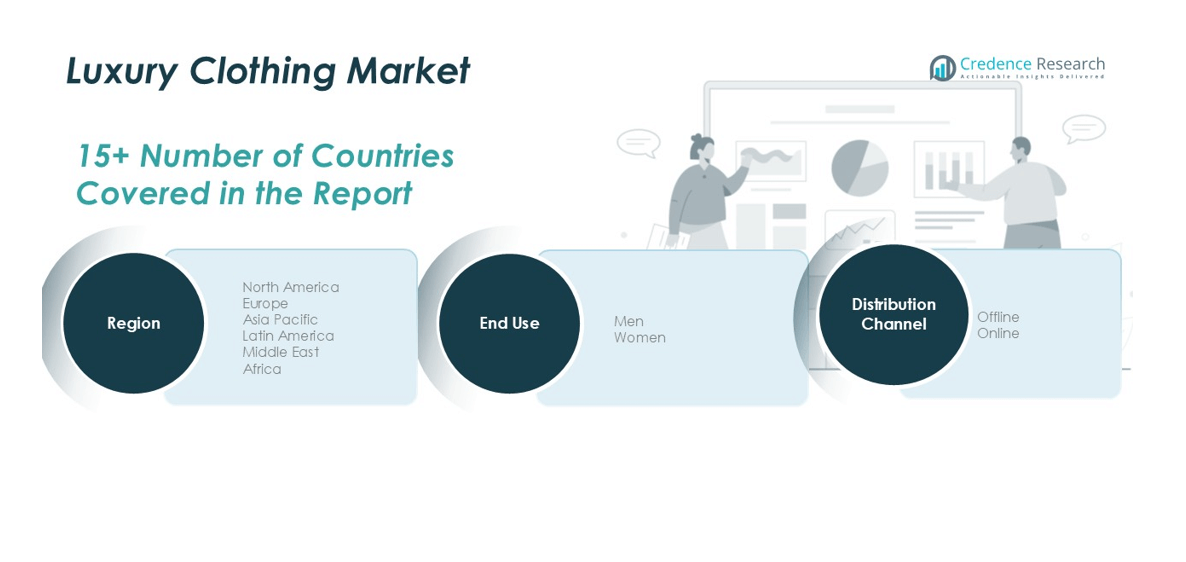
The women’s segment dominated the global luxury clothing market in 2024, accounting for 62.4% of total revenue. This dominance is driven by higher spending on fashion apparel, frequent seasonal launches, and the growing influence of social media trends. Premium brands continually introduce exclusive collections for women, emphasizing craftsmanship, sustainability, and brand heritage. Additionally, the rise of online fashion influencers and luxury collaborations with female celebrities have accelerated demand. The men’s segment, while smaller, is expanding steadily due to rising interest in tailored wear and luxury streetwear among younger professionals.
- For instance, NIYARA India, a premium women's fashion apparel brand, launched its exclusive online store with a target of achieving a turnover of INR 5 crore in its first year, delivering high-quality, stylish, and accessible fashion tailored to modern Indian women.
By Distribution Channel:
The offline retail segment held the largest share of 68.7% in 2024, supported by the immersive brand experience offered in luxury boutiques, departmental stores, and exclusive brand outlets. Consumers prefer in-person shopping to experience fabric quality, fitting, and personalized styling. Flagship stores in fashion capitals such as Paris, Milan, and New York further strengthen brand perception and exclusivity. However, the online retail segment is gaining traction, driven by digital transformation, e-commerce platforms, and virtual showrooms enhancing convenience for tech-savvy luxury consumers.
- For example, Zegna disclosed that its men’s luxury apparel business achieved sales of about €1.3 billion in 2023, showing real growth momentum in the men’s domain.
Key Growth Drivers
Rising Disposable Income and Urbanization
Increasing disposable incomes and rapid urbanization across emerging economies are fueling the demand for luxury clothing. Consumers in regions such as Asia-Pacific and the Middle East are exhibiting strong purchasing power and aspirational buying behavior. The growth of high-net-worth individuals (HNWIs) and millennials’ preference for premium fashion labels are further strengthening market expansion. As urban lifestyles evolve, spending on branded apparel and exclusive designer collections continues to grow, driving sustained revenue for luxury fashion houses worldwide.
- For instance, Louis Vuitton unveiled “LV The Place Bangkok”, a multi-level concept store in the heart of Bangkok’s Gaysorn Amarin, featuring a boutique, café, restaurant by chef Gaggan Anand, and immersive exhibitions of the brand’s heritage, reflecting the city’s rising affluence and appetite for luxury experiences.
Brand Influence and Celebrity Endorsements
Celebrity collaborations and influencer-driven marketing have become pivotal in enhancing brand recognition and desirability in the luxury clothing segment. High-profile partnerships and red-carpet appearances amplify consumer interest and reinforce a brand’s image of exclusivity. Social media platforms such as Instagram and TikTok allow brands to engage directly with affluent audiences and trend-conscious consumers. This powerful digital presence, combined with curated marketing campaigns, has accelerated global demand, particularly among younger demographics seeking prestige and individuality in fashion.
- For instance, Rihanna's partnership with PUMA led to the release of the FENTY Creeper sneaker, which sold out within three hours of its presale, resulting in a 183% surge in searches for PUMA.
Expansion of E-Commerce and Omnichannel Retailing
The integration of e-commerce with luxury retail has opened new growth avenues for brands. Digital transformation enables luxury labels to reach global consumers through virtual showrooms, exclusive online launches, and AI-driven personalization. The shift toward omnichannel strategies seamlessly linking online platforms with in-store experiences has enhanced accessibility while maintaining exclusivity. Furthermore, high-end fashion houses are investing in direct-to-consumer platforms and augmented reality (AR) fitting tools, providing immersive shopping experiences that strengthen customer loyalty and boost online sales volumes.
Key Trends and Opportunities
Sustainability and Ethical Luxury Fashion
Sustainability is emerging as a defining trend within the luxury clothing market. Consumers are increasingly conscious of ethical sourcing, eco-friendly materials, and transparent supply chains. Leading brands are adopting circular fashion models, using organic fabrics, and emphasizing traceability to align with global sustainability goals. This shift not only enhances brand credibility but also attracts environmentally aware millennials and Gen Z consumers. The growing demand for sustainable luxury apparel presents significant opportunities for innovation and long-term brand differentiation.
- For instance, Stella McCartney leads with innovative materials like grape-based vegan leather and Mylo™ mushroom leather, along with a pledge to reduce plastics in packaging, setting benchmarks in cruelty-free and eco-conscious luxury fashion.
Customization and Digital Personalization
Personalization is redefining the luxury shopping experience, as consumers seek exclusive and tailored products that reflect individuality. Brands are leveraging data analytics, artificial intelligence, and 3D visualization to offer custom designs and made-to-order services. From monogrammed pieces to virtual fitting sessions, technology-driven customization enhances engagement and perceived value. This trend provides an opportunity for brands to deepen customer relationships and command premium pricing, while ensuring a distinct competitive edge in an increasingly digital and experience-oriented marketplace.
- For instance, Louis Vuitton has leveraged augmented reality to allow customers to customize their bags in real-time, previewing personalized designs through 3D visualization before purchase. This technology creates a unique, tailor-made experience that deepens brand engagement.
Key Challenges
Counterfeit Products and Brand Dilution
The proliferation of counterfeit luxury goods poses a significant threat to established brands. Fake products erode consumer trust, diminish brand exclusivity, and impact profit margins. The rise of online marketplaces has made it easier for counterfeiters to distribute unauthorized merchandise globally. Luxury brands are investing in blockchain-based authentication and advanced tracking systems to safeguard intellectual property. Despite these efforts, combating counterfeiting remains an ongoing challenge that affects both brand equity and customer confidence across major markets.
High Pricing and Economic Volatility
Luxury clothing’s premium pricing structure limits accessibility, particularly during periods of economic instability. Fluctuating exchange rates, inflation, and geopolitical tensions can reduce consumer spending on non-essential luxury items. While affluent customers remain relatively resilient, middle-income aspirational buyers often delay or reduce purchases. To mitigate these risks, luxury brands are diversifying product lines, introducing entry-level collections, and expanding in emerging markets. Nonetheless, balancing exclusivity with affordability continues to be a key strategic and operational challenge.
Regional Analysis
North America
The North America luxury clothing market was valued at USD 18,054.40 million in 2018 and reached USD 20,437.10 million in 2024, projected to hit USD 29,528.15 million by 2032, expanding at a CAGR of 4.8%. The region holds a 24.4% market share in 2024, supported by high consumer spending power, strong brand awareness, and increasing demand for premium lifestyle apparel. Major luxury hubs such as New York and Los Angeles drive growth through flagship stores and exclusive collaborations. Additionally, digital adoption and the rising popularity of luxury streetwear continue to enhance regional sales momentum.
Europe
Europe’s luxury clothing market recorded USD 16,489.20 million in 2018 and grew to USD 18,144.89 million in 2024, projected to reach USD 24,566.45 million by 2032, growing at a CAGR of 3.9%. Holding a 21.6% share in 2024, Europe remains the leading region for luxury fashion, driven by iconic brands such as Gucci, Prada, and Burberry. The region’s fashion capitals Paris, Milan, and London serve as global style benchmarks. Strong tourism inflows, heritage craftsmanship, and established retail networks continue to sustain Europe’s dominance in the global luxury clothing market.
Asia Pacific
The Asia Pacific luxury clothing market was valued at USD 29,527.68 million in 2018 and rose to USD 34,939.05 million in 2024, anticipated to reach USD 53,796.57 million by 2032, growing at the fastest CAGR of 5.6%. The region commands a 41.6% market share in 2024, supported by rapid urbanization, rising disposable incomes, and expanding millennial and Gen Z luxury consumers. China, Japan, and India are major contributors, with increasing demand for high-end fashion and online retail penetration. International brands continue to expand their presence through flagship stores and regional e-commerce platforms.
Latin America
The Latin America luxury clothing market stood at USD 4,877.60 million in 2018, increasing to USD 5,570.00 million in 2024, and is expected to reach USD 7,514.99 million by 2032, at a CAGR of 3.9%. Holding a 6.6% share in 2024, the market is gaining traction through growing luxury consumption in Brazil and Mexico. Rising middle-class incomes, increasing fashion awareness, and the entry of global brands are fueling growth. However, economic fluctuations and limited luxury retail infrastructure pose minor challenges to consistent expansion across the region.
Middle East
The Middle East luxury clothing market was valued at USD 2,089.36 million in 2018, reaching USD 2,205.98 million in 2024, and projected to grow to USD 2,770.05 million by 2032, with a CAGR of 3.0%. The region accounts for a 2.6% market share in 2024, driven by affluent consumers in the UAE and Saudi Arabia who favor high-end fashion brands. Expanding retail spaces, luxury malls, and exclusive designer boutiques in cities like Dubai and Riyadh support market demand, though dependence on tourism remains a key growth factor.
Africa
Africa’s luxury clothing market was valued at USD 1,761.76 million in 2018, growing to USD 2,601.18 million in 2024, and projected to reach USD 3,287.94 million by 2032, registering a CAGR of 2.6%. With a 2.2% market share in 2024, growth is supported by rising urbanization, a growing affluent population, and increased exposure to global fashion through digital platforms. South Africa and Nigeria are emerging markets where international brands are gradually expanding. However, limited luxury retail infrastructure and high import costs restrain faster adoption across the continent.
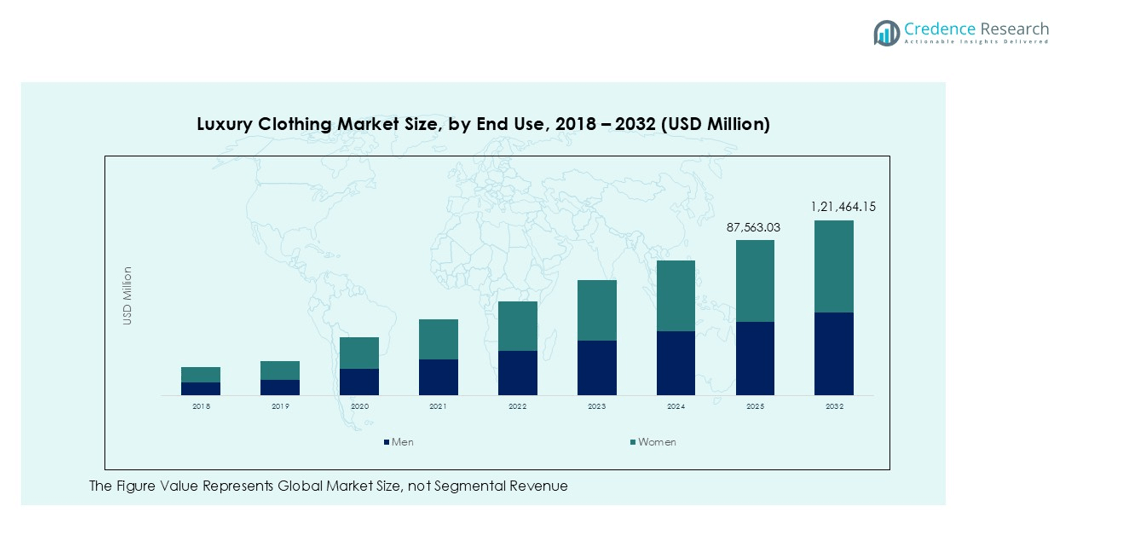
Market Segmentations:
By End Use:
- Men
- Women
By Distribution Channel:
- Online Retail
- Offline Retail (Brand Stores, Departmental Stores, Boutiques)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the global luxury clothing market is characterized by the presence of prominent brands such as Gucci, Prada, Burberry, Dolce & Gabbana, Giorgio Armani, Calvin Klein, Valentino, Kate Spade, and Phillip Lim. These players dominate the industry through strong brand heritage, innovative design, and expansive global retail networks. Companies are actively investing in digital transformation, sustainability initiatives, and exclusive collaborations to strengthen market presence and attract younger consumers. Strategic marketing through celebrity endorsements and social media influencers continues to drive brand loyalty and visibility. Moreover, leading luxury houses are focusing on personalized shopping experiences and limited-edition collections to maintain exclusivity. Expansion into emerging markets, coupled with the integration of e-commerce and omnichannel strategies, is reshaping competitive dynamics. Continuous innovation in materials, ethical sourcing, and customer engagement remains central to maintaining competitive advantage in an increasingly digital and experience-driven luxury apparel industry.
Key Player Analysis
- Burberry Group Plc
- Calvin Klein Inc.
- Dolce & Gabbana S.r.l.
- Giorgio Armani S.p.A.
- Prada S.p.A.
- Kate Spade & Company
- Phillip Lim (3.1 Phillip Lim)
- Valentino S.p.A.
- Gucci (Kering S.A.)
Recent Developments
- In April 2025, Prada Group announced the acquisition of Versace from Capri Holdings in a deal worth approximately USD 1.4 billion, marking one of the most significant consolidations in Italian luxury fashion.
- In September 2025, Gucci unveiled its latest collection titled “La Famiglia” under creative director Demna Gvasalia, featuring a limited see-now, buy-now launch strategy that strengthens the brand’s digital-first and exclusivity-driven approach.
- In October 2025, Reliance Brands Limited formed a strategic alliance with Stella McCartney to introduce her sustainable luxury label in India, with multichannel distribution of ready-to-wear and vegan accessories.
- On March 4 2025, Sofia Richie Grainge collaborated with Tommy Hilfiger to launch “Sofia for Tommy”, a 24-piece clothing and accessories collection inspired by classic American prep style and designed for everyday self-expression.
Report Coverage
The research report offers an in-depth analysis based on End Use, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The luxury clothing market is expected to witness steady growth driven by rising global fashion consciousness and premium lifestyle adoption.
- Digital transformation and virtual retail experiences will redefine how consumers engage with luxury brands.
- Sustainability and ethical production will become central to brand positioning and consumer preference.
- The women’s luxury segment will continue to dominate, supported by strong demand for designer apparel and accessories.
- Asia Pacific will emerge as the fastest-growing region due to expanding middle-class populations and urbanization.
- Personalized and made-to-order collections will gain popularity, enhancing exclusivity and brand loyalty.
- Collaborations between luxury houses and streetwear or sportswear brands will attract younger demographics.
- E-commerce and omnichannel retail strategies will strengthen brand accessibility across global markets.
- Investments in emerging markets and flagship store expansion will fuel long-term revenue growth.
- Innovation in materials, digital design, and sustainability practices will shape the future competitive landscape.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Income and Urbanization
Increasing disposable incomes and rapid urbanization, especially in emerging economies like Asia-Pacific and the Middle East, are fueling demand for luxury clothing as consumers seek premium brands and exclusive designer collections.
Brand Influence and Celebrity Endorsements
Celebrity collaborations, influencer marketing, and high-profile partnerships amplify brand desirability and exclusivity, driving consumer interest and boosting sales, particularly among younger, trend-conscious demographics.
Expansion of E-Commerce and Omnichannel Retailing
Digital transformation and the integration of e-commerce with traditional retail have expanded market reach, enabling luxury brands to offer immersive online experiences and seamless omnichannel shopping, thus attracting tech-savvy consumers.
Sustainability and Ethical Luxury Fashion
Growing consumer awareness of ethical sourcing, eco-friendly materials, and transparent supply chains is pushing luxury brands to innovate with sustainable practices, attracting environmentally conscious millennials and Gen Z buyers.
Personalization and Customization
The demand for personalized and made-to-order luxury apparel is increasing, as consumers seek unique products that reflect their individuality, prompting brands to invest in digital tools and bespoke services to enhance customer engagement and loyalty.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Luxury Clothing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Luxury Clothing Market projected to grow between 2025 and 2032?
Which Global Luxury Clothing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Luxury Clothing Market?
Who are the leading companies in the Global Luxury Clothing Market?
Which region commanded the largest share of the Global Luxury Clothing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Men
- 1.2.2 Women
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 83,898.20 million → 2032: USD 121,464.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Luxury Clothing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Luxury Clothing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Luxury Clothing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Luxury Clothing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Luxury Clothing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Luxury Clothing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Luxury Clothing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Luxury Clothing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 83,898.20 million → 2032: USD 121,464.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Luxury Clothing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Men
- 12.3.7.2 Women
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Luxury Clothing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Luxury Clothing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Luxury Clothing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Luxury Clothing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gucci (Kering S.A.)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Prada S.p.A.
- 18.4 Burberry Group Plc
- 18.5 Dolce & Gabbana S.r.l.
- 18.6 Giorgio Armani S.p.A.
- 18.7 Calvin Klein Inc.
- 18.8 Valentino S.p.A.
- 18.9 Kate Spade & Company
- 18.10 Phillip Lim (3.1 Phillip Lim)
- 18.11 Stella McCartney
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

