
Market Overview
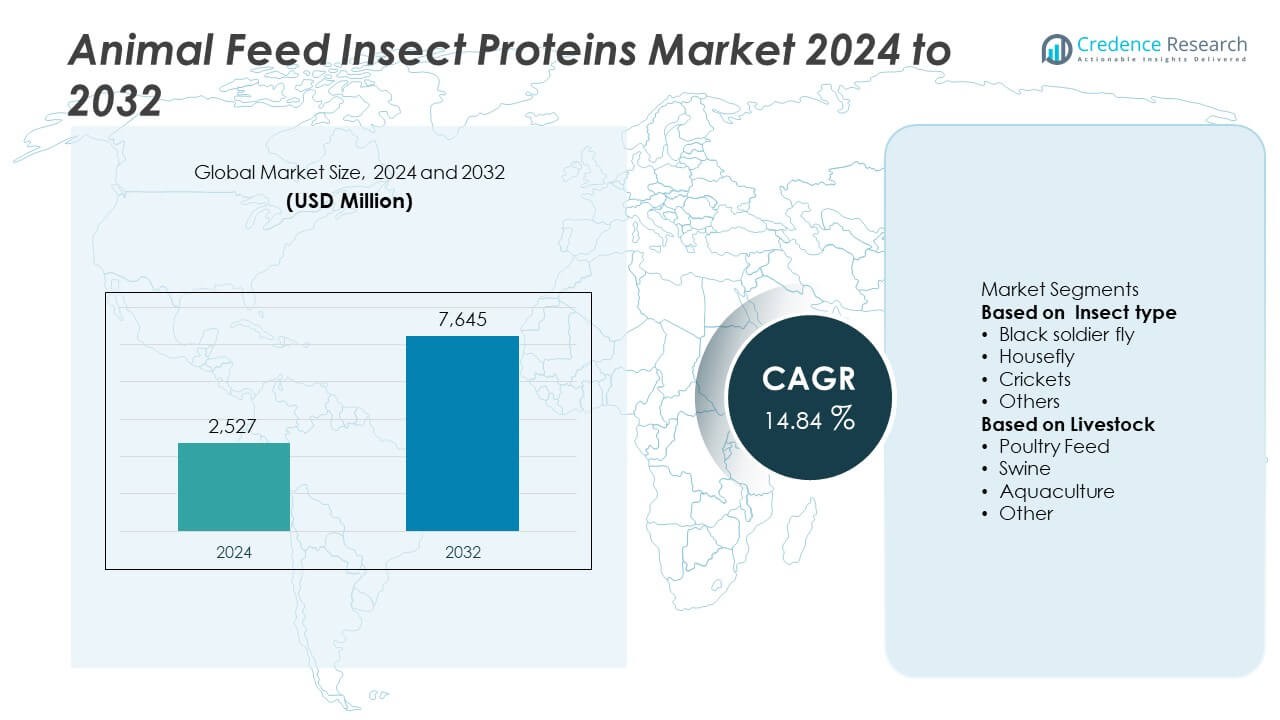
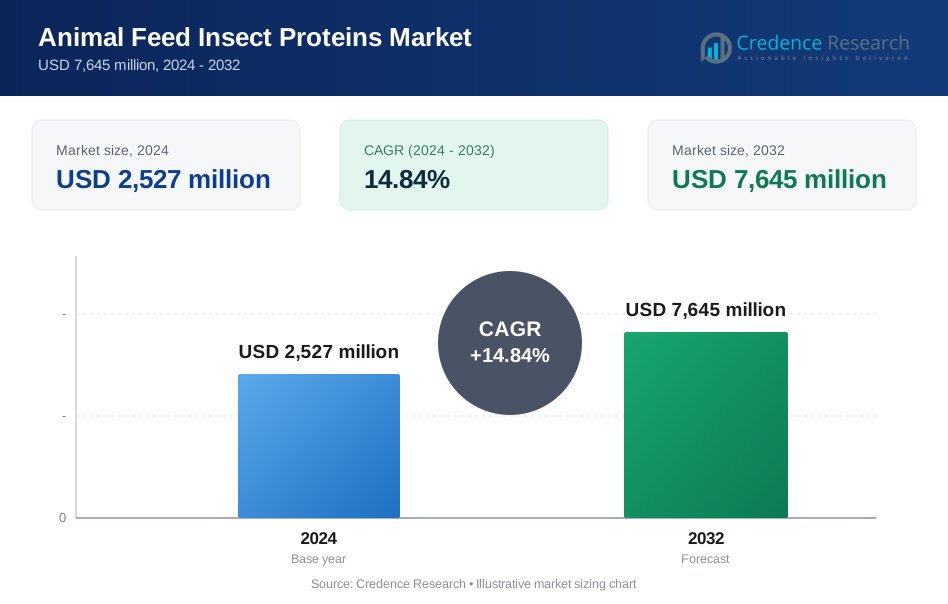
The Animal Feed Insect Proteins market was valued at USD 2,527 million in 2024 and is projected to reach USD 7,645 million by 2032, expanding at a CAGR of 14.84% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Animal Feed Insect Proteins Market Size 2024 | USD 2,527 Million |
| Animal Feed Insect Proteins Market, CAGR | 14.84% |
| Animal Feed Insect Proteins Market Size 2032 | USD 7,645 Million |
The Animal Feed Insect Proteins market is led by prominent companies including Protix, Ynsect SAS, Innovafeed, Nutrition Technologies, Enviroflight, HiProMine S.A, Hexafly Biotech, INSECTIFii, NextProtein, and BETA HATCH. These players dominate through advanced bioconversion technologies, sustainable protein extraction methods, and expansion of insect farming facilities. Europe led the global market with a 42.3% share in 2024, driven by strong regulatory support, large-scale production in France and the Netherlands, and growing integration of insect protein in aquafeed and poultry diets. Asia-Pacific followed with a 33.7% share, supported by rapid adoption in animal nutrition and waste valorization projects across China, Vietnam, and Malaysia.
Market Insights
- The Animal Feed Insect Proteins market was valued at USD 2,527 million in 2024 and is projected to reach USD 7,645 million by 2032, expanding at a CAGR of 14.84% during the forecast period.
- Rising demand for sustainable and high-protein feed ingredients is driving large-scale adoption across poultry, aquaculture, and swine sectors.
- Black soldier fly protein led the market with a 46.5% share in 2024, supported by its strong amino acid composition, high digestibility, and eco-friendly production cycle.
- Key players such as Protix, Ynsect SAS, Innovafeed, and Nutrition Technologies are investing in automation, large-scale production facilities, and feed-grade product innovation to strengthen market positioning.
- Europe dominated with a 42.3% share, followed by Asia-Pacific with 33.7%, driven by favorable regulations, rapid insect farming development, and increasing inclusion of insect protein in commercial feed formulations.
Market Segmentation Analysis:
By Insect Type
The black soldier fly segment dominated the Animal Feed Insect Proteins market in 2024 with a 46.8% share, driven by its high protein content, efficient feed conversion, and sustainable cultivation practices. It is widely used in aquaculture and poultry feed due to its balanced amino acid profile and digestibility. Black soldier fly larvae production is expanding rapidly across Asia-Pacific and Europe, supported by technological advances in insect rearing and waste bioconversion. Other species, such as houseflies and crickets, are gaining traction as complementary protein sources for niche applications in pet food and specialty livestock diets.
- For instance, research found that dried larvae of Hermetia illucens (black soldier fly) achieved a protein content of 45.29 g per 100 g dry-matter, lipid content of 4.12 g per 100 g dry-matter and ash content of 9.03 g per 100 g dry-matter in one trial.
By Livestock
The aquaculture segment held the largest 49.2% share in 2024, emerging as the leading consumer of insect protein-based feed. Increasing demand for sustainable fish farming and the rising cost of fishmeal have accelerated the use of insect-derived proteins as an alternative. Aquafeed manufacturers are adopting black soldier fly and mealworm-based formulations to enhance feed efficiency and promote growth performance. Poultry feed follows closely, driven by rising meat consumption and the need for natural protein enrichment. Continuous R&D in nutrient optimization and scalable production reinforces insect protein adoption across livestock categories.
- For instance, trials by Ÿnsect showed that shrimp fed a diet containing 50% mealworm-derived insect meal experienced a significantly lower mortality rate after a bacterial challenge compared to the control group, with a 76.9% lower mortality rate than the control.
Key Growth Drivers
Rising Demand for Sustainable Protein Sources
The growing need for sustainable and cost-effective protein alternatives in animal feed is a major growth driver for the Animal Feed Insect Proteins market. Insect-based proteins provide a high nutritional value and reduce reliance on traditional sources such as soy and fishmeal. The use of insect farming also promotes waste recycling and lower carbon emissions, aligning with global sustainability goals. Increasing environmental awareness and regulatory support for insect-derived feeds are accelerating the adoption of these protein solutions across poultry, aquaculture, and livestock industries.
- For instance, Protix reported that a commercial trial with its ProteinX® black soldier fly meal led to an average body weight of 4,669 g in Atlantic salmon, compared to 4,260 g in the control group.
Expansion of Aquaculture and Poultry Industries
The rapid expansion of aquaculture and poultry farming is fueling the demand for insect protein feed. These sectors require high-quality, digestible proteins to enhance growth and feed conversion rates. Insect proteins such as black soldier fly meal provide balanced amino acid content, improving animal health and performance. The rising global consumption of seafood and poultry products is encouraging feed manufacturers to adopt sustainable alternatives, boosting large-scale insect protein production and incorporation into commercial feed formulations.
- For instance, HiProMine S.A. deployed a production line in their Karkoszów plant in 2024 with the capacity to produce up to 30,000 tonnes of larva and 30,000 tonnes of insect frass per year, making it one of the largest suppliers of insect components in Europe.
Technological Advancements in Insect Farming
Automation, vertical farming, and controlled rearing systems are improving insect farming efficiency, lowering production costs, and ensuring consistent protein yields. The use of bioconversion technology enables large-scale waste recycling into high-protein insect meal. Companies are integrating AI-based monitoring and precision feeding systems to optimize larvae growth and nutrient composition. These advancements are strengthening the scalability and profitability of insect protein production, driving broader adoption in feed manufacturing and promoting long-term industry growth.
Key Trends & Opportunities
Growing Investment and Regulatory Support
Investments in insect-based protein production facilities and government support for sustainable feed alternatives present strong opportunities. The European Union, North America, and Asia-Pacific are implementing favorable regulations for insect-derived feed inclusion. Public-private partnerships are fostering research on nutrient optimization and feed safety. This growing policy support and financial backing are helping manufacturers expand capacity and develop regionally compliant, nutrient-rich insect feed formulations for different livestock applications.
- For instance, Innovafeed announced a production scale-up involving over 10 billion black soldier fly maggots at its factory in France, converting these larvae into protein and oil for animal and pet nutrition.
Emerging Use in Pet and Specialty Animal Feed
The growing popularity of high-protein, sustainable pet food formulations creates a new growth opportunity for insect protein suppliers. Insect meal provides hypoallergenic and easily digestible protein suitable for companion animals. Brands are marketing insect-based feed as premium, eco-friendly alternatives that align with ethical consumer trends. Increasing demand from specialty animal nutrition sectors such as aquariums and zoos further expands market potential for tailored insect protein applications.
- For instance, Ÿnsect SAS introduced its “Sprÿng” insect-based ingredient line for pet-food manufacturers, offering ingredient batches with protein content up to 71 g per 100 g dry-matter and ash content below 5 g per 100 g.
Key Challenges
High Production and Processing Costs
The high cost of insect rearing, processing, and protein extraction remains a major challenge. Specialized infrastructure and energy requirements increase operational expenses compared to conventional protein sources. This cost gap limits large-scale adoption, especially among small feed producers. To address this, industry players are investing in automation, waste valorization, and co-product utilization to improve cost efficiency and achieve economies of scale in commercial insect protein production.
Regulatory and Consumer Acceptance Barriers
Despite growing recognition, insect protein still faces regulatory and consumer acceptance hurdles in several regions. Complex approval procedures and inconsistent international standards delay market entry for new products. Some consumers and farmers remain hesitant due to limited awareness of insect protein benefits. Continuous education, transparent labeling, and safety validation are essential to building trust and achieving widespread market acceptance across livestock and aquaculture feed applications.
Regional Analysis
North America
North America accounted for a 34.7% share of the Animal Feed Insect Proteins market in 2024, driven by strong demand for sustainable and high-quality protein sources in aquaculture and poultry feed. The United States leads the region, supported by government initiatives promoting circular agriculture and waste-to-protein technologies. Feed manufacturers are adopting black soldier fly-based ingredients to reduce dependency on fishmeal imports. Increasing consumer awareness of sustainable livestock production and the presence of advanced insect farming infrastructure further strengthen market growth across the region.
Europe
Europe held a 30.2% share in 2024, supported by early regulatory approvals and strong policy backing for insect-derived proteins in feed applications. Countries such as France, the Netherlands, and Belgium lead innovation in large-scale insect production facilities. The European Union’s sustainable feed initiatives and restrictions on traditional fishmeal usage drive greater adoption of insect meal. The aquaculture and poultry sectors are key contributors, while growing investment in R&D and commercialization of high-protein insect products continue to enhance market competitiveness.
Asia-Pacific
Asia-Pacific captured a 25.4% share in 2024, emerging as the fastest-growing regional market. Rising meat and seafood consumption, coupled with high feed costs, has encouraged feed producers to adopt insect proteins as cost-effective alternatives. China, Vietnam, and Thailand are expanding insect farming operations to support aquaculture and poultry production. Government programs promoting food security and waste management are boosting regional output. Increasing collaborations between local insect protein firms and global feed manufacturers are expected to further accelerate growth across this region.
Latin America
Latin America represented a 5.6% share in 2024, with growing adoption of insect-based feed ingredients in aquaculture and livestock farming. Brazil and Mexico dominate the regional market due to rising demand for sustainable animal nutrition and expanding aquafeed industries. The region benefits from favorable climate conditions and abundant organic waste resources for insect cultivation. However, limited technological infrastructure and investment still restrain large-scale commercialization. Ongoing partnerships with international insect protein producers are expected to strengthen regional production capabilities over the forecast period.
Middle East & Africa
The Middle East & Africa accounted for a 4.1% share in 2024, driven by increasing efforts to achieve feed self-sufficiency and promote sustainable agriculture. Countries such as South Africa and the United Arab Emirates are investing in pilot insect farming projects for poultry and aquaculture applications. The region’s growing dependence on imported feed proteins is encouraging local production of insect-based alternatives. While market development is still in early stages, supportive government initiatives and international collaborations are paving the way for gradual expansion of insect protein feed usage.
Market Segmentations:
By Insect type
- Black soldier fly
- Housefly
- Crickets
- Others
By Livestock
- Poultry Feed
- Swine
- Aquaculture
- Other
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Animal Feed Insect Proteins market features key players such as Nutrition Technologies, Protix, HiProMine S.A, Ynsect SAS, NextProtein, Hexafly Biotech, Enviroflight, INSECTIFii, Innovafeed, and BETA HATCH. These companies are driving market growth through large-scale production of black soldier fly and mealworm-based protein ingredients tailored for poultry, aquaculture, and swine feed. Leading manufacturers focus on scaling up automated bioconversion systems, enhancing protein yields, and ensuring compliance with feed safety regulations. Strategic collaborations with feed producers and research institutions are accelerating innovation in nutrient optimization and sustainable sourcing. Expansion of regional production facilities and circular economy models using organic waste as feedstock are also key strategies adopted by market leaders to reduce production costs and strengthen supply chain resilience. The competition remains intense as companies prioritize eco-efficient production technologies and long-term partnerships with agribusinesses to meet rising global demand for alternative protein sources.
Key Player Analysis
- Nutrition Technologies
- Protix
- HiProMine S.A
- Ynsect SAS
- NextProtein
- Hexafly Biotech
- Enviroflight
- INSECTIFii
- Innovafeed
- BETA HATCH
Recent Developments
- In February 2025, HiProMine S.A. announced a partnership with Brenntag to distribute its insect-derived proteins, fats and functional feed ingredients under GMP+ certification across the EMEA region via Brenntag’s animal-nutrition portfolio.
- In May 2024, HiProMine opened an additional plant in Europe dedicated to insect-protein and fat production for aquaculture and livestock feed, significantly increasing its manufacturing capacity.
- In April 2024, Protix publicly reported that its ProteinX® insect meal reduces CO₂ emissions by 78 % compared to poultry meal and up to 89 % compared to soy protein concentrate, marking a major sustainability data milestone for insect-based feed ingredients.
- In October 2023, Tyson Foods, Inc., one of the world’s largest food companies, has reached an agreement for a two-fold investment with Protix, the leading global insect ingredients company. The strategic investment will support the growth of the emerging insect ingredient industry and expand the use of insect ingredient solutions to create more efficient sustainable proteins and lipids for use in the global food system.
Report Coverage
The research report offers an in-depth analysis based on Insect type, Livestock and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for insect-based proteins will increase due to the need for sustainable animal nutrition.
- Black soldier fly protein will remain dominant because of its high digestibility and efficient waste conversion.
- Expansion in aquaculture feed production will boost adoption of insect-derived ingredients.
- Large-scale investments in insect farming technology will enhance production capacity and cost efficiency.
- Regulations supporting alternative protein use in livestock feed will accelerate global market growth.
- Integration of automation and AI in insect rearing facilities will improve yield consistency.
- Collaborations between feed manufacturers and insect protein producers will strengthen supply chains.
- Asia-Pacific will emerge as a key growth hub driven by rising poultry and aquafeed demand.
- Research in nutritional optimization will enhance the amino acid balance of insect-based feeds.
- Consumer preference for eco-friendly and circular economy feed solutions will shape future industry expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Animal Feed Insect Proteins market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Animal Feed Insect Proteins market projected to grow between 2025 and 2032?
Which Animal Feed Insect Proteins market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Animal Feed Insect Proteins market?
Who are the leading companies in the Animal Feed Insect Proteins market?
Which region commanded the largest share of the Animal Feed Insect Proteins market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Animal Feed Insect Proteins Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Animal Feed Insect Proteins Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,527 million → 2032: USD 7,645 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Animal Feed Insect Proteins Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Animal Feed Insect Proteins Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Animal Feed Insect Proteins Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Animal Feed Insect Proteins Market Drivers
- 3.3 Animal Feed Insect Proteins Market Restraints & Challenges
- 3.4 Animal Feed Insect Proteins Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Animal Feed Insect Proteins Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Animal Feed Insect Proteins Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Animal Feed Insect Proteins category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Animal Feed Insect Proteins Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Animal Feed Insect Proteins Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Animal Feed Insect Proteins market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Animal Feed Insect Proteins Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Animal Feed Insect Proteins Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Animal Feed Insect Proteins Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Animal Feed Insect Proteins (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Animal Feed Insect Proteins Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Animal Feed Insect Proteins Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Animal Feed Insect Proteins Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Animal Feed Insect Proteins Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Animal Feed Insect Proteins Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Animal Feed Insect Proteins Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Animal Feed Insect Proteins Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Animal Feed Insect Proteins Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Animal Feed Insect Proteins Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
