
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Industrial Catalyst Market Size 2024 | USD 2090.72 million |
| Germany Industrial Catalyst Market, CAGR | 6.8% |
| Germany Industrial Catalyst Market Size 2032 | USD 3539.4 million |
Market Overview:
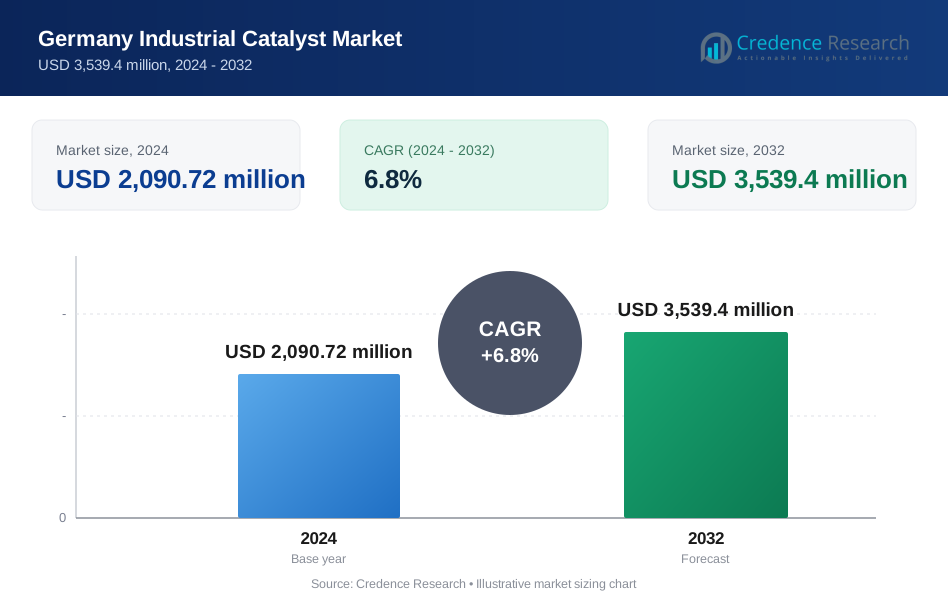
The Germany Industrial Catalyst Market is projected to grow from USD 2090.72 million in 2024 to an estimated USD 3539.4 million by 2032, with a compound annual growth rate (CAGR) of 6.8% from 2024 to 2032.
Several factors are driving the growth of the industrial catalyst market in Germany. Stringent environmental regulations, such as the Euro 6 emission standards, are prompting the need for advanced catalysts to produce cleaner fuels and reduce emissions. Additionally, continuous technological advancements in catalyst technologies have enhanced process efficiencies, selectivity, and product yields, making catalysts indispensable in modern chemical manufacturing. The growing global demand for cleaner energy sources is also driving the need for efficient refining catalysts, as refineries are pressured to produce low-sulfur fuels. Furthermore, the expansion of end-use industries like petrochemicals, automotive, and pharmaceuticals is increasing the demand for catalysts to support complex chemical reactions and improve production processes.
Germany, as a leader in the European industrial catalyst market, benefits from a strong industrial base and a commitment to innovation, particularly in green technologies and advanced manufacturing. Despite challenges such as rising energy costs and international competition, Germany's industrial sector remains resilient, focusing on specialized and high-value products. The presence of major chemical and automotive companies, alongside its strategic emphasis on manufacturing excellence and sustainability, positions Germany as a key player in the global industrial catalyst market. Furthermore, Germany’s well-established infrastructure and robust research and development ecosystem enable continuous advancements in catalyst technologies. This dynamic environment ensures Germany’s competitive edge, helping it maintain its leadership in industrial catalyst innovation.
Market Insights:
- The Germany Industrial Catalyst Market is expected to grow significantly from USD 2,090.72 million in 2024 to USD 3,539.4 million by 2032, driven by increasing demand for cleaner fuels and advanced catalyst technologies.
- The global industrial catalyst market is projected to grow from USD 31.56 billion in 2024 to USD 51.15 billion by 2032, with a CAGR of 6.22% from 2024 to 2032.
- Stringent environmental regulations, such as the Euro 6 emission standards, are pushing industries to adopt more efficient catalysts to meet emission reduction targets.
- Technological advancements in catalyst materials, including nanocatalysts and improved recyclability, are enhancing process efficiency, selectivity, and cost-effectiveness.
- The global shift towards cleaner energy sources is driving the demand for refining catalysts, essential in producing low-sulfur and high-quality fuels.
- Key end-use industries like petrochemicals, automotive, and pharmaceuticals are expanding, increasing the need for advanced catalysts to optimize complex production processes.
- The high cost of catalyst production, particularly for those involving precious metals or complex materials, remains a key market challenge, limiting adoption for small-scale enterprises.
- The rise of alternative technologies, such as enzymatic reactions and bio-based production methods, poses a competitive threat to traditional catalytic processes, potentially limiting market growth.
Report Scope
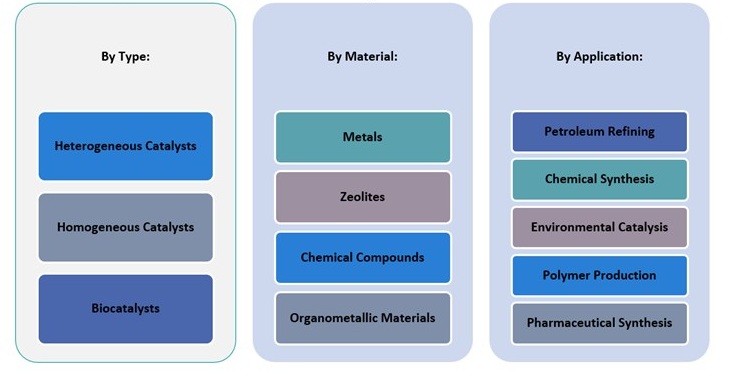
This report segments the Germany Industrial Catalyst Market as follow
Market Drivers:
Stringent Environmental Regulations
Germany's industrial catalyst market is significantly influenced by the country's stringent environmental regulations. As part of its commitment to reducing carbon emissions and promoting sustainable practices, Germany has enforced strict policies and regulations that demand the use of advanced catalysts to minimize pollutants. For instance, the Euro 6 emissions standards for vehicles have pushed automotive manufacturers to adopt more efficient catalysts to reduce harmful emissions. Furthermore, the European Union’s broader environmental goals, including those related to the reduction of greenhouse gases, continue to shape the demand for catalysts across various industrial sectors. These regulatory pressures are driving investments in cleaner and more efficient catalyst technologies, ultimately fostering market growth.
Technological Advancements in Catalyst Technologies
Technological innovations in catalyst design and production are key drivers of the industrial catalyst market in Germany. For instance, BASF, for instance, recently inaugurated a Catalyst Development and Solids Processing Center in Ludwigshafen, enabling rapid development of innovative catalyst technologies. These innovations help to improve process efficiency, increase reaction rates, and enhance selectivity, which in turn leads to higher productivity and cost-effectiveness in industrial processes. As manufacturers seek to optimize their production lines, the demand for more advanced and specialized catalysts rises, thus propelling the market forward. Research and development activities in the country’s well-established industrial sector further contribute to the ongoing evolution of catalyst technologies.
Growing Demand for Cleaner Fuels
The global shift towards cleaner and more sustainable energy sources is a significant driver for the industrial catalyst market in Germany. As the country transitions toward renewable energy and aims to meet EU-wide emissions targets, the demand for refined petroleum products has increased, especially for cleaner fuels. This has resulted in a higher requirement for refining catalysts, which are essential in the production of low-sulfur and high-quality fuels. Additionally, the automotive industry’s move toward electric vehicles (EVs) has also generated demand for catalysts in vehicle emission control systems. This growing emphasis on clean energy and reduced emissions has made catalysts a crucial component in ensuring that industries comply with both national and international environmental standards.
Expansion of Key End-Use Industries
The industrial catalyst market in Germany is also driven by the growth of key end-use industries, including petrochemicals, automotive, and pharmaceuticals. As these sectors expand and evolve, they increasingly rely on catalysts to support complex chemical processes and optimize production efficiency. In the petrochemical industry, catalysts are essential for refining processes such as cracking, hydrotreating, and reforming. Meanwhile, the pharmaceutical industry depends on catalysts to drive high-precision chemical reactions that produce active pharmaceutical ingredients (APIs). As these industries continue to grow, the demand for advanced catalysts to enhance performance and meet regulatory standards increases, fueling market expansion in Germany.
Market Trends:
Shift Towards Green Catalysts
A significant trend in the Germany industrial catalyst market is the increasing focus on green catalysts, driven by the growing emphasis on sustainability and environmental responsibility. As industries continue to seek ways to reduce their environmental impact, the demand for catalysts that facilitate cleaner, more energy-efficient processes have grown. Green catalysts are designed to reduce the consumption of harmful chemicals, lower energy use, and minimize the production of waste. This shift is particularly evident in the chemical and petrochemical industries, where green catalytic processes are being adopted to produce biofuels, biodegradable polymers, and other sustainable products. The growing preference for these eco-friendly solutions aligns with both regulatory requirements and the broader market trend toward sustainability.
Advancements in Catalyst Recycling and Reusability
An emerging trend in the Germany industrial catalyst market is the increased focus on catalyst recycling and reusability. For example, Germany's push for a circular economy has driven investments in innovative regeneration methods that optimize catalyst performance while minimizing ecological impact. With industries aiming to improve the sustainability of their operations, the demand for catalysts that can be reused or regenerated after their initial use is on the rise. This trend is particularly important in sectors like refining and petrochemicals, where catalysts are often expensive and integral to process efficiency. Manufacturers are increasingly investing in technologies that allow catalysts to be regenerated, extending their operational lifespan and reducing the need for constant replacement. This approach not only improves cost-effectiveness but also helps companies meet environmental regulations related to waste reduction and resource conservation.
Integration of Artificial Intelligence in Catalyst Development
Another prominent trend is the integration of artificial intelligence (AI) and machine learning (ML) in the development and optimization of industrial catalysts. These advanced technologies are being employed to enhance catalyst design, predict performance outcomes, and streamline production processes. By utilizing AI and ML, researchers can analyze vast amounts of data, identify patterns, and optimize catalyst formulations to achieve superior efficiency and selectivity. This trend is helping companies reduce development costs and accelerate time-to-market for new catalyst products. In Germany, where technological innovation is highly prioritized, the application of AI in catalyst research is expected to continue to grow, further improving the competitiveness of the market.
Rise of Customized Catalysts for Specialized Applications
The demand for customized catalysts tailored to meet specific industrial requirements is also a growing trend in the Germany industrial catalyst market. As industries become more specialized, the need for catalysts designed to optimize unique processes has increased. For instance, BASF offers bespoke catalyst solutions designed to improve reaction rates and selectivity in industries such as pharmaceuticals and automotive manufacturing. These customized solutions are designed to improve reaction rates, selectivity, and efficiency for particular applications, allowing manufacturers to optimize their production processes and meet the increasingly complex regulatory standards. This trend reflects the shift toward more targeted and specialized catalyst solutions in response to evolving industry needs.
Market Challenges Analysis:
High Cost of Catalyst Production
One of the primary restraints in the Germany industrial catalyst market is the high cost associated with the production of catalysts. The development and manufacturing of advanced catalysts, especially those involving precious metals or complex materials, require significant investment in research and development, raw materials, and production processes. These costs are passed on to end-users, making catalysts an expensive component in industrial processes. This high cost can be a barrier for small and medium-sized enterprises (SMEs) or companies operating on tight margins, potentially limiting their ability to invest in advanced catalyst technologies. Moreover, the cost of replacing catalysts, particularly in high-turnover industries, can add significant operational costs, thereby challenging the market's growth.
Regulatory Compliance and Standardization Issues
Another challenge faced by the industrial catalyst market in Germany is the complexity of regulatory compliance and the constantly evolving nature of environmental standards. Germany's strict emission regulations and sustainability requirements demand that catalysts meet high performance and environmental standards. However, the continual updates to these regulations, particularly within the European Union, can be burdensome for manufacturers. This dynamic regulatory environment creates uncertainty and complicates the development of catalysts that can comply with changing standards, potentially delaying product launches and increasing costs for manufacturers. Additionally, discrepancies in standards across different regions can make it challenging for companies to ensure their products are universally compliant.
Competition from Alternative Technologies
The rise of alternative technologies also presents a challenge to the industrial catalyst market in Germany. For instance, in certain industries, innovative processes or technologies, such as enzymatic reactions or bio-based production methods, are emerging as viable alternatives to traditional catalytic processes. These alternatives offer potential advantages in terms of efficiency, cost, and environmental impact. As these technologies mature, they may pose a competitive threat to the demand for conventional industrial catalysts, especially if they prove to be more cost-effective or sustainable in specific applications. The growing interest in these alternatives could limit the growth potential of the catalyst market in certain sectors.
Market Opportunities:
The Germany industrial catalyst market presents significant opportunities driven by increasing demand for cleaner and more sustainable production processes. With Germany’s commitment to meeting rigorous environmental standards and reducing carbon emissions, the market is poised for growth in the development of catalysts that support cleaner industrial practices. Industries such as automotive, petrochemicals, and energy are actively seeking advanced catalysts to optimize their production processes, improve efficiency, and comply with stringent emission regulations. As industries work towards more sustainable operations, there is a growing opportunity for catalyst manufacturers to innovate by developing green and eco-friendly catalyst solutions, which will align with the country’s environmental goals. This trend offers a promising avenue for companies involved in catalyst production to capitalize on the rising demand for low-emission technologies and sustainable products.
Additionally, technological advancements present an attractive opportunity for market players in Germany. The increasing integration of artificial intelligence and machine learning in catalyst development allows for more efficient and precise catalyst design, offering the potential to enhance performance and reduce production costs. Furthermore, the growing trend of customized catalysts for specialized applications opens new doors for innovation, particularly in sectors like pharmaceuticals, automotive, and renewable energy. With these technological advancements, manufacturers can develop tailored solutions that meet specific industry needs, creating an opportunity to gain a competitive edge in a rapidly evolving market. These factors combined highlight substantial opportunities for growth and innovation within Germany’s industrial catalyst market.
Market Segmentation Analysis:
The Germany Industrial Catalyst Market is segmented based on type, application, and material, each contributing uniquely to market dynamics.
By Type Segment: The market is dominated by heterogeneous catalysts, which are widely used in petroleum refining, chemical synthesis, and environmental catalysis due to their efficiency and versatility. Homogeneous catalysts, while less common, are critical in specific chemical synthesis applications, offering high selectivity in reactions. Biocatalysts are gaining traction, particularly in pharmaceutical synthesis and environmentally friendly chemical processes, as they offer more sustainable and selective alternatives to traditional catalysts.
By Application Segment: Petroleum refining holds the largest share in the market, with catalysts used to improve the quality of fuels and reduce emissions. Chemical synthesis is another key segment, where catalysts enhance reaction speeds and yields. Environmental catalysis, driven by increasing environmental regulations, is growing rapidly, focusing on reducing emissions and supporting green technologies. The polymer production segment uses catalysts to improve the efficiency of polymerization processes, while pharmaceutical synthesis relies on catalysts to produce active pharmaceutical ingredients with high precision.
By Material Segment: Metals, especially precious metals like platinum and palladium, dominate the market due to their effectiveness in catalysis at high temperatures. Zeolites are used extensively in petrochemical and refining industries for their high surface area and ion-exchange properties. Chemical compounds, including acids and bases, are used for specific reactions, while organometallic materials are gaining popularity in specialized applications due to their unique catalytic properties.
Segmentation:
By Type Segment
- Heterogeneous Catalysts
- Homogeneous Catalysts
- Biocatalysts
By Application Segment
- Petroleum Refining
- Chemical Synthesis
- Environmental Catalysis
- Polymer Production
- Pharmaceutical Synthesis
By Material Segment
- Metals
- Zeolites
- Chemical Compounds
- Organometallic Materials
Regional Analysis:
Germany's industrial catalyst market is concentrated in regions with significant refining and chemical manufacturing activities. The North and West regions of the country, which host key industrial hubs such as Hamburg, Bremen, and Duisburg, play a dominant role in the market. These areas are strategically positioned near major ports and transportation networks, facilitating efficient distribution and access to international markets. The concentration of Germany's 13 refineries in these regions, which are responsible for a substantial portion of the country’s crude oil processing, positions them as the largest consumers of industrial catalysts in the country. This region is expected to maintain a leading position in the industrial catalyst market due to its continued emphasis on refining and petrochemical production.
Other regions in Germany, including Bavaria and Baden-Württemberg, have seen increasing demand for industrial catalysts, particularly due to their growing chemical manufacturing and automotive sectors. These areas are investing in advanced technologies and focusing on the development and adoption of green catalysts and sustainable production processes. This shift is helping to expand the industrial catalyst market beyond the traditional refining sector, with growing interest in applications such as automotive emissions control and specialized chemical manufacturing. While the North and West regions continue to dominate the market, regions like Bavaria and Baden-Württemberg are gradually increasing their market share, driven by a broader adoption of catalyst technologies across various industries.
In terms of market share, the North and West regions hold the largest share, estimated at over 60% of the total industrial catalyst market in Germany. The remaining 40% is divided among other regions, with Bavaria and Baden-Württemberg accounting for a significant portion of this share. These regions are expected to continue growing in their contributions to the market as demand for specialized and environmentally friendly catalyst solutions rises. This regional diversification highlights the expanding scope of the industrial catalyst market across Germany, driven by technological advancements and a broader focus on sustainability.
Key Player Analysis:
- BASF SE
- Johnson Matthey PLC
- Clariant AG
- Evonik Industries AG
- Haldor Topsoe A/S
- Arkema Group
- Akzo Nobel N.V.
- INEOS Group
- Umicore
- SABIC Germany
Competitive Analysis:
The Germany industrial catalyst market is highly competitive, with several key players dominating the landscape. Major global catalyst manufacturers, such as BASF SE, Clariant AG, and Evonik Industries, are prominent players in the market, leveraging their strong research and development capabilities to produce high-performance catalysts. These companies focus on innovation, introducing advanced catalyst technologies that meet the increasing demand for sustainability and efficiency in industrial processes. Additionally, several regional players also contribute to the market, particularly in specialized catalyst applications for the chemical, automotive, and energy sectors. The competition is intensifying as companies invest in green catalysts, customized solutions, and technologies that comply with stringent environmental regulations. Strategic partnerships, acquisitions, and collaborations are common strategies used by market players to strengthen their market position. With technological advancements and the ongoing push toward cleaner production processes, competition in the Germany industrial catalyst market is expected to remain robust.
Recent Developments:
- In December 2024, BASF inaugurated its new Catalyst Development and Solids Processing Center in Ludwigshafen, Germany. This state-of-the-art facility aims to accelerate the development of innovative catalyst and process technologies, serving as a hub for pilot-scale synthesis of chemical catalysts. The center is equipped with cutting-edge process equipment, enabling faster and more focused R&D activities essential for the green transformation.
- In Feb, 2025, Johnson Matthey PLC announced a partnership with Bosch to develop catalyst-coated membranes (CCMs) for fuel cell stacks. These CCMs will be integrated into Bosch's fuel cell power modules for commercial vehicles, promoting zero-emission hydrogen technology. The collaboration focuses on advancing cleaner mobility solutions and energy generation.
Market Concentration & Characteristics:
The Germany industrial catalyst market is characterized by a high level of market concentration, dominated by several key players who significantly influence market dynamics. Major corporations such as BASF SE, Evonik Industries AG, and Clariant AG hold substantial market shares, collectively accounting for a significant portion of the market. These companies leverage their extensive research and development capabilities, global distribution networks, and strong customer relationships to maintain their market positions. Their focus on innovation and technological advancement enables them to offer a diverse range of catalyst solutions catering to various industrial applications, including petroleum refining, chemical manufacturing, and environmental solutions. This concentrated market structure fosters intense competition, driving continuous improvements in catalyst performance and the development of sustainable technologies.
Report Coverage:
The research report offers an in-depth analysis based on Type Segment, Application Segment and Material Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Germany's industrial catalyst market is set to benefit from the rising demand for cleaner fuels and advanced refining technologies.
- Technological advancements in refining processes will drive the need for high-performance catalysts that enhance fuel quality and production efficiency.
- Stringent environmental regulations, such as the Euro 6 standards, will continue to promote the adoption of catalysts that reduce sulfur and nitrogen emissions.
- The German government’s focus on decarbonization and carbon reduction initiatives will encourage the use of catalysts that facilitate cleaner production.
- Growing investments in renewable energy and biofuels will create new opportunities for catalysts in sustainable fuel production.
- The North and West regions of Germany, with their concentration of refining and chemical industries, are expected to remain dominant in catalyst demand.
- Collaborations between industry and research institutions will lead to innovations in catalyst technologies, meeting the evolving needs of various sectors.
- Advances in catalyst recycling and reusability will improve the sustainability of industrial processes, making catalysts more cost-effective and environmentally friendly.
- Customized catalysts tailored to specific industrial requirements will become more prevalent, as industries seek solutions to optimize complex processes.
- Despite economic challenges, Germany’s commitment to industrial modernization and sustainability will support steady growth in the industrial catalyst sector.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Germany's strict environmental policies, including Euro 6 emission standards and EU-wide greenhouse gas reduction targets, are compelling industries to adopt advanced catalysts to minimize pollutants and comply with regulatory requirements, driving market growth.
Technological Advancements in Catalyst Technologies
Continuous innovation in catalyst design, such as nanocatalysts and improved recyclability, is enhancing process efficiency and selectivity, making catalysts more indispensable for modern chemical manufacturing and supporting market expansion.
Growing Demand for Cleaner Fuels
The transition towards renewable energy and the need for low-sulfur, high-quality fuels are increasing the demand for refining catalysts, as refineries and automotive sectors strive to meet stricter emission standards and sustainability goals.
Expansion of Key End-Use Industries
Growth in Germany's petrochemical, automotive, and pharmaceutical sectors is boosting the need for catalysts to support complex chemical reactions, improve yields, and meet evolving production and regulatory requirements.
Focus on Green and Reusable Catalysts
The push for sustainability and circular economy practices is driving demand for green catalysts and catalyst recycling technologies, enabling industries to reduce waste, lower costs, and align with Germany’s environmental objectives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Germany Industrial Catalyst Market?
What factors are driving the growth of the Germany Industrial Catalyst Market?
What are some challenges faced by the Germany Industrial Catalyst Market?
Who are the major players in the Germany Industrial Catalyst Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Heterogeneous Catalysts
- 1.2.2 Homogeneous Catalysts
- 1.2.3 Biocatalysts
- 1.3 By Material
- 1.3.1 Metals
- 1.3.2 Zeolites
- 1.3.3 Chemical Compounds
- 1.3.4 Organometallic Materials
- 1.4 By Application
- 1.4.1 Petroleum Refining
- 1.4.2 Chemical Synthesis
- 1.4.3 Environmental Catalysis
- 1.4.4 Polymer Production
- 1.4.5 Pharmaceutical Synthesis
- 1.5 By Region (Germany)
- 1.5.1 North & West
- 1.5.2 Bavaria
- 1.5.3 Baden-Württemberg
- 1.5.4 Other Regions
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,090.72 million → 2032: USD 3,539.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Germany Industrial Catalyst Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Germany Industrial Catalyst Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Germany Industrial Catalyst Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Germany Industrial Catalyst Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Germany Industrial Catalyst Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Germany Industrial Catalyst Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Germany Industrial Catalyst Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Germany Industrial Catalyst Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,090.72 million → 2032: USD 3,539.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Germany Industrial Catalyst Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Heterogeneous Catalysts
- 12.3.7.2 Homogeneous Catalysts
- 12.3.7.3 Biocatalysts
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metals
- 12.4.7.2 Zeolites
- 12.4.7.3 Chemical Compounds
- 12.4.7.4 Organometallic Materials
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Petroleum Refining
- 12.5.7.2 Chemical Synthesis
- 12.5.7.3 Environmental Catalysis
- 12.5.7.4 Polymer Production
- 12.5.7.5 Pharmaceutical Synthesis
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Region (Germany) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 North & West
- 12.6.7.2 Bavaria
- 12.6.7.3 Baden-Württemberg
- 12.6.7.4 Other Regions
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Germany Industrial Catalyst End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Germany Industrial Catalyst Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Germany Industrial Catalyst Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Germany Industrial Catalyst Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson Matthey PLC
- 18.4 Clariant AG
- 18.5 Evonik Industries AG
- 18.6 Haldor Topsoe A/S
- 18.7 Arkema Group
- 18.8 Akzo Nobel N.V.
- 18.9 INEOS Group
- 18.10 Umicore
- 18.11 SABIC Germany
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

