
Market Overview
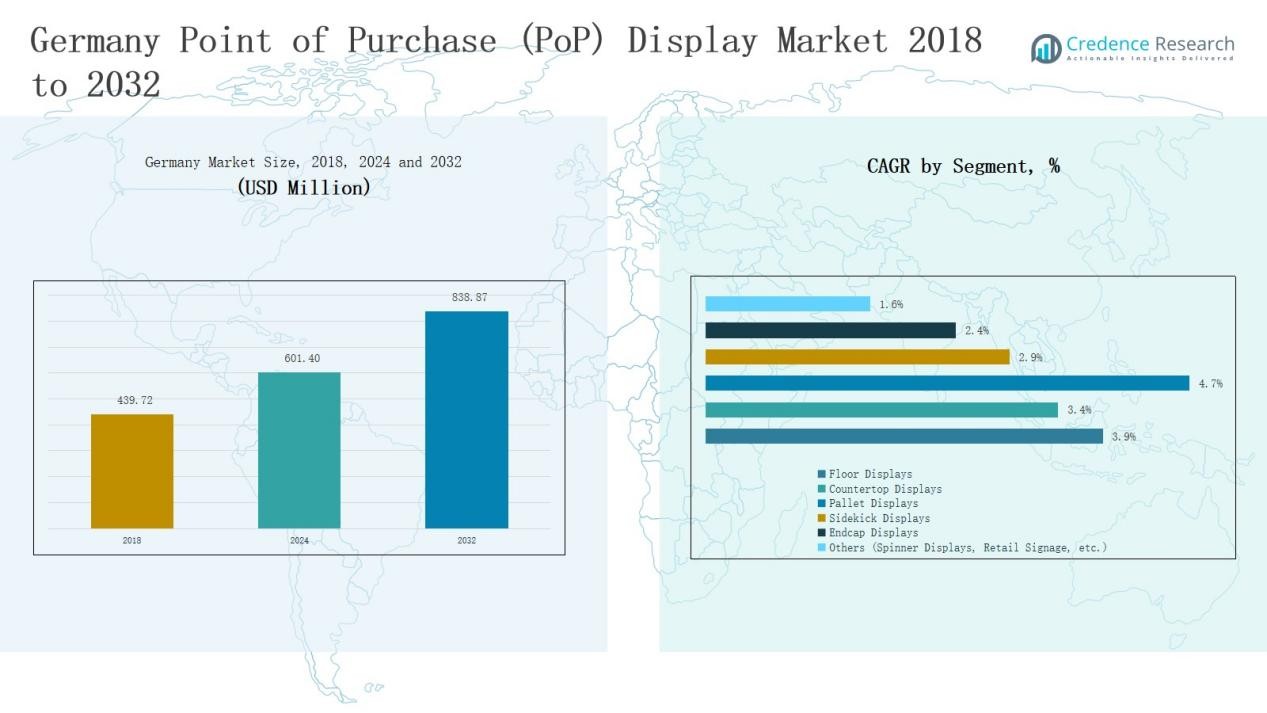
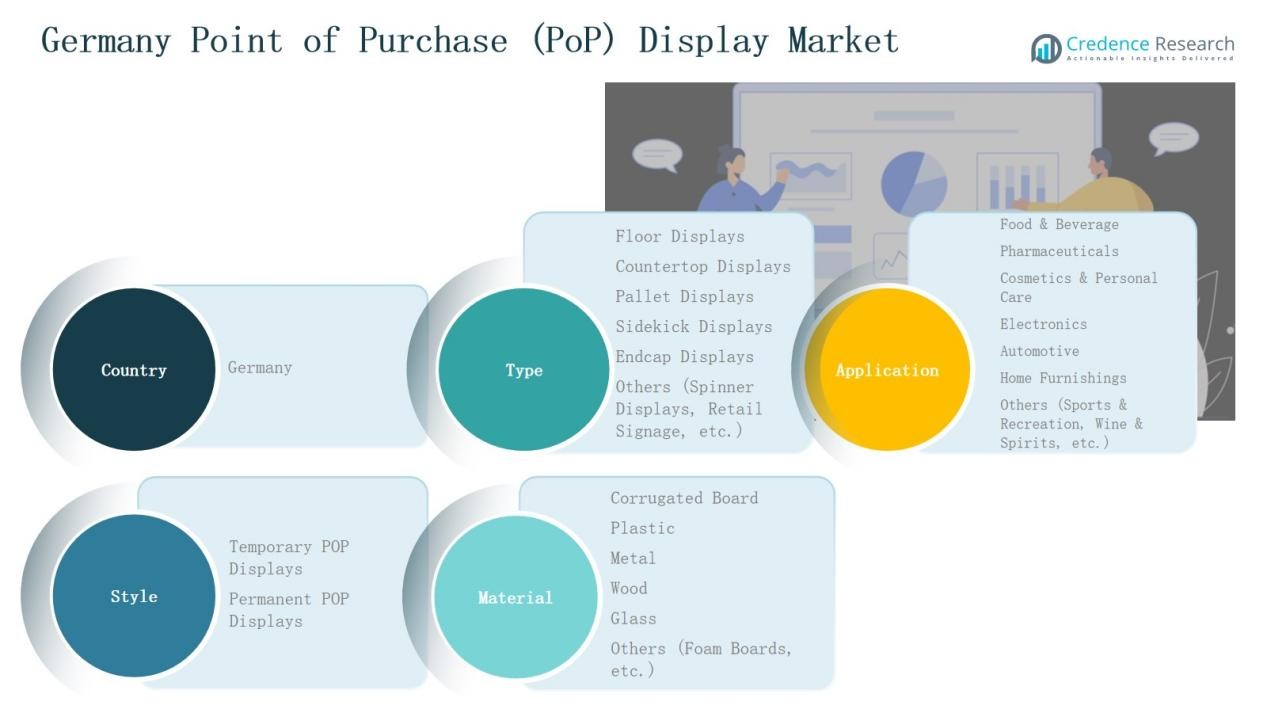
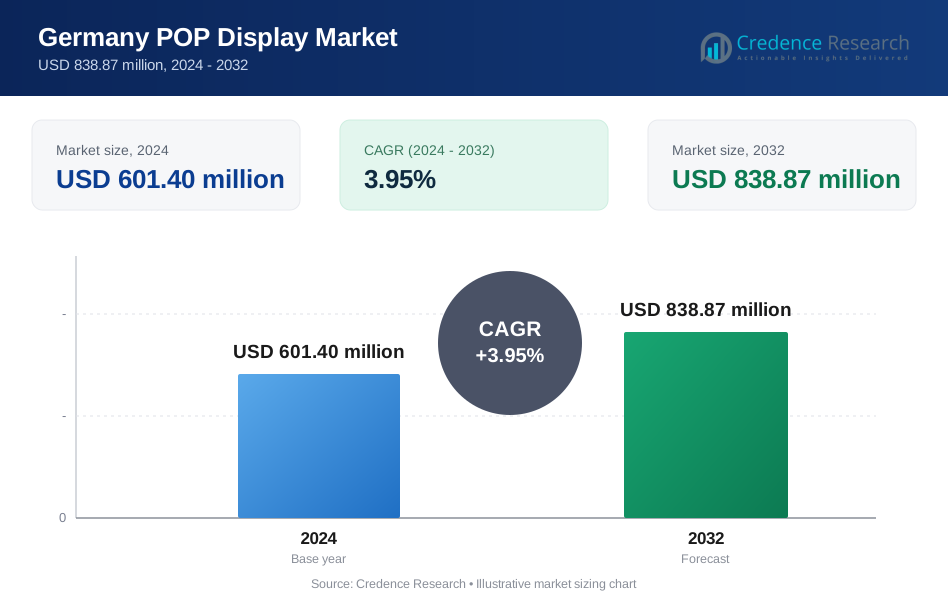
Germany Point of Purchase (PoP) Display Market size was valued at USD 439.72 million in 2018 to USD 601.40 million in 2024 and is anticipated to reach USD 838.87 million by 2032, at a CAGR of 3.95% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Point of Purchase (PoP) Display Market Size 2024 | USD 601.40 Million |
| Germany Point of Purchase (PoP) Display Market, CAGR | 3.95% |
| Germany Point of Purchase (PoP) Display Market Size 2032 | USD 838.87 Million |
The Germany Point of Purchase (PoP) Display Market is shaped by leading players such as POP Solutions Group, MHK Displays GmbH, Smurfit Kappa Group, DS Smith Plc, STI Group, Koehler Paper Group, Model Group, Panther Display, Kohlschein GmbH, and Thimm Group. These companies strengthen their positions through innovation, sustainability, and strong partnerships with FMCG, cosmetics, and electronics retailers. While global leaders focus on scalable, eco-friendly solutions, regional specialists emphasize customization and rapid service to support local retailers. In 2024, the South region led the market with 28% share, supported by dense retail infrastructure, strong FMCG activity, and high consumer spending, making it the most significant contributor to national revenue.
Market Insight
- The Germany Point of Purchase (PoP) Display Market grew from USD 439.72 million in 2018 to USD 601.40 million in 2024 and will reach USD 838.87 million by 2032.
- Floor displays dominated with 34% share in 2024, driven by supermarkets and large retail chains boosting impulse purchases and product visibility.
- The food & beverage segment led applications with 42% share in 2024, supported by FMCG promotions, packaged snacks, and strong demand for ready-to-drink products.
- Temporary PoP displays held 58% share in 2024, reflecting their cost-effectiveness and flexibility for seasonal promotions across diverse retail formats.
- The South region led with 28% share in 2024, followed by the West at 32%, highlighting strong FMCG activity, high spending, and robust retail infrastructure.
Market Segment Insights
By Type
Floor displays held the largest share of the Germany Point of Purchase (PoP) Display Market, accounting for around 34% of total revenue in 2024. Their dominance stems from strong adoption in supermarkets and large retail chains, where they effectively capture consumer attention and drive impulse purchases. Pallet and endcap displays follow, supported by their ability to promote bulk packaging and seasonal campaigns. Countertop and sidekick displays contribute to brand visibility in convenience stores, while niche categories such as spinner displays and retail signage add incremental value for specialty retail formats.
- For instance, in June 2024, DS Smith supplied floor display solutions for German supermarket chains, optimizing recyclable cardboard displays to improve product visibility for fast-moving consumer goods.
By Application
The food & beverage segment dominated the Germany Point of Purchase (PoP) Display Market, securing over 42% share in 2024. Strong demand for ready-to-drink products, packaged snacks, and promotional campaigns by FMCG giants reinforced growth in this segment. Cosmetics and personal care followed with notable traction, leveraging premium countertop and endcap displays to enhance brand appeal. Pharmaceuticals gained momentum due to rising OTC product visibility, while electronics and automotive applications used durable POP displays for feature-driven promotions. Niche categories, including sports, recreation, and wine & spirits, offered steady contributions, especially in premium retail outlets.
- For instance, Coca-Cola Germany launched limited-edition PoP displays across EDEKA outlets to promote its FIFA Euro 2024 tie-in beverages, driving retail engagement.
By Style
Temporary PoP displays led the Germany Point of Purchase (PoP) Display Market with a 58% revenue share in 2024, driven by their cost-effectiveness and flexibility for seasonal and promotional campaigns. Retailers widely prefer corrugated and lightweight formats for short-term events, enabling rapid deployment across diverse stores. Permanent PoP displays accounted for the remaining share, favored in luxury, electronics, and automotive retail due to their durability, high-quality materials, and long-term branding impact. The balance between temporary and permanent styles reflects Germany’s mix of promotional-driven FMCG retail and premium-focused specialty markets.
Key Growth Drivers
Rising Retail Modernization
Germany’s expanding network of supermarkets, hypermarkets, and convenience stores fuels demand for advanced PoP displays. Retail modernization initiatives encourage brands to adopt eye-catching floor and pallet displays that improve visibility and consumer engagement. Increasing competition among FMCG companies drives promotional activities, pushing retailers to invest in differentiated display solutions. This modernization enhances the shopping experience, boosts impulse purchases, and sustains steady growth for the PoP display market across the country.
Strong FMCG and Food & Beverage Demand
The food and beverage sector, accounting for the largest application share, anchors growth in Germany’s PoP display market. Frequent promotional campaigns, product launches, and seasonal marketing drive consistent adoption of temporary displays. Global and domestic FMCG companies leverage PoP formats to influence consumer decisions at checkout points. Rising consumption of packaged foods, beverages, and convenience items further strengthens demand, making food & beverage a major growth driver for the market.
Shift Toward Sustainable Materials
Sustainability has become a decisive factor for German retailers and brands, driving demand for eco-friendly PoP displays. Corrugated board, recyclable plastics, and responsibly sourced wood are increasingly preferred to reduce environmental impact. Regulatory pressures and consumer expectations around green practices encourage manufacturers to redesign displays with lower carbon footprints. This shift supports innovation in biodegradable and reusable materials, enabling retailers to align with sustainability goals while maintaining display effectiveness and brand appeal.
- For instance, DS Smith introduced a new line of 100% recyclable corrugated PoP displays in Germany, designed to cut carbon emissions by up to 30% compared to conventional plastic displays.
Key Trends & Opportunities
Digital Integration in Displays
The integration of digital features, including LED lighting, QR codes, and interactive screens, is gaining momentum in Germany’s PoP display market. Retailers are exploring these technologies to provide immersive product experiences and capture customer data. Digital elements help brands stand out in competitive retail environments, particularly in electronics and cosmetics. The adoption of such interactive solutions represents a significant opportunity for manufacturers, allowing them to deliver smarter, consumer-driven display formats that enhance engagement.
- For instance, Samsung Electronics Germany deployed interactive digital screens at MediaMarkt stores, allowing consumers to test product features virtually and compare devices on-screen before purchase.
Expansion in Premium Retail Sectors
Germany’s premium cosmetics, personal care, and electronics segments are creating new opportunities for high-quality, permanent PoP displays. Brands increasingly favor durable wood, glass, and metal structures that align with luxury retail standards. These displays not only support long-term brand visibility but also improve store aesthetics, reinforcing premium positioning. As consumer spending on luxury products rises, opportunities for innovative, permanent display solutions are set to expand, offering manufacturers profitable avenues beyond mass retail channels.
- For instance, Kling GmbH, a German display specialist, delivered custom high-gloss wooden and acrylic PoP displays for luxury cosmetics brands, emphasizing brand individuality and sustainable materials made in Germany.
Key Challenges
High Cost of Permanent Displays
Permanent PoP displays require significant investment due to expensive materials such as glass, metal, or wood. For retailers, especially small and mid-sized stores, the high upfront cost limits adoption. Brands may hesitate to allocate large budgets for long-term installations in competitive markets with frequent product turnover. Balancing durability with cost-efficiency remains a critical challenge for manufacturers and retailers seeking to expand premium PoP display usage in Germany.
Intense Market Competition
The Germany PoP display market is highly competitive, with global leaders and regional specialists vying for contracts. Continuous price pressure and the need for customization put strain on manufacturers’ profit margins. Companies must differentiate through innovation, design quality, and sustainability to remain competitive. Intense rivalry often leads to shorter product life cycles and faster design refresh requirements, creating operational challenges for both large-scale suppliers and smaller domestic players.
Regulatory and Environmental Pressures
Germany’s strict regulations on sustainability and packaging waste impose challenges on PoP display producers. Compliance requires constant investment in eco-friendly materials and processes, raising production costs. Retailers and brands face scrutiny from both regulators and consumers over environmental impact, which limits flexibility in material choices. Manufacturers must adapt quickly to evolving environmental standards while balancing cost, durability, and performance, making regulatory compliance a persistent challenge in the market.
Regional Analysis
North
The North region accounted for 22% share of the Germany Point of Purchase (PoP) Display Market in 2024. Strong retail presence in Hamburg and Bremen supports consistent adoption of floor and pallet displays. Food and beverage promotions drive significant demand, while increasing preference for sustainable corrugated board enhances market traction. The region’s well-established logistics networks encourage rapid rollout of temporary displays across supermarkets. Premium cosmetics and electronics retailers also invest in permanent PoP solutions. It remains a vital hub for display manufacturers seeking volume-driven opportunities.
South
The South region commanded 28% share of the market in 2024, driven by the dense retail infrastructure in Bavaria and Baden-Württemberg. Major FMCG and automotive companies leverage pallet and endcap displays for product visibility. High consumer spending power sustains adoption of permanent displays in electronics and personal care outlets. The region’s strong manufacturing base encourages innovation in eco-friendly materials. Seasonal promotional campaigns across large hypermarkets further boost temporary PoP demand. It continues to serve as the largest contributor to overall market revenue in Germany.
East
The East region captured 18% share of the Germany Point of Purchase (PoP) Display Market in 2024. Rising retail development in cities such as Leipzig and Dresden expands opportunities for countertop and sidekick displays. Supermarket expansion and growth of convenience chains fuel steady demand for temporary formats. Electronics and pharmaceutical sectors are emerging as strong adopters in urban clusters. Increasing awareness of sustainable practices is driving use of corrugated and recyclable materials. It reflects steady but growing adoption across diverse retail applications.
West
The West region held 32% share of the market in 2024, making it the second-largest after the South. Strong FMCG concentration in North Rhine-Westphalia and Hesse boosts high-volume display adoption. Supermarkets and discount chains actively deploy pallet and floor displays to promote packaged foods and beverages. Premium retail in Düsseldorf and Frankfurt accelerates demand for durable permanent formats. The presence of major display manufacturers ensures steady supply and design innovation. It stands out for its balanced contribution from both temporary and permanent display styles.
Market Segmentations:
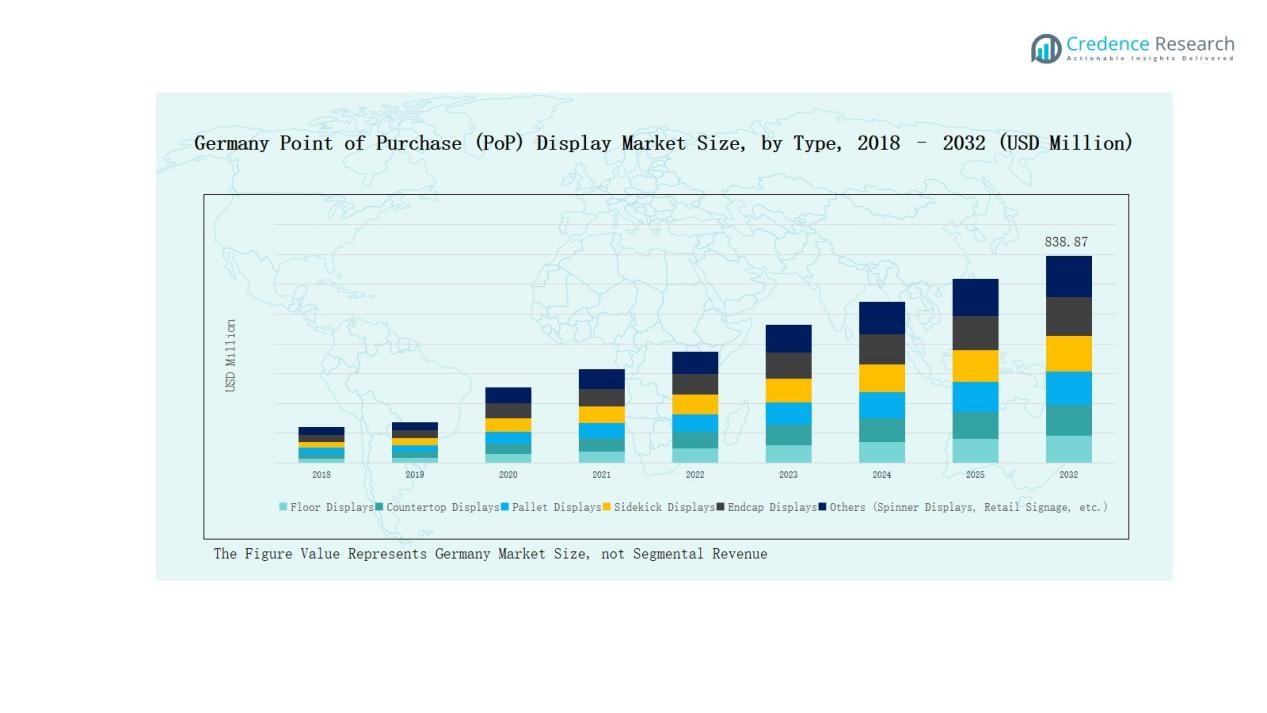
By Type
- Floor Displays
- Countertop Displays
- Pallet Displays
- Sidekick Displays
- Endcap Displays
- Others (Spinner Displays, Retail Signage, etc.)
By Application
- Food & Beverage
- Pharmaceuticals
- Cosmetics & Personal Care
- Electronics
- Automotive
- Home Furnishings
- Others (Sports & Recreation, Wine & Spirits, etc.)
By Style
- Temporary PoP Displays
- Permanent PoP Displays
By Material
- Corrugated Board
- Plastic
- Metal
- Wood
- Glass
- Others (Foam Boards, etc.)
By Region
- North
- South
- East
- West
Competitive Landscape
The Germany Point of Purchase (PoP) Display Market features a mix of global leaders and regional specialists competing for market share through design innovation, sustainability, and customer-focused solutions. Companies such as Smurfit Kappa Group, DS Smith Plc, and STI Group maintain strong positions by offering wide product portfolios, scalable production, and eco-friendly display options. Regional players like MHK Displays GmbH, Panther Display, and Kohlschein GmbH emphasize customization and flexible solutions to serve mid-sized retailers and niche markets. Intense competition drives continuous advancements in corrugated board and recyclable plastic displays to align with Germany’s strict sustainability regulations. Partnerships with FMCG brands, cosmetic companies, and premium electronics retailers play a vital role in strengthening visibility. Price sensitivity remains a challenge, pushing firms to balance cost efficiency with quality. Overall, the market is characterized by high rivalry, frequent product innovation, and strong emphasis on environmental compliance as a key differentiator.
Key Players
- POP Solutions Group
- MHK Displays GmbH
- Smurfit Kappa Group
- DS Smith Plc
- STI Group
- Koehler Paper Group
- Model Group
- Panther Display
- Kohlschein GmbH
- Thimm Group
Recent Developments
- In October 2024, POP Solutions Group acquired a majority stake in MHK Displays GmbH, strengthening its presence in the Germany Point of Purchase (PoP) Display Market.
- In June 2023, DS Smith introduced a new range of eco-friendly POP displays made from 100% recycled content designed for recyclability.
- In July 2023, Menasha Packaging Company partnered with a top consumer electronics brand to develop interactive floor displays for a new product launch.
Report Coverage
The research report offers an in-depth analysis based on Type, Application. Style, Material and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Retailers will increase adoption of eco-friendly corrugated and recyclable plastic displays.
- Demand for digital and interactive PoP displays will expand across electronics and cosmetics.
- Food and beverage promotions will remain the largest driver of temporary display usage.
- Permanent displays will gain traction in premium retail sectors such as luxury and automotive.
- Regional manufacturers will strengthen competitiveness through customization and quick turnaround services.
- Partnerships between FMCG companies and display providers will drive innovation in design.
- Regulatory focus on sustainability will accelerate investment in biodegradable display materials.
- Discount and convenience store formats will continue to expand demand for countertop displays.
- Increasing use of data-driven retail strategies will shape display placement and design decisions.
- The market will see rising competition between multinational suppliers and domestic specialists.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Germany Point of Purchase (PoP) Display Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Germany Point of Purchase (PoP) Display Market projected to grow between 2025 and 2032?
Which Germany Point of Purchase (PoP) Display Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Germany Point of Purchase (PoP) Display Market?
Who are the leading companies in the Germany Point of Purchase (PoP) Display Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany POP Display Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany POP Display Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 601.40 million → 2032: USD 838.87 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany POP Display Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany POP Display Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany POP Display Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany POP Display Market Drivers
- 3.3 Germany POP Display Market Restraints & Challenges
- 3.4 Germany POP Display Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany POP Display Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany POP Display Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany POP Display category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany POP Display Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany POP Display Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany POP Display market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany POP Display Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany POP Display Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany POP Display Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany POP Display (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany POP Display Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany POP Display Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany POP Display Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany POP Display Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany POP Display Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany POP Display Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany POP Display Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany POP Display Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany POP Display Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
