
Market Overview
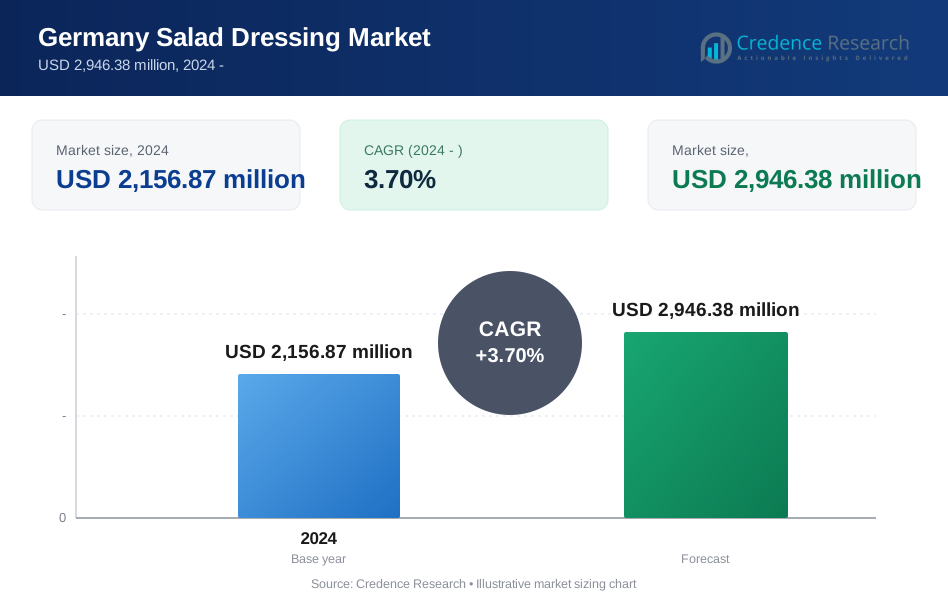
Germany Salad Dressing Market size was valued at USD 1,685.66 million in 2018 to USD 2,156.87 million in 2024 and is anticipated to reach USD 2,946.38 million by 2032, at a CAGR of 3.70 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Salad Dressing Market Size 2024 | USD 2,156.87 Million |
| Germany Salad Dressing Market, CAGR | 3.70% |
| Germany Salad Dressing Market Size 2032 | USD 2,946.38 Million |
The Germany Salad Dressing Market is highly competitive, with key players including Dr. Oetker, Remia, Homann-Feinkost GmbH, Kühne KG, Vogeley GmbH, Mautner Markhof Feinkost GmbH, Supro-Nährmittel AG, Heinrich Kühlmann GmbH & Co. KG, Stokes Sauces, and Bagel Brothers GmbH. These companies compete through product innovation, strong retail networks, and expansion into organic and clean-label offerings to meet evolving consumer preferences. Among regional markets, Berlin leads with a 28% share, driven by diverse consumer demand, modern retail infrastructure, and rising adoption of organic and premium dressings, positioning it as the growth hub in Germany.
Market Insights
- The Germany Salad Dressing Market grew from USD 1,685.66 million in 2018 to USD 2,156.87 million in 2024 and is projected to reach USD 2,946.38 million by 2032, at a CAGR of 3.70%.
- Mayonnaise led the market with a 38% share in 2024, while sauces and vinaigrettes gained traction through consumer preference for international flavors and healthier alternatives.
- Conventional dressings dominated with 72% share, but organic products at 28% are expanding quickly, supported by growing demand for clean-label, natural, and sustainable options.
- Retail stores commanded 54% of sales, followed by foodservice at 33%, while off-trade channels at 13% are expanding due to rising e-commerce penetration in Germany.
- Berlin led with 28% market share in 2024, followed by Munich at 25%, Bremen at 24%, and Hamburg at 23%, highlighting strong regional diversity in consumption patterns.
Market Segment Insights
By Product Type
Mayonnaise holds the dominant position in the Germany Salad Dressing Market with a 38% share. Its popularity is driven by strong consumer preference for creamy textures, versatility in both home and foodservice use, and frequent innovation in flavors. Sauces follow closely, supported by rising demand for international cuisine and convenient ready-to-use products. Oil-based dressings such as vinaigrettes maintain steady adoption among health-conscious consumers emphasizing lighter options. Balsamic, ranch, and Italian dressings show stable but niche demand, catering to specific taste profiles, while other varieties contribute marginally to overall growth.
For instance, Unilever Germany expanded its Hellmann’s mayonnaise portfolio by launching a vegan mayonnaise variant to meet the growing flexitarian and plant-based food demand.
By Category
Conventional products dominate the Germany Salad Dressing Market with a 72% share, reflecting affordability, widespread availability, and consumer familiarity with traditional brands. Conventional dressings continue to benefit from strong retail penetration and extensive product variety across supermarkets and foodservice outlets. Organic dressings, holding a 28% share, are steadily gaining traction, supported by Germany’s rising preference for clean-label, natural, and sustainable food choices. The organic segment is further driven by expanding availability in premium retail chains and increasing consumer awareness of healthier alternatives.
By Distribution Channel
Retail stores lead the Germany Salad Dressing Market with a 54% share, supported by strong supermarket and hypermarket networks that provide broad product visibility and convenience. Foodservice channels contribute 33% of sales, benefiting from Germany’s growing dining-out culture and the extensive use of dressings in quick-service and casual dining establishments. Other off-trade channels account for 13%, covering online platforms and specialty stores that serve niche or premium consumer segments. Rising e-commerce penetration is expected to strengthen growth in the off-trade segment, particularly for premium and organic dressings.
For instance, REWE Group expanded its private-label salad dressing line in Germany with organic variants under the “REWE Bio” brand, targeting growing demand for natural and clean-label products.
 Key Growth Drivers
Rising Consumer Preference for Convenience Foods
The demand for ready-to-use salad dressings in Germany continues to grow, supported by fast-paced lifestyles and increased adoption of convenience-based meals. Consumers prefer packaged dressings that reduce preparation time while maintaining taste variety, particularly mayonnaise and sauces. Supermarkets and quick-service restaurants heavily promote these products, strengthening their visibility. This shift in consumption patterns positions salad dressings as essential pantry staples, fueling consistent market growth across both retail and foodservice channels.
For instance, Unilever launched Hellmann’s vegan mayonnaise in Germany, meeting rising demand for plant-based dressing alternatives in both retail and foodservice channels.
Increasing Health-Conscious Consumption
German consumers are becoming more health-conscious, driving strong interest in oil-based vinaigrettes and organic dressings. These products appeal to individuals seeking lighter, low-fat, or clean-label alternatives. The trend aligns with Germany’s broader move toward natural and sustainable food consumption. Retailers are expanding shelf space for such products, while manufacturers introduce innovations like low-calorie or additive-free variants. This driver creates a pathway for premium and differentiated products to gain traction in a competitive market landscape.
For instance, Kraft Heinz acquired a majority stake in Just Spices to roll out clean-label salad dressings in German retail, emphasizing natural ingredients and transparency.
Expansion of Retail and E-commerce Channels
The well-established retail sector in Germany provides significant support to the salad dressing market, ensuring wide product distribution. Hypermarkets, supermarkets, and specialty stores dominate, but the rapid expansion of e-commerce is reshaping purchasing behavior. Online platforms allow brands to reach younger and urban consumers who value convenience and diverse options. With digital promotions and direct-to-consumer models gaining popularity, this distribution expansion is accelerating product accessibility, boosting both conventional and organic categories.
Key Trends & Opportunities
Growth of Organic and Clean-Label Products
Organic salad dressings represent an emerging opportunity, driven by Germany’s strong consumer preference for natural and chemical-free foods. Shoppers increasingly associate health benefits with clean-label and sustainably sourced products. Brands introducing certified organic or non-GMO dressings are finding acceptance in both premium retail and online channels. This trend supports premiumization while addressing sustainability concerns, creating new avenues for product differentiation in a mature market.
For instance, Briannas launched a line of dressings made with certified non-GMO ingredients, free from artificial flavors, synthetic colors, chemicals or preservatives.
Innovation in Flavors and Packaging
Manufacturers are investing in flavor innovation to capture diverse consumer palates, introducing regional and international recipe-based dressings. At the same time, packaging innovation, such as resealable bottles, squeezable pouches, and eco-friendly containers, is enhancing usability and sustainability appeal. These innovations not only attract younger consumers but also reinforce brand loyalty in competitive retail spaces. This trend highlights opportunities for companies to strengthen their market position by aligning with consumer demand for novelty and convenience.
For instance, Kraft Heinz Canada launched Pure J.L. KRAFT Dressings & Marinades in 2024. The line has twelve premium, shelf-stable offerings made without artificial preservatives, flavours, or colours.
 Key Challenges
Price Sensitivity Among Consumers
Despite premiumization trends, a significant portion of German consumers remains price-sensitive, particularly in the conventional dressing category. Discount retailers and private-label brands often dominate this segment, putting pressure on margins for established players. Balancing affordability with innovation becomes a key challenge for manufacturers. Brands must ensure competitive pricing while still meeting evolving consumer expectations on quality and variety.
Intense Market Competition
The Germany Salad Dressing Market is highly competitive, with international brands, regional players, and private labels all vying for market share. Continuous product innovation and aggressive marketing strategies are required to maintain visibility. This competition reduces brand differentiation and increases pressure on advertising budgets. Smaller brands often face difficulties establishing strong footholds in an environment dominated by established names and low-cost alternatives.
Regulatory and Labeling Requirements
Germany enforces strict regulations on food labeling, ingredient disclosure, and health claims, creating challenges for manufacturers. Compliance with these standards increases production costs and slows down product launches. Companies also face pressure to reformulate recipes to eliminate additives or reduce fat, sugar, and salt content. Failure to meet evolving standards can result in reputational risks and limited market access, making regulatory compliance a key barrier to growth.
Regional Analysis
Berlin
Berlin accounted for 28% of the Germany Salad Dressing Market in 2024, supported by its diverse consumer base and strong demand for convenience foods. The city reflects a mix of traditional preferences for mayonnaise and rising adoption of organic vinaigrettes. It benefits from modern retail infrastructure and the presence of international brands that cater to varied tastes. Health-conscious consumers in Berlin are driving growth of organic dressings, supported by clean-label demand. Foodservice outlets also create consistent demand for sauces and flavored variants. The regional market shows steady growth, fueled by both premiumization and affordability-driven private labels.
Munich
Munich represented 25% of the Germany Salad Dressing Market in 2024, strengthened by high disposable income and preference for premium food products. It remains a strong market for mayonnaise and sauces, with increasing traction for balsamic and Italian dressings. Retail chains in Munich actively expand shelf space for organic and sustainable options, reflecting consumer preference for healthier choices. It is driven by an active dining culture, where foodservice outlets contribute significantly to sales. Innovative packaging solutions and premium flavors gain high acceptance among younger consumers. This dynamic consumer environment ensures long-term growth prospects in the region.
Hamburg
Hamburg contributed 23% of the Germany Salad Dressing Market in 2024, benefiting from its position as a key port city with diverse culinary influences. The market here is led by sauces and oil-based dressings, supported by demand from multicultural households. It also gains strength from strong foodservice demand, particularly in casual dining and quick-service restaurants. The region reflects growing adoption of eco-friendly packaging, which supports sustainable brand positioning. It demonstrates steady performance across conventional and organic categories. Hamburg continues to attract both domestic and international players with its evolving consumer base.
Bremen
Bremen held 24% of the Germany Salad Dressing Market in 2024, with strong reliance on retail sales and growing preference for affordable conventional products. It maintains a high share for mayonnaise, but interest in ranch and vinaigrettes is gradually increasing. The region benefits from supermarket and discount store penetration that strengthens accessibility. It is supported by competitive pricing strategies of private-label brands, which influence consumer purchasing behavior. The organic segment shows gradual expansion as awareness of health and sustainability grows. Bremen provides a balanced market with opportunities for both mass-market and niche players.
 Market Segmentations:
By Product Type
- Mayonnaise
- Sauces
- Oil-Based Dressings (Vinaigrettes)
- Balsamic Dressing
- Ranch Dressing
- Italian Dressing
- Others
By Category
- Conventional
- Organic
By Distribution Channel
- Foodservice
- Retail Stores
- Other Off-trade Channels
By Region
- Berlin
- Munich
- Hamburg
- Bremen
Competitive Landscape
The Germany Salad Dressing Market is characterized by strong competition among established domestic players, international brands, and private labels. Companies such as Dr. Oetker, Kühne KG, Homann-Feinkost GmbH, and Remia dominate through wide product portfolios and strong distribution across retail and foodservice channels. These brands focus on product innovation, expanding organic and clean-label ranges to align with consumer health trends. Private labels from discount retailers also hold a significant share, appealing to price-sensitive buyers with affordable alternatives. International players enhance competitiveness by introducing global flavors and premium dressings tailored to German consumer preferences. Marketing strategies emphasize brand differentiation through packaging innovation, flavor variety, and sustainable sourcing practices. Mergers, acquisitions, and partnerships further strengthen market positioning and help companies expand presence in e-commerce. The competitive environment continues to intensify, requiring continuous innovation, compliance with strict regulations, and adaptability to evolving consumer demand for healthier and premium dressing options.
Key Players
- Oetker
- Remia
- Homann-Feinkost GmbH
- Kühne KG
- Vogeley GmbH
- Mautner Markhof Feinkost GmbH
- Supro-Nährmittel AG
- Heinrich Kühlmann GmbH & Co. KG
- Stokes Sauces
- Bagel Brothers GmbH
Recent Developments
- In April 2025, Foodiverse and Taylor Farms completed the acquisition of Bonduelle Group’s salad operations in Germany.
- In March 2025, Bonduelle finalized the sale of its packaged salad business assets in Germany to Taylor Farms.
- In August 2025, Dole launched its Apple Harvest Premium Salad Kit in the market, featuring a unique apple cider vinaigrette, as part of its seasonal fall product lineup aimed at meeting consumer demand for restaurant-inspired salad experiences at home.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Category, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer demand for organic and clean-label salad dressings will continue to rise.
- Mayonnaise will retain dominance, but vinaigrettes and balsamic dressings will gain popularity.
- E-commerce sales will expand as online grocery shopping becomes more common in Germany.
- Retail stores will maintain leadership, though foodservice adoption will strengthen.
- Flavor innovation will drive growth, with international and regional tastes gaining attention.
- Sustainable and eco-friendly packaging will become a core focus for manufacturers.
- Private label dressings will expand, creating stronger competition for established brands.
- Health-focused consumers will prefer low-fat, low-sugar, and additive-free options.
- Marketing strategies will emphasize premiumization and product differentiation.
- Strategic partnerships and acquisitions will shape competitive positioning in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Germany Salad Dressing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Germany Salad Dressing Market projected to grow between 2025 and 2032?
Which Germany Salad Dressing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Germany Salad Dressing Market?
Who are the leading companies in the Germany Salad Dressing Market?
Which region commanded the largest share of the Germany Salad Dressing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Salad Dressing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Salad Dressing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,156.87 million → forecast year: USD 2,946.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Salad Dressing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Salad Dressing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Salad Dressing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Salad Dressing Market Drivers
- 3.3 Germany Salad Dressing Market Restraints & Challenges
- 3.4 Germany Salad Dressing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Salad Dressing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Salad Dressing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Salad Dressing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Salad Dressing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Salad Dressing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Salad Dressing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Salad Dressing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Salad Dressing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Salad Dressing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Salad Dressing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Salad Dressing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Salad Dressing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Salad Dressing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Salad Dressing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Salad Dressing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Salad Dressing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Salad Dressing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Salad Dressing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Salad Dressing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
