
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rainwater Harvesting Market Size 2024 | USD 1,081.47 million |
| Rainwater Harvesting Market, CAGR | 9.66% |
| Rainwater Harvesting Market Size 2032 | USD 2,239.96 million |
Market Overview
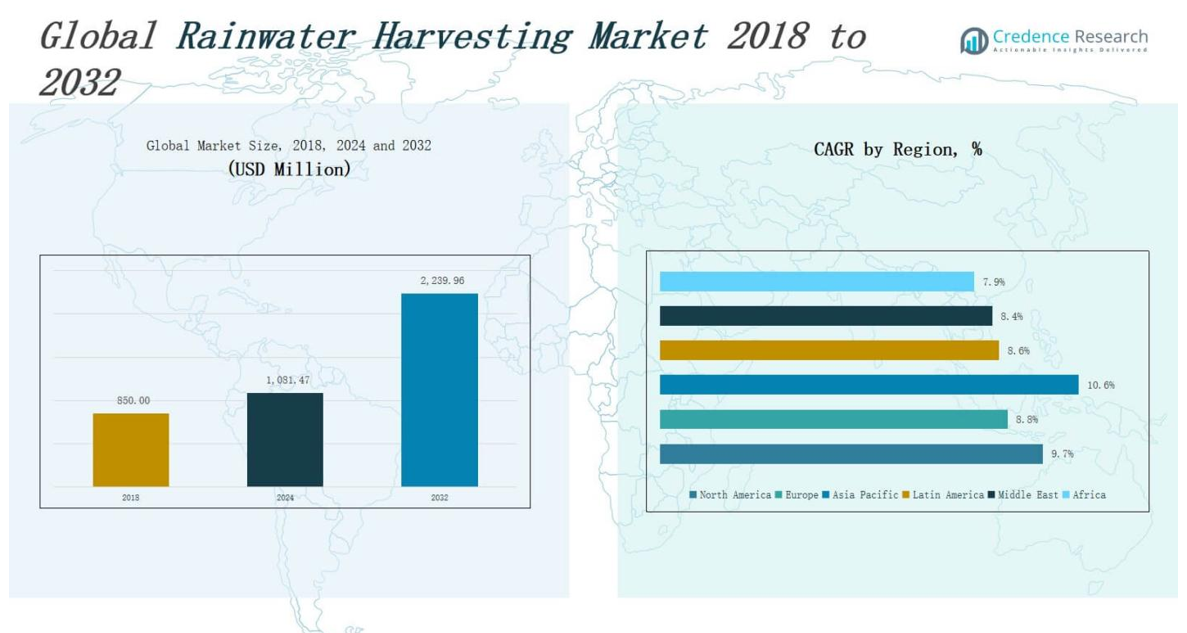
The Rainwater Harvesting Market size was valued at USD 850.00 million in 2018 to USD 1,081.47 million in 2024 and is anticipated to reach USD 2,239.96 million by 2032, at a CAGR of 9.66 % during the forecast period.
The Rainwater Harvesting Market is witnessing robust growth driven by increasing water scarcity, rising awareness of sustainable water management, and supportive government regulations promoting rainwater collection systems. Rapid urbanization and industrial expansion are straining existing water infrastructure, prompting adoption of decentralized water solutions like rainwater harvesting across residential, commercial, and industrial sectors. Technological advancements in filtration, storage, and automated harvesting systems are enhancing efficiency and user adoption. Green building initiatives and certifications such as LEED are further encouraging integration of rainwater systems in modern construction. In addition, climate change-induced irregular rainfall patterns are elevating the need for alternative water sources, particularly in drought-prone and arid regions. The market also benefits from cost savings associated with reduced reliance on municipal water supply and lower stormwater management costs. Increasing public and private sector investment in water conservation technologies and growing emphasis on environmental compliance are reinforcing the trend toward sustainable water solutions, propelling the demand for rainwater harvesting systems globally.
The Rainwater Harvesting Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. Asia Pacific leads the market due to rapid urbanization, water scarcity, and strong government support in countries like India and China. North America and Europe follow, driven by stringent environmental regulations and adoption in green building projects. Latin America, the Middle East, and Africa show growing demand, especially in rural and drought-prone areas. It benefits from public initiatives, infrastructure development, and rising awareness of water conservation. Key players in the market include Kingspan Group Plc, Watts Water Technologies Inc., Otto Graf GmbH, Barr Plastics Inc., Stormsaver Ltd., Ecozi Ltd., RainHarvest Systems LLC, and Water Harvesting Solutions Inc., each contributing to innovation, global expansion, and tailored system offerings to meet diverse application needs across these geographies.
Market Insights
- The Rainwater Harvesting Market was valued at USD 850.00 million in 2018 and is projected to reach USD 2,239.96 million by 2032, growing at a CAGR of 9.66%.
- Rising water scarcity, rapid urbanization, and strained municipal infrastructure are accelerating demand for decentralized rainwater systems across residential, commercial, and industrial sectors.
- Supportive government policies, tax incentives, and mandates for rainwater systems in new construction are driving global adoption.
- Technological advancements in storage, filtration, and automation are improving system efficiency, making them more accessible and appealing to end-users.
- The market faces challenges due to lack of regulatory standardization and high initial costs, especially in rural and low-income regions.
- Asia Pacific leads the global market, followed by North America and Europe, while Latin America, the Middle East, and Africa show rising demand driven by water shortages and rural development initiatives.
- Key players include Kingspan Group Plc, Watts Water Technologies Inc., Otto Graf GmbH, Barr Plastics Inc., Stormsaver Ltd., Ecozi Ltd., and RainHarvest Systems LLC.
Market Drivers
Growing Water Scarcity and Stress on Conventional Resources
The Rainwater Harvesting Market is expanding due to the rising global water crisis and declining freshwater availability. Increasing population, industrialization, and agricultural activities are straining conventional water supplies. Governments and environmental agencies are promoting alternative sources like rainwater harvesting to ease the burden. It provides a decentralized and cost-effective solution in both urban and rural areas. The market is gaining traction in water-stressed regions, where conventional infrastructure cannot meet demand. Climate variability also makes it a vital resource.
- For instance, in Uganda, the UNEP Copenhagen Climate Centre is collaborating with local partners to promote rooftop rainwater harvesting as a climate adaptation tool, prioritizing water storage technologies identified in the country’s Technology Needs Assessments.
Government Policies and Regulatory Support
Supportive regulations and incentives are accelerating the adoption of rainwater harvesting systems worldwide. Mandates in several countries require new construction projects to include rainwater collection infrastructure. Tax benefits, subsidies, and grants encourage residential and commercial users to invest in these systems. It aligns with global sustainability goals and water conservation policies. Municipal bodies are enforcing compliance to reduce reliance on public water supply. The Rainwater Harvesting Market benefits directly from these institutional frameworks.
- For instance, the West Bengal government mandates rainwater harvesting for large construction projects exceeding 20,000 square meters, specifying minimum percentages for surface storage and groundwater recharge based on building height to ensure effective water conservation.
Technological Advancements and System Efficiency
Technological progress is enhancing the efficiency, reliability, and usability of rainwater harvesting systems. Innovations in storage tanks, filtration units, smart sensors, and automated pumps are making these systems more appealing to consumers. It allows seamless integration with building management systems and optimizes water collection and usage. Low-maintenance designs are encouraging broader adoption in urban settings. The Rainwater Harvesting Market is responding to demand for user-friendly, efficient, and scalable solutions that meet diverse water needs.
Rising Demand from Green Building and Sustainability Initiatives
The rise of eco-conscious construction and sustainability standards is fueling demand for rainwater harvesting solutions. Certifications like LEED and BREEAM promote use of rainwater systems in energy-efficient buildings. Developers and facility managers are integrating these systems to reduce environmental impact and operational costs. It supports water self-sufficiency and aligns with circular resource strategies. The Rainwater Harvesting Market is growing as builders seek to meet environmental benchmarks and consumer demand for sustainable infrastructure.
Market Trends
Integration with Smart Water Management Technologies
Smart technologies are transforming how rainwater harvesting systems are monitored and operated. IoT-enabled sensors, automated filtration units, and real-time data analytics are allowing users to track water levels, quality, and consumption patterns. These features improve water efficiency and support predictive maintenance. Building management systems increasingly integrate rainwater harvesting into overall water usage strategies. It enables more responsive control and greater user awareness. The Rainwater Harvesting Market is aligning with the broader shift toward smart and sustainable infrastructure.
- For instance, Rain Harvesting Connect in Australia offers smart tank gauges with float and pressure sensors, providing water level accuracy to within 20mm and 50mm respectively, and allows users to monitor all gauges and set custom alerts via a smartphone app.
Adoption in Urban Infrastructure and Real Estate Projects
Urban developers are prioritizing rainwater harvesting systems in residential, commercial, and institutional projects. Space-efficient and modular designs are allowing easier implementation in dense urban settings. Real estate regulations and environmental standards are encouraging project developers to integrate such systems early in the planning stage. It provides long-term operational savings and enhances project sustainability ratings. The Rainwater Harvesting Market is benefiting from the increased alignment of urban planning with green infrastructure and water resilience goals.
- For instance, Infosys has implemented rainwater harvesting across its Bengaluru campus, collecting over 200 million liters of rainwater each year, as documented in its 2024 Sustainability Report.
Increased Focus on Rural and Agricultural Applications
The market is expanding into rural areas where agricultural and domestic water demand often exceeds supply. Governments and NGOs are deploying low-cost, community-based rainwater harvesting systems to ensure water availability for irrigation and livestock. It offers a reliable backup during dry seasons and improves soil moisture retention. Farmers are adopting rooftop and surface catchment methods for better water access. The Rainwater Harvesting Market is gaining momentum in regions where traditional irrigation systems are inadequate or unreliable.
Rising Preference for Modular and Customizable Systems
End users are increasingly opting for modular rainwater harvesting systems that can be tailored to specific site requirements. Scalable tank sizes, flexible filtration options, and customizable layouts are supporting wider adoption in both residential and industrial sectors. It enables cost-efficient deployment without overhauling existing infrastructure. These systems are particularly popular in retrofitting projects. The Rainwater Harvesting Market is responding to this trend by offering plug-and-play solutions that simplify installation and operation across varied environments.
Market Challenges Analysis
Lack of Standardization and Regulatory Uniformity
The Rainwater Harvesting Market faces challenges due to inconsistent regulations and a lack of standardized practices across regions. In many countries, there is no uniform code governing the design, installation, or quality control of rainwater harvesting systems. This regulatory fragmentation creates uncertainty for manufacturers, contractors, and end users. It limits large-scale adoption, particularly in commercial and industrial applications. Absence of performance benchmarks also affects consumer confidence. The Rainwater Harvesting Market requires clearer policy frameworks to support wider and safer implementation.
High Initial Costs and Limited Public Awareness
High upfront costs related to equipment, installation, and maintenance hinder market growth, especially in low-income and rural areas. Many users are unaware of the long-term economic and environmental benefits of rainwater harvesting. It reduces the willingness to invest, even where water scarcity is a serious concern. Lack of awareness campaigns, technical training, and financial incentives further slows adoption. The Rainwater Harvesting Market must address these cost and knowledge barriers to reach its full potential across diverse user segments.
Market Opportunities
Expansion in Industrial and Commercial Sectors
The Rainwater Harvesting Market has strong opportunities in the industrial and commercial segments where water usage is high and operational cost savings are a priority. Manufacturing plants, hospitality chains, and large office complexes can reduce dependence on municipal supplies by implementing rainwater harvesting systems. It supports sustainability goals and helps meet environmental compliance standards. Developers are exploring integration into green building designs to enhance LEED or BREEAM ratings. Custom-engineered systems tailored for high-capacity use cases are gaining traction. The market can capitalize on this demand by offering scalable and automated solutions.
Rising Demand in Water-Stressed Emerging Economies
Emerging economies with growing populations and limited water infrastructure present significant opportunities for the Rainwater Harvesting Market. Countries in Asia, Africa, and Latin America face frequent droughts, making alternative water sources essential. Government programs promoting decentralized water systems create a favorable environment for adoption. It allows rural communities to improve water access without relying on expensive public infrastructure. NGOs and international agencies are also funding rainwater projects in remote areas. The market has room to grow by developing affordable, easy-to-maintain systems tailored for these regions.
Market Segmentation Analysis:
By Component
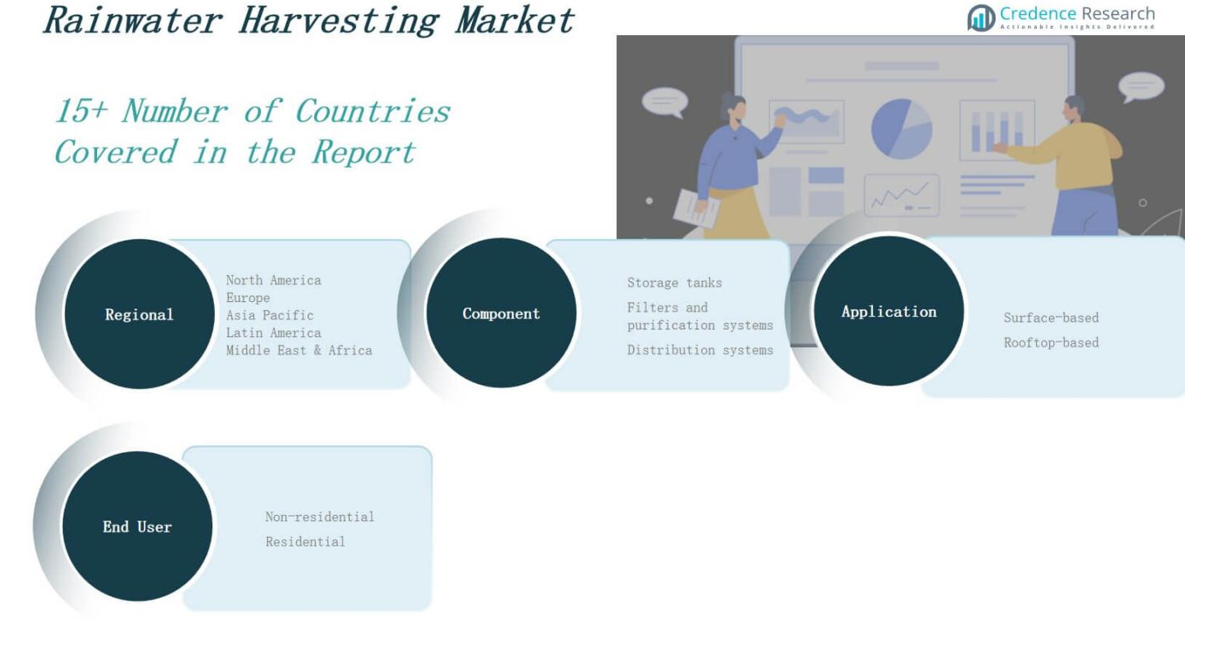
The Rainwater Harvesting Market is segmented into storage tanks, filters and purification systems, and distribution systems. Storage tanks hold the largest share due to their essential role in water collection and retention. Demand is rising for durable, corrosion-resistant tanks in both above-ground and underground configurations. Filters and purification systems are gaining traction with the increasing need for potable and clean water. Distribution systems, though smaller in share, are vital for moving harvested water efficiently across applications.
- For instance, Camplas supplies GRP (Glass-Reinforced Plastic) tanks, recognized for their corrosion resistance and high tensile strength-over 13,000 Camplas SuperTanks are installed worldwide, supporting long-term outdoor use and customizable capacities up to 100 cubic meters.
By Application
Based on application, the market is divided into surface-based and rooftop-based systems. Rooftop-based systems dominate due to their widespread use in residential and small commercial buildings. They are easier to install and maintain, making them cost-effective for urban settings. Surface-based systems are more prevalent in large-scale and rural applications where land availability is not a constraint. The Rainwater Harvesting Market sees growing adoption of hybrid systems to optimize collection across multiple surfaces.
- For instance, Tata Power Solar has installed over 10,000 rooftop solar water harvesting systems across Indian cities, significantly reducing municipal water demand in residential complexes. Surface-based systems are more prevalent in large-scale and rural applications where land availability is not a constraint.
By End-user
The end-user segment includes residential and non-residential users. Residential users lead the market, driven by water conservation awareness and integration in eco-friendly housing. Governments support adoption through incentives and regulations. Non-residential users such as industries, commercial buildings, and institutions are increasing investments to reduce utility costs and comply with sustainability targets. It benefits from expanding infrastructure that supports high-volume, automated systems tailored to large-scale water demands.
Segments:
Based on Component
- Storage Tanks
- Filters and Purification Systems
- Distribution Systems
Based on Application
- Surface-based
- Rooftop-based
Based on End-user
- Residential
- Non-residential
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Rainwater Harvesting Market size was valued at USD 226.95 million in 2018 to USD 283.99 million in 2024 and is anticipated to reach USD 587.10 million by 2032, at a CAGR of 9.7% during the forecast period. The region holds a significant share due to strong regulatory frameworks promoting water conservation in the U.S. and Canada. Adoption is high in residential, commercial, and institutional sectors. It benefits from advanced infrastructure and strong awareness of environmental sustainability. Demand for smart rainwater harvesting systems is growing in urban development projects. The Rainwater Harvesting Market in North America is also driven by the need to reduce dependence on municipal water systems in drought-prone areas.
Europe
The Europe Rainwater Harvesting Market size was valued at USD 194.57 million in 2018 to USD 236.49 million in 2024 and is anticipated to reach USD 458.41 million by 2032, at a CAGR of 8.8% during the forecast period. Europe has a mature market with strong environmental policies supporting rainwater reuse. Countries like Germany, the UK, and France promote rainwater harvesting in buildings through construction codes and green building certifications. It sees widespread adoption in both residential and commercial developments. Urban infrastructure planning increasingly includes water conservation technologies. The Rainwater Harvesting Market in Europe is reinforced by high public awareness and institutional investment.
Asia Pacific
The Asia Pacific Rainwater Harvesting Market size was valued at USD 316.29 million in 2018 to USD 414.14 million in 2024 and is anticipated to reach USD 917.04 million by 2032, at a CAGR of 10.6% during the forecast period. The region leads in market share due to growing water scarcity, large population, and expanding urbanization. Governments in India, China, and Southeast Asia actively promote adoption through public initiatives and infrastructure mandates. It offers high potential in both rural and urban areas. Residential use dominates, but industrial uptake is rising. The Rainwater Harvesting Market in Asia Pacific is rapidly evolving, supported by low-cost systems and high demand for sustainable water access.
Latin America
The Latin America Rainwater Harvesting Market size was valued at USD 49.13 million in 2018 to USD 61.85 million in 2024 and is anticipated to reach USD 117.98 million by 2032, at a CAGR of 8.6% during the forecast period. Brazil and Argentina are key contributors due to frequent droughts and inadequate public water infrastructure in rural areas. Adoption is rising in agriculture and residential sectors. It is supported by local initiatives promoting water independence. Urban centers are integrating rainwater harvesting into sustainable housing and public facilities. The Rainwater Harvesting Market in Latin America is gaining attention for its potential to reduce pressure on municipal systems.
Middle East
The Middle East Rainwater Harvesting Market size was valued at USD 34.85 million in 2018 to USD 41.74 million in 2024 and is anticipated to reach USD 78.63 million by 2032, at a CAGR of 8.4% during the forecast period. Extreme water scarcity and arid climate drive the need for alternative water sources across the region. Countries like the UAE and Saudi Arabia are investing in water sustainability, including rainwater collection. It is gaining momentum in infrastructure development projects and green building initiatives. The Rainwater Harvesting Market in the Middle East benefits from growing emphasis on non-conventional water solutions. Commercial and institutional segments show strong growth potential.
Africa
The Africa Rainwater Harvesting Market size was valued at USD 28.22 million in 2018 to USD 43.26 million in 2024 and is anticipated to reach USD 80.79 million by 2032, at a CAGR of 7.9% during the forecast period. Large rural populations and limited access to piped water systems create strong demand for decentralized water collection. NGOs and international donors support rainwater harvesting for domestic and agricultural use. It is especially vital in regions with seasonal rainfall and poor infrastructure. Adoption is growing in schools, health centers, and small farms. The Rainwater Harvesting Market in Africa presents significant opportunity for affordable and scalable system providers.
Key Player Analysis
- Barr Plastics Inc.
- Ecozi Ltd.
- HarvestH2o
- Heritage Water Tanks
- Innovative Water Solutions LLC
- Kingspan Group Plc
- Metroll
- Molloy Precast Products Ltd.
- Oasis Water Harvesting
- Osmosis Autopump India Pvt. Ltd.
- Otto Graf GmbH Kunststofferzeugnisse
- RainHarvest Systems LLC
- Rainwater Connection
- Stormsaver Ltd.
- Vareo Blu Ltd.
- Water Field Technologies Pvt. Ltd.
- Water Harvesting Solutions Inc.
- Watts Water Technologies Inc.
- WISY AG
Competitive Analysis
The Rainwater Harvesting Market features a mix of global and regional players competing through product innovation, pricing strategies, and geographic expansion. Leading companies focus on delivering modular, cost-effective, and easy-to-install systems tailored to residential, commercial, and industrial needs. It is witnessing increased investment in smart technologies, including automated controls and filtration systems. Companies such as Kingspan Group Plc, Watts Water Technologies Inc., and Otto Graf GmbH maintain strong positions through diversified product portfolios and strategic partnerships. Smaller players target niche markets with customized and region-specific solutions. The Rainwater Harvesting Market is shaped by regulatory standards, sustainability goals, and rising demand across water-stressed regions. Competition remains intense as companies aim to strengthen distribution networks and scale operations in emerging economies. Strategic mergers, local manufacturing, and after-sales service are key factors enhancing competitive advantage across the sector.
Recent Developments
- In July 2023, Oldcastle Infrastructure acquired Hydro International Ltd. to expand its portfolio of stormwater and rainwater harvesting solutions, strengthening its position in global water management systems.
- In January 2025, Rain Enhancement Technologies Holdco (RET Holdco) began trading on NASDAQ under the ticker symbols RAIN and RAINW, following a merger with Coliseum Acquisition Corp, marking a significant entry into the rain-enhancement and harvesting sector.
- In February 2023, Stormsaver Ltd. introduced two new residential rainwater harvesting systems equipped with integrated GRP tanks and twin booster pumps, enhancing domestic water conservation efficiency.
- In March 2025, Hitachi Energy launched a rainwater harvesting project at its Halol factory in western India as part of its sustainability initiatives.
Market Concentration & Characteristics
The Rainwater Harvesting Market is moderately fragmented, with a mix of global corporations and regional players competing across various segments. It is characterized by strong product diversification, with offerings ranging from basic storage tanks to advanced automated systems integrated with smart technologies. Companies focus on innovation, cost efficiency, and regional customization to meet varying climatic and infrastructural needs. The market favors scalable and modular solutions, allowing both rural and urban users to adopt systems suited to their needs. Entry barriers are moderate, driven by regulatory requirements, upfront investment, and the need for technical expertise in system design and maintenance. Strategic partnerships, local manufacturing capabilities, and after-sales service play a vital role in market positioning. The Rainwater Harvesting Market is also influenced by environmental policies and sustainability goals, which shape procurement decisions in both public and private sectors. Growth potential remains high, especially in emerging economies facing acute water scarcity and infrastructure limitations.
Report Coverage
The research report offers an in-depth analysis based on Component, Applicqtion, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for rainwater harvesting systems will grow due to increasing global water scarcity and stressed municipal supply networks.
- Governments will expand regulatory support, making rainwater collection mandatory in new residential and commercial developments.
- Urban infrastructure projects will increasingly integrate smart rainwater harvesting systems with automated controls and real-time monitoring.
- Manufacturers will focus on modular, scalable systems to meet the needs of both large-scale and small-scale applications.
- Rural areas will adopt affordable and low-maintenance harvesting solutions supported by NGOs and development agencies.
- Industrial and commercial sectors will adopt rainwater systems to reduce utility costs and meet environmental compliance standards.
- Public awareness campaigns will help overcome knowledge gaps and boost adoption in underpenetrated regions.
- Technological innovations will enhance water quality management through advanced filtration and purification systems.
- Partnerships between governments and private players will drive infrastructure development and product accessibility.
- The market will witness increased activity from startups offering smart, IoT-enabled water management solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Water Scarcity and Stress on Conventional Resources
Increasing population, industrialization, and agricultural activities are straining traditional water supplies, making rainwater harvesting a vital decentralized solution in both urban and rural areas, especially in water-stressed regions.
Supportive Government Policies and Regulatory Mandates
Many governments are implementing regulations, tax incentives, and mandates requiring rainwater harvesting systems in new construction, directly driving adoption across residential, commercial, and industrial sectors.
Technological Advancements in System Efficiency
Innovations in storage, filtration, and automation are making rainwater harvesting systems more efficient, user-friendly, and cost-effective, encouraging broader adoption and integration with smart building management systems.
Expansion of Green Building and Sustainability Initiatives
The rise of eco-conscious construction and certifications like LEED and BREEAM are promoting the integration of rainwater harvesting systems in new developments, supporting sustainability goals and operational cost savings.
Rising Demand in Emerging Economies and Rural Areas
Emerging markets in Asia, Africa, and Latin America face acute water shortages and limited infrastructure, creating strong demand for affordable, decentralized rainwater harvesting solutions supported by public and NGO initiatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Rainwater Harvesting Market?
What are the key segments within the Rainwater Harvesting Market?
What are some challenges faced by the Rainwater Harvesting Market?
Who are the major players in the Rainwater Harvesting Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Residential
- 1.2.2 Non-residential (Commercial & Industrial)
- 1.2.3 Institutional
- 1.3 By Component
- 1.3.1 Storage Tanks
- 1.3.2 Filters and Purification Systems
- 1.3.3 Distribution Systems
- 1.4 By Application
- 1.4.1 Rooftop-based
- 1.4.2 Surface-based
- 1.4.3 Hybrid Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,081.47 million → 2032: USD 2,239.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rainwater Harvesting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rainwater Harvesting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rainwater Harvesting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rainwater Harvesting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rainwater Harvesting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rainwater Harvesting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rainwater Harvesting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rainwater Harvesting Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,081.47 million → 2032: USD 2,239.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rainwater Harvesting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Non-residential (Commercial & Industrial)
- 12.3.7.3 Institutional
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Storage Tanks
- 12.4.7.2 Filters and Purification Systems
- 12.4.7.3 Distribution Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Rooftop-based
- 12.5.7.2 Surface-based
- 12.5.7.3 Hybrid Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rainwater Harvesting End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Rainwater Harvesting Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Rainwater Harvesting Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Rainwater Harvesting Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kingspan Group Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Watts Water Technologies Inc.
- 18.4 Otto Graf GmbH
- 18.5 Barr Plastics Inc.
- 18.6 Stormsaver Ltd.
- 18.7 Ecozi Ltd.
- 18.8 RainHarvest Systems LLC
- 18.9 Water Harvesting Solutions Inc.
- 18.10 WISY AG
- 18.11 Heritage Water Tanks
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

