
Market Overview:
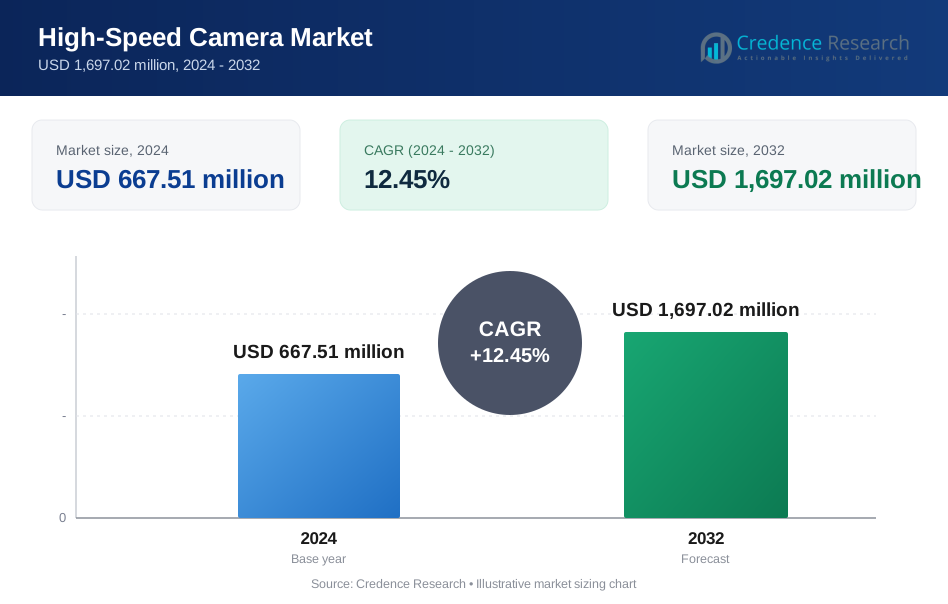
The High-Speed Camera Market size was valued at USD 450.00 million in 2018 to USD 667.51 million in 2024 and is anticipated to reach USD 1,697.02 million by 2032, at a CAGR of 12.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High-Speed Camera Market Size 2024 | USD 667.51 million |
| High-Speed Camera Market, CAGR | 12.45% |
| High-Speed Camera Market Size 2032 | USD 1,697.02 million |
Demand for high-speed cameras continues to rise due to their expanding role in automotive crash testing, defense analysis, industrial inspection, and research applications. Manufacturers and researchers rely on high-frame-rate imaging to detect motion patterns, improve process control, and reduce failure risks. Advanced imaging sensors, paired with AI-based processing, now enable real-time diagnostics in robotics and machine vision. Industries adopt these systems for fault analysis, process optimization, and predictive maintenance. Innovation in portable, high-resolution models has also broadened their use across field studies and academic labs.
North America leads the market due to strong investment in aerospace, defense, and automotive testing. Europe follows with a focus on precision manufacturing and sustainability-led R&D. Asia Pacific is emerging rapidly, driven by high electronics production and expanding academic research in China, Japan, and South Korea. India shows potential with growing demand from industrial automation and public R&D programs. Latin America, the Middle East, and Africa are at early stages of adoption, with steady growth expected as awareness, infrastructure, and localized support improve.

Market Insights:
- The High-Speed Camera Market expanded from USD 450.00 million in 2018 to USD 667.51 million in 2024 and is projected to reach USD 1,697.02 million by 2032, reflecting sustained demand growth at a CAGR of 12.45% driven by industrial, defense, and research adoption.
- North America leads with about 5% share in 2024 due to strong aerospace, defense testing, and automotive crash analysis infrastructure, followed by Asia Pacific at 27.4% supported by electronics manufacturing and R&D expansion, and Europe at 21.4% driven by precision engineering and automotive safety regulations.
- Asia Pacific represents the fastest-growing region with a 4% share, supported by rapid industrial automation, semiconductor manufacturing growth, and increasing investments in academic and defense research across China, Japan, and South Korea.
- By spectrum, Visible RGB dominates the segment mix with an estimated 52% share, supported by broad usage across industrial inspection, media production, and automotive testing where color clarity and resolution remain critical.
- X-Ray accounts for nearly 28% of the segment share due to rising non-destructive testing and medical diagnostics demand, while Infrared holds about 20%, driven by thermal analysis, defense surveillance, and advanced research applications.
Market Drivers
Rising Use of High-Speed Imaging in Automotive Safety and Crash Testing
The automotive sector drives demand for high-speed imaging in crash testing and component durability studies. OEMs use ultra-high-frame-rate cameras to capture impact sequences and deformation patterns. These insights improve airbag deployment timing and passenger safety design. Regulatory bodies enforce strict testing benchmarks, further supporting demand. The High-Speed Camera Market benefits from integration into vehicle R&D labs and simulation environments. It enables detailed analysis of failures and stress under controlled conditions. High-definition imaging helps validate computational models for safety. It also reduces physical prototyping costs for advanced crash scenarios.
Growing Demand from Aerospace and Defense Testing Facilities Worldwide
Aerospace and defense sectors require precise motion capture to study ballistic behavior, propulsion, and vibration tests. These industries use high-speed cameras in hypersonic trials, missile tracking, and aircraft systems validation. Camera systems withstand harsh testing conditions and offer detailed frame-by-frame analysis. The High-Speed Camera Market benefits from investments in space missions, tactical weapon systems, and drone development. It supports equipment reliability studies through high-fidelity motion tracking. Advanced imaging tools also help assess system performance during extreme G-force events. Global defense modernization programs sustain long-term procurement. Governments prioritize sensor-based evaluations over traditional test rigs.
- For instance, Vision Research’s Phantom TMX 7510 captures up to 76,000 fps at full 1280×800 resolution, using a backside-illuminated sensor optimized for high-speed, low-light environments. Its capabilities make it a standard tool in aerospace and defense testing for analyzing fast events such as shockwaves and flow separation.
Integration into Industrial Automation and Quality Control Processes
High-speed cameras are being adopted across manufacturing lines for process diagnostics and real-time defect detection. They enable precision analysis of high-speed conveyor, stamping, and assembly operations. Industries use them to monitor machinery for wear and avoid unplanned downtime. The High-Speed Camera Market gains traction in electronics, pharmaceuticals, and packaging industries. It helps identify causes of bottlenecks and improves equipment utilization. Optical sensors paired with AI deliver faster pattern recognition. Manufacturers benefit from sharper visual documentation during audits and troubleshooting. These systems enhance overall product quality and yield.
- For instance, NAC’s MEMRECAM ACS-1 M60 captures high-speed footage at 60,000 fps at 1280 × 800 resolution and up to 1 million fps at reduced resolution. Its high light sensitivity and support for high-magnification imaging make it suitable for precision diagnostics in industrial and research settings.
R&D Adoption Across Biomechanics, Fluid Dynamics, and Scientific Research
Academic and commercial labs increasingly rely on high-speed imaging to explore biomechanics, combustion, and nanomaterial responses. High-resolution frame capture allows researchers to observe fast phenomena previously invisible to the human eye. The High-Speed Camera Market finds demand in physics, chemistry, and biological sciences. It enables clear visualizations in tissue strain studies, bubble dynamics, and explosion tests. Fluid motion studies benefit from non-contact diagnostics across transparent flow setups. Researchers integrate advanced cameras with laser illumination and motion tracking tools. Faster frame rates improve the accuracy of velocity and force measurements. Demand from universities, defense labs, and private institutes continues to grow.
Market Trends
Adoption of AI and Edge Processing Capabilities for Real-Time Analysis
High-speed cameras are evolving beyond data capture, integrating AI and edge computing features. These systems support real-time decision-making in industrial and research environments. The High-Speed Camera Market reflects a shift toward intelligent imaging platforms. It now enables real-time frame selection, pattern recognition, and object tracking. AI models run directly on the camera, reducing post-processing time. This advancement supports machine vision applications with fast feedback loops. Manufacturers use these tools for adaptive inspection and robotic guidance. Edge capabilities minimize bandwidth requirements and improve response accuracy.
- For instance, Vision Research’s Phantom VEO 710 supports ultra‑high‑speed recording at up to 680,000 fps at reduced resolution, enabling detailed capture of extremely fast events. The camera includes programmable I/O and auto‑trigger features that support precise event capture in industrial and scientific testing environments.
Emergence of Compact, Lightweight Cameras with Enhanced Portability
The market is seeing strong traction in lightweight, portable camera designs that maintain high resolution. These units fit into space-limited environments such as medical labs, drones, and embedded testing setups. The High-Speed Camera Market benefits from this shift in size-performance balance. It expands applications across aerospace interiors, flexible inspection arms, and vehicle interiors. Engineers deploy compact units in harsh field conditions without compromising data quality. Miniaturized optics and chipsets support high-speed imaging in wearables and robotics. Portability also improves installation efficiency in remote test environments. Compact cameras support dynamic motion studies with minimal system weight.
Use of Hyperspectral and Infrared Imaging for Advanced Diagnostics
Advanced imaging modes such as infrared and hyperspectral capture are gaining traction. These techniques enable new use cases across scientific research and industrial inspection. The High-Speed Camera Market expands into thermography, combustion diagnostics, and semiconductor analysis. Cameras now integrate multispectral sensors to capture both motion and material properties. These systems monitor thermal stress, chemical changes, and emissivity variations. In aerospace, they help assess material behavior under extreme heat loads. In semiconductors, they detect micro-defects in wafers and chips. Dual-mode cameras support both visible and IR imaging in a single device.
Cloud Integration and Remote Access for High-Speed Data Workflows
Cloud-enabled workflows are transforming how high-speed footage is stored, accessed, and analyzed. Users now upload captured data to cloud platforms for collaborative processing and review. The High-Speed Camera Market supports this shift by embedding network-ready features in modern units. It enables researchers and engineers to access test results across sites. Remote configuration and diagnostics reduce onsite setup time. Cloud integration supports scalable data storage and long-term archiving. It also streamlines report generation and analytics in regulated industries. Users apply cloud tools for image stitching, frame extraction, and annotation tasks.
- For instance, Vision Research's Phantom T4040 includes standard 10Gb Ethernet for direct data transfer to cloud platforms, enabling remote access across sites with up to 256 GB onboard memory buffering.
Market Challenges Analysis
High Equipment Cost and Maintenance Requirements Limit Widespread Adoption
High-speed cameras remain expensive due to advanced optics, precision sensors, and thermal control systems. Their pricing often exceeds the budgets of small labs or independent researchers. The High-Speed Camera Market faces slow adoption in price-sensitive industries. Maintenance costs also remain high due to calibration, sensor drift, and component wear. Users must regularly upgrade storage interfaces and cooling modules. Complex setup procedures demand trained personnel, increasing operational overhead. Technical support is essential, especially for synchronized multi-camera setups. Affordability limits repeat purchases across emerging markets and small enterprises.
Large Data Volume and Complex Storage Infrastructure Constraints
High-speed imaging generates large data sets within seconds, requiring advanced storage solutions. Each frame sequence can occupy several gigabytes, stressing storage networks and servers. The High-Speed Camera Market faces technical limitations in real-time processing and archival. Legacy infrastructure struggles with bandwidth and latency, leading to dropped frames or delays. Compression algorithms may reduce quality and compromise accuracy in analysis. Transferring high-resolution files between departments or sites also causes bottlenecks. Without dedicated pipelines and storage clusters, efficient data handling becomes a challenge. These issues impact deployment in fast-paced industrial setups.

Market Opportunities
Growth in Sports Technology and Motion Analytics for Training Enhancement
High-speed cameras are finding new applications in sports science for biomechanical analysis and motion optimization. Coaches and analysts use them to study joint movement, posture, and timing during peak performance. The High-Speed Camera Market benefits from partnerships with sports tech firms and universities. It supports athlete-specific training programs with precise motion tracking. These systems enhance recovery analysis and injury prevention efforts. Wearable integration expands performance monitoring in real-time. Demand continues from football, athletics, and motorsports sectors.
Expansion in Life Sciences, Surgical Robotics, and Microfluidics Research
Life sciences and healthcare offer strong growth potential through applications in microscopy and surgical robotics. The High-Speed Camera Market supports dynamic cellular imaging and drug delivery system development. Microfluidics labs rely on high-speed visualization to study flow behavior and droplet formation. Cameras enable non-invasive diagnostics and validation of robotic surgery tools. Research institutions adopt high-frame imaging in embryology and neuroscience. It improves understanding of biological responses under mechanical or chemical stimuli.
Market Segmentation Analysis:
By component, image sensors lead the High-Speed Camera Market due to their role in capturing high-resolution frames at extreme speeds. Processors follow, supporting real-time data handling and playback. Lenses play a vital role in maintaining clarity and sharpness, while memory is crucial for storing rapid sequences without frame loss. Fans and cooling systems help stabilize performance during high-intensity operations. The others category includes accessories and custom modules for niche use cases.
By application, automotive and transportation dominate usage, driven by crash testing and motion analysis. Aerospace and defense rely on high-speed systems for missile tracking and system validation. The consumer electronics segment benefits from demand in product R&D and quality inspection. Healthcare uses cameras in surgical training and biomechanics. Media and entertainment apply these tools in slow-motion filming and visual effects. The others segment includes industrial inspection and academic research.
- For instance, iX Cameras’ i-SPEED 7 series delivers over 1 million fps at reduced resolution, with elite models like the i-SPEED 727 reaching up to 2.45 million fps. It is widely used in materials testing, fluid dynamics, and high-speed manufacturing diagnostics, including Digital Image Correlation and crack propagation studies.
By spectrum, visible RGB cameras account for the largest share due to broad industrial use. Infrared cameras support thermal imaging and defense applications. X-ray spectrum cameras are gaining traction in non-destructive testing and medical diagnostics.
By frame rate, the 1000–10000 FPS range leads due to its balance of performance and cost. 250–1000 FPS serves entry-level industrial needs. Higher segments like 10000–30000 FPS and 30000–50000 FPS address research and crash test labs. The above 50000 FPS range caters to aerospace and ultra-fast motion studies where precision is critical. The High-Speed Camera Market continues to expand across all these performance tiers.
- For instance, Shimadzu’s HyperVision HPV-X3 captures up to 20 million frames per second using its FTCMOS3 sensor, enabling researchers to visualize ultra-fast phenomena such as shock waves and material fracture dynamics in advanced scientific studies.
Segmentation:
By Component
- Image Sensors
- Processors
- Lens
- Memory
- Fans and Cooling
- Others
By Application
- Automotive and Transportation
- Consumer Electronics
- Aerospace and Defense
- Healthcare
- Media and Entertainment
- Others
By Spectrum
- Infrared
- X-Ray
- Visible RGB
By Frame Rate
- 250 – 1000 FPS
- 1000 – 10000 FPS
- 10000 – 30000 FPS
- 30000 – 50000 FPS
- Above 50000 FPS
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Regional Analysis:
North America
The North America High-Speed Camera Market size was valued at USD 165.92 million in 2018 to USD 243.17 million in 2024 and is anticipated to reach USD 617.38 million by 2032, at a CAGR of 12.4% during the forecast period. North America accounts for the largest share, capturing approximately 36.5% of the global market in 2024. It benefits from mature adoption across automotive crash testing, aerospace validation, and industrial robotics. Defense contractors and research institutions invest heavily in ultra-high-speed imaging for systems analysis. The U.S. drives most of the demand due to early technological adoption, advanced infrastructure, and strong R&D funding. Canada supports growth through academic research and industrial testing in sectors like mining and energy. Cloud-enabled workflows and AI-driven analytics tools are widely integrated. Strong vendor presence, including global market leaders, improves accessibility and after-sales support.
Europe
The Europe High-Speed Camera Market size was valued at USD 101.07 million in 2018 to USD 143.10 million in 2024 and is anticipated to reach USD 340.00 million by 2032, at a CAGR of 11.5% during the forecast period. Europe holds a 21.4% market share in 2024, driven by adoption in automotive, aerospace, and precision manufacturing. Germany leads the region with applications in vehicle safety testing and industrial automation. The UK and France invest in defense and research imaging systems. EU-backed sustainability projects also use high-speed cameras for fluid dynamics and material testing. Industry 4.0 initiatives promote real-time quality monitoring across production lines. Universities and research institutes adopt compact systems for biomechanics, optics, and combustion studies. Vendors across Germany and France offer customized, region-specific solutions. Advanced image processing and machine learning integration strengthen Europe’s position in R&D applications.
Asia Pacific
The Asia Pacific High-Speed Camera Market size was valued at USD 118.44 million in 2018 to USD 182.93 million in 2024 and is anticipated to reach USD 509.95 million by 2032, at a CAGR of 13.7% during the forecast period. The region accounts for around 27.4% of the global market in 2024, with China, Japan, and South Korea leading adoption. Rapid industrialization, strong electronics manufacturing, and automotive R&D drive demand. China supports market growth through state-backed defense and aerospace programs. Japan leverages high-speed imaging in robotics and microelectronics development. South Korea applies advanced systems in semiconductor fabs and academic labs. India emerges as a promising market, supported by growing automation and Make-in-India initiatives. Universities and research centers in the region are key adopters of portable, mid-range camera systems. Vendors are expanding their footprint through localized support and cost-effective models. Infrastructure upgrades improve real-time data handling and storage.
Latin America
The Latin America High-Speed Camera Market size was valued at USD 35.10 million in 2018 to USD 51.66 million in 2024 and is anticipated to reach USD 123.66 million by 2032, at a CAGR of 11.6% during the forecast period. Latin America represents a 7.7% market share in 2024. Brazil leads regional adoption, especially in automotive, mining, and industrial inspection. Mexico contributes through electronics and consumer goods testing. Growth remains steady as local universities and labs integrate camera systems for material and motion studies. Import-dependent procurement and limited vendor presence pose pricing and service challenges. Rising demand in food processing and packaging inspection supports incremental uptake. Public sector investments in defense and research facilities improve adoption. OEMs and integrators explore partnerships with regional distributors to improve reach. Technological awareness continues to rise across mid-sized enterprises.
Middle East
The Middle East High-Speed Camera Market size was valued at USD 19.35 million in 2018 to USD 27.10 million in 2024 and is anticipated to reach USD 62.97 million by 2032, at a CAGR of 11.2% during the forecast period. It holds a 4.1% share of the global market in 2024. The region’s demand is concentrated in aerospace, oil and gas, and defense sectors. GCC countries invest in high-speed imaging to support surveillance, weapon testing, and facility monitoring. Research labs in the UAE and Saudi Arabia deploy camera systems for scientific and fluid dynamics research. Infrastructure development drives adoption for structural testing and materials diagnostics. Limited local manufacturing pushes reliance on imported systems. Vendors focus on modular, rugged models suited for extreme environments. Government-backed innovation programs provide long-term growth potential. High-performance imaging solutions align with energy sector modernization and process control.
Africa
The Africa High-Speed Camera Market size was valued at USD 10.13 million in 2018 to USD 19.56 million in 2024 and is anticipated to reach USD 43.05 million by 2032, at a CAGR of 10.0% during the forecast period. Africa holds a 2.9% share of the global market in 2024. South Africa leads adoption, driven by aerospace testing, mining operations, and university-based research. Egypt and Nigeria are emerging contributors, using high-speed imaging in materials testing and diagnostics. Procurement is often tied to academic grants and international collaborations. Limited technical support and high import costs hinder broader deployment. Training and maintenance capacity gaps delay advanced integration. Public labs prioritize high-speed systems for education and prototype evaluation. Regional demand is expected to grow with expansion in infrastructure, utilities, and manufacturing sectors. Vendors explore capacity-building partnerships to strengthen long-term presence.
Key Player Analysis:
- Photron Ltd.
- Vision Research Inc. (Phantom)
- NAC Image Technology
- Mikrotron GmbH
- Optronis GmbH
- Fastec Imaging
- Excelitas Technologies Corp
- Olympus Corporation
- Motion Capture Technologies
- DEL Imaging Systems LLC
Competitive Analysis:
The High-Speed Camera Market features a competitive landscape shaped by technology leadership, product performance, and application depth. Key players compete through frame rate capability, sensor sensitivity, and system reliability. Established vendors focus on advanced image sensors, high-bandwidth processors, and efficient thermal design. It favors companies with strong R&D pipelines and close ties to automotive, aerospace, and defense customers. Product portfolios range from compact portable units to ultra-high-speed laboratory systems. Vendors pursue differentiation through software analytics, AI-based image processing, and real-time data handling. Strategic partnerships with research institutions strengthen product validation and adoption. Regional expansion remains a priority, with localized support and customization gaining importance. Pricing strategy balances premium performance with mid-range offerings for industrial users. Competitive intensity remains high due to rapid technology cycles and rising demand across scientific and industrial domains.
Recent Developments:
- In February 2025, Shimadzu launched the HyperVision HPV-X3 high-speed video camera, which doubles the speed of its predecessor to 20 million fps and triples the resolution. Featuring an FTCMOS3 sensor and frame synchronization capabilities, this camera enables unprecedented imaging of ultra-fast, microscopic physical and industrial phenomena.
- In February 2025, Vision Research launched the Phantom T2110 high-speed camera, capable of capturing up to 483,300 fps. Equipped with a 12-bit BSI sensor and advanced synchronization features, it provides exceptional low-light performance and ultra-fast imaging suited for scientific, industrial, and cinematic applications.
- In September 2024, RDI Technologies launched three high-speed cameras: the FASTEC HS5i, HS7i, and an upgraded Iris MX with integrated PC controllers. These models enhance data capture efficiency, portability, and high-speed performance, particularly boosting Motion Amplification for field and industrial vibration analysis.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application, Spectrum, Frame Rate and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Adoption will expand across advanced manufacturing as factories demand faster visual diagnostics and defect tracking tools.
- Research institutions will increase usage to study fast physical, chemical, and biological phenomena with higher accuracy.
- Automotive testing will continue to rely on high-speed imaging for safety validation and materials analysis.
- Aerospace and defense programs will strengthen demand for ultra-high-frame-rate systems in propulsion and impact testing.
- Integration of AI-based analytics will improve real-time decision support and reduce post-test processing time.
- Compact and portable camera designs will unlock new use cases in field testing and mobile laboratories.
- Healthcare applications will grow through surgical motion analysis, biomechanics, and medical device testing.
- Demand for infrared and multispectral imaging will rise in thermal diagnostics and non-destructive evaluation.
- Emerging economies will show faster adoption as industrial automation and academic research expand.
- Vendor competition will intensify around software ecosystems, service support, and application-specific customization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Use of High-Speed Imaging in Automotive Safety and Crash Testing
Automotive manufacturers and regulatory bodies increasingly rely on high-speed cameras to capture detailed crash sequences and component durability, improving vehicle safety and reducing prototyping costs. This drives adoption in R&D labs and crash simulation environments.
Growing Demand from Aerospace and Defense Testing Facilities
Aerospace and defense sectors require ultra-high-speed imaging for missile tracking, propulsion analysis, and system validation under extreme conditions. Investments in space missions, tactical weapon systems, and modernization programs sustain long-term demand for advanced camera systems.
Integration into Industrial Automation and Quality Control
Manufacturing industries are adopting high-speed cameras for real-time defect detection, process diagnostics, and predictive maintenance. These systems enhance product quality, reduce downtime, and support Industry 4.0 initiatives through AI-enabled visual inspection.
Expansion of R&D in Biomechanics, Fluid Dynamics, and Scientific Research
Academic and commercial research labs use high-speed cameras to study fast physical, chemical, and biological phenomena, enabling breakthroughs in biomechanics, combustion, and nanomaterial analysis. This broadens the market across universities and research institutes.
Adoption of AI and Edge Processing for Real-Time Analysis
The integration of AI and edge computing in high-speed cameras allows for real-time pattern recognition, object tracking, and adaptive inspection, reducing post-processing time and enabling smarter machine vision applications in industrial and research settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for High-Speed Camera Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the High-Speed Camera Market projected to grow between 2024 and 2032?
Which High-Speed Camera Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the High-Speed Camera Market?
Who are the leading companies in the High-Speed Camera Market?
Which region commanded the largest share of the High-Speed Camera Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Spectrum
- 1.2.1 Infrared
- 1.2.2 X-Ray
- 1.2.3 Visible RGB
- 1.3 By Component
- 1.3.1 Image Sensors
- 1.3.2 Processors
- 1.3.3 Lens
- 1.3.4 Memory
- 1.3.5 Fans and Cooling
- 1.3.6 Others
- 1.4 By Frame Rate
- 1.4.1 250 – 1000 FPS
- 1.4.2 1000 – 10000 FPS
- 1.4.3 10000 – 30000 FPS
- 1.4.4 30000 – 50000 FPS
- 1.4.5 Above 50000 FPS
- 1.5 By Application
- 1.5.1 Automotive and Transportation
- 1.5.2 Consumer Electronics
- 1.5.3 Aerospace and Defense
- 1.5.4 Healthcare
- 1.5.5 Media and Entertainment
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 667.51 million → 2032: USD 1,697.02 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global High-Speed Camera Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global High-Speed Camera Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global High-Speed Camera Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global High-Speed Camera Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global High-Speed Camera Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global High-Speed Camera Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global High-Speed Camera Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global High-Speed Camera Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 667.51 million → 2032: USD 1,697.02 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global High-Speed Camera Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Spectrum - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Infrared
- 12.3.7.2 X-Ray
- 12.3.7.3 Visible RGB
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Image Sensors
- 12.4.7.2 Processors
- 12.4.7.3 Lens
- 12.4.7.4 Memory
- 12.4.7.5 Fans and Cooling
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Frame Rate - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 250 – 1000 FPS
- 12.5.7.2 1000 – 10000 FPS
- 12.5.7.3 10000 – 30000 FPS
- 12.5.7.4 30000 – 50000 FPS
- 12.5.7.5 Above 50000 FPS
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Automotive and Transportation
- 12.6.7.2 Consumer Electronics
- 12.6.7.3 Aerospace and Defense
- 12.6.7.4 Healthcare
- 12.6.7.5 Media and Entertainment
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global High-Speed Camera End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global High-Speed Camera Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global High-Speed Camera Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global High-Speed Camera Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Photron Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vision Research Inc. (Phantom)
- 18.4 NAC Image Technology
- 18.5 Mikrotron GmbH
- 18.6 Optronis GmbH
- 18.7 Fastec Imaging
- 18.8 Excelitas Technologies Corp
- 18.9 Olympus Corporation
- 18.10 Motion Capture Technologies
- 18.11 DEL Imaging Systems LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

