
Market Overview
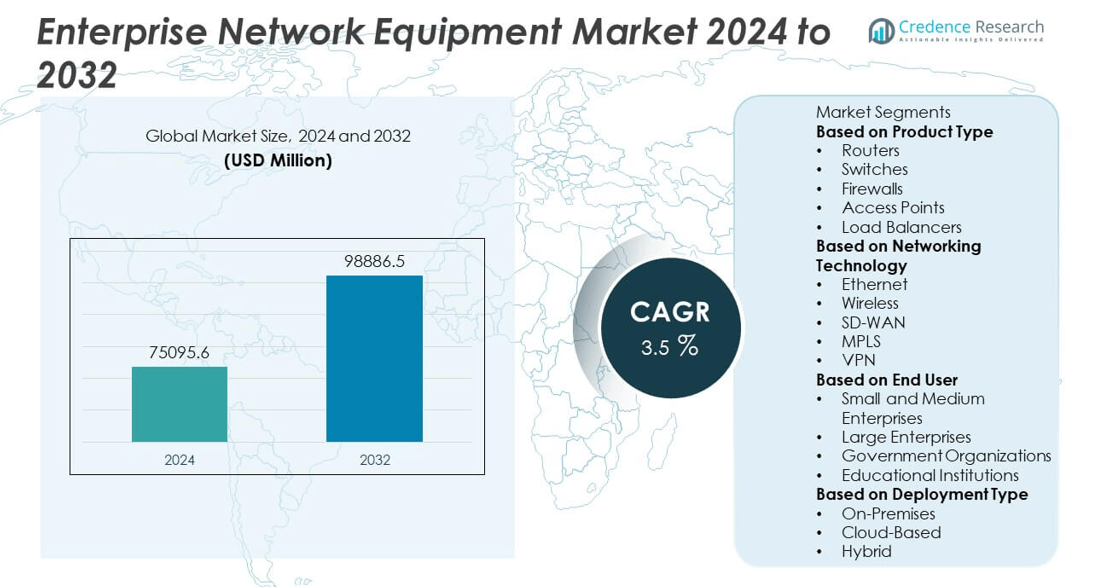
Enterprise Network Equipment Market was valued at USD 75,095.6 million in 2024 and is projected to reach USD 98,886.5 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Enterprise Network Equipment Market Size 2024 | USD 75,095.6 million |
| Enterprise Network Equipment Market, CAGR | 3.5% |
| Enterprise Network Equipment Market Size 2032 | USD 98,886.5 million |
The Enterprise Network Equipment Market grows steadily, driven by the rising need for high-speed, reliable connectivity, expanding cloud adoption, and increasing IoT deployments across industries. Enterprises invest in advanced routers, switches, and security appliances to enhance performance, scalability, and threat protection. It benefits from trends such as the integration of AI and machine learning for network optimization.
The Enterprise Network Equipment Market spans key regions, including North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, each demonstrating distinct growth drivers. North America leads in technology adoption, supported by strong enterprise IT investments and advanced infrastructure. Europe focuses on secure, compliant networking solutions, driven by strict data protection regulations. Asia-Pacific experiences rapid expansion fueled by large-scale 5G rollouts, IoT adoption, and industrial automation. Latin America and the Middle East & Africa show potential through digital transformation initiatives and infrastructure upgrades. Prominent players shaping the market landscape include Cisco Systems, Juniper Networks, Hewlett Packard Enterprise, and Arista Networks. These companies compete by offering innovative, scalable, and secure networking solutions tailored to evolving enterprise needs, while investing in AI-driven management, virtualization capabilities.
Market Insights
- The Enterprise Network Equipment Market was valued at USD 75,095.6 million in 2024 and is projected to reach USD 98,886.5 million by 2032, at a CAGR of 3.5% during the forecast period.
- The market growth is supported by rising demand for high-speed, reliable connectivity, expanding cloud adoption, and the increasing integration of IoT devices across multiple industries.
- Key trends include the integration of AI and machine learning for automated network optimization, the transition toward software-defined networking and virtualization, and the expansion of edge computing to enable low-latency applications.
- Competition is intense, with major players such as Cisco Systems, Hewlett Packard Enterprise, Arista Networks, and Juniper Networks focusing on innovation, scalability, and security to strengthen market positions.
- High capital investment requirements, rapid technological changes, and complex integration processes act as restraints, especially for small and medium-sized enterprises.
- North America dominates due to advanced infrastructure and early adoption of emerging technologies, while Europe focuses on secure and compliant networking, and Asia-Pacific shows the fastest growth driven by 5G deployments and industrial automation.
- Vendors align strategies with sustainability goals by offering energy-efficient equipment and smart power management features, creating opportunities in environmentally conscious markets and supporting long-term cost savings for enterprises.
Market Drivers
Rising Demand for High-Speed and Reliable Connectivity Across Enterprises
The Enterprise Network Equipment Market experiences strong growth due to the need for high-speed, low-latency connectivity in modern enterprises. Organizations depend on advanced networking hardware to support data-intensive applications, video conferencing, and cloud-based platforms. It benefits from the shift toward gigabit and multi-gigabit networks to handle increasing traffic volumes. Enterprises seek equipment with improved bandwidth management and quality of service capabilities to ensure seamless operations. Network hardware that delivers stability and scalability gains preference in competitive markets. Vendors invest in innovation to meet the performance expectations of various industries.
- For instance, Juniper Networks’ T1600 core router delivers 800 Gb/s full-duplex throughput and supports 1.6 Tbit/s half-duplex throughput, enabling robust, high-capacity network backbones.
Expanding Adoption of Cloud Services and Hybrid IT Architectures
Cloud migration drives significant demand for advanced network infrastructure in the Enterprise Network Equipment Market. Enterprises require solutions that integrate on-premise systems with public and private cloud environments. It increases the demand for switches, routers, and security appliances capable of handling hybrid workloads. Secure and efficient data transfer between cloud resources and enterprise networks remains a priority. The shift to hybrid IT models requires adaptable network designs that maintain performance across diverse environments. Providers offer products with advanced virtualization support and cloud management features to address these needs.
- For instance, Juniper’s ACX7100 and ACX7509 routers include weighted fair queuing (WFQ), priority queuing, and traffic-shaping and policing functions to manage hybrid traffic classes effectively.
Growing Internet of Things (IoT) Deployments Across Industries
The Enterprise Network Equipment Market gains momentum from widespread IoT adoption in sectors such as manufacturing, healthcare, and logistics. It creates demand for robust network infrastructure capable of supporting thousands of connected devices. Enterprises prioritize equipment that ensures secure device onboarding, low-latency communication, and reliable data flow. IoT-specific network management features, such as traffic segmentation and edge computing support, gain traction. The increasing complexity of IoT ecosystems drives the need for high-capacity switches and wireless solutions. Vendors respond with products designed for industrial-grade reliability and scalability.
Rising Focus on Network Security and Threat Mitigation
Security concerns remain a central driver for the Enterprise Network Equipment Market. It pushes enterprises to adopt equipment with integrated threat detection, encryption, and access control mechanisms. Network hardware that offers real-time monitoring and automated threat response gains higher acceptance. Compliance with data protection regulations reinforces the demand for secure network designs. Enterprises require solutions that defend against sophisticated cyberattacks targeting both core and edge infrastructure. Vendors enhance their offerings with AI-driven analytics and zero-trust architecture support to address evolving threats.
Market Trends
Integration of Artificial Intelligence and Machine Learning for Network Optimization
The Enterprise Network Equipment Market witnesses a growing trend toward embedding AI and ML capabilities into network infrastructure. Enterprises deploy intelligent systems that enable automated traffic management, predictive maintenance, and performance optimization. It helps reduce downtime by identifying potential faults before they impact operations. AI-driven analytics enhance decision-making by providing real-time insights into network usage patterns. Vendors focus on developing self-healing networks that adapt to changing conditions without manual intervention. The adoption of AI-enabled equipment increases operational efficiency and reduces the total cost of ownership for enterprises.
- For instance, Juniper’s Mist AIOps platform has eliminated 90 percent of wireless network trouble tickets and has provisioned over 4,000 access points in a single deployment day.
Shift Toward Software-Defined Networking and Network Function Virtualization
A clear trend in the Enterprise Network Equipment Market is the transition from hardware-centric designs to software-driven architectures. It enables enterprises to manage networks with greater flexibility, scalability, and control. SDN and NFV allow centralized configuration, reducing reliance on proprietary hardware and enabling faster deployment of new services. This shift supports cost-effective scaling to meet dynamic workload demands. Vendors offer solutions that integrate with existing systems while supporting virtualization standards. Enterprises benefit from reduced complexity and improved agility in network operations.
- For instance, Cisco DNA Center’s Plug-and-Play workflows support zero-touch provisioning across large-scale deployments, while Juniper’s Mist Wired Assurance automates switch onboarding within minutes and surfaces per-port metrics for precise policy enforcement.
Expansion of Edge Computing Infrastructure to Support Emerging Applications
Edge computing deployment continues to influence the Enterprise Network Equipment Market significantly. It drives demand for equipment that processes data closer to its source, reducing latency and improving application performance. Enterprises in sectors like manufacturing, retail, and healthcare invest in edge-ready switches, routers, and security appliances. This trend supports use cases such as real-time analytics, AR/VR applications, and autonomous systems. Vendors design compact, energy-efficient equipment to meet the needs of distributed edge environments. The growth of 5G networks further accelerates the integration of edge capabilities into enterprise infrastructure.
Increased Focus on Sustainable and Energy-Efficient Network Solutions
Sustainability goals shape purchasing decisions in the Enterprise Network Equipment Market. It encourages enterprises to select products with lower energy consumption, recyclable materials, and efficient cooling mechanisms. Green networking initiatives align with regulatory requirements and corporate responsibility objectives. Vendors invest in developing energy-optimized switches and routers that reduce operational costs. The adoption of smart power management features becomes a standard expectation. Energy efficiency not only addresses environmental concerns but also enhances the long-term economic value of network investments.
Market Challenges Analysis
High Capital Investment Requirements and Cost Pressures on Enterprises
The Enterprise Network Equipment Market faces the challenge of significant upfront costs for advanced networking infrastructure. It requires enterprises to allocate substantial budgets for high-performance switches, routers, security appliances, and software platforms. Smaller organizations often delay upgrades due to limited capital, which slows adoption rates. Rapid technology evolution shortens product life cycles, forcing frequent reinvestment. Maintenance and training expenses add to the overall financial burden. Vendors must balance innovation with affordability to retain competitiveness in price-sensitive segments.
Complex Integration and Security Risks in Evolving Network Environments
Integrating new network equipment into existing infrastructure remains a persistent challenge for the Enterprise Network Equipment Market. It often involves compatibility issues, lengthy deployment timelines, and operational disruptions. The growing complexity of hybrid and multi-cloud architectures increases the risk of configuration errors. Cybersecurity threats intensify as networks expand to accommodate IoT devices, remote workforces, and edge computing nodes. Enterprises require robust security features without compromising performance, yet implementing these measures demands specialized expertise. Vendors need to provide flexible, interoperable solutions that address integration hurdles while ensuring advanced threat protection.
Market Opportunities
Rising Adoption of 5G and Advanced Wireless Technologies
The Enterprise Network Equipment Market presents strong opportunities through the expansion of 5G infrastructure and next-generation wireless networks. It enables enterprises to deploy high-speed, low-latency connectivity solutions for mission-critical applications. Industries such as manufacturing, transportation, and healthcare can leverage 5G-enabled equipment to enhance automation, remote operations, and real-time data analytics. Vendors have the opportunity to develop specialized switches, routers, and access points optimized for 5G environments. The growth of private 5G networks opens new revenue streams in enterprise-specific deployments. Integration of advanced wireless technologies into core and edge infrastructure creates potential for long-term contracts and recurring service models.
Growing Demand for Cloud-Managed and AI-Driven Networking Solutions
Cloud-managed platforms create significant growth prospects for the Enterprise Network Equipment Market. It supports enterprises in simplifying network management, improving scalability, and enabling centralized control. AI-driven analytics embedded in equipment provide predictive insights, automated troubleshooting, and optimized resource allocation. Enterprises increasingly seek solutions that combine security, performance, and agility in a single platform. Vendors offering cloud-native and AI-enabled products can cater to the evolving needs of hybrid work environments. The ability to deliver subscription-based models and managed services further expands market penetration opportunities.
Market Segmentation Analysis:
By Product Type
The Enterprise Network Equipment Market segments by product type into routers, switches, wireless access points, network security appliances, and network management software. Routers and switches hold a strong position due to their critical role in managing data flow and enabling connectivity across enterprise environments. Wireless access points gain increasing adoption with the expansion of mobile devices and remote workforces. Network security appliances see rising demand due to heightened cyber threats and regulatory compliance requirements. Network management software grows steadily as enterprises seek centralized monitoring, configuration control, and performance optimization. It creates opportunities for vendors offering integrated hardware and software solutions that improve operational efficiency.
- For instance, Juniper’s T1600 core router achieves 1.6 Tbit/s capacity (800 Gbit/s full-duplex) with forwarding of 1.92 billion packets per second, enabling high-performance backbone networks.
By Networking Technology
The Enterprise Network Equipment Market divides by networking technology into wired and wireless solutions. Wired networking retains dominance in environments where stability, security, and high throughput are critical, such as data centers and large corporate offices. Wireless networking registers faster growth, driven by the need for flexibility, mobility, and ease of deployment. It benefits from advancements in Wi-Fi 6, Wi-Fi 6E, and upcoming Wi-Fi 7 technologies, which offer higher speeds and lower latency. Enterprises adopt hybrid networking models that combine the reliability of wired systems with the convenience of wireless connectivity. Vendors focus on interoperability between these technologies to meet diverse operational requirements.
- For instance, Aruba’s 550 Series Wi-Fi 6 access points handle up to 1.5 Gbps wireless throughput and support 256 clients per radio, enabling high-density deployment.
By End-User
The Enterprise Network Equipment Market categorizes end-users into IT and telecom, banking and financial services (BFSI), healthcare, manufacturing, government, retail, and others. IT and telecom lead the segment due to continuous infrastructure upgrades and high bandwidth requirements. BFSI prioritizes secure, low-latency networks to support digital transactions and regulatory compliance. Healthcare invests in reliable connectivity to enable telemedicine, electronic health records, and IoT-based patient monitoring. Manufacturing adopts advanced networking to support automation, robotics, and smart factory initiatives. Government agencies focus on secure communication networks for public services and defense applications. Retail leverages network infrastructure for omnichannel operations and real-time inventory management. It offers growth opportunities across sectors seeking to modernize infrastructure and enhance operational resilience.
Segments:
Based on Product Type
- Routers
- Switches
- Firewalls
- Access Points
- Load Balancers
Based on Networking Technology
- Ethernet
- Wireless
- SD-WAN
- MPLS
- VPN
Based on End User
- Small and Medium Enterprises
- Large Enterprises
- Government Organizations
- Educational Institutions
Based on Deployment Type
- On-Premises
- Cloud-Based
- Hybrid
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest market share in the Enterprise Network Equipment Market, accounting for approximately 38% of global revenue in 2024. Strong technological infrastructure, high penetration of advanced networking solutions, and early adoption of innovations such as AI-driven network management support the region’s leadership. The United States dominates within the region due to its concentration of large enterprises, data centers, and cloud service providers. It benefits from ongoing investments in 5G infrastructure, cybersecurity solutions, and edge computing deployments. Canada contributes to growth with expanding IT services and government initiatives promoting digital transformation. Vendors in North America focus on developing high-performance, secure, and scalable networking solutions to address enterprise demands for hybrid work and IoT integration.
Europe
Europe captures around 27% of the Enterprise Network Equipment Market, supported by mature IT infrastructure and strong demand for secure networking in regulated industries such as BFSI and healthcare. Germany, the United Kingdom, and France lead adoption, driven by industrial automation, smart manufacturing, and cloud migration. It gains momentum from EU-wide digital transformation initiatives and investments in 5G and fiber-optic networks. Enterprises in Europe place high importance on compliance with GDPR and other data protection regulations, which fuels demand for integrated security features in networking equipment. The region also sees rising adoption of sustainable and energy-efficient network solutions aligned with environmental regulations. Vendors target European enterprises with products that balance performance, compliance, and environmental responsibility.
Asia-Pacific
Asia-Pacific accounts for approximately 24% of the Enterprise Network Equipment Market and exhibits the fastest growth rate among all regions. Rapid economic development, expanding digital infrastructure, and increasing enterprise IT budgets drive adoption in countries such as China, Japan, India, and South Korea. It benefits from large-scale 5G rollouts, widespread IoT deployments, and strong demand for cloud computing services. The manufacturing sector in the region accelerates investment in industrial networking for automation and smart factory projects. Governments in countries like India and China support initiatives for digital transformation and cybersecurity resilience. Vendors in Asia-Pacific focus on delivering cost-effective yet advanced networking solutions tailored to diverse market needs, from large-scale enterprises to small and medium-sized businesses.
Latin America
Latin America holds about 6% of the Enterprise Network Equipment Market, with growth primarily driven by Brazil, Mexico, and Argentina. The region experiences rising adoption of cloud services, e-commerce platforms, and mobile connectivity solutions. It faces challenges such as uneven infrastructure development and budget constraints among enterprises. However, ongoing investments in data centers and fiber-optic networks create opportunities for vendors. Enterprises in sectors like banking, retail, and telecommunications increasingly seek reliable and secure networking equipment to support digital services. Vendors focusing on competitive pricing and localized support gain an advantage in this cost-sensitive market.
Middle East & Africa
The Middle East & Africa region represents roughly 5% of the Enterprise Network Equipment Market, supported by growing investments in smart city projects, digital government services, and modernized enterprise infrastructure. The United Arab Emirates, Saudi Arabia, and South Africa lead adoption with initiatives in 5G, cloud computing, and IoT integration. It benefits from a strong push toward diversifying economies and developing technology hubs. Limited infrastructure in some parts of the region presents challenges, but the demand for secure and scalable networks is rising. Vendors targeting this region prioritize solutions that combine advanced performance with resilience in challenging environments.
Key Player Analysis
- Dell Technologies
- MikroTik
- Nokia
- Arista Networks
- ZTE Corporation
- Juniper Networks
- Extreme Networks
- TP-Link
- Cisco Systems
- Hewlett Packard Enterprise
Competitive Analysis
The competitive landscape of the Enterprise Network Equipment Market is defined by the presence of global leaders including Cisco Systems, Hewlett Packard Enterprise, Arista Networks, Juniper Networks, Dell Technologies, Nokia, TP-Link, Extreme Networks, ZTE Corporation, and MikroTik. These companies compete on innovation, product performance, scalability, and security capabilities to capture a larger customer base. Cisco Systems maintains a dominant position through its extensive portfolio of networking hardware, software, and integrated security solutions. Hewlett Packard Enterprise focuses on intelligent edge solutions and cloud-managed networking. Arista Networks leads in high-performance data center and cloud networking, while Juniper Networks emphasizes AI-driven automation and security integration. Dell Technologies leverages its broad IT infrastructure expertise to deliver end-to-end networking solutions, and Nokia strengthens its position with advanced IP networking and 5G-ready products. TP-Link and MikroTik cater to cost-sensitive segments with competitive pricing and reliable performance, while Extreme Networks and ZTE Corporation expand their portfolios with innovative, software-driven architectures. Strategic partnerships, mergers, and continuous R&D investments remain central to sustaining competitive advantage in this dynamic market.
Recent Developments
- In June 2025, Nokia integrated 5th Gen AMD EPYC processors into its Cloud Platform for improved performance and energy efficiency.
- In March 2025, Nokia launched 5G.MIL initiatives with Lockheed Martin and Verizon and showcased optical networking innovations at MWC.
- In February 2025, MikroTik added new storage-related features in RouterOS for devices supporting external storage such as RB1100, X86, and CHR platforms.
Market Concentration & Characteristics
The Enterprise Network Equipment Market demonstrates a moderate to high level of concentration, with a few dominant players controlling significant market share through extensive portfolios, global reach, and strong brand recognition. It features a competitive mix of multinational corporations and specialized vendors, each focusing on innovation, scalability, and security to differentiate their offerings. The market is characterized by rapid technological evolution, with trends such as software-defined networking, AI-driven automation, and cloud-managed infrastructure shaping product development. It demands consistent investment in research and development to address evolving enterprise requirements for speed, reliability, and secure connectivity. Vendors compete on performance, interoperability, and service quality, while strategic partnerships and acquisitions remain central to strengthening market positioning. It also benefits from recurring revenue models through managed services and subscription-based solutions, creating long-term client relationships. The market structure favors companies that can adapt quickly to emerging networking standards and deliver integrated solutions that align with hybrid and multi-cloud strategies.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Networking Technology, End-User, Deployment Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see increased adoption of AI-driven network management solutions.
- Cloud-managed networking will expand across enterprises of all sizes.
- Demand for high-speed connectivity will drive upgrades to advanced Ethernet and optical systems.
- 5G integration will enhance enterprise network capabilities and performance.
- Security-focused network designs will gain priority in procurement decisions.
- Edge computing deployments will increase demand for distributed networking solutions.
- Software-defined networking will become a standard approach in enterprise infrastructure.
- Energy-efficient and sustainable network equipment will see higher adoption.
- Vendors will focus on delivering more interoperable and scalable solutions.
- Strategic partnerships will strengthen product innovation and market reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Need for High-Speed, Reliable Connectivity
Enterprises are upgrading to advanced network equipment to support data-intensive applications, video conferencing, and cloud platforms, driving demand for high-performance routers, switches, and wireless solutions.
Expanding Cloud Adoption and Hybrid IT Architectures
The migration to cloud and hybrid IT models requires network equipment that can seamlessly integrate on-premises and cloud environments, increasing demand for scalable, secure, and virtualized networking solutions.
Proliferation of IoT Devices Across Industries
Widespread IoT deployments in sectors like manufacturing, healthcare, and logistics are fueling the need for robust, scalable network infrastructure capable of supporting thousands of connected devices with low latency and high reliability.
Rising Focus on Network Security and Threat Mitigation
Growing cybersecurity threats and strict regulatory requirements are pushing enterprises to invest in network equipment with integrated security features, such as real-time threat detection, encryption, and zero-trust architectures.
Integration of AI and Machine Learning for Network Optimization
Vendors are embedding AI and ML capabilities into network equipment to enable automated traffic management, predictive maintenance, and self-healing networks, which enhance operational efficiency and reduce downtime for enterprises.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Enterprise Network Equipment, and what is its projected size in 2032?
Which Enterprise Network Equipment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Enterprise Network Equipment market?
Who are the leading companies in the Enterprise Network Equipment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Small and Medium Enterprises
- 1.2.2 Large Enterprises
- 1.2.3 Government Organizations
- 1.2.4 Educational Institutions
- 1.3 By Product Type
- 1.3.1 Routers
- 1.3.2 Switches
- 1.3.3 Firewalls
- 1.3.4 Access Points
- 1.3.5 Load Balancers
- 1.4 By Deployment Type
- 1.4.1 On-Premises
- 1.4.2 Cloud-Based
- 1.4.3 Hybrid
- 1.5 By Networking Technology
- 1.5.1 Ethernet
- 1.5.2 Wireless
- 1.5.3 SD-WAN
- 1.5.4 MPLS
- 1.5.5 VPN
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 75,095.6 million → 2032: USD 98,886.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Enterprise Network Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Enterprise Network Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Enterprise Network Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Enterprise Network Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Enterprise Network Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Enterprise Network Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Enterprise Network Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Enterprise Network Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 75,095.6 million → 2032: USD 98,886.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Enterprise Network Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small and Medium Enterprises
- 12.3.7.2 Large Enterprises
- 12.3.7.3 Government Organizations
- 12.3.7.4 Educational Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Routers
- 12.4.7.2 Switches
- 12.4.7.3 Firewalls
- 12.4.7.4 Access Points
- 12.4.7.5 Load Balancers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premises
- 12.5.7.2 Cloud-Based
- 12.5.7.3 Hybrid
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Networking Technology - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Ethernet
- 12.6.7.2 Wireless
- 12.6.7.3 SD-WAN
- 12.6.7.4 MPLS
- 12.6.7.5 VPN
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Enterprise Network Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Enterprise Network Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Enterprise Network Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Enterprise Network Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cisco Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hewlett Packard Enterprise
- 18.4 Arista Networks
- 18.5 Juniper Networks
- 18.6 Dell Technologies
- 18.7 Nokia
- 18.8 TP-Link
- 18.9 Extreme Networks
- 18.10 ZTE Corporation
- 18.11 MikroTik
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

