
Market Overview
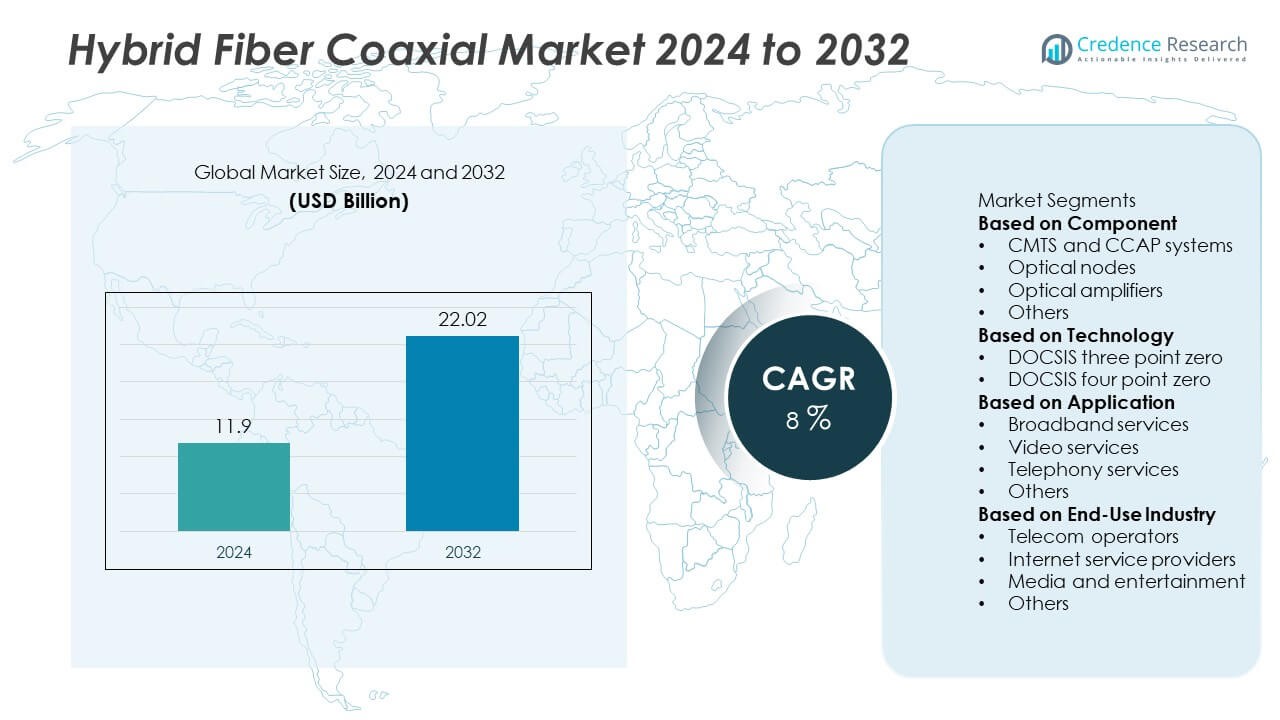
Hybrid Fiber Coaxial market size reached USD 11.9 billion in 2024 and is expected to rise to USD 22.02 billion by 2032. The market is set to grow at a CAGR of 8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hybrid Fiber Coaxial market Size 2024 | USD 11.9 Billion |
| Hybrid Fiber Coaxial market , CAGR | 8% |
| Hybrid Fiber Coaxial market Size 2032 | USD 22.02 Billion |
Top players in the Hybrid Fiber Coaxial market include Arris International, Cisco Systems, CommScope, Teleste Corporation, Huawei Technologies, Casa Systems, Nokia, Ciena Corporation, Harmonic Inc., and Technicolor SA. These companies strengthen their position through continuous DOCSIS advancements, enhanced CMTS platforms, and scalable optical components that support multi-gigabit broadband delivery. Their focus on virtualization, automation, and improved network efficiency helps operators upgrade hybrid networks with lower deployment costs. North America leads the market with a 38% share, driven by strong broadband adoption and extensive modernization of legacy coaxial networks. Europe and Asia Pacific follow, supported by growing digital services and steady operator investments.
Market Insights
- The market reached USD 11.9 billion in 2024 and will grow at a CAGR of 8%. Growth strengthens as operators expand hybrid networks to meet rising digital demand.
- Strong demand for high-speed broadband drives adoption of CMTS and CCAP systems, which hold a 45% share. DOCSIS four point zero leads technology use with a 52% share as operators push for higher upstream capacity.
- Multi-gigabit service expansion and network virtualization shape key trends, supporting faster upgrades and flexible operations. Streaming growth, remote work, and cloud use increase pressure for stable hybrid networks.
- Competition intensifies as major players enhance DOCSIS platforms and optical components. Fiber rollouts create restraints by raising performance expectations, while hybrid networks face heavy maintenance needs across ageing coaxial lines.
- North America leads with a 38% share, followed by Europe at 27% and Asia Pacific at 24%. Broadband services hold a 58% share, driven by strong data consumption across residential and enterprise users.
Market Segmentation Analysis:
By Component
CMTS and CCAP systems lead the component segment with a 45% market share. These platforms support unified bandwidth control and help operators manage dense subscriber loads. Optical nodes hold 28% share as service providers enhance last-mile delivery for stronger signal quality. Optical amplifiers secure 18% share due to their role in long-distance transmission stability. Other components make up 9% share through improved reliability and reduced maintenance needs. CMTS and CCAP systems stay dominant because operators demand real-time network optimization. Continued DOCSIS upgrades also reinforce their leadership across hybrid fiber coaxial networks.
- For instance, CommScope's E6000 Converged Edge Router (CER) is the industry's leading and most widely-deployed Converged Cable Access Platform (CCAP), used by operators across North America and globally. The platform is designed to provide high channel density and power efficiency.
By Technology
DOCSIS four point zero dominates the technology segment with a 52% market share. This version improves spectral efficiency and supports multi-gigabit performance for advanced digital applications. DOCSIS three point zero holds 48% share as many legacy systems still rely on it for stable speeds. Adoption of DOCSIS four point zero rises as competition from fiber networks increases. Operators prefer this upgrade because it delivers higher upstream capacity. The technology also offers a flexible migration path without complete infrastructure replacement. Strong performance and future-ready design maintain its leadership in hybrid deployments.
- For instance, Harmonic enables multi-gigabit upstream and downstream speeds through its CableOS Cloud-Native Core platform, which powers over 33 million cable modems globally, including deployments with major operators in Europe.
By Application
Broadband services lead the application segment with a 58% market share due to rising demand for fast internet. Video services capture 24% share, driven by growth in streaming and cloud-based entertainment. Telephony services hold 12% share through integrated voice offerings delivered over hybrid networks. Other applications secure 6% share, supported by IoT expansion and connected device adoption. Broadband services remain dominant because operators focus on high-speed access and low-latency performance. Digital lifestyles push continuous upgrades across hybrid networks. This demand strengthens broadband’s long-term leadership in the application landscape.
Key Growth Drivers
Rising Demand for High-Speed Broadband
Demand for high-speed broadband grows as homes and businesses rely on data-heavy tasks. Hybrid fiber coaxial networks offer strong downstream capacity, which helps operators deliver fast services without major infrastructure changes. Continuous expansion of streaming, gaming, and cloud-based tools drives upgrades across hybrid systems. Operators focus on low latency and consistent performance to meet user expectations. The flexible design of hybrid networks supports scalable improvements through DOCSIS enhancements. Growing digital adoption strengthens investment in hybrid deployments. This rising need for stable high-speed access positions hybrid fiber coaxial networks as a key broadband solution.
- For instance, Comcast upgraded more than 100,000 nodes with mid-split configurations delivering up to 85 MHz of upstream spectrum to support low-latency applications and lay the foundation for DOCSIS 4.0.
Cost-Efficient Network Expansion
Hybrid fiber coaxial networks support cost-efficient expansion because they reuse existing coaxial infrastructure. This approach reduces upgrade costs and shortens deployment timelines compared with full fiber rollouts. Operators boost capacity using advanced DOCSIS standards and software-based improvements. Lower capital needs help providers extend services to new regions. Cost efficiency also supports competitive pricing and rapid launch of upgraded broadband plans. Providers benefit from reduced construction work and simpler upgrade paths. This model helps operators balance performance goals with budget limits. Demand for affordable network expansion keeps this driver strong.
- For instance, Charter Communications is upgrading its network using DOCSIS 3.1 and 4.0 high-split enhancements, which raise upstream capacity, typically without requiring new fiber builds to every home.
Increasing Adoption of DOCSIS Upgrades
DOCSIS upgrades remain a major growth driver as operators enhance hybrid network capability. DOCSIS four point zero supports higher upstream capacity and improved latency for modern digital activities. The upgrade path enables multi-gigabit speeds without full infrastructure replacement. Strong demand for real-time applications encourages operators to improve spectral efficiency and signal processing. These upgrades support long-term scalability and better energy use. Providers gain stronger competitive positioning against fiber services. Continuous DOCSIS evolution reinforces hybrid network relevance. This shift improves performance across residential and enterprise markets.
Key Trends and Opportunities
Expansion of Multi-Gigabit Services
The expansion of multi-gigabit broadband creates strong opportunities for hybrid fiber coaxial systems. Operators use advanced DOCSIS standards to increase bandwidth and meet rising data needs. Growth in remote work, cloud gaming, and high-resolution content drives demand for faster speeds. Hybrid networks allow providers to offer premium service tiers at lower upgrade cost. Enterprises adopt higher-speed plans for cloud platforms and analytics tools. This trend pushes operators to optimize spectral capacity and support future-ready performance. Multi-gigabit service adoption strengthens the value of hybrid deployments.
- For instance, Nokia tested its 25G PON coexistence modules over HFC backbones, enabling operators to deliver multi-gigabit services across combined infrastructures.
Network Modernization Through Virtualization
Virtualization becomes a major trend as operators adopt software-driven systems for greater flexibility. Virtual CMTS and cloud-based control platforms enable faster service delivery and better traffic management. Automation improves operational efficiency and helps providers reduce hardware dependence. Real-time analytics enhance performance and support proactive maintenance. Virtualized hybrid networks scale faster and handle rising user demand more effectively. Providers gain opportunities to modernize networks without extensive physical upgrades. This shift strengthens hybrid network capability in competitive environments.
- For instance, Cisco deployed its virtualized cBR-8 platform supporting up to 256,000 L2TP sessions in operator-grade environments. It also offers up to 1.6 Tbps of capacity in a single chassis and supports up to 256 service groups with Remote PHY, enabling maximum speeds approaching 10 Gbps per subscriber.
Key Challenges
Rising Competition From Fiber Networks
Hybrid fiber coaxial networks face growing competition from expanding fiber deployments. Fiber-to-the-home projects attract users with higher speeds and long-term reliability. This shift pressures hybrid networks to deliver improved performance through frequent upgrades. Customers often view fiber as a premium service option. Operators must balance investment needs while improving hybrid capabilities. Competitive pressure forces providers to enhance pricing and service quality. Fiber expansion creates long-term market hurdles for hybrid systems. Operators respond with targeted upgrades and advanced DOCSIS adoption.
Increasing Infrastructure Maintenance Requirements
Hybrid fiber coaxial networks require ongoing maintenance due to faster wear of coaxial components. Ageing cables and amplifiers affect signal strength and reliability. Providers invest in inspections and replacements to maintain performance. These activities raise operational costs and slow expansion efforts. Environmental factors such as heat, moisture, and physical stress increase maintenance needs. Operators rely on advanced monitoring to detect issues early. High maintenance demands reduce long-term scalability. This challenge pushes providers to modernize systems and optimize operational practices.
Regional Analysis
North America North America holds a market share of 38%, driven by strong broadband adoption and continuous DOCSIS upgrades across major operators. Service providers invest in multi-gigabit rollouts and network automation to support rising demand from streaming, cloud gaming, and remote work. The region benefits from extensive legacy coaxial networks that enable cost-effective modernization. Growth stays steady as operators enhance upstream capacity and improve latency to compete with expanding fiber deployments. Government programs supporting rural broadband expansion also boost hybrid network investments. Strong digital consumption patterns reinforce North America’s leading position in the market.
Europe
Europe accounts for a market share of 27%, supported by ongoing modernization of hybrid broadband infrastructure across key countries. Operators focus on improving service quality through DOCSIS enhancements and targeted coaxial upgrades. The region sees rising demand for high-speed connectivity due to cloud adoption and digital media growth. Regulatory support for network improvement and fair-competition frameworks encourages operators to expand hybrid services. Competition from fiber networks drives hybrid systems to deliver higher performance and stability. The shift toward digital public services and connected homes strengthens the region’s reliance on hybrid deployment models.
Asia Pacific
Asia Pacific captures a market share of 24%, driven by rising internet penetration and rapid expansion of digital services across developing economies. Operators invest in hybrid fiber coaxial networks to deliver affordable high-speed broadband in dense urban regions. Growth accelerates as streaming, online education, and mobile-first ecosystems expand. Countries with large populations support strong demand for hybrid upgrades to manage traffic loads efficiently. Hybrid networks provide a practical solution where fiber rollout remains slow or costly. Continuous DOCSIS adoption and rising multi-device usage reinforce Asia Pacific’s growing importance in the global market.
Latin America
Latin America holds a market share of 7%, supported by growing investments in broadband infrastructure and gradual modernization of cable networks. Operators use hybrid fiber coaxial systems to expand coverage in urban and semi-urban areas at lower cost. Rising digital entertainment consumption and small-business connectivity needs strengthen market demand. Economic constraints make hybrid networks a cost-effective alternative to full fiber deployment. Service providers adopt DOCSIS improvements to enhance speed and reliability. The region continues to develop through targeted upgrades and government-led connectivity programs that improve digital inclusion.
Middle East and Africa
The Middle East and Africa represent a market share of 4%, with growth driven by increasing broadband adoption and gradual expansion of hybrid network infrastructure. Operators invest in hybrid systems to offer competitive internet services while managing deployment costs in diverse geographic areas. Urban regions see stronger adoption as demand rises for streaming, cloud services, and digital banking. Hybrid networks help bridge gaps where fiber expansion remains limited or slow. Government initiatives promoting digital transformation encourage further investment. Steady enhancements in network capacity and reliability support the region’s emerging presence in the market.
Market Segmentations:
By Component
- CMTS and CCAP systems
- Optical nodes
- Optical amplifiers
- Others
By Technology
- DOCSIS three point zero
- DOCSIS four point zero
By Application
- Broadband services
- Video services
- Telephony services
- Others
By End-Use Industry
- Telecom operators
- Internet service providers
- Media and entertainment
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape features major players such as Arris International, Cisco Systems, CommScope, Teleste Corporation, Huawei Technologies, Casa Systems, Nokia, Ciena Corporation, Harmonic Inc., and Technicolor SA. These companies focus on strengthening hybrid fiber coaxial infrastructure through continuous DOCSIS upgrades, advanced CMTS platforms, and enhanced optical components. Vendors invest in multi-gigabit solutions and network virtualization to improve flexibility and reduce operational complexity. Strategic partnerships with telecom operators help accelerate regional deployments and support faster service rollouts. Companies also expand R&D activities to deliver higher upstream capacity and better latency performance. Competitive pressure intensifies as firms integrate AI-driven monitoring and cloud-based network control to support scalable modernization. Operators prefer suppliers offering end-to-end hybrid solutions that combine performance, cost efficiency, and long-term upgrade paths.
Key Player Analysis
- Arris International
- Cisco Systems
- CommScope
- Teleste Corporation
- Huawei Technologies
- Casa Systems
- Nokia
- Ciena Corporation
- Harmonic Inc.
- Technicolor SA
Recent Developments
- In August 2025, CommScope achieved record-breaking downstream speeds of over 16 Gbps at a CableLabs interoperability event, demonstrating the technology's readiness.
- In June 2025, CommScope announced that Liberty Global had chosen it to support its DOCSIS 4.0 Distributed Access Architecture (DAA) deployment.
- In September 2024, Harmonic and Mediacom Communications Corporation announced the production deployment of Unified DOCSIS 4.0 on a live HFC network in Moline, Illinois.
Report Coverage
The research report offers an in-depth analysis based on Component, Technology, Application, End-Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Operators will expand multi-gigabit broadband plans to meet rising data usage.
- DOCSIS four point zero adoption will accelerate as providers seek higher upstream capacity.
- Hybrid networks will integrate more automation to improve service reliability.
- Virtual CMTS platforms will gain traction as operators shift toward software-driven control.
- Network upgrades will focus on reducing latency for cloud gaming and real-time applications.
- Hybrid systems will remain a cost-effective alternative in regions where fiber rollout is slow.
- Demand for enhanced optical components will increase to support long-distance transmission.
- Maintenance optimization tools will grow as operators monitor ageing coaxial lines more closely.
- Integration of AI-driven traffic management will support better bandwidth allocation.
- Regional investments will rise as governments push for broader digital access and connectivity.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for High-Speed Broadband
As homes and businesses increasingly rely on data-intensive applications, hybrid fiber coaxial networks are essential for delivering fast, stable internet without requiring full infrastructure replacement. This demand is further fueled by the expansion of streaming, gaming, and cloud-based services.
Cost-Efficient Network Expansion
Hybrid fiber coaxial systems allow operators to upgrade and expand broadband coverage by leveraging existing coaxial infrastructure, significantly reducing capital expenditure and deployment time compared to full fiber rollouts. This cost efficiency enables rapid service launches and competitive pricing.
Increasing Adoption of DOCSIS Upgrades
Continuous advancements in DOCSIS technology, especially the transition to DOCSIS 4.0, enable operators to offer higher upstream capacity and multi-gigabit speeds. These upgrades support real-time applications and future-proof hybrid networks against growing competition from fiber deployments.
Expansion of Multi-Gigabit Services
The proliferation of remote work, cloud gaming, and high-resolution content is driving operators to expand multi-gigabit broadband offerings. Hybrid fiber coaxial networks, enhanced by advanced DOCSIS standards, allow providers to deliver premium service tiers efficiently.
Network Modernization Through Virtualization
Operators are increasingly adopting virtual CMTS and cloud-based control platforms to improve operational flexibility, automate network management, and scale services rapidly. Virtualization supports faster upgrades, reduces hardware dependency, and enhances network reliability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Hybrid Fiber Coaxial market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hybrid Fiber Coaxial market projected to grow between 2025 and 2032?
Which Hybrid Fiber Coaxial market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hybrid Fiber Coaxial market?
Who are the leading companies in the Hybrid Fiber Coaxial market?
Which region commanded the largest share of the Hybrid Fiber Coaxial market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 CMTS and CCAP systems
- 1.2.2 Optical nodes
- 1.2.3 Optical amplifiers
- 1.2.4 Others
- 1.3 By Technology
- 1.3.1 DOCSIS three point zero
- 1.3.2 DOCSIS four point zero
- 1.4 By Application
- 1.4.1 Broadband services
- 1.4.2 Video services
- 1.4.3 Telephony services
- 1.4.4 Others
- 1.5 By End-Use Industry
- 1.5.1 Telecom operators
- 1.5.2 Internet service providers
- 1.5.3 Media and entertainment
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11.9 billion → 2032: USD 22.02 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hybrid Fiber Coaxial Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hybrid Fiber Coaxial Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hybrid Fiber Coaxial Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hybrid Fiber Coaxial Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hybrid Fiber Coaxial Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hybrid Fiber Coaxial Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hybrid Fiber Coaxial Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hybrid Fiber Coaxial Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11.9 billion → 2032: USD 22.02 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hybrid Fiber Coaxial Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 CMTS and CCAP systems
- 12.3.7.2 Optical nodes
- 12.3.7.3 Optical amplifiers
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 DOCSIS three point zero
- 12.4.7.2 DOCSIS four point zero
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Broadband services
- 12.5.7.2 Video services
- 12.5.7.3 Telephony services
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Telecom operators
- 12.6.7.2 Internet service providers
- 12.6.7.3 Media and entertainment
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hybrid Fiber Coaxial End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hybrid Fiber Coaxial Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hybrid Fiber Coaxial Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hybrid Fiber Coaxial Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arris International
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cisco Systems
- 18.4 CommScope
- 18.5 Teleste Corporation
- 18.6 Huawei Technologies
- 18.7 Casa Systems
- 18.8 Nokia
- 18.9 Ciena Corporation
- 18.10 Harmonic Inc.
- 18.11 Technicolor SA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

