
Market Overview
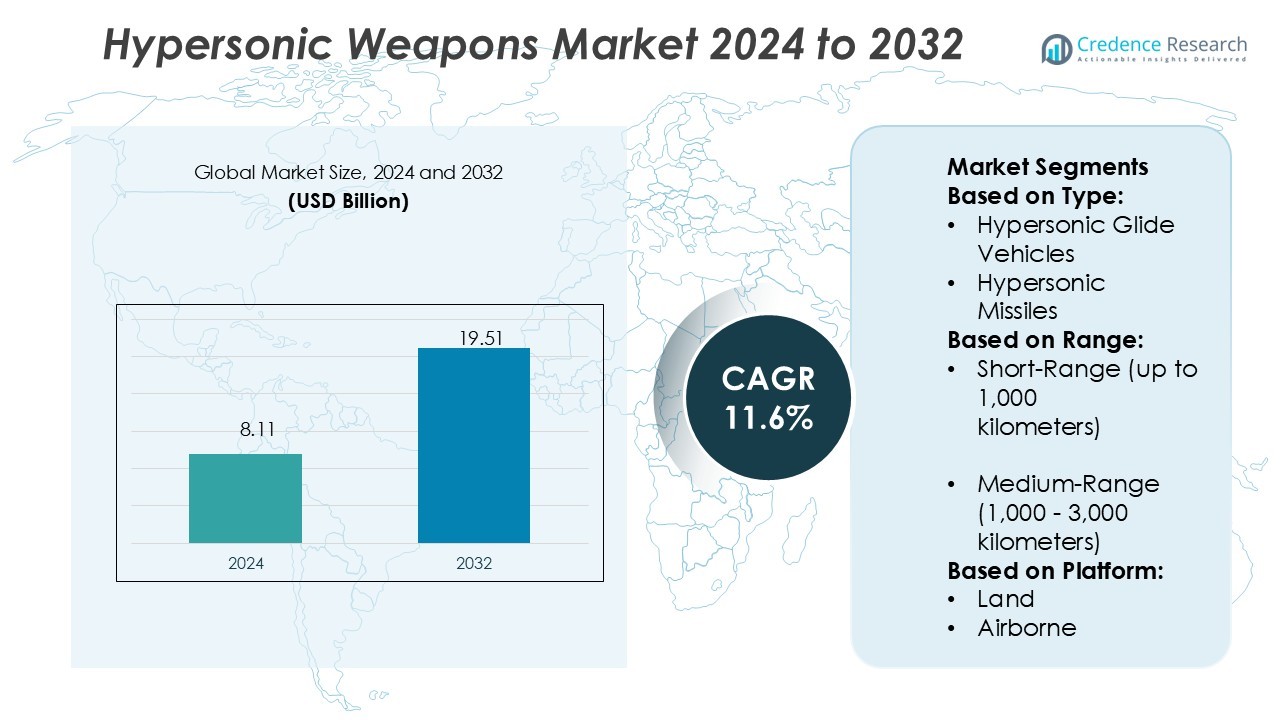
Hypersonic Weapons Market size was valued USD 8.11 billion in 2024 and is anticipated to reach USD 19.51 billion by 2032, at a CAGR of 11.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hypersonic Weapons Market Size 2024 | USD 8.11 Billion |
| Hypersonic Weapons Market, CAGR | 11.6% |
| Hypersonic Weapons Market Size 2032 | USD 19.51 Billion |
The hypersonic weapons market is shaped by top players including Lockheed Martin Corporation, Northrop Grumman, RTX, BAE Systems, Thales Group, Leonardo S.p.A., AIRBUS, L3Harris Technologies, Inc., NXP Semiconductors, Infineon Technologies AG, Robert Bosch GmbH, Aerojet Rocketdyne Holdings Inc., General Dynamics Corporation, The Boeing Company, BrahMos Aerospace Pvt. Ltd., Denel Dynamics, J.S.C. Tactical Missiles Corporation, and Raytheon Technologies. These companies drive innovation in propulsion, guidance, and thermal protection systems to enhance strike capabilities. North America leads the global market with a 38% share, supported by extensive U.S. defense programs and strong government funding. The region’s dominance is reinforced by advanced R&D infrastructure, strategic defense contracts, and continuous technological innovation, positioning it as the primary hub for hypersonic weapons development.
Market Insights
- The hypersonic weapons market size was USD 8.11 billion in 2024 and is expected to reach USD 19.51 billion by 2032, growing at a CAGR of 11.6%.
- Rising defense modernization programs and advancements in propulsion and thermal protection technologies are driving strong demand for hypersonic systems across major military powers.
- Integration into multi-domain operations, including land, airborne, and naval platforms, reflects a growing trend, with airborne systems holding the largest segment share due to rapid deployment capabilities.
- High development and deployment costs, along with technical complexity, remain key restraints, limiting widespread adoption to nations with significant defense budgets and advanced R&D capacity.
- North America leads the market with a 38% regional share, supported by extensive U.S. defense initiatives, while Asia-Pacific accounts for 30% and emerges as the fastest-growing region due to strategic programs in China, India, and Japan, reinforcing the global competitive landscape dominated by leading defense contractors and technology firms.
Market Segmentation Analysis:
By Type
In the hypersonic weapons market, hypersonic glide vehicles hold the dominant share at 57%. Their ability to maneuver at high speeds while evading missile defense systems drives their adoption. These vehicles offer longer range, higher survivability, and precision strike capabilities compared to hypersonic missiles. Defense modernization programs in the U.S., Russia, and China emphasize glide vehicle development due to their strategic deterrence value. Hypersonic missiles continue to gain traction in tactical roles, but glide vehicles remain the preferred choice for long-range, high-impact operations, strengthening their market leadership.
- For instance, Airbus advances digital twin integration across its platforms: over 12,000 aircraft are connected via the Skywise platform, enabling real-time sensor data streaming to virtual models for predictive maintenance.
By Range
The long-range segment leads the market with a 49% share, supported by growing strategic defense initiatives. Nations prioritize weapons capable of traveling above 3,000 kilometers to ensure deterrence and reach critical targets. Investments in advanced propulsion systems and thermal protection technologies enhance long-range system efficiency. Geopolitical tensions and great power competition further accelerate demand for intercontinental capabilities. While medium-range systems gain traction for regional conflicts, the long-range category dominates due to its ability to reinforce military superiority and strategic reach, making it the most vital range classification in the hypersonic market.
- For instance, RTX’s Pratt & Whitney business, in collaboration with Collins Aerospace, completed a rated-power test of a 1 MW electric motor in its hybrid-electric demonstrator.
By Platform
Airborne platforms account for the largest market share at 46%, driven by flexibility and rapid deployment. Fighter jets and bombers equipped with hypersonic weapons can launch strikes across wide operational zones. Programs such as the U.S. Air Force’s AGM-183 ARRW and Russia’s Kinzhal missile highlight investment in air-launched hypersonics. The airborne segment benefits from reduced infrastructure dependency and faster deployment timelines compared to land or naval systems. While naval platforms are expanding with integration on submarines and destroyers, airborne platforms dominate due to their proven adaptability, strong funding, and integration with existing air combat systems.
Key Growth Drivers
Rising Defense Modernization Programs
Global defense modernization is a major driver for the hypersonic weapons market. Nations such as the U.S., China, and Russia are heavily investing in next-generation strike capabilities. Governments seek to strengthen deterrence strategies by deploying advanced hypersonic systems capable of penetrating missile defenses. Large defense budgets and multi-billion-dollar R&D programs enhance hypersonic development. The race for technological superiority in long-range precision strike weapons ensures consistent funding and accelerates deployment timelines, positioning hypersonic weapons as a critical element of modern military power projection.
- For instance, Infineon became the first semiconductor firm to develop 300-millimeter GaN (gallium nitride) power wafers inside its high-volume manufacturing lines, pushing power density and efficiency forward.
Geopolitical Tensions and Strategic Rivalries
Escalating geopolitical tensions and military rivalries drive hypersonic weapons demand. Border conflicts, territorial disputes, and competition for global dominance push nations to adopt faster and more evasive weapons. Hypersonics provide unmatched speed and maneuverability, giving military forces a tactical advantage in both deterrence and combat. Strategic competitors are prioritizing hypersonic deployment to counter adversaries and maintain superiority. As regional conflicts intensify, countries across Asia-Pacific, North America, and Europe accelerate procurement, ensuring hypersonics remain a priority investment in national defense strategies.
- For instance, BAE Systems announced a sixteen-fold increase in 155 mm artillery shell production capacity using a continuous flow processing method for explosives and propellants. ([Business Insider].
Advancements in Propulsion and Materials Technology
Technological progress in propulsion systems and advanced materials supports market expansion. Scramjet engines and novel thermal protection materials enable sustained flight at Mach 5+ speeds. These advancements enhance reliability, reduce vulnerability, and extend operational range for hypersonic systems. Defense contractors are collaborating with aerospace firms to integrate cutting-edge composites and heat-resistant alloys into designs. Continuous innovation improves cost-effectiveness and performance, making hypersonic weapons more feasible for large-scale deployment. Technology breakthroughs strengthen competitiveness and ensure that governments maintain long-term investments in these next-generation strike capabilities.
Key Trends & Opportunities
Integration with Multi-Domain Operations
A key trend is the integration of hypersonic weapons into multi-domain warfare strategies. Defense forces are aligning hypersonic programs with air, land, sea, and space platforms to enhance mission flexibility. This creates opportunities for joint-force applications and seamless interoperability across military branches. Naval integration on submarines and destroyers, alongside air-launched platforms, expands operational use. Such cross-domain deployment strengthens deterrence and broadens defense strategies, making hypersonic weapons a central feature in future battle doctrines.
- For instance, Northrop’s Stand-in Attack Weapon (SiAW) has been delivered to the U.S. Air Force for testing. The high-speed missile is engineered to fit inside F-35 internal weapons bays and is intended to complement multi-domain strike strategies by engaging rapidly relocatable targets within enemy anti-access/area-denial environments.
Growing Defense Collaborations and Alliances
International collaborations in hypersonic research present opportunities for market growth. NATO members, Japan, India, and Australia are pursuing joint programs with established defense powers. These partnerships allow cost-sharing, knowledge exchange, and faster development timelines. For example, U.S. and Australian collaboration under the SCIFiRE program highlights joint hypersonic testing. Expanding alliances not only enhance technological expertise but also drive adoption beyond traditional military powers. This cooperative approach strengthens collective security, ensuring broader global demand for hypersonic systems.
- For instance, NXP introduced LDMOS transistors that deliver 1,500 W peak RF output power (MMRF1317H) between 1,030–1,090 MHz, enabling high-power radar and IFF systems.
Key Challenges
High Development and Deployment Costs
The hypersonic weapons market faces challenges due to high R&D and production costs. Advanced propulsion systems, specialized materials, and extensive testing require billions in investment. Many developing countries find it difficult to allocate sufficient defense budgets for hypersonic programs. Even established powers struggle with balancing costs against competing defense priorities. These financial barriers limit widespread adoption, restricting participation to a few nations with substantial resources. The high costs of deployment and maintenance may delay large-scale procurement.
Technical Complexity and Safety Concerns
Developing hypersonic weapons involves extreme technical complexity, creating significant challenges for manufacturers. Sustaining stable flight at Mach 5+ speeds requires advanced thermal management, precision guidance, and robust propulsion systems. Failures during testing can lead to major financial losses and program delays. Safety concerns surrounding heat-resistant materials and integration with existing platforms further complicate adoption. The complexity of ensuring operational reliability under extreme conditions makes development a high-risk endeavor. These hurdles slow commercialization and prolong timelines for global deployment.
Regional Analysis
North America
North America leads the hypersonic weapons market with a 38% share, driven by extensive U.S. defense programs. The region invests heavily in R&D, supported by agencies such as DARPA and the U.S. Department of Defense. Programs like the AGM-183 ARRW and the Hypersonic Conventional Strike Weapon highlight strong funding commitments. Rising competition with China and Russia further accelerates development. The presence of major defense contractors, advanced aerospace infrastructure, and significant government budgets ensures continuous innovation. North America’s focus on long-range deterrence and rapid deployment capabilities secures its dominant position in the global hypersonic market.
Europe
Europe holds a 22% share of the hypersonic weapons market, supported by NATO-led initiatives and domestic programs. France, Germany, and the U.K. invest in indigenous systems while strengthening collaboration with allies to counter growing global threats. The European Union emphasizes joint research to close capability gaps with the U.S., Russia, and China. Programs focusing on air-launched and land-based systems are gaining traction. Defense industrial bases across Europe benefit from technological partnerships, ensuring steady progress. Regional demand is driven by strategic deterrence requirements, defense modernization, and rising security concerns due to geopolitical instability.
Asia-Pacific
Asia-Pacific accounts for 30% of the global market, emerging as the fastest-growing region. China dominates with advanced hypersonic missile programs like DF-17, while India and Japan expand indigenous development. Regional investments are fueled by escalating territorial disputes, maritime tensions, and strategic rivalries. Governments prioritize hypersonic weapons for both tactical and long-range operations. Collaboration with global defense firms enhances local innovation. Expanding aerospace and defense budgets, particularly in China and India, support large-scale adoption. Asia-Pacific’s rapid industrialization, technological advancement, and heightened security environment make it a critical growth hub in the global hypersonic weapons market.
Latin America
Latin America captures a 4% share, with slow but steady progress in defense modernization. Brazil leads regional initiatives, focusing on advanced aerospace technologies and potential hypersonic research collaborations. Budgetary constraints and competing social priorities limit large-scale adoption across most countries. However, interest in hypersonic weapons is rising as regional governments seek to modernize missile capabilities and enhance deterrence. Partnerships with global defense firms are key to accessing technology. Although Latin America’s role remains small compared to major markets, gradual investments and collaborative programs may support future regional growth in the hypersonic weapons sector.
Middle East & Africa
The Middle East & Africa region holds a 6% share, with growing interest in advanced defense systems. Nations such as Saudi Arabia, Israel, and the UAE are exploring hypersonic technologies to strengthen deterrence. Rising regional conflicts and security challenges drive procurement efforts. However, dependence on imports and partnerships with Western defense contractors limits indigenous development. Investments focus primarily on missile defense integration and future-oriented strike capabilities. Africa remains a minor contributor due to limited budgets. The region’s market growth is shaped by rising security threats, modernization needs, and collaborations with leading defense suppliers.
Market Segmentations:
By Type:
- Hypersonic Glide Vehicles
- Hypersonic Missiles
By Range:
- Short-Range (up to 1,000 kilometers)
- Medium-Range (1,000 - 3,000 kilometers)
By Platform:
- Land
- Airborne
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The hypersonic weapons market is shaped by leading players such as Leonardo S.p.A., Robert Bosch GmbH, AIRBUS, RTX, Thales Group, L3Harris Technologies, Inc., Infineon Technologies AG, BAE Systems, Northrop Grumman, and NXP Semiconductors. The hypersonic weapons market is highly competitive, driven by rapid advancements in propulsion, guidance, and materials technologies. Companies are focusing on high-speed strike systems capable of penetrating advanced missile defense networks. Significant investments in R&D and testing programs aim to enhance speed, maneuverability, and precision while ensuring operational reliability. Defense contractors prioritize long-range deterrence capabilities and integration across land, air, and naval platforms. Strategic collaborations, government-funded programs, and international partnerships are central to strengthening market presence. The competitive environment is defined by technological innovation, defense alliances, and growing demand for next-generation weapons, fueling steady market expansion.
Key Player Analysis
- Leonardo S.p.A.
- Robert Bosch GmbH
- AIRBUS
- RTX
- Thales Group
- L3Harris Technologies, Inc.
- Infineon Technologies AG
- BAE Systems
- Northrop Grumman
- NXP Semiconductors
Recent Developments
- In May 2025, Scopic acquired ZoomRadar, a provider of real-time weather data and radar visualization tools. The acquisition aims to enhance ZoomRadar’s platform using Scopic’s expertise in AI and cloud technologies. This move strengthens Scopic’s position in delivering advanced weather intelligence solutions across various industries.
- In January 2025, Arbe partnered with NVIDIA to integrate its high-resolution MIMO radar with NVIDIA’s DRIVE AGX platform. The collaboration enables real-time free-space mapping and detection of small obstacles under all conditions. This joint solution aims to advance safety and performance in ADAS and autonomous driving systems.
- In March 2024 Castelion, a startup aiming to develop hypersonic weapons for the Pentagon, announced that it has conducted its first system test. This marks a significant step as a growing number of smaller hypersonic arms manufacturers challenge large defense contractors with more cost-effective and rapidly produced products, according to Reuters.
- In March 2024, US tests hypersonic missile in Pacific as it aims to keep up with China and Russia. B-52 crews take part in hypersonic weapon familiarization to China that Washington remains competitive in this advanced weapons arena, where Beijing is often perceived to have an advantage.
Report Coverage
The research report offers an in-depth analysis based on Type, Range, Platform and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Hypersonic weapons will gain wider adoption as nations prioritize long-range deterrence.
- Advancements in propulsion will improve speed, range, and maneuverability of future systems.
- Integration with multi-domain operations will expand deployment across land, air, and naval platforms.
- Defense collaborations will accelerate technology sharing and shorten development cycles.
- Miniaturization of electronics will enhance precision guidance and strike accuracy.
- Stronger thermal protection materials will support extended hypersonic flight endurance.
- Rising geopolitical tensions will drive continuous investments in hypersonic programs.
- Testing and simulation capabilities will advance to reduce risks and costs.
- Demand for air-launched systems will grow due to rapid deployment flexibility.
- International regulatory discussions may emerge to address security and arms control.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Defense Modernization Programs
Major military powers such as the U.S., China, and Russia are investing heavily in next-generation hypersonic strike capabilities to strengthen deterrence and maintain technological superiority. These modernization efforts are fueling consistent funding and accelerating the deployment of hypersonic weapons.
Geopolitical Tensions and Strategic Rivalries
Escalating border conflicts, territorial disputes, and great power competition are pushing nations to adopt hypersonic weapons for their unmatched speed and maneuverability, providing a tactical advantage and reinforcing national security strategies.
Advancements in Propulsion and Materials Technology
Breakthroughs in scramjet engines and heat-resistant materials are enabling sustained flight at Mach 5+ speeds, improving reliability, range, and survivability of hypersonic systems, and making them more viable for large-scale deployment.
Integration with Multi-Domain Operations
The trend toward integrating hypersonic weapons across land, air, and naval platforms is expanding operational flexibility and enabling joint-force applications, which increases the attractiveness and utility of hypersonic systems for modern militaries.
Growing Defense Collaborations and Alliances
International partnerships and joint R&D programs, such as those between the U.S. and Australia, are accelerating technology sharing, reducing development timelines, and broadening the adoption of hypersonic weapons beyond traditional military powers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hypersonic Weapons Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hypersonic Weapons Market projected to grow between 2025 and 2032?
Which Hypersonic Weapons Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hypersonic Weapons Market?
Who are the leading companies in the Hypersonic Weapons Market?
Which region commanded the largest share of the Hypersonic Weapons Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Hypersonic Glide Vehicles
- 1.2.2 Hypersonic Missiles
- 1.3 By Range
- 1.3.1 Short-Range (up to 1,000 kilometers)
- 1.3.2 Medium-Range (1,000 - 3,000 kilometers)
- 1.3.3 Long-Range (above 3,000 kilometers)
- 1.4 By Platform
- 1.4.1 Land
- 1.4.2 Airborne
- 1.4.3 Naval
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8.11 billion → 2032: USD 19.51 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hypersonic Weapons Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hypersonic Weapons Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hypersonic Weapons Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hypersonic Weapons Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hypersonic Weapons Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hypersonic Weapons Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hypersonic Weapons Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hypersonic Weapons Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8.11 billion → 2032: USD 19.51 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hypersonic Weapons Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hypersonic Glide Vehicles
- 12.3.7.2 Hypersonic Missiles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Short-Range (up to 1,000 kilometers)
- 12.4.7.2 Medium-Range (1,000 - 3,000 kilometers)
- 12.4.7.3 Long-Range (above 3,000 kilometers)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Platform - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Land
- 12.5.7.2 Airborne
- 12.5.7.3 Naval
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hypersonic Weapons Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hypersonic Weapons Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hypersonic Weapons Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Lockheed Martin Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Northrop Grumman
- 17.4 RTX
- 17.5 BAE Systems
- 17.6 Thales Group
- 17.7 Leonardo S.p.A.
- 17.8 AIRBUS
- 17.9 L3Harris Technologies, Inc.
- 17.10 General Dynamics Corporation
- 17.11 The Boeing Company
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

