
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Hypo Anti Allergic Baby Food Market Size 2024 | 3269.9 million |
| FHypo Anti Allergic Baby Food Market, CAGR | 3.9% |
| Hypo Anti Allergic Baby Food Market Size 2032 | USD 4440.77 million |
Market Overview:
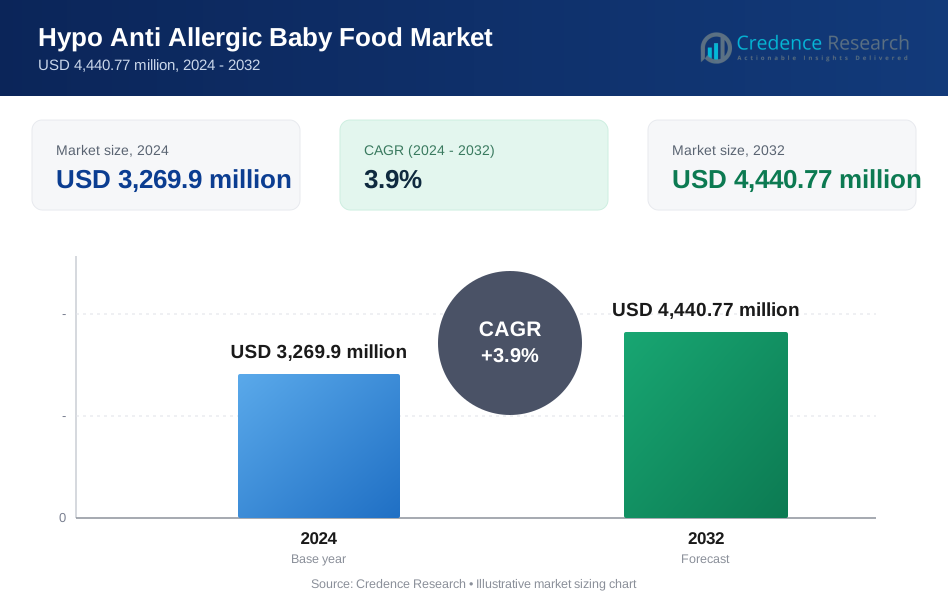
The Hypo Anti Allergic Baby Food Market is projected to grow from USD 3269.9 million in 2024 to an estimated USD 4440.77 million by 2032, with a compound annual growth rate (CAGR) of 3.9% from 2024 to 2032.
The primary drivers of the hypoallergenic baby food market include the increasing prevalence of food allergies among infants and the growing demand for safe, allergen-free products. Parents are becoming more aware of the risks associated with allergenic foods and are prioritizing preventive measures, including tailored nutrition solutions. Campaigns led by healthcare organizations and pediatricians have further amplified awareness of hypoallergenic options, driving adoption rates. Additionally, advancements in food science have enabled the development of high-quality products with enhanced nutritional profiles, catering to the needs of health-conscious consumers. Rising disposable incomes, urbanization, and a growing preference for organic and natural ingredients further bolster the market's momentum. The convenience offered by ready-to-consume hypoallergenic baby food has also emerged as a key factor influencing purchasing behavior.
Regionally, North America holds the largest share of the hypoallergenic baby food market, attributed to a high prevalence of infant allergies, increased awareness, and widespread availability of premium products. Europe follows closely, driven by strict food safety regulations, a strong focus on child health, and significant consumer trust in hypoallergenic formulations. Meanwhile, the Asia-Pacific region is expected to exhibit the fastest growth during the forecast period, fueled by rising birth rates, urbanization, and a growing middle class with increased spending power and awareness of specialized baby food options. Emerging markets in Latin America and the Middle East & Africa are also seeing steady growth, supported by improving healthcare infrastructure, growing retail penetration, and a shift in consumer preferences toward allergen-free and specialized nutrition products. These regions present lucrative opportunities for market players looking to expand their global footprint.
Market Insights:
- The market is expected to grow from USD 3,269.9 million in 2024 to USD 4,440.77 million by 2032, with a steady CAGR of 3.9%, driven by rising awareness and demand for allergen-free products.
- Increasing prevalence of infant food allergies and heightened parental awareness are key drivers, encouraging the adoption of specialized hypoallergenic baby food.
- Advancements in food science and the incorporation of organic and natural ingredients have enhanced product quality and aligned with health-conscious consumer preferences.
- North America leads the market due to high prevalence of allergies, increased consumer awareness, and the availability of premium hypoallergenic products.
- Europe follows closely, supported by stringent food safety regulations and a strong focus on organic, allergen-free formulations trusted by consumers.
- The Asia-Pacific region is projected to witness the fastest growth, fueled by rising birth rates, urbanization, and an expanding middle class with growing spending power.
- Challenges such as high production costs, premium pricing, and limited awareness in emerging regions could hinder market growth but also present opportunities for affordable and localized product offerings.
Market Drivers:
Rising Prevalence of Infant Food Allergies
The growing prevalence of food allergies among infants is a significant driver of the hypoallergenic baby food market. Research indicates that an increasing number of children worldwide are diagnosed with food allergies, necessitating specialized dietary solutions. Cow's milk protein allergy (CMPA) and other allergenic conditions are becoming more common, prompting parents to seek hypoallergenic alternatives to traditional baby food. For instance, Nestlé has developed a hypoallergenic infant formula that uses extensively hydrolyzed proteins to reduce allergenicity, providing a safe alternative for infants with CMPA. The heightened awareness of these conditions and their potential health risks has led to a surge in demand for allergen-free nutrition, positioning hypoallergenic baby food as a critical solution for addressing these dietary needs.
Increased Parental Awareness and Health Consciousness
Parental awareness of the importance of allergen-free and nutrient-rich food for infants has grown substantially in recent years. Modern parents are more health-conscious and actively seek products that minimize the risk of allergic reactions while promoting optimal growth and development. Educational campaigns by healthcare professionals, pediatricians, and global organizations have played a crucial role in spreading awareness about food allergies and the benefits of hypoallergenic diets. For example, the American Academy of Pediatrics (AAP) has been actively promoting guidelines for the prevention of food allergies in children, encouraging early introduction of allergenic foods under medical supervision. This heightened awareness has led to an increased willingness among parents to invest in premium, safe, and effective baby food options tailored to their child’s specific needs.
Advancements in Food Science and Technology
Technological advancements in the food industry have significantly contributed to the development of hypoallergenic baby food. Innovations in processing techniques, such as extensive protein hydrolysis and amino acid-based formulations, ensure the elimination of allergens while retaining essential nutrients. For example, Danone's Nutricia brand has developed an amino acid-based formula that is free from cow's milk proteins, providing a complete nutritional solution for infants with severe allergies. These advancements have enabled manufacturers to create highly specialized products that cater to the dietary requirements of infants with allergies or sensitivities. Furthermore, the growing trend toward organic and natural formulations aligns with consumer preferences, further boosting the appeal of hypoallergenic baby food. Continuous research and development efforts by industry players are expected to enhance product offerings and fuel market growth.
Shifting Consumer Preferences and Market Expansion
Consumer preferences are shifting toward safer and more transparent food choices, driving the growth of the hypoallergenic baby food market. Parents increasingly prefer products with clear labeling, free from artificial additives, and made with natural or organic ingredients. This trend has created opportunities for manufacturers to differentiate their offerings and appeal to a broader audience. For instance, Happy Family Organics offers a range of hypoallergenic baby foods that are certified organic and free from common allergen. Additionally, the expansion of retail and e-commerce channels has made hypoallergenic baby food more accessible to consumers globally. Emerging markets in Asia-Pacific, Latin America, and Africa are experiencing growing demand, fueled by rising disposable incomes and urbanization, making these regions key areas for market growth and investment.
Market Trends:
Surging Demand for Plant-Based Hypoallergenic Baby Food
A notable trend in the hypoallergenic baby food market is the increasing preference for plant-based formulations. Parents are increasingly gravitating toward plant-based products as they are perceived to be safer, less allergenic, and environmentally sustainable. This shift is driven by growing concerns about the environmental impact of animal-based products and the rising adoption of vegan and vegetarian diets. Companies are responding to this trend by introducing plant-based hypoallergenic options, such as soy-based and pea-protein-based baby foods, which cater to the needs of infants with dairy or other animal-protein allergies. For instance, Else Nutrition recently launched its plant-based infant formula in Australia, which is free from dairy and soy and Clean Label certified. This formula aims to replicate the nutritional benefits of human milk while catering to infants with allergies, reflecting the growing demand for plant-based hypoallergenic options in the market. The market for plant-based alternatives is projected to grow at a faster pace, reflecting this evolving consumer preference.
Growth of E-Commerce as a Key Distribution Channel
The expansion of e-commerce is reshaping how hypoallergenic baby food is purchased, particularly in developed regions like North America and Europe. Online platforms offer convenience, a wide variety of product choices, and the ability to access detailed nutritional information, which appeals to tech-savvy and health-conscious parents. For example, Danone reported a increase in online sales of its plant-based baby food products in 2023, driven by the convenience of e-commerce and direct-to-consumer models. This shift has allowed parents to access specialized hypoallergenic products more easily, particularly during the pandemic when online shopping surged. Moreover, the availability of subscription models and direct-to-consumer (DTC) delivery services has boosted the accessibility of specialized hypoallergenic products. Emerging markets in Asia-Pacific and Latin America are also witnessing a surge in online shopping, driven by increasing internet penetration and smartphone usage. This trend is prompting manufacturers to invest in robust e-commerce strategies to capture a larger market share.
Integration of Organic and Clean Label Ingredients
The growing preference for organic and clean-label products is transforming the hypoallergenic baby food market. Parents are increasingly prioritizing baby foods made without artificial additives, preservatives, or genetically modified organisms (GMOs). Organic hypoallergenic baby food, often certified by reputable regulatory agencies, is becoming a sought-after category. For instance, Serenity Kids has gained recognition for its organic baby food products that are Clean Label Project certified. Their formulas are independently tested for over 200 contaminants, ensuring they meet high safety standards. Additionally, clean-label products, which emphasize transparency about sourcing, processing, and ingredient lists, are gaining traction. These products align with consumer values of health, safety, and sustainability, further driving their demand. Manufacturers are capitalizing on this trend by introducing premium offerings that meet these criteria, creating a competitive advantage in the market.
Personalization and Functional Nutrition Offerings
The trend toward personalized nutrition is gaining momentum in the hypoallergenic baby food market. Parents increasingly seek tailored solutions to meet their child’s specific nutritional needs and sensitivities. Functional ingredients, such as probiotics, prebiotics, and omega-3 fatty acids, are being incorporated into hypoallergenic baby food to support digestion, immune health, and cognitive development. For example, NGeneBio, a Korean startup, offers personalized nutrition solutions by analyzing an infant's microbiome to tailor dietary recommendations. This innovative approach ensures that each baby receives optimal nutrients for their growth and development, marking a significant advancement in personalized infant nutrition. This trend aligns with the broader movement toward functional foods in the overall nutrition industry. Advances in data analytics and nutritional science are enabling manufacturers to offer customized products that appeal to health-conscious consumers, setting the stage for sustained growth in this segment.
Market Challenges Analysis:
High Production Costs and Premium Pricing
One of the major challenges in the hypoallergenic baby food market is the high production cost associated with developing specialized allergen-free products. Processes like extensive protein hydrolysis or the formulation of amino acid-based products require advanced technology and strict quality controls, leading to increased manufacturing expenses. Consequently, these products are often priced significantly higher than conventional baby food, limiting their affordability for middle- and low-income families. This premium pricing remains a significant barrier to widespread adoption, particularly in emerging markets where cost-sensitive consumers dominate.
Limited Awareness in Emerging Markets
While awareness of hypoallergenic baby food is steadily growing in developed regions, it remains limited in many emerging economies. Lack of education about food allergies, their risks, and the benefits of hypoallergenic solutions prevents many parents from considering these products. Additionally, cultural and regional dietary practices often dominate infant feeding choices, making it challenging for hypoallergenic baby food manufacturers to penetrate these markets. Addressing this awareness gap through targeted educational campaigns and collaborations with healthcare providers is critical for market expansion.
Regulatory and Labeling Challenges
The hypoallergenic baby food market faces strict regulatory scrutiny due to its critical role in infant nutrition. Variations in food safety standards, allergen labeling requirements, and certification processes across different regions present significant challenges for manufacturers. Ensuring compliance with diverse regulatory frameworks while maintaining product quality and cost efficiency can be complex and resource-intensive. Mislabeling or inconsistencies in product claims can also erode consumer trust, making adherence to stringent guidelines vital for market success.
Supply Chain and Ingredient Sourcing Issues
Sourcing high-quality, allergen-free raw materials remains a significant challenge for manufacturers. The complexity of supply chains, coupled with the need for rigorous testing to ensure ingredient purity, often leads to delays and increased costs. These challenges are further exacerbated by disruptions in global supply chains, such as those caused by geopolitical tensions or pandemics, which can impact production timelines and product availability.
Market Opportunities:
The hypoallergenic baby food market presents significant opportunities for growth, driven by increasing consumer demand for tailored nutritional solutions for infants with food sensitivities. Emerging markets, particularly in regions such as Asia-Pacific, Latin America, and the Middle East & Africa, offer substantial potential due to rising birth rates, improving healthcare awareness, and expanding disposable incomes. These regions are witnessing a shift toward premium baby food products as urbanization and parental education levels increase. Companies that focus on strategic market penetration, localized production, and affordable product offerings tailored to regional preferences can capitalize on the untapped demand in these markets.
Additionally, advancements in product innovation and personalization create new avenues for growth. The incorporation of functional ingredients, such as probiotics, omega-3 fatty acids, and plant-based proteins, aligns with consumer preferences for nutrition-enhancing and environmentally sustainable options. There is also a growing demand for organic and clean-label hypoallergenic baby food, which reflects evolving consumer priorities around health and transparency. The expansion of e-commerce and direct-to-consumer platforms further amplifies market opportunities by enabling broader reach and direct engagement with consumers. Companies that leverage digital channels, invest in research and development, and build strong partnerships with pediatricians and healthcare organizations are well-positioned to drive market growth and establish a competitive advantage in this dynamic industry.
Market Segmentation Analysis:
The hypoallergenic baby food market is segmented into distinct categories, addressing various consumer needs and product specifications.
By Product Type, extensively hydrolyzed formulas dominate the segment due to their proven effectiveness in managing cow's milk protein allergy (CMPA). Amino acid-based formulas serve infants with severe allergic reactions, while rice-based and soy-based formulas offer alternative protein sources for diverse dietary needs.
By Product Form, milk powder holds a significant market share due to its convenience, cost-effectiveness, and longer shelf life. However, liquid milk products are rapidly gaining traction for their ready-to-use benefits, appealing to busy parents.
By Product Origin, the organic segment is experiencing strong growth, reflecting rising consumer demand for clean-label and eco-friendly products. Conventional products, however, maintain a notable share due to their affordability and widespread availability.
By Age of the Child, the baby segment (6–12 months) leads, as parents often introduce specialized nutrition at this stage. The newborn (0–6 months) segment also holds considerable demand, particularly for infants diagnosed early with food allergies, while the toddler (1–3 years) segment is steadily growing.
By End-User, infants with cow’s milk protein allergy (CMPA) represent the largest share, as CMPA is the most common dietary intolerance in newborns. Infants with multiple food allergies form a growing segment, driving demand for highly specialized hypoallergenic solutions.
Segmentation:
By Product Type
- Extensively Hydrolyzed Formulas
- Amino Acid-Based Formulas
- Rice-Based Formulas
- Soy-Based Formulas
By product form:
- Liquid milk
- Milk powder
By product origin:
- Organic
- Conventional
By age of the child:
- Newborn
- Baby
- Toddler
By End-User
- Infants with Cow's Milk Protein Allergy (CMPA)
- Infants with Multiple Food Allergies
By region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North American hypoallergenic baby food market holds the largest share, accounting for approximately 35% of the global market. This dominance is attributed to high awareness levels about food allergies, significant disposable incomes, and a well-established healthcare infrastructure. The United States is the primary contributor to the regional market, supported by a growing preference for premium and specialized baby food products. Government initiatives, coupled with proactive campaigns by healthcare organizations to educate parents about infant allergies, have further accelerated market growth. The presence of key manufacturers and the availability of advanced products also strengthen the market in this region.
Europe follows closely, capturing around 30% of the market share. Stringent food safety regulations, coupled with a strong emphasis on organic and allergen-free products, drive growth in this region. Countries like Germany, France, and the United Kingdom lead the European market due to high consumer awareness and demand for premium hypoallergenic baby food. Additionally, the widespread acceptance of clean-label products and the willingness of parents to invest in high-quality nutrition solutions are contributing factors. Increasing collaboration between manufacturers and healthcare providers is expected to further expand the market in the coming years.
The Asia-Pacific region is projected to witness the fastest growth, with a market share of approximately 20%. Rapid urbanization, rising disposable incomes, and increasing parental awareness about infant nutrition are fueling demand in this region. Markets in China, India, and Japan are particularly dynamic, driven by high birth rates and a growing middle class seeking safe and specialized dietary solutions for infants. The expansion of e-commerce platforms and the availability of affordable hypoallergenic baby food options are additional factors propelling growth in this region.
Latin America and the Middle East & Africa collectively account for about 15% of the market. In Latin America, improving economic conditions and healthcare infrastructure, particularly in Brazil and Mexico, are driving adoption. Similarly, in the Middle East & Africa, rising awareness of infant health and increasing investments in retail distribution are key factors promoting market growth. However, limited awareness and higher product costs pose challenges in these regions, creating opportunities for manufacturers to address these gaps through affordable, localized solutions.
Key Player Analysis:
- Abbott Laboratories
- Beingmate Baby & Child Food Co., Ltd.
- Danone Nutricia
- Danone S.A.
- Earth's Best
- Enfamil USA
- Gerber Products Company
- Hain Celestial Group
- HiPP GmbH & Co. KG
- Humana-baby
- Mead Johnson Nutrition
- Natures one
- Nestle
- Parent's Choice Infant Formula
- Royal FrieslandCampina N.V.
- The Kraft Heinz Company
Competitive Analysis:
The hypoallergenic baby food market is highly competitive, with key players focusing on product innovation, strategic partnerships, and market expansion to maintain their competitive edge. Prominent companies, including Nestlé, Danone, Abbott Laboratories, and Mead Johnson Nutrition, dominate the market, leveraging their extensive product portfolios, global reach, and strong research and development capabilities. These players invest heavily in developing advanced formulations, such as extensively hydrolyzed and amino acid-based products, to cater to the growing demand for allergen-free baby food. Emerging players are increasingly emphasizing organic, plant-based, and clean-label hypoallergenic solutions to capture niche market segments. The rise of e-commerce and direct-to-consumer channels has further intensified competition, enabling smaller brands to reach consumers directly. Regional manufacturers are also gaining traction by offering affordable and localized products in emerging markets. For instance, Nestlé has automated the end-to-end production of hypoallergenic baby foods at its Biessenhofen factory in Germany, enhancing efficiency and production capacity. The industry’s competitive landscape is characterized by innovation, branding strategies, and a focus on meeting evolving consumer preferences.
Recent Developments:
- In August 2024, Abbott Laboratories expanded its Pure Bliss™ infant formula line to include organic and European-made products. The new offerings cater to specific dietary preferences, featuring organic ingredients and A2 milk, addressing the rising demand for diverse infant nutrition solutions in the U.S. market.
- On March 7, 2023, Danone launched its hypoallergenic baby formula brand, Pepticate, in the U.S. market. Designed for infants with cow’s milk allergies, the formula uses hydrolyzed proteins to enhance tolerance. This launch was strategically timed amid ongoing formula shortages, providing essential nutritional support for infants with food allergies.
- In January 2024, Reckitt/Mead Johnson Nutrition issued a voluntary recall of certain batches of Enfamil Nutramigen Hypoallergenic infant formula due to potential contamination with Cronobacter sakazakii. The recall was precautionary after tests indicated possible contamination in products distributed outside the U.S., although no related illnesses were reported.
Market Concentration & Characteristics:
The hypoallergenic baby food market is moderately concentrated, with a mix of global leaders and regional players competing to address diverse consumer needs. Established companies such as Nestlé, Danone, and Abbott Laboratories dominate the market due to their strong brand recognition, robust distribution networks, and continuous investment in research and development. These players maintain significant market share by offering a wide range of advanced formulations and leveraging economies of scale to optimize production and distribution. The market is characterized by high innovation intensity, driven by the demand for allergen-free, organic, and clean-label products. Consumer preference for transparent labeling and functional nutrition has further influenced product differentiation. While premium pricing is prevalent, smaller regional players are increasingly introducing affordable alternatives, particularly in emerging markets. The market also exhibits strong regulatory oversight, with manufacturers adhering to stringent safety standards to ensure product quality and consumer trust, shaping its competitive dynamics.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By product form, By product origin, By age of the child and By End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The hypoallergenic baby food market is poised for robust growth, driven by increasing awareness of infant food allergies globally.
- Rising demand for organic and clean-label formulations will continue to shape consumer preferences and product innovation.
- Advancements in food science will enable the development of more effective and nutritionally rich allergen-free solutions.
- Expanding e-commerce platforms will enhance product accessibility, particularly in emerging markets with growing internet penetration.
- Asia-Pacific is expected to experience the fastest growth, fueled by urbanization, rising disposable incomes, and increasing parental awareness.
- Manufacturers will increasingly focus on affordable and regionally tailored products to address unmet needs in developing economies.
- Strategic partnerships between manufacturers and healthcare providers will drive awareness and trust in hypoallergenic baby food solutions.
- Regulatory frameworks will become more stringent, emphasizing safety, transparency, and accurate labeling, influencing market dynamics.
- The integration of functional ingredients like probiotics and omega-3s will expand product offerings and cater to health-conscious parents.
- Sustainability initiatives, including plant-based and eco-friendly packaging, will gain prominence as a competitive differentiator in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the hypoallergenic baby food market?
What are the primary drivers of market growth?
Which region holds the largest market share?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hypo Anti Allergic Baby Food Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hypo Anti Allergic Baby Food Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,269.9 million → 2032: USD 4,440.77 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hypo Anti Allergic Baby Food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hypo Anti Allergic Baby Food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hypo Anti Allergic Baby Food Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hypo Anti Allergic Baby Food Market Drivers
- 3.3 Hypo Anti Allergic Baby Food Market Restraints & Challenges
- 3.4 Hypo Anti Allergic Baby Food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hypo Anti Allergic Baby Food Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hypo Anti Allergic Baby Food Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hypo Anti Allergic Baby Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hypo Anti Allergic Baby Food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Hypo Anti Allergic Baby Food Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Hypo Anti Allergic Baby Food market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hypo Anti Allergic Baby Food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hypo Anti Allergic Baby Food Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Hypo Anti Allergic Baby Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hypo Anti Allergic Baby Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Hypo Anti Allergic Baby Food Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hypo Anti Allergic Baby Food Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Hypo Anti Allergic Baby Food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hypo Anti Allergic Baby Food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hypo Anti Allergic Baby Food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hypo Anti Allergic Baby Food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hypo Anti Allergic Baby Food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hypo Anti Allergic Baby Food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hypo Anti Allergic Baby Food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
