
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
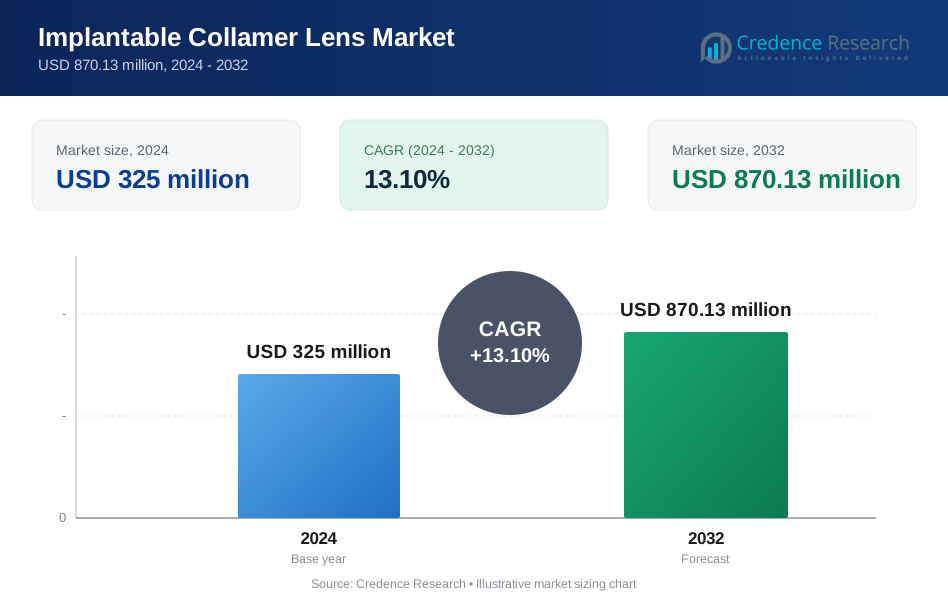
| Implantable Collamer Lens Market Size 2024 | USD 325 Million |
| Implantable Collamer Lens Market, CAGR | 13.10% |
| Implantable Collamer Lens Market Size 2032 | USD 870.13 Million |
Market Overview
The Implantable Collamer Lens market is projected to grow from USD 325 million in 2024 to USD 870.13 million by 2032, reflecting a compound annual growth rate (CAGR) of 13.10%.
The Implantable Collamer Lens (ICL) market is driven by increasing prevalence of myopia and astigmatism, coupled with growing patient preference for minimally invasive corrective procedures. Technological advancements in lens design and the rising acceptance of vision correction surgeries enhance market growth. Additionally, heightened awareness campaigns by healthcare providers about the benefits and safety of ICLs contribute to the market's expansion. The trend towards personalized medical devices also supports the adoption of tailored ICL solutions, further propelling the market forward.
The Implantable Collamer Lens (ICL) market demonstrates significant geographical diversity, with North America and Asia-Pacific being the leading regions, collectively holding over 55% of the global market share. North America benefits from advanced healthcare infrastructure and high patient awareness, while Asia-Pacific is experiencing rapid growth due to rising disposable incomes and expanding healthcare facilities. Key players driving the market include Carl Zeiss Meditec, Bausch + Lomb, Alcon, STAAR Surgical, and Johnson & Johnson, all of whom are continuously innovating and expanding their global presence to meet the increasing demand for advanced vision correction solutions.
Market Drivers
Rising Prevalence of Refractive Errors
The Implantable Collamer Lens (ICL) market is significantly influenced by the increasing occurrence of refractive errors globally. Nearsightedness, or myopia, remains the most common condition, affecting a substantial portion of the population. For instance, more than 11 million Americans have common vision problems that can be corrected with prescriptive eyewear. Furthermore, other conditions like astigmatism, which causes blurred or distorted vision, and hyperopia or farsightedness, are prevalent. Presbyopia, an age-related condition marked by difficulty in reading small print, also contributes to the growing demand for effective corrective solutions like ICLs.
Technological Advancements in ICL
Recent advancements in ICL technology have notably enhanced the biocompatibility of these lenses, reducing potential complications and improving overall patient outcomes. For instance, a study published in PLOS ONE in 2024 showed that vertical implantation of a toric implantable collamer lens (ICL) showed good rotational stability, and appropriate visual acuity correction results with relatively low vaulting. These modern ICLs offer superior visual quality, including sharper night vision and minimized glare, attributes that are increasingly valued by patients. Additionally, the ability to customize these lenses to fit individual vision correction needs ensures that more patients can achieve optimal results from their procedures.
Preference for Permanent Solutions
ICLs are becoming a favored option for those seeking permanent vision correction solutions, providing an attractive alternative to traditional glasses and contact lenses. This shift is largely due to the improved quality of life ICLs offer, particularly for individuals with high refractive errors or those who find traditional vision aids inconvenient. The permanence of ICLs eliminates the ongoing costs and maintenance associated with other corrective options, making them a cost-effective solution in the long term.
Expanded Access and Economic Factors
The expansion of specialized ophthalmic clinics and advancements in surgical techniques have made ICL procedures more accessible and safer, fueling market growth. Economically, rising disposable incomes have allowed more individuals to consider elective procedures like ICL surgery. Additionally, the integration of ICL procedures into health insurance plans in some regions has made these surgeries more accessible to a broader audience, further driving market expansion.
Market Trends
Expanding Market Reach and Technological Advancements
The Implantable Collamer Lens (ICL) market is witnessing significant expansion in emerging markets, driven by enhanced healthcare infrastructure and rising awareness of the benefits of ICLs. Efforts to increase affordability through government subsidies and various financing options are making these advanced corrective procedures more accessible, thereby broadening the market base. Concurrently, technological advancements continue to evolve, with newer ICLs featuring smaller, more discreet designs that improve both patient comfort and aesthetic appeal. The commitment to ongoing research and development is also yielding lenses with improved visual outcomes, such as enhanced night vision and reduced glare, catering to the increasing demand for high-quality vision correction.
Broadening Indications and Emphasizing Patient-Centric Approaches
ICL technology is exploring broader clinical applications, including the treatment of presbyopia. This development is particularly promising as it offers a potential single-surgery solution for correcting both near and distant vision challenges, thus expanding the scope of treatable conditions. ICL technology is expanding to address a wider range of vision correction needs. For instance, the global prevalence of diabetes, which can affect eye health, is estimated at 10.5% of adults and is projected to grow to more than 12% by 2045. This trend may increase the potential patient base for ICLs. Additionally, there is a significant population of approximately 1.4 billion people worldwide who suffer from symptoms of dry eye without clinical signs, and over 750 million people who have both symptoms and clinical signs of dry eye. These conditions may influence patients' choices for vision correction, potentially favoring ICLs over traditional contact lenses. The long-term cost-effectiveness of ICLs, despite higher initial surgery costs, continues to attract a wider audience. Additionally, enhanced surgical techniques and a strong focus on post-operative care are pivotal in improving patient safety and satisfaction, ensuring optimal outcomes and bolstering patient confidence in ICL procedures.
Market Challenges Analysis
Surgical Challenges and Post-Operative Complications
The Implantable Collamer Lens (ICL) market faces significant challenges related to surgical risks and post-operative complications that can impact patient outcomes. Serious infections such as endophthalmitis pose risks of severe vision loss, while increased intraocular pressure can precipitate glaucoma. For instance, data from a government health authority survey indicates that serious infections such as endophthalmitis occur in approximately 0.02% of ICL procedures, posing risks of severe vision loss. Additionally, ICLs have been associated with an elevated risk of cataract formation over time. Dislocation of the lens is another concern, which may necessitate further surgical intervention to correct. Post-operatively, patients might experience visual fluctuations or discomfort, along with symptoms of dry eye syndrome, which are common but can diminish satisfaction and overall quality of life following the surgery. These challenges necessitate meticulous surgical planning and patient management to minimize risks and enhance recovery.
Economic and Competitive Pressures
High costs associated with ICL surgery present a substantial barrier to wider adoption. While some insurance plans offer coverage for these procedures, the extent and availability of such coverage can vary greatly, affecting patient accessibility. Furthermore, the long-term outcomes of ICL surgeries are still under scrutiny as durability and visual results over extended periods are being evaluated, which can influence both patient and practitioner confidence in this technology. Regulatory hurdles also pose significant delays and financial burdens on manufacturers aiming to bring new ICL models to market. Competition from other vision correction methods, such as LASIK, PRK, and more traditional solutions like glasses and contact lenses, continues to challenge the ICL market. These traditional and surgical alternatives often offer lower cost and well-established outcomes, appealing to a broad segment of potential patients. Additionally, strict eligibility criteria for ICL surgery ensure that not all patients are suitable candidates, further narrowing the market potential and necessitating comprehensive pre-operative evaluations to ensure optimal patient selection and safety.
Market Segmentation Analysis:
By Indication:
The Implantable Collamer Lens (ICL) market is segmented by indications, primarily focusing on correcting conditions such as myopia (nearsightedness), hyperopia (farsightedness), and astigmatism. Myopia represents a significant segment due to its high prevalence globally, driving the demand for effective corrective solutions. Astigmatism, characterized by irregular corneal shapes leading to blurred vision, also substantially contributes to market growth as patients seek precise and permanent corrective procedures. Hyperopia, though slightly less prevalent, still generates notable demand for ICLs as the global population ages, increasing the incidence of this condition. These indications highlight the extensive need for advanced, minimally invasive solutions that ICLs offer, catering to a diverse range of refractive errors.
By End User:
On the end-user front, the ICL market is distinctly categorized into hospitals, ophthalmic clinics, ambulatory surgical centers, and eye research institutes. Hospitals and ophthalmic clinics form the largest segments due to their extensive infrastructure and patient volume, providing numerous opportunities for ICL procedures. Ambulatory surgical centers are rapidly growing in popularity due to their cost-effectiveness and shorter patient wait times. Meanwhile, eye research institutes play a crucial role in advancing ICL technology through continuous research and clinical trials, enhancing the safety and efficacy of the lenses. This segmentation illustrates the diverse settings in which ICLs are utilized, each contributing uniquely to the market's expansion and evolution.
Segments:
Based on Indication:
- Myopia
- Hyperopia
- Astigmatism
Based on End User:
- Hospitals
- Ophthalmic Clinics
- Ambulatory Surgical Centers
- Eye Research Institutes
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
In North America, the Implantable Collamer Lens (ICL) market holds a significant market share, estimated at around 30% of the global market. This dominance is driven by advanced healthcare infrastructure, high healthcare spending, and a strong focus on aesthetic and corrective vision procedures. The region benefits from a robust presence of leading ophthalmic clinics and surgeons, complemented by a well-established regulatory framework that facilitates the rapid adoption of innovative medical devices. For instance, a government health authority report indicates that there are approximately 19,000 practicing ophthalmologists in the United States alone, providing a strong foundation for ICL procedures. The prevalence of refractive errors, such as myopia and astigmatism, continues to rise among the North American population, further fuelling the demand for ICLs. Additionally, awareness campaigns and educational programs enhance understanding and acceptance of ICLs, supported by comprehensive insurance coverage that often includes elective vision correction procedures.
Asia-Pacific
The Asia-Pacific region is rapidly emerging as a key player in the Implantable Collamer Lens market, currently holding approximately 25% of the global market share. This growth is primarily fueled by increasing disposable incomes, rising healthcare expenditures, and a burgeoning awareness of advanced vision correction technologies. China and India are pivotal to this expansion, given their large populations and growing incidence of refractive errors. The market's expansion is further supported by improvements in healthcare infrastructure and an increasing number of specialized ophthalmic clinics and hospitals. Government initiatives across the region promote healthcare advancements, including vision correction technologies, thereby enhancing market growth. As more patients in Asia-Pacific opt for ICLs over traditional corrective methods, the region is expected to continue its rapid growth trajectory, potentially increasing its market share in the coming years.
Key Player Analysis
- Carl Zeiss Meditec
- Bausch + Lomb
- Alcon
- STAAR Surgical
- Johnson & Johnson
Competitive Analysis
The competitive landscape of the Implantable Collamer Lens (ICL) market is characterized by the strong presence of leading players such as Carl Zeiss Meditec, Bausch + Lomb, Alcon, STAAR Surgical, and Johnson & Johnson. Market leaders are striving to expand their global reach and capture larger shares through specialized product offerings. The competition is further intensified by significant investments in research and development aimed at introducing advanced ICL models that address a broader range of refractive errors. Additionally, companies are leveraging their extensive distribution networks and ophthalmic expertise to maintain a competitive edge, driving continuous advancements in the market.
Recent Developments
- In March 2024, STAAR Surgical Company, a leading manufacturer, developer and marketer of Implantable Collamer Lenses (ECL) for myopia, presbyopia, and astigmatism, declared the sale of three million lenses worldwide.
- In April 2024, Carl Zeiss Meditec AG completed the acquisition of D.O.R.C. (Dutch Ophthalmic Research Center), which enhances and complements ZEISS Medical Technology’s broad ophthalmic portfolio.
- In February 2024, Carl Zeiss Meditec AG reached a favorable resolution with Topcon to settle its lawsuit against the Japanese company’s U.S.-based subsidiaries.
- In March 2022, STAAR Surgical announced that the U.S. Food and Drug Administration (FDA) has granted approval of the EVO/EVO+ Visian Implantable Collamer Lens for the correction of myopia and myopia with astigmatism.
Market Concentration & Characteristics
The Implantable Collamer Lens (ICL) market is characterized by moderate to high market concentration, with a few key players dominating the industry. These leading companies possess significant market share due to their established reputations, extensive distribution networks, and strong focus on innovation. The market's concentration is further reinforced by the high barriers to entry, including the need for advanced technological expertise, rigorous regulatory approvals, and substantial capital investments. Additionally, the market exhibits characteristics of rapid technological advancements and a strong emphasis on product differentiation, with companies continually striving to improve the safety, effectiveness, and customization options of ICLs. Despite the concentration, the market remains dynamic, driven by ongoing research and development, as well as growing demand for advanced vision correction solutions across various global regions. This competitive environment encourages continuous innovation and high-quality standards, benefiting both the market and end-users.
Report Coverage
The research report offers an in-depth analysis based on Indication, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Implantable Collamer Lens market is expected to experience steady growth due to increasing prevalence of refractive errors globally.
- Advances in lens technology will continue to improve visual outcomes and patient satisfaction.
- Emerging markets in Asia-Pacific will drive significant demand as healthcare infrastructure improves and awareness increases.
- The growing preference for permanent vision correction solutions will boost the adoption of ICLs over traditional methods.
- Regulatory approvals for new ICL models will expand market offerings and enhance competitiveness.
- Insurance coverage expansion will make ICL procedures more accessible to a broader population.
- Technological innovations will lead to more customizable and biocompatible ICLs, attracting a wider patient base.
- The market will see increased competition from alternative vision correction methods, such as LASIK and PRK.
- Continuous investment in research and development will drive the introduction of advanced ICL products.
- The market is likely to benefit from rising disposable incomes, particularly in developing regions, enhancing overall market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Implantable Collamer Lens Market?
What factors are driving the growth of the Implantable Collamer Lens Market?
What are the key segments within the Implantable Collamer Lens Market?
What are some challenges faced by the Implantable Collamer Lens Market?
Who are the major players in the Implantable Collamer Lens Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Implantable Collamer Lens Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Implantable Collamer Lens Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 325 million → 2032: USD 870.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Implantable Collamer Lens Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Implantable Collamer Lens Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Implantable Collamer Lens Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Implantable Collamer Lens Market Drivers
- 3.3 Implantable Collamer Lens Market Restraints & Challenges
- 3.4 Implantable Collamer Lens Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Implantable Collamer Lens Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Implantable Collamer Lens Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Implantable Collamer Lens category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Implantable Collamer Lens Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Implantable Collamer Lens Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Implantable Collamer Lens market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Implantable Collamer Lens Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Implantable Collamer Lens Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Implantable Collamer Lens Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Implantable Collamer Lens (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Implantable Collamer Lens Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Implantable Collamer Lens Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Implantable Collamer Lens Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Implantable Collamer Lens Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Implantable Collamer Lens Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Implantable Collamer Lens Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Implantable Collamer Lens Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Implantable Collamer Lens Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Implantable Collamer Lens Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
