
Market Overview:
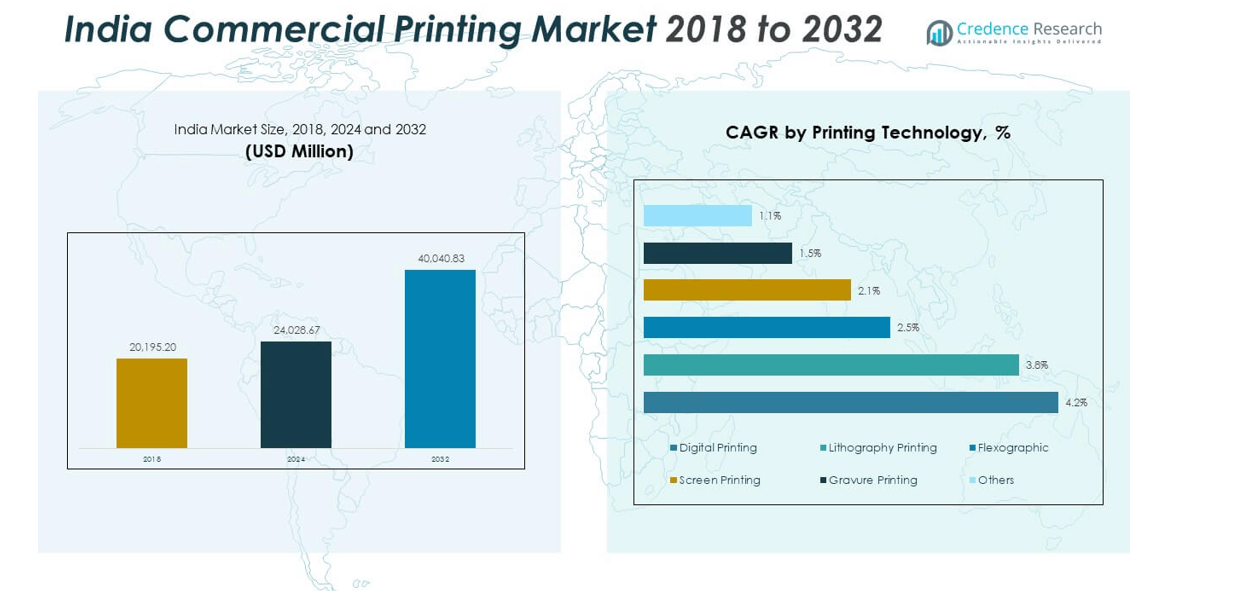
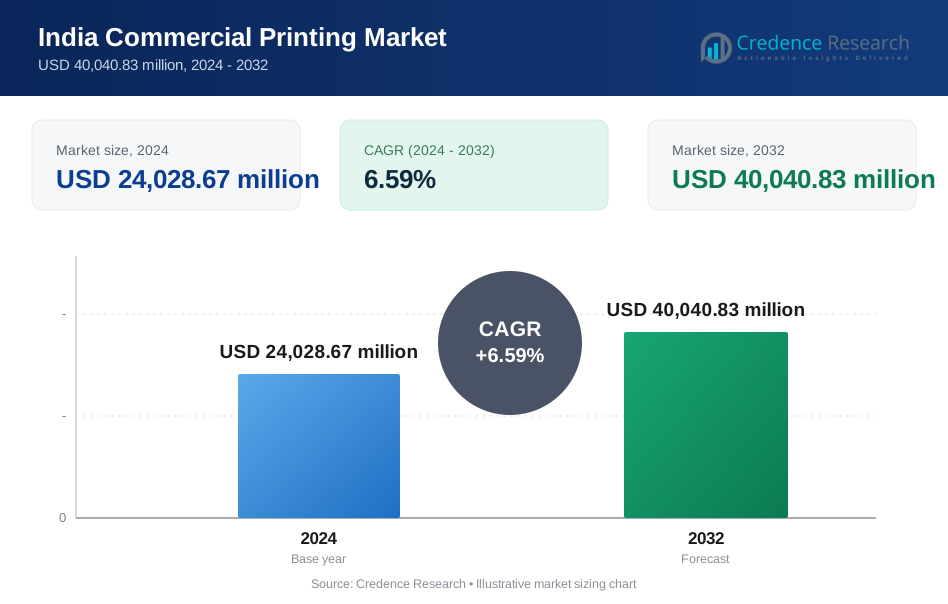
The India Commercial Printing Market size was valued at USD 20,195.20 million in 2018, reached USD 24,028.67 million in 2024, and is anticipated to attain USD 40,040.83 million by 2032, at a CAGR of 6.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Commercial Printing Market Size 2024 | USD 24,028.67 million |
| India Commercial Printing Market, CAGR | 6.59% |
| India Commercial Printing Market Size 2032 | USD 40,040.83 million |
Growth in advertising, retail, and packaging sectors drives consistent demand for commercial printing. Expanding e-commerce activities and rising brand promotions push businesses toward high-quality printed materials. The adoption of digital printing technology enhances speed, flexibility, and customization. Corporate demand for brochures, catalogs, and marketing collateral continues to rise. Sustainability trends promote the use of eco-friendly inks and recyclable substrates. These factors collectively strengthen market performance across urban and semi-urban zones.
South India leads the market due to strong demand from packaging and IT-related industries in cities such as Bengaluru, Chennai, and Hyderabad. Western India follows with a robust presence in commercial advertising and FMCG packaging across Mumbai and Pune. Northern India contributes significantly through educational publishing and government documentation. Eastern and northeastern regions are emerging with growing e-commerce and retail networks. Central India shows gradual expansion supported by small-scale enterprises and improved infrastructure. Each subregion’s contribution enhances the market’s overall growth momentum across the country.
Market Insights
- The India Commercial Printing Market was valued at USD 20,195.20 million in 2018, reached USD 24,028.67 million in 2024, and is projected to attain USD 40,040.83 million by 2032, expanding at a CAGR of 6.59% during 2024–2032.
- South India holds the highest market share at 30%, led by advanced packaging, IT, and retail printing in cities like Bengaluru, Chennai, and Hyderabad. Western India follows with 27%, driven by FMCG and advertising sectors in Mumbai and Pune.
- Northern India captures 25% share, sustained by strong educational publishing and public sector printing activities across Delhi and Uttar Pradesh.
- Eastern and Northeastern regions collectively hold 15% share but are the fastest-growing territories, supported by rising e-commerce penetration and regional retail investments.
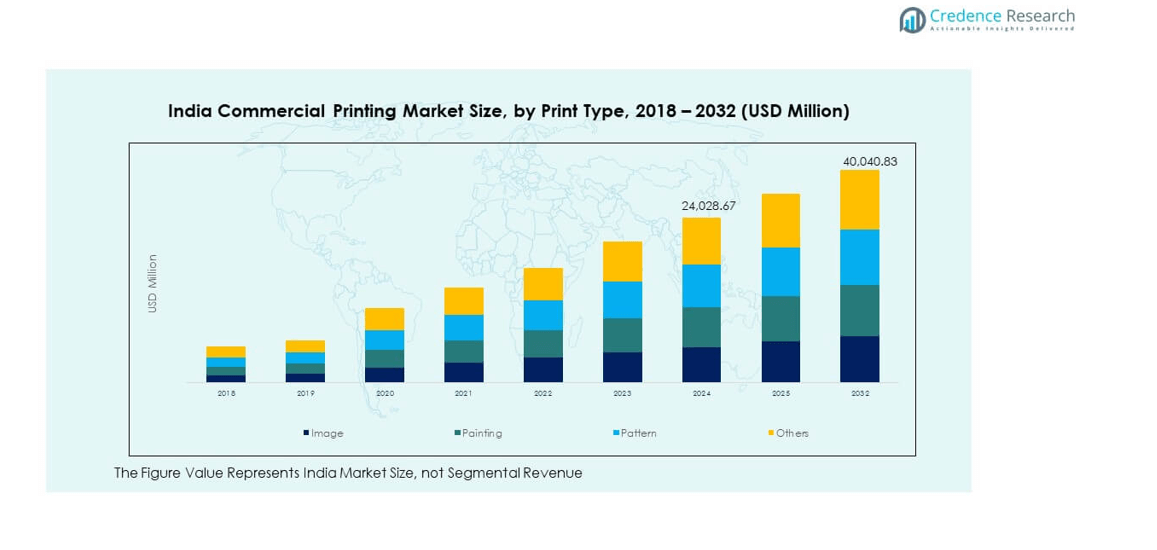
- In segment share distribution, image printing accounts for the largest portion at around 35%, followed by pattern printing near 28%, reflecting rising demand for advertising visuals and packaging design applications.
Market Drivers
Expanding Packaging and E-Commerce Demand Drives Print Volumes
The India Commercial Printing Market benefits from rising packaging consumption across retail and e-commerce sectors. Online marketplaces use printed boxes, labels, and inserts to boost brand recall. FMCG companies invest in high-quality flexible and corrugated packaging to meet growing consumer expectations. It gains traction from packaging converters that integrate short-run digital printing to manage seasonal demand. Variable data technology supports custom designs and localized campaigns. The rapid rise in online retail accelerates print orders for secondary and tertiary packaging. SMEs adopt cost-effective print solutions for promotional packaging. Increased use of recyclable substrates drives sustainable print growth.
Corporate Branding and Marketing Investments Bolster Print Demand
Corporate organizations spend more on visual branding across brochures, catalogues, and event materials. The India Commercial Printing Market sees steady demand from enterprises using print for trade shows and direct mail campaigns. Companies value tangible print materials to enhance client engagement and recall. It gains momentum from hybrid marketing that blends print and digital outreach. Offset and digital printers benefit from steady corporate contracts that ensure consistent revenue. Banks and insurance firms rely on secure transactional printing for statements and policy documents. Strong demand from brand identity projects fuels business expansion for mid-sized printing firms. The trend enhances long-term partnerships between service providers and enterprises.
Technological Advancements Improve Print Quality and Turnaround
The adoption of digital and hybrid presses transforms printing speed, precision, and cost-efficiency. The India Commercial Printing Market leverages inkjet and electrophotographic systems to meet short-run, on-demand jobs. Automated workflows enable real-time monitoring and minimize setup delays. It benefits from new color management tools that ensure consistent output across media. Print providers deploy software for variable data handling to serve personalized campaigns. Energy-efficient printing machines reduce operational expenses and carbon footprint. Integration of UV-curable inks boosts durability across signage and packaging. These developments enhance service differentiation in a highly competitive market.
- For instance, Canon India’s imagePRESS V1000 digital press introduced in 2025 at Print Expo Chennai supports up to 10,000-sheet feeding and handles thick coated papers, enhancing uptime and media versatility for commercial printers.
Government Initiatives and Urbanization Strengthen Industry Expansion
Public infrastructure projects, smart city programs, and educational drives increase print requirements nationwide. The India Commercial Printing Market experiences rising orders from educational publishing and government documentation. Urbanization boosts demand for advertising materials and outdoor signage. It benefits from skill development initiatives that strengthen the workforce in printing clusters. Government procurement of printed forms, manuals, and communication materials sustains consistent contracts. Public campaigns on health and social awareness expand large-format printing demand. Regional policies promoting MSME development encourage investment in new print facilities. This ecosystem reinforces the long-term resilience of the industry.
- For instance, the National Skill Development Corporation (NSDC) supports training programs in printing and packaging through its allied skill councils under initiatives like Pradhan Mantri Kaushal Vikas Yojana (PMKVY), helping enhance technical capabilities and workforce readiness across India’s commercial printing sector.
Market Trends
Rising Adoption of Digital Printing for On-Demand Production
The India Commercial Printing Market witnesses a rapid shift toward digital presses driven by low setup time and flexibility. Digital printing enables customized short runs with reduced waste. It supports fast-changing marketing cycles and localized promotions. Print firms adopt cloud-based job management for streamlined workflows. Integration of digital front-end systems ensures color consistency across multiple print media. The shift reduces material inventory needs while improving cost control. Businesses also prefer digital platforms for variable content marketing. These factors strengthen the dominance of digital printing in urban centers.
Integration of Sustainable and Eco-Friendly Print Practices
Growing environmental awareness drives adoption of green printing processes. The India Commercial Printing Market benefits from investments in water-based and soy-based inks. Print houses use recycled paper, energy-efficient presses, and low-VOC materials. Clients prioritize sustainability certification in vendor selection. It pushes printers to upgrade facilities for waste management and carbon reduction. Demand for biodegradable packaging materials continues to grow. Brands use eco-labels and minimalistic designs to align with green values. Sustainability becomes a key differentiator in competitive bids for large accounts.
- For instance, ITC’s Printing and Packaging Division (PSPD) operates FSC-certified manufacturing units and has adopted water-based and low-VOC inks, aligning with its corporate sustainability strategy to reduce environmental impact across packaging and print operations.
Growth of Print Automation and Cloud-Based Production Management
Automation reshapes print production through AI-driven scheduling and predictive maintenance. The India Commercial Printing Market integrates cloud solutions that centralize file management and proofing. Real-time monitoring enhances accuracy and turnaround times. It improves collaboration across multiple print sites. Robotic material handling reduces manual intervention and boosts safety. Workflow software enables seamless order tracking and billing. These tools allow printers to scale operations efficiently. The shift toward smart production lines improves margins and reliability for large print networks.
Expansion of Hybrid and Specialty Printing for Niche Segments
The demand for specialty finishes such as embossing, foiling, and 3D effects rises across premium print categories. The India Commercial Printing Market gains traction from luxury packaging and high-end marketing materials. Print providers combine offset and digital capabilities for hybrid print jobs. It helps brands create eye-catching materials for limited-edition campaigns. Growth in décor and textile printing adds new revenue channels. Industrial inkjet applications extend across ceramics and signage. This diversification supports higher margins and long-term growth opportunities for advanced print shops.
- For instance, Fujifilm India unveiled its Revoria Press series at PrintPack 2025, offering specialty color management and metallic finish options, enabling luxury packaging printers to achieve over 2,400 dpi quality and advanced embellishment control.
Market Challenges Analysis
Rising Raw Material Prices and Supply Chain Constraints Impact Profitability
The India Commercial Printing Market faces pressure from fluctuating costs of paper, ink, and chemicals. Import dependence for specialty substrates adds risk during currency fluctuations. It struggles with inconsistent supply of coated papers and polymers. High logistics costs increase production expenses for regional printers. SMEs find it hard to absorb cost increases without raising client prices. Power supply fluctuations and fuel costs add to operational challenges. Global pulp shortages cause longer lead times for raw material procurement. Maintaining price competitiveness while ensuring quality becomes a key challenge for market players.
Digital Substitution and Shifting Media Preferences Reduce Print Volumes
The rise of digital advertising and online media continues to challenge traditional printing segments. The India Commercial Printing Market experiences volume decline in magazines, newspapers, and office documents. Clients move toward digital communication to reduce environmental impact and costs. It compels printers to reposition services toward value-added solutions. Educational institutions adopt e-learning platforms reducing textbook printing. Corporate clients favor online brochures and digital signatures. Maintaining relevance in a digital-first landscape requires continuous innovation. Balancing print relevance with new media integration remains a long-term industry challenge.
Market Opportunities
Expanding Scope for Value-Added and Personalized Printing Services
Growing demand for customized promotional materials creates opportunities for service differentiation. The India Commercial Printing Market can capitalize on variable-data, short-run, and personalized printing. Retail brands invest in event-specific campaigns that need high design flexibility. It allows printers to offer packaging prototypes and personalized marketing kits. Integration of AR and QR technologies enhances interactivity. Enterprises seek print solutions linked to digital engagement platforms. Rising luxury packaging and premium labeling markets open space for niche high-margin segments.
Strong Growth Potential Across Tier-II and Tier-III Cities
Emerging cities represent the next wave of print industry expansion. The India Commercial Printing Market gains traction from retail growth and rising disposable incomes in smaller urban clusters. It supports regional packaging hubs and localized print distribution. Educational institutions and government programs in these areas boost publishing demand. Better logistics and industrial parks enable cost-effective setup of new print facilities. The market expansion toward these cities improves competitiveness and nationwide coverage for large print service networks.
Market Segmentation Analysis
By Printing Technology
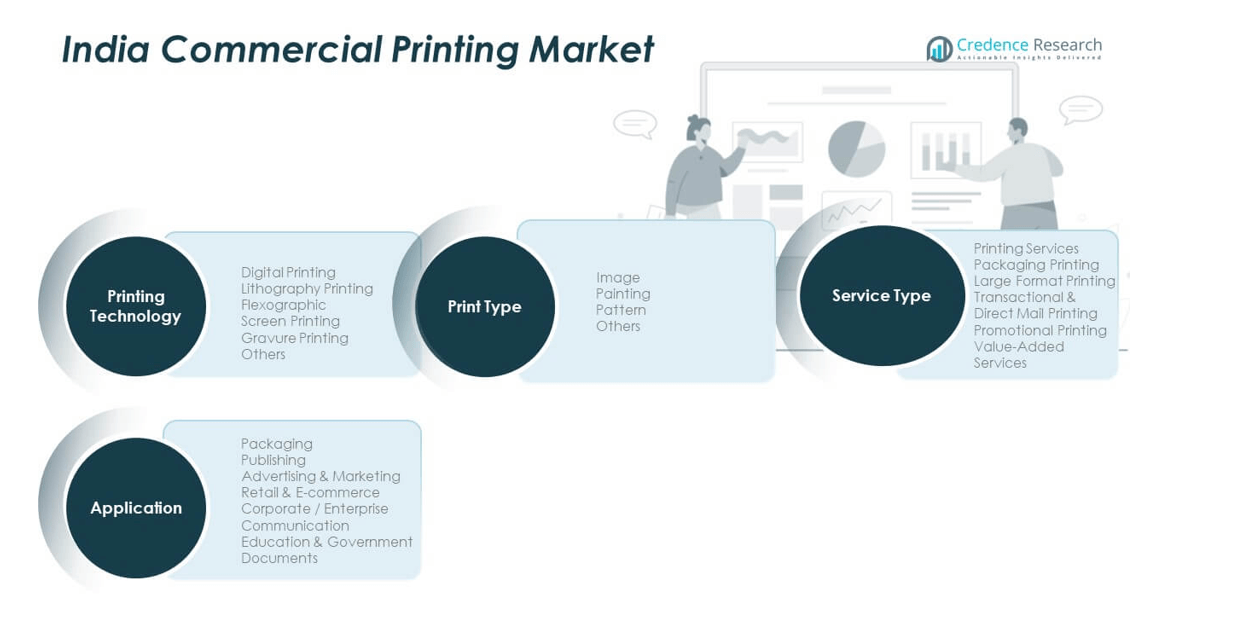
The India Commercial Printing Market covers digital, lithography, flexographic, screen, gravure, and other printing methods. Digital printing dominates due to short-run flexibility and fast turnaround. Lithography maintains relevance in bulk commercial applications. Flexographic and gravure printing lead in packaging due to high-quality color output. Screen printing remains key in textiles and signage. Each technology caters to specific production needs, driving diverse investment patterns.
By Application
Key applications include packaging, publishing, advertising, retail, corporate communication, and education. The India Commercial Printing Market sees packaging as the largest segment driven by FMCG and e-commerce. Publishing sustains steady demand from educational institutions. Advertising and retail sectors push short-run jobs and promotional prints. Corporate clients depend on transactional and marketing materials for branding.
- For instance, Parksons Packaging operates eight advanced print facilities across India with multi-process offset and flexographic lines, supporting major FMCG and personal care brands through customized folding carton and label printing solutions.
By Service Type
Printing services range from packaging and large format to transactional, promotional, and value-added services. The India Commercial Printing Market benefits from increased demand for packaging printing with brand differentiation. Large format and promotional printing grow through outdoor advertising and events. Transactional printing remains relevant in finance and telecom sectors. Value-added services like finishing and personalization provide competitive advantages.
By Print Type
Print types include image, painting, pattern, and others. The India Commercial Printing Market uses image and pattern printing widely in advertising and décor. Artistic and creative print jobs find demand in customized gifting and retail. Pattern printing supports textile and interior applications. This diversity strengthens the sector’s adaptability to new consumer trends.
- For instance, HP India’s Latex 700 and 800 printer series support high-resolution fabric and wallpaper printing up to 1,200 dpi, helping design studios and décor firms expand into pattern-based interior applications with eco-certified water-based inks.
Segmentation
By Printing Technology:
- Digital Printing
- Lithography Printing
- Flexographic Printing
- Screen Printing
- Gravure Printing
- Others
By Application:
- Packaging
- Publishing
- Advertising & Marketing
- Retail & E-commerce
- Corporate / Enterprise Communication
- Education & Government Documents
By Service Type:
- Printing Services
- Packaging Printing
- Large Format Printing
- Transactional & Direct Mail Printing
- Promotional Printing
- Value-Added Services
By Print Type:
- Image
- Painting
- Pattern
- Others
Regional Analysis
The India Commercial Printing Market shows distinct regional concentration across India. The South region accounts for roughly 30 % of total market share. The West region holds close to 27 %. The North region contributes about 25 %. The East and North-East region share near 15 %, while Central India covers around 3 %. These shares reflect established industrial zones and urban demand centres.
South India leads due to strong retail growth, expanding e-commerce, and thriving IT and packaging sectors in cities like Bengaluru, Hyderabad and Chennai. Printers in this region benefit from consistent demand for packaging, labels and corporate materials. It draws large printing houses owing to available infrastructure and stable power supply. The West region records robust demand from Mumbai and Pune, driven by advertising, film-industry print collateral, and FMCG packaging needs. It attracts investment because of logistics networks and proximity to ports.
The North region sees steady demand from educational publishing houses and government documentation projects. Printers there rely on demand from populous states and institutional printing jobs. It faces competition from digital media but retains strength through textbooks and legal document printing. The East and North-East record gradual growth led by regional retail expansion and rising e-commerce penetration. It shows potential for future growth once infrastructure improves. Central India remains under-penetrated but slowly gains ground via regional retail and governmental contracts.
Key Player Analysis
- Thomson Press
- Parksons Graphics
- Hindustan Press
- Multivista Global
- Nutech Print Services
- Printech India
- Manipal Technologies
- ITC Print & Packaging (ITC PSPD)
- MPS Limited
Competitive Analysis
The India Commercial Printing Market features a mix of large national players and mid-size regional firms that compete on quality, turnaround time and service breadth. Major firms leverage state-of-the-art digital, flexographic and hybrid presses to offer packaging, corporate, and large-format printing. These players operate multiple facilities across regions to meet diverse demand quickly. It allows them to achieve economies of scale and cross-region delivery capabilities. Regional printers focus on rapid service for nearby clients. They offer personalized services, short-run digital jobs and competitive pricing to capture small and medium enterprises. Some specialise in niche services such as security printing, variable data printing or eco-friendly substrate procurement. These niches help them differentiate from larger rivals. Pricing pressure from regional competitors forces national players to improve efficiency and adopt automation. Some printers form alliances with packaging converters or logistics firms to broaden their service scope. Competition drives continuous equipment upgrades and process optimisation industry-wide.
Recent Developments
- In July 2025, Canon India launched an upgraded version of its imagePRESS V1000 digital press featuring a new vacuum paper feeding deck at Print Expo Chennai, enhancing efficiency for high-volume commercial printing with support for up to 10,000 sheets and thick coated papers.
- In February 2025, Print Plus signed a deal with Bindwel Technologies to acquire the advanced Bindline bookbinding system at PrintPack 2025, incorporating features like the Signa Gatherer and Freedom 5K perfect binder to boost production capabilities for book printing and exports.
- In February 2025, FUJIFILM India unveiled next-generation printing solutions, including the Revoria series, in its graphic communications portfolio at PrintPack India 2025, targeting advancements in commercial and packaging print applications.
Report Coverage
The research report offers an in-depth analysis based on Printing Technology, Application, Service Type and Print Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook
- The India Commercial Printing Market will expand through sustained demand in packaging, retail, and corporate sectors.
- Digital printing will continue to dominate due to fast turnaround and personalization capabilities.
- Hybrid presses combining offset and digital functions will gain traction for short-run premium work.
- Automation and workflow integration will enhance operational efficiency for print houses nationwide.
- Sustainability will remain a strategic focus with greater use of recyclable substrates and green inks.
- E-commerce growth will elevate demand for printed packaging and logistics materials.
- Tier-II and Tier-III cities will emerge as new growth centers driven by retail and education sectors.
- Corporate branding and variable-data print campaigns will strengthen enterprise-driven print volumes.
- Technological advancements in color management and UV-curable systems will elevate print quality.
- Industry consolidation through mergers and partnerships will help firms expand service capacity and geographic reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Commercial Printing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Commercial Printing Market projected to grow between 2024 and 2032?
Which India Commercial Printing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Commercial Printing Market?
Who are the leading companies in the India Commercial Printing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24,028.67 million → 2032: USD 40,040.83 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Commercial Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Commercial Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Commercial Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Commercial Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Commercial Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Commercial Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Commercial Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Commercial Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24,028.67 million → 2032: USD 40,040.83 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Commercial Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 India Commercial Printing Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Commercial Printing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Commercial Printing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

