
Vehicle plants and refineries set sealing demand
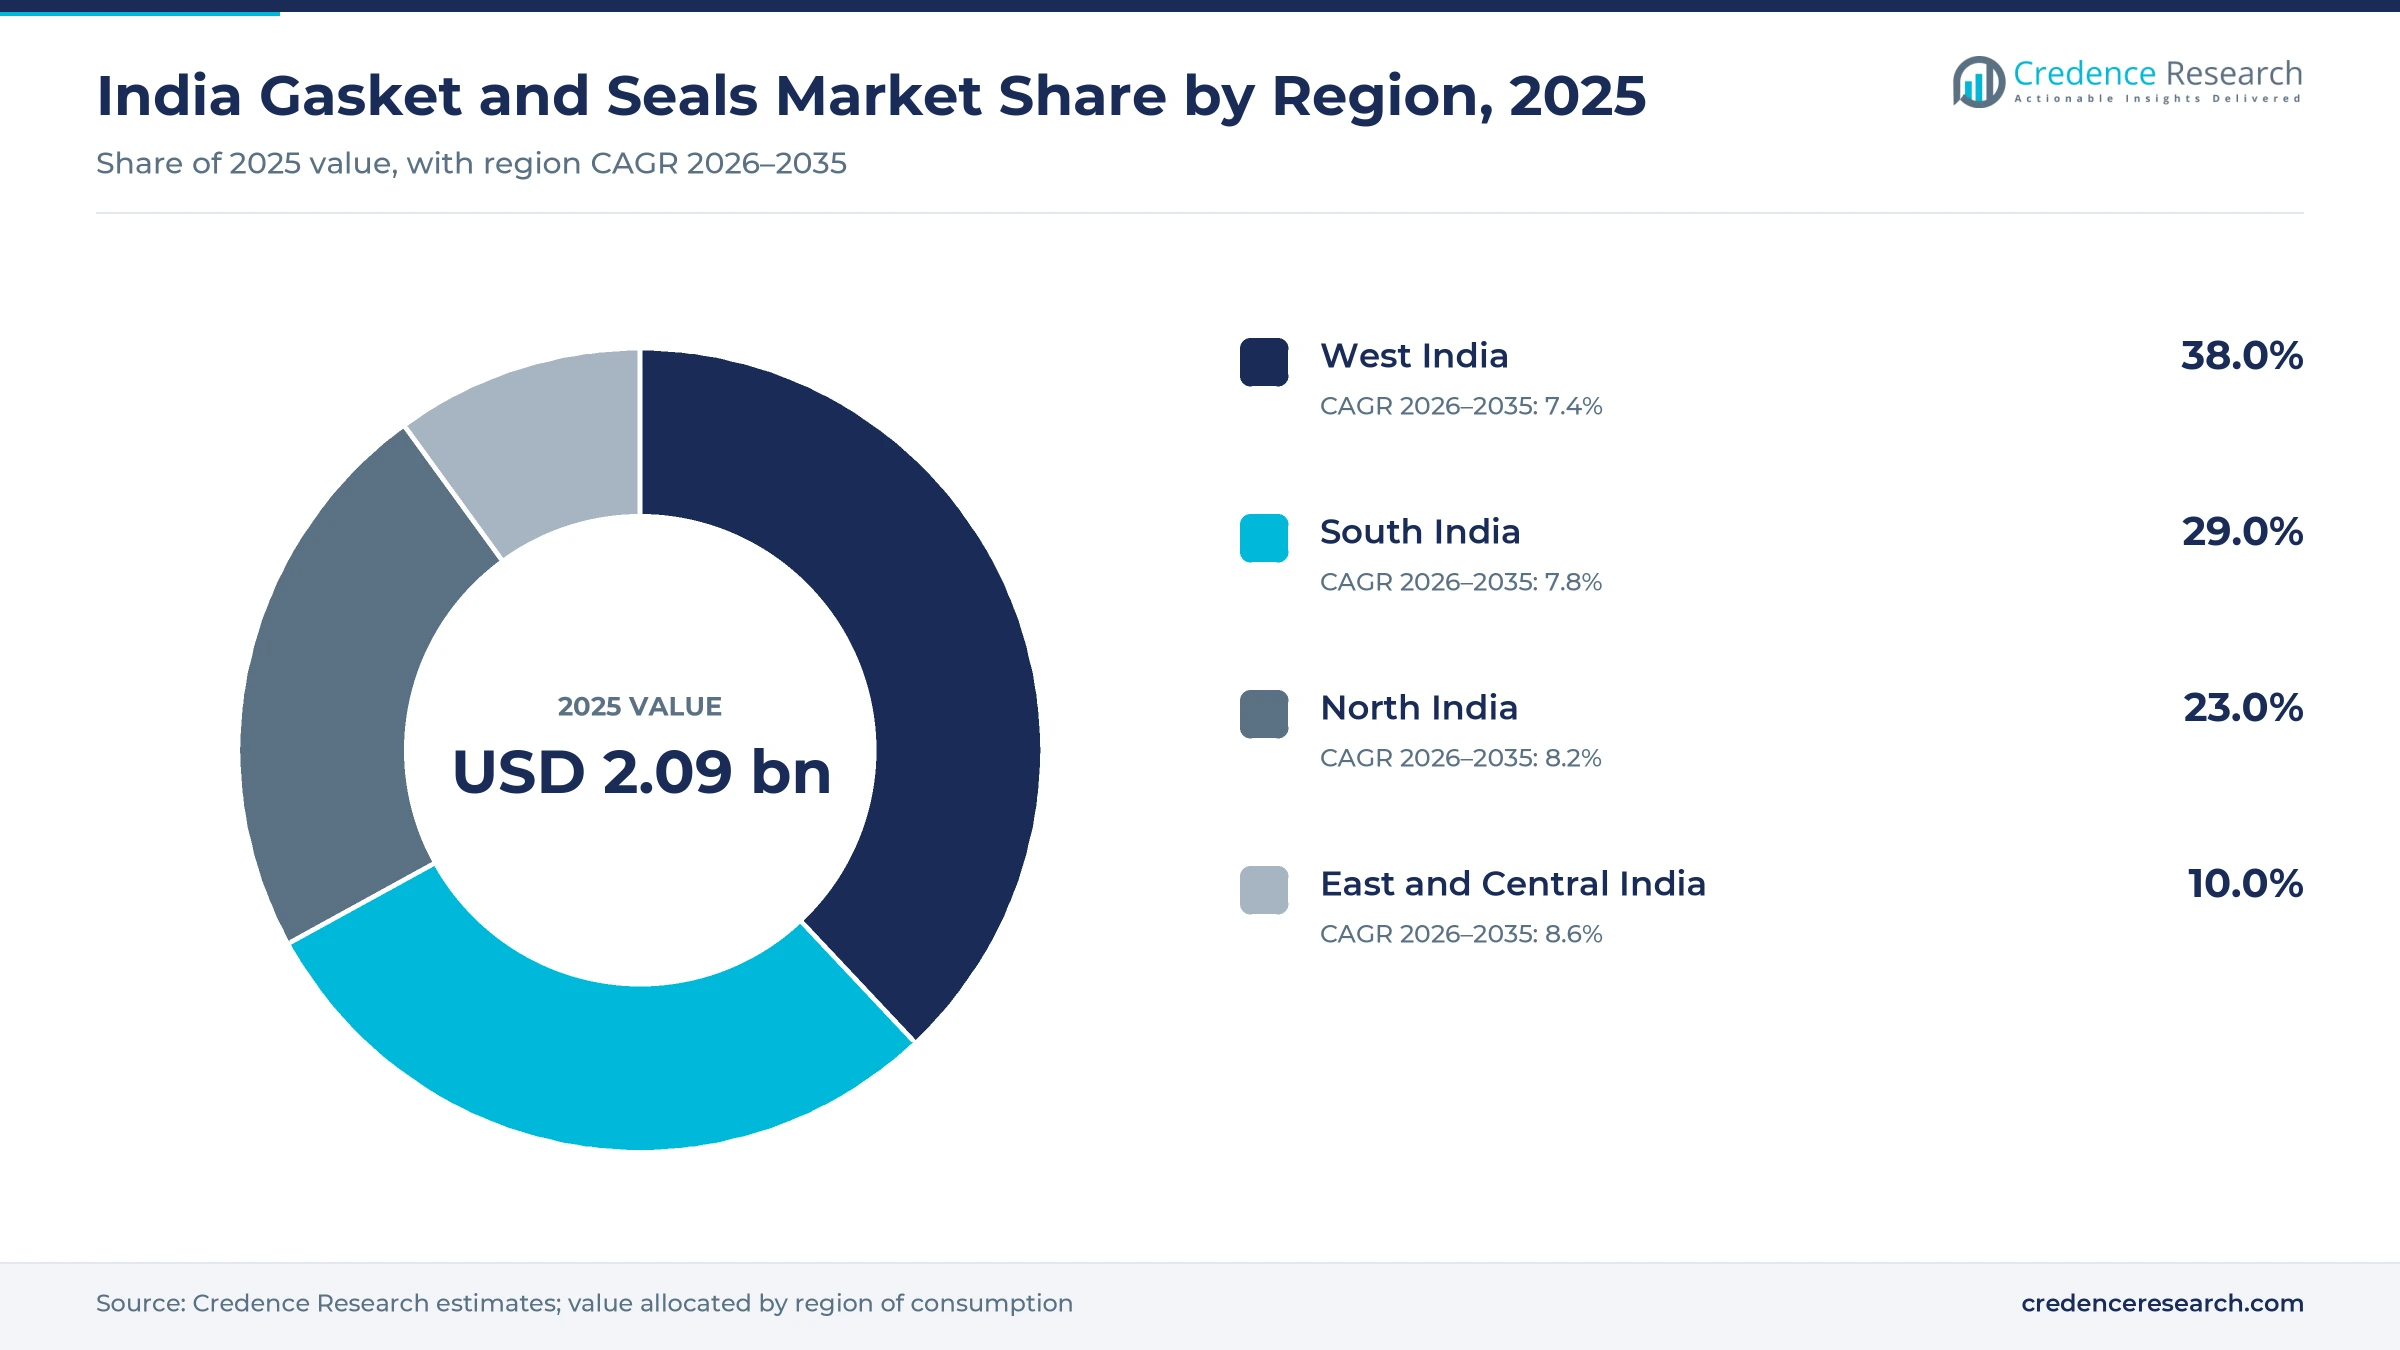
The India gasket and seals market was valued at USD 2.09 billion in 2025 and is projected to increase from USD 2.26 billion in 2026 to USD 4.43 billion by 2035, registering a CAGR of 7.78% during 2026–2035. Demand comes from vehicle and engine makers that fit cylinder head gaskets, oil seals and door weatherstrips, and from refineries, chemical plants, pump makers and factories that replace flange gaskets and mechanical seals during every shutdown. West India held the largest regional share, 38.0% in 2025, because Maharashtra and Gujarat combine dense auto clusters with the largest refining and chemical base. East and Central India is the fastest-growing region at 8.6% a year, as petrochemical and steel projects add process capacity there. Global sealing groups are moving production into India, while rubber prices that reached a record level in November 2026 test the margins of molded seal makers.
Static gaskets and dynamic seals for vehicles and plants make up the count
The market counts the value of gaskets and seals sold in India, covering metallic, semi-metallic and non-metallic gaskets, rotary shaft seals, molded packings and O-rings, and motor vehicle body seals such as door and window weatherstrips. It includes parts supplied to vehicle, machinery and equipment makers and replacement parts bought by workshops, refineries and plant maintenance teams.
Raw elastomer compounds, jointing sheet sold by weight, adhesives and sealants applied as liquids are excluded from the count. Value moves from polymer, graphite and steel suppliers through compounders and seal makers, many with their own tooling, to vehicle makers under multi-year programs and to process plants through distributors and service centers.
India Gasket and Seals Market Insights
- The India gasket and seals market rises from USD 2.09 billion in 2025 to USD 4.43 billion by 2035, a 7.78% CAGR during 2026–2035, as vehicle output and process capacity expand together.
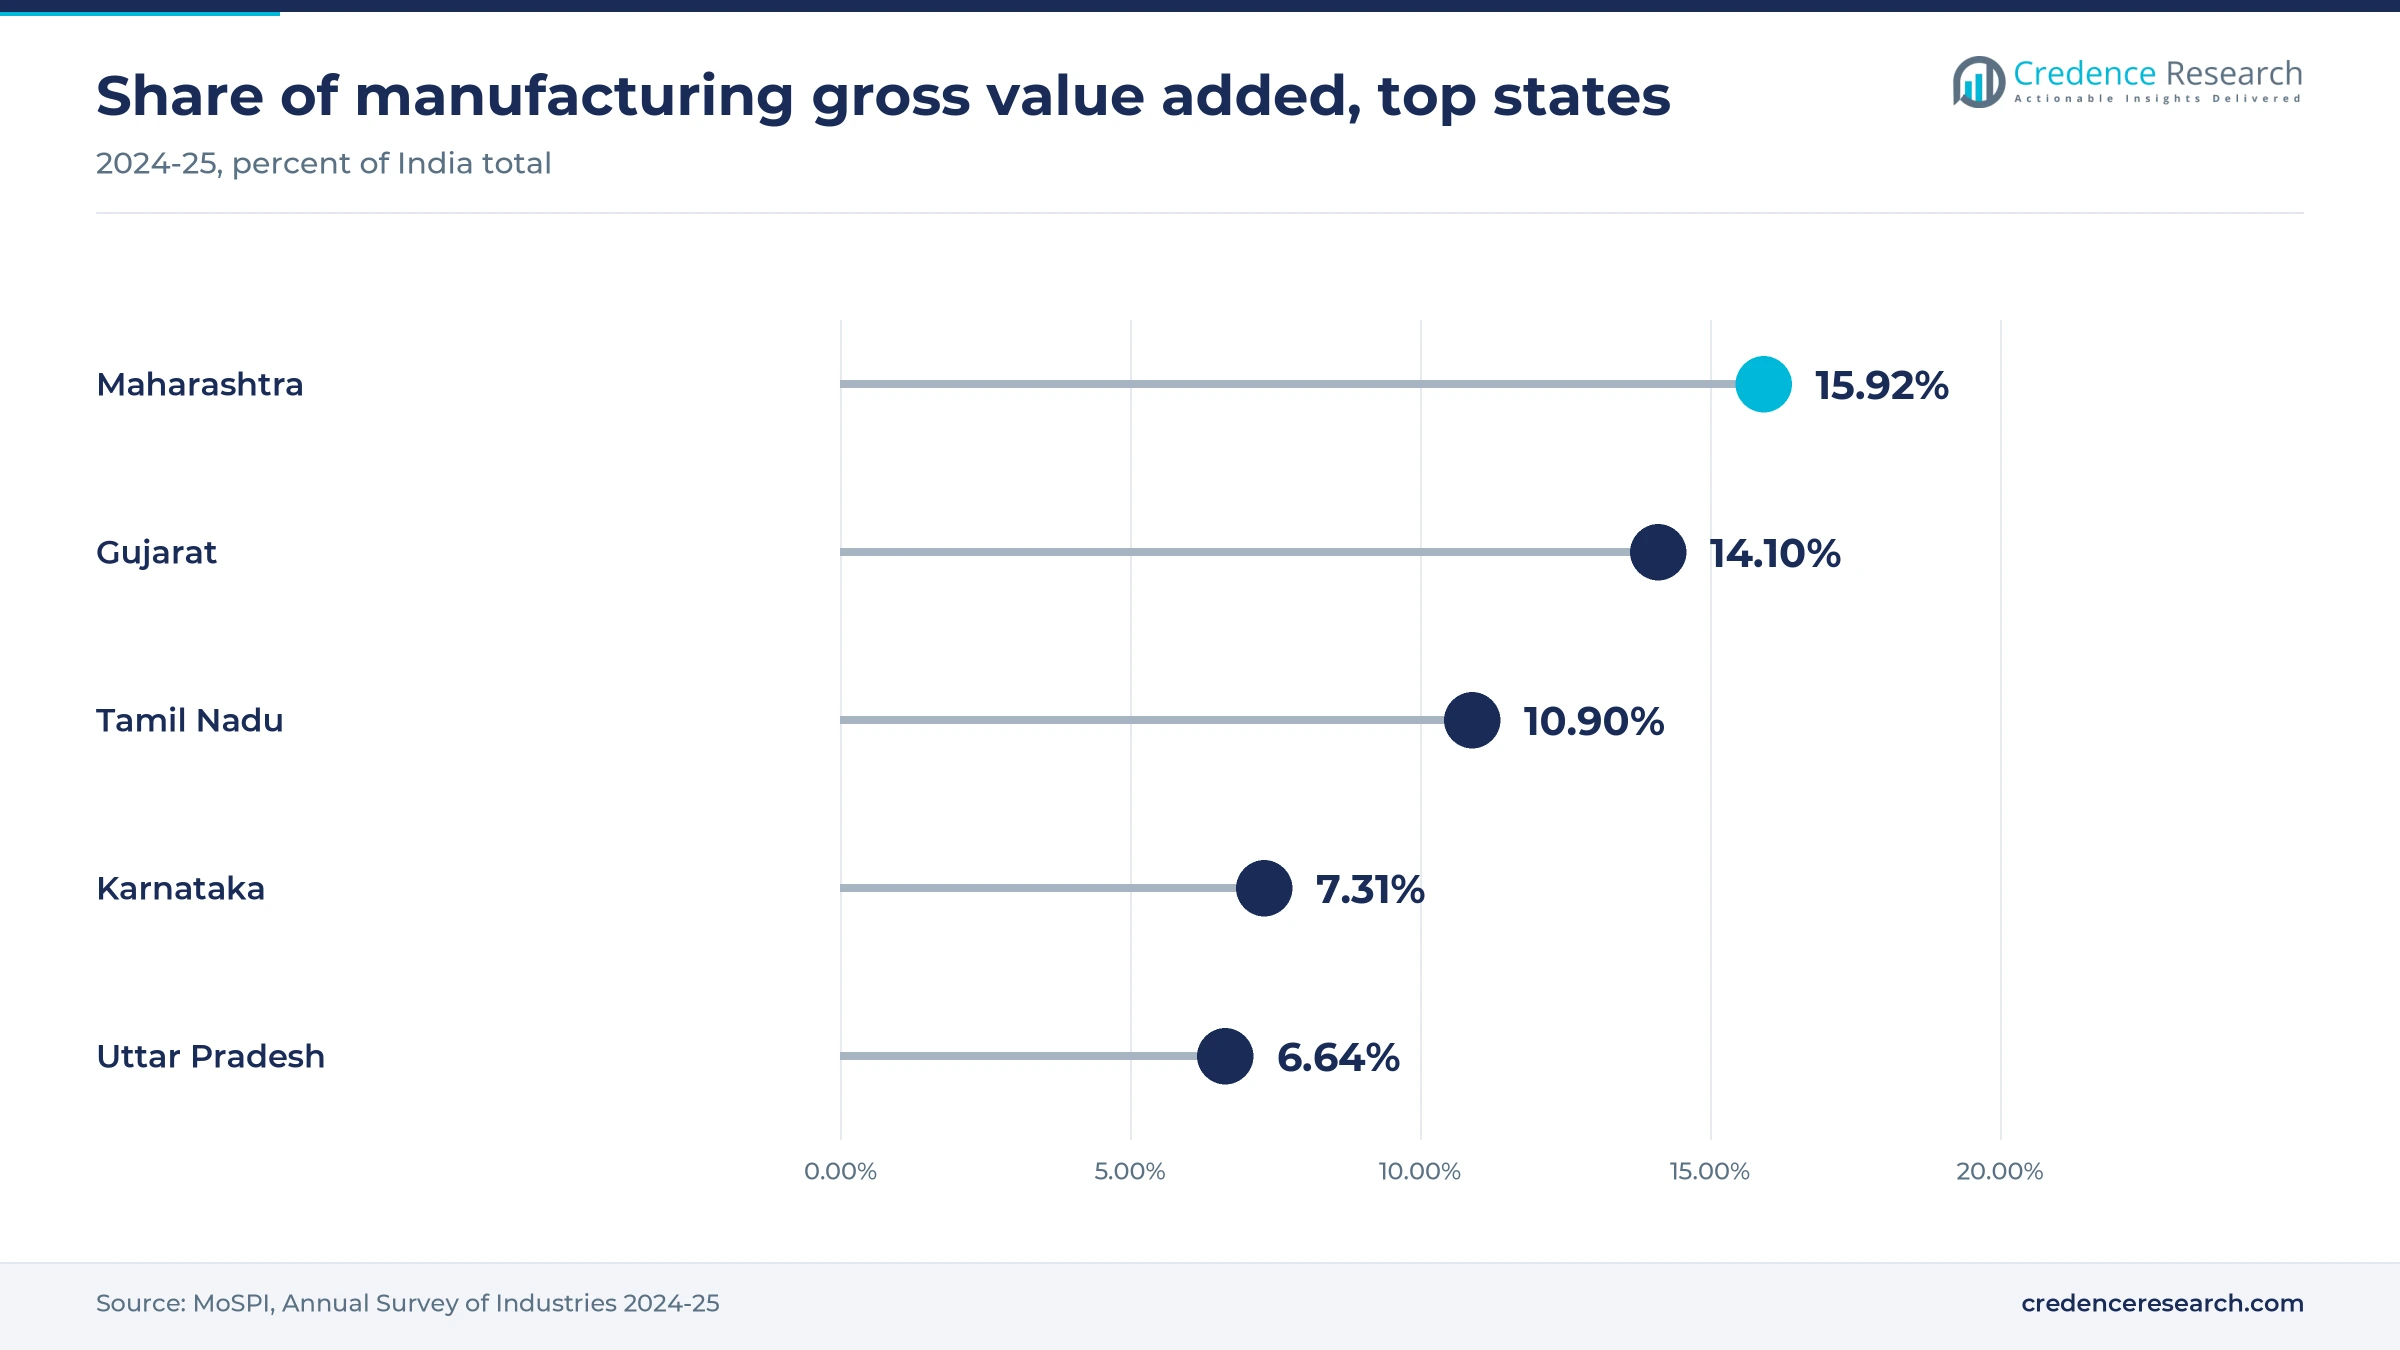
- West India held 38.0% of 2025 value, because Maharashtra and Gujarat together produced about 30% of India's manufacturing gross value added in 2024-25.
- Non-metallic Gaskets held 22.0% of 2025 value, since fiber, graphite, PTFE and rubber gaskets seal engines, pumps and flanged pipe joints.
- India plans to raise refining capacity from 258.1 to 309.5 million metric tons a year by 2030, which adds thousands of flanged joints and pump seals.
- Trelleborg broke ground in April 2026 on a Bengaluru plant that is set to raise its Indian sealing capacity by 30% in 2027.
Non-metallic gaskets lead as body seals grow fastest
Non-metallic gaskets lead while body seals follow car output
Based on product, the market is categorized into metallic gaskets, semi-metallic gaskets, non-metallic gaskets, shaft seals, molded packing and seals, and motor vehicle body seals. Non-metallic Gaskets led with 22.0% of 2025 value because fiber, graphite and rubber gaskets seal cylinder heads, oil pans, gearboxes and low-pressure flanges, the positions that vehicle and pump makers buy in the largest numbers. Motor Vehicle Body Seals grow fastest at 8.5% a year, because each car carries several meters of door and window weatherstrip, and passenger vehicle exports rose 17.5% to 9.05 lakh units in FY26, SIAM data show.
Automotive leads as petrochemical plants grow fastest
Based on application, the market is categorized into automotive, industrial and manufacturing, oil and gas, chemicals and petrochemicals, electrical and electronics, marine and rail, and others. Automotive led with 45.0% of 2025 value because domestic vehicle wholesales reached a record 2.83 crore units in FY26, according to SIAM and every engine, axle and door needs sealing. Chemicals & Petrochemicals grow fastest at 8.8% a year, as the Barmer refinery that opened in July 2026 carries 2.4 million metric tons a year of integrated petrochemical capacity. Public sector refiners also expect their petrochemical intensity index to rise from 4.1 to about 9.3 once current projects finish.
OEM supply leads and grows ahead of replacement buying
Based on end user, the market is categorized into original equipment manufacturer (OEM) and aftersales market. Original Equipment Manufacturer (OEM) led with 66.0% of 2025 value because gaskets and seals are specified into vehicle and equipment programs that run for five years or more, and component sales to OEMs rose 16.3% in FY26, ACMA reported. This channel also grows fastest at 8.0% a year as new models and new plants add first-fit volume. Replacement buying through the automotive aftermarket grew 9% to INR 1,08,453 crore over the same year and remains tied to the vehicle parc.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Non-metallic Gaskets | 22.0% | Motor Vehicle Body Seals | 8.5% |
| By Application | Automotive | 45.0% | Chemicals & Petrochemicals | 8.8% |
| By End User | Original Equipment Manufacturer (OEM) | 66.0% | Original Equipment Manufacturer (OEM) | 8.0% |
Seal prices span from a few rupees to thousands
Pricing for gaskets and seals in India splits into two separate systems. Vehicle makers buy gaskets and seals under multi-year contracts with annual price reviews, and many contracts index rubber and steel costs only partly. Process plants and workshops buy from list prices that range from a few rupees for a small spiral wound gasket to several thousand rupees for a cartridge mechanical seal. Elastomer and stainless steel costs move prices most, and natural rubber, the base of molded seals and weatherstrips, moves most often. Suppliers of engineered seals earn higher margins through design, testing and field service.
| Product or input | Typical price or fee | Basis |
|---|---|---|
| Small spiral wound gaskets, 1/2 inch and up | INR 10 to INR 25 per piece in most listings | IndiaMART seller listings, November 2026 |
| 16-inch metal spiral wound gasket | INR 2,553 per piece | IndiaMART seller listing, November 2026 |
| Kammprofile gaskets | INR 150 to INR 280 per piece | IndiaMART seller listings, November 2026 |
| Single spring mechanical seals | INR 150 to INR 3,500 per piece | IndiaMART seller listings, November 2026 |
| Cartridge mechanical seals | INR 4,200 to INR 8,500 per piece | IndiaMART seller listings, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Car output, refinery builds and EVs widen seal use
Record vehicle output lifts first-fit seal volumes
Vehicle output sets the floor for sealing demand, because every new engine, transmission and door is fitted with gaskets, oil seals and weatherstrips before the vehicle leaves the plant. The Indian auto component industry grew 12.7% to INR 7.60 lakh crore in FY26, Autocar Professional reported from ACMA data. Talbros, which supplies gaskets to Maruti Suzuki, Tata Motors and Bajaj Auto, announced about Rs 580 crore of multi-year orders across its businesses in June 2025. Automotive buyers account for 45.0% of 2025 value in the Credence Research estimate. Suppliers with approved parts on high-volume platforms gain most, while makers without OEM approvals stay confined to replacement channels.
Refinery and petrochemical builds add flanged joints
New process capacity creates demand for spiral wound and kammprofile gaskets on flanges and for mechanical seals on pumps and compressors, with a second wave at every maintenance turnaround. India plans to raise refining capacity from 258.1 million metric tons a year to 309.5 million metric tons by 2030, Construction World reported from a Rajya Sabha reply in December 2025. HPCL Rajasthan Refinery, a 9 million metric ton plant, was inaugurated in July 2026, ThePrint reported. IndianOil signed an MoU with the Odisha government in April 2025 for a Rs 61,077 crore petrochemical complex at Paradip. Seal makers with API-qualified designs and site service teams benefit most.
Electric vehicles bring new sealing positions
Electrification moves sealing content from the engine toward the battery and motor, because battery packs, motor housings, inverters and charging inlets all need gaskets that keep out water and dust. India sold about 2.3 million electric vehicles in 2025, an 8% share of registrations, Free Press Journal reported from India Energy Storage Alliance analysis of Vahan data. The government raised the PM E-Drive outlay to Rs 11,900 crore in August 2026 and kept electric two-wheeler subsidies open to March 2028. Talbros said about Rs 160 crore of its June 2025 orders came from the EV segment. Suppliers with battery enclosure and e-axle seal designs gain share as electric models scale.
Factory output growth keeps maintenance demand steady
Replacement demand from factories rises with plant output, because pumps, valves, mixers and gearboxes wear seals and gaskets in proportion to running hours. Manufacturing gross value added rose 9.59% to INR 26.94 lakh crore in 2024-25, according to the Annual Survey of Industries released by MoSPI in September 2026. Basic metals, motor vehicles, chemicals, pharmaceuticals and food products made up more than 45% of that value, and all of them run fluid-handling equipment. Rail adds a steady buyer, because every LHB coach carries seals in its bogies, brakes and doors, and Indian Railways built more than 4,224 such coaches between April and November 2025, up about 18%. Distributors and seal makers with stock near industrial clusters capture these repeat orders.
Global makers localize while exporters win programs
Global sealing groups shift production into India
Global sealing groups are shifting production into India to meet local content demands from vehicle makers and shorter lead times from process plants. Trelleborg Sealing Solutions broke ground in April 2026 on a 50,000 square meter greenfield site in Bengaluru, which is set to raise its capacity by 30% in 2027, Indian Chemical News reported. Freudenberg commissioned two plants in Morinda, Punjab, worth about Rs 385 crore in October 2024, one of them for Freudenberg-NOK India seals, gaskets and O-rings. SKF India's industrial business, listed separately after the October 2025 demerger, plans a Pune facility by 2028. Local capacity narrows the price gap with Indian makers and raises the bar for small suppliers.
Process plants shift to engineered seals with monitoring
Refiners and chemical producers are shifting from simple packings toward cartridge mechanical seals with support systems, gas seals and condition monitoring, to cut leaks, nitrogen use and unplanned shutdowns. John Crane told Industrial Automation India in June 2026 that its Type 93AX coaxial separation seal can cut nitrogen consumption by up to 80% against conventional designs. Sealmatic India opened a 25,000 square foot unit at Kaman, Vasai, which raised its capacity by 65% and is dedicated to API vessels for seal supply systems. This shift moves value from commodity parts toward engineered seals sold with industrial pump packages and field service.
Export programs give Indian makers a second growth channel
Exports offer Indian gasket and seal makers an opening, because global vehicle makers are adding suppliers outside China and India already ships proven parts. Auto component exports rose 5% to USD 24 billion in FY26, with Europe recording the strongest growth, Autocar Professional reported from ACMA data. Talbros said about Rs 150 crore of its June 2025 orders were export business, mainly in Europe. Makers that hold IATF 16949 approvals and can tool new parts quickly stand to win multi-year global programs. Indian makers that stay focused only on domestic replacement demand miss this volume.
Import substitution opens room in high-spec gaskets
High-specification gaskets remain an opening for local makers, because India still buys much of this range from Germany and the United States rather than from low-cost Asian suppliers. India imported about USD 168.5 million of metal-composite gaskets under HS 8484 in 2023, with Germany supplying 24% and the United States 12.4%, UN Comtrade data compiled by TrendEconomy show, while China supplied only 9.2%. Sealmatic said in January 2025 that it had supplied mechanical seals for India's midget submarine program. Indian suppliers that qualify for defense, rail and refinery approvals can replace these imports at lower cost and shorter lead time. Refiners and rail buyers gain local stock and faster replacement during shutdowns.
Rubber prices, project delays and EV mix squeeze makers
Record natural rubber prices squeeze molded seal makers
Natural rubber costs have swung sharply, which hurts makers of molded seals and weatherstrips that sell under fixed-price OEM contracts. RSS 4 grade averaged Rs 183.74 per kg in December 2025, SIAM commodity data show, then reached a record Rs 300 per kg in Kottayam and Kochi on Nov. 2, 2026, Onmanorama reported. Small compounders and body-seal makers without price escalation clauses are most exposed, while larger suppliers can renegotiate quarterly.
Imported specialty elastomers add currency risk
Specialty seals depend on imported synthetic and fluorinated elastomers, so a weaker rupee raises costs before any price revision reaches customers. The rupee fell to 89.52 per U.S. dollar by January 2026, which Autocar Professional said adds a hidden tax on synthetic rubber bought from Korea and Japan. Makers of nitrile rubber and FKM oil seals for engines and hydraulics are most exposed when contracts are priced in rupees.
Refinery project delays shift industrial orders
Industrial sealing orders follow refinery and petrochemical milestones, so a delayed project pushes gasket and seal deliveries into later years. IndianOil moved the deadline for its Panipat expansion from 15 to 25 million metric tons a year from September 2024 to December 2025 and raised its cost by about 10%, Outlook Business reported in December 2023. The Barmer refinery was also inaugurated in July 2026 after an earlier April schedule. Specialist suppliers with few project customers carry the largest timing risk.
Electric powertrains remove engine gasket content
Battery electric vehicles carry no cylinder head, exhaust or oil pan gaskets, so engine gasket makers lose content as the powertrain mix shifts. The cut in the PM E-Drive two-wheeler subsidy to Rs 2,500 per kWh, capped at Rs 5,000 per vehicle, slows that shift in the largest vehicle segment, which gives engine gasket makers time to retool, Autocar Professional reported in August 2026. EV components still made up only 4.6% of domestic OEM supplies in FY26, ACMA data show. Makers that depend on engine gasket sets must retool for battery and motor sealing before volumes move.
West India leads while the east adds petrochemicals
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| West India | 0.80 | 38.0% | 7.3% |
| South India | 0.61 | 29.0% | 7.8% |
| North India | 0.48 | 23.0% | 8.2% |
| East and Central India | 0.21 | 10.0% | 8.6% |
West India leads on refining and auto clusters
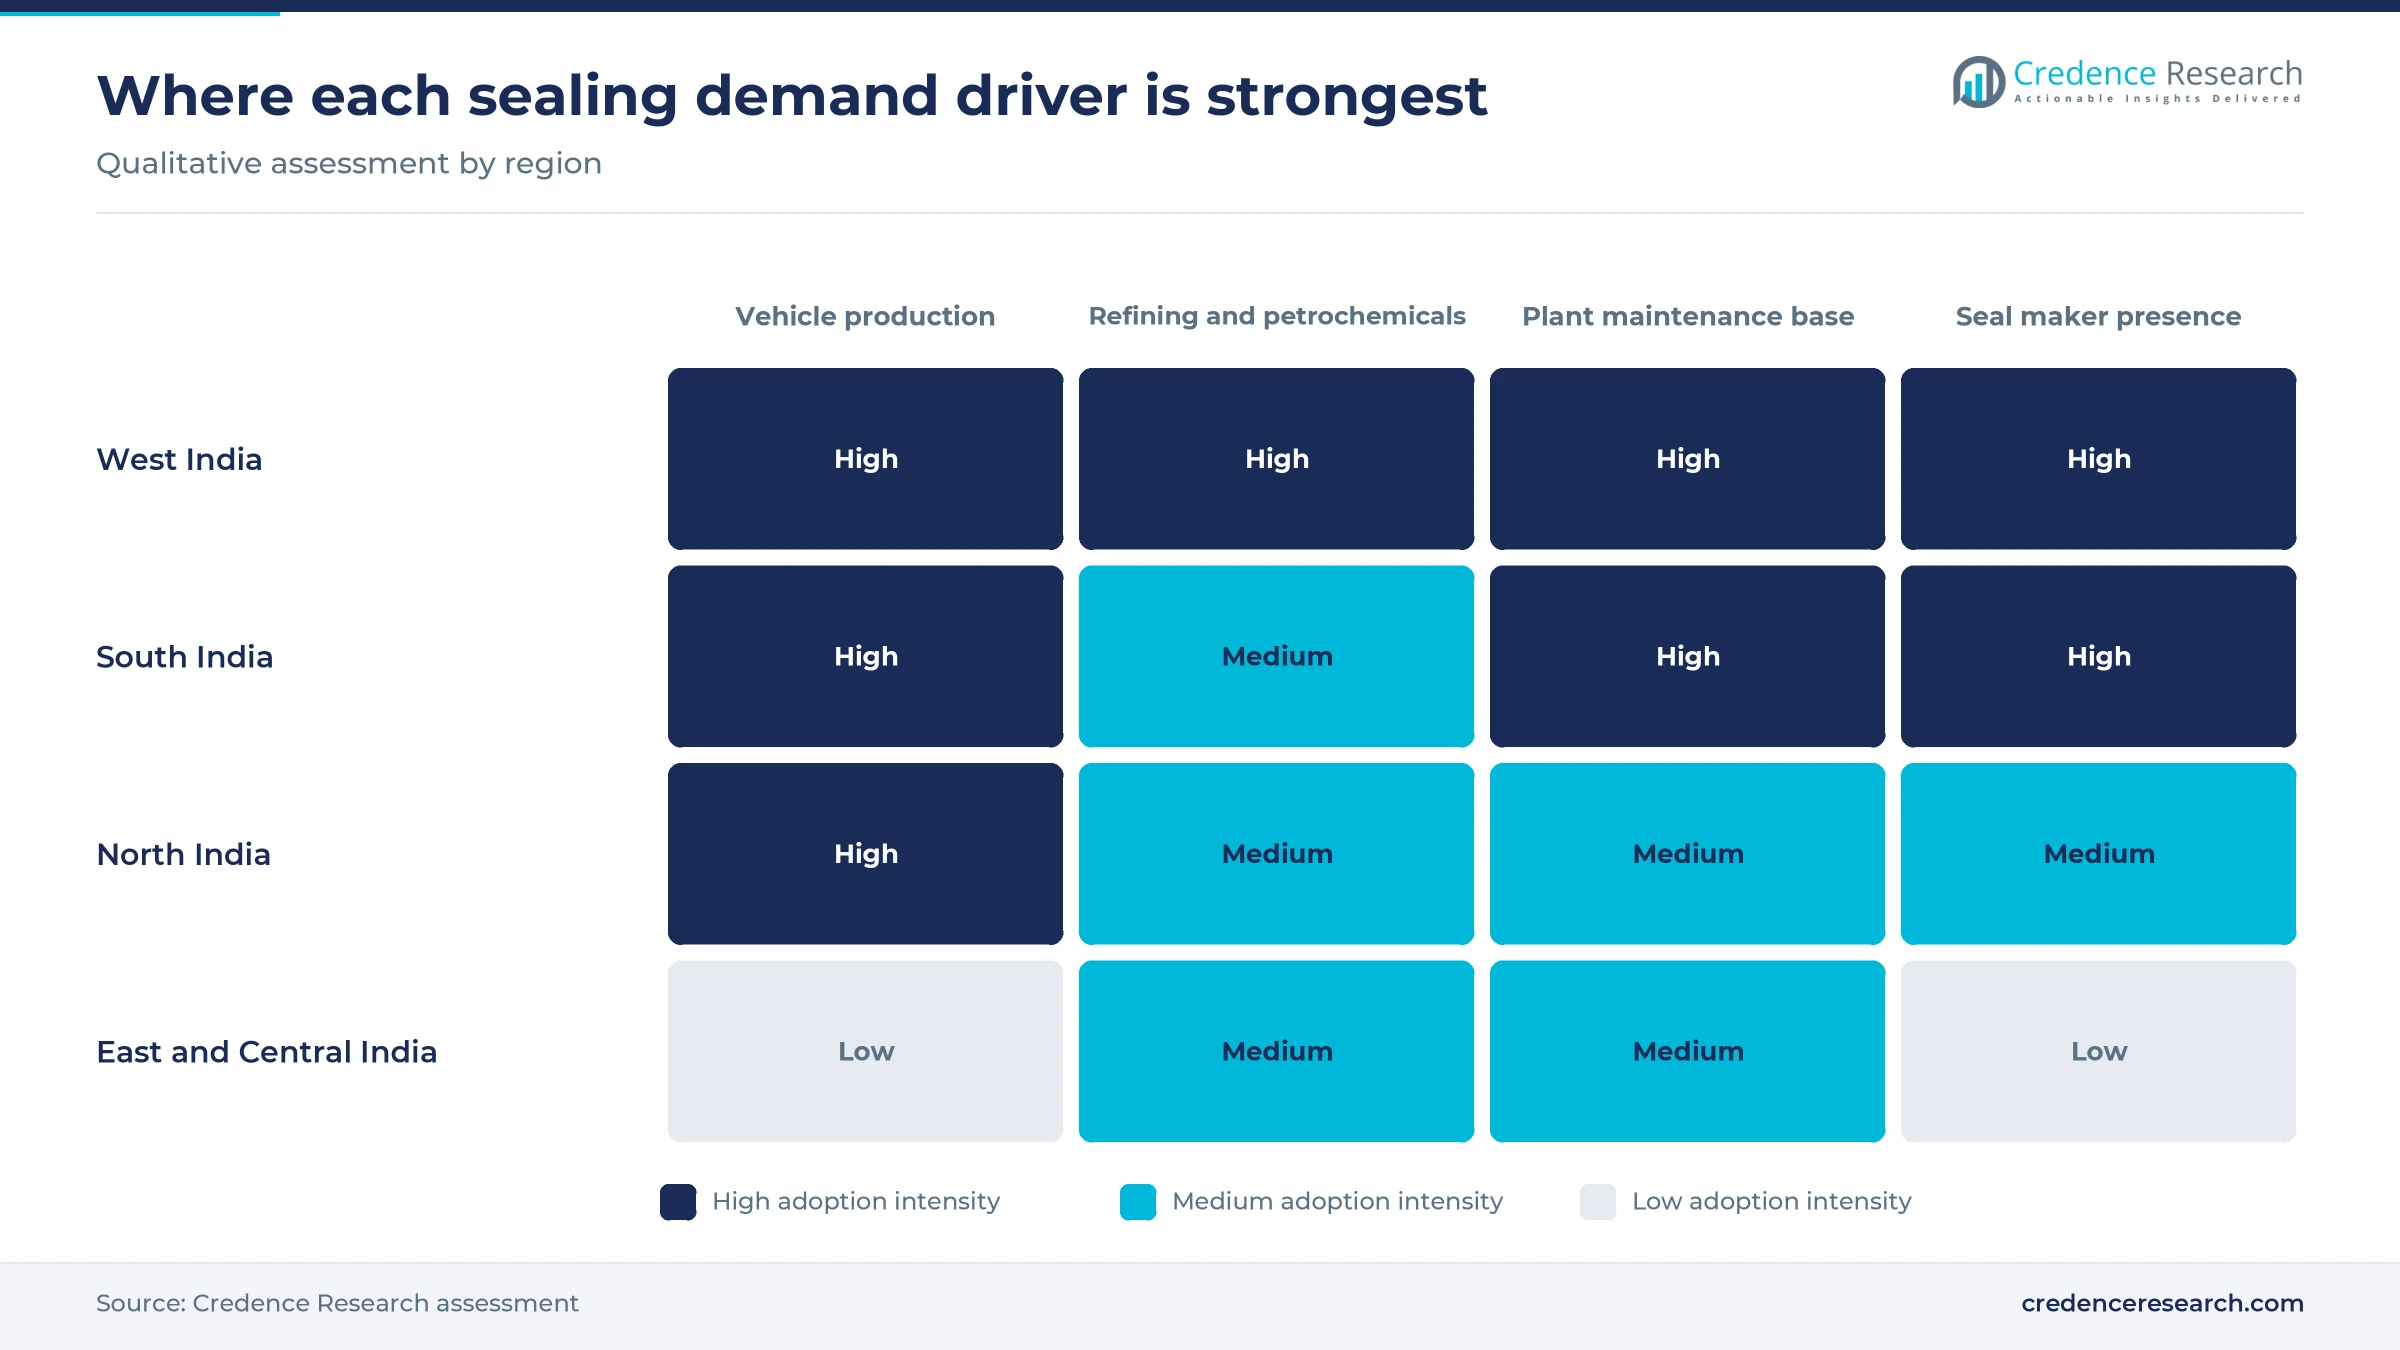
West India held 38.0% of 2025 value and grows at 7.3% a year through 2035. Maharashtra produced 15.92% and Gujarat 14.10% of manufacturing gross value added in 2024-25, according to MoSPI, the two largest state shares. Pune, Chakan and Aurangabad build vehicles and engines, while Jamnagar, Vadodara and Dahej run refineries and chemical plants that buy flange gaskets and pump seals. Toyoda Gosei supplies weatherstrips to Suzuki Motor Gujarat from its plant in Gujarat, and Banco and Sealmatic make gaskets and seals in Vadodara and Vasai.
South India grows on car exports and new seal plants
South India held 29.0% of 2025 value and grows at 7.8% a year. Tamil Nadu produced 10.90% and Karnataka 7.31% of manufacturing gross value added in 2024-25, MoSPI data show, and the two states host large car, truck and engine plants. Trelleborg is building its larger Bengaluru plant, and KLINGER set up a supply subsidiary near Bengaluru in the Chennai Bengaluru Industrial Corridor. Chennai's car and truck plants and the ICF coach lines keep first-fit volumes growing in the region.
North India adds a refinery and two-wheeler volume
North India held 23.0% of 2025 value and grows at 8.2% a year. Uttar Pradesh produced 6.64% of manufacturing gross value added in 2024-25, and Haryana hosts the Gurugram and Manesar car and two-wheeler clusters. The new Barmer refinery in Rajasthan and the Panipat expansion in Haryana add process demand. Freudenberg-NOK India moved seal production to its new Morinda plant in Punjab, close to tractor and two-wheeler customers.
East and Central India grows from new process capacity
East and Central India held 10.0% of 2025 value and is the fastest-growing region at 8.6% a year. IndianOil signed its MoU for the Paradip petrochemical complex in April 2025, and steel plants across Odisha, Jharkhand and Chhattisgarh run large pump and valve fleets. Credence Research assesses seal service coverage as thinner here than in the west and south, so suppliers that add local stock can win maintenance contracts.
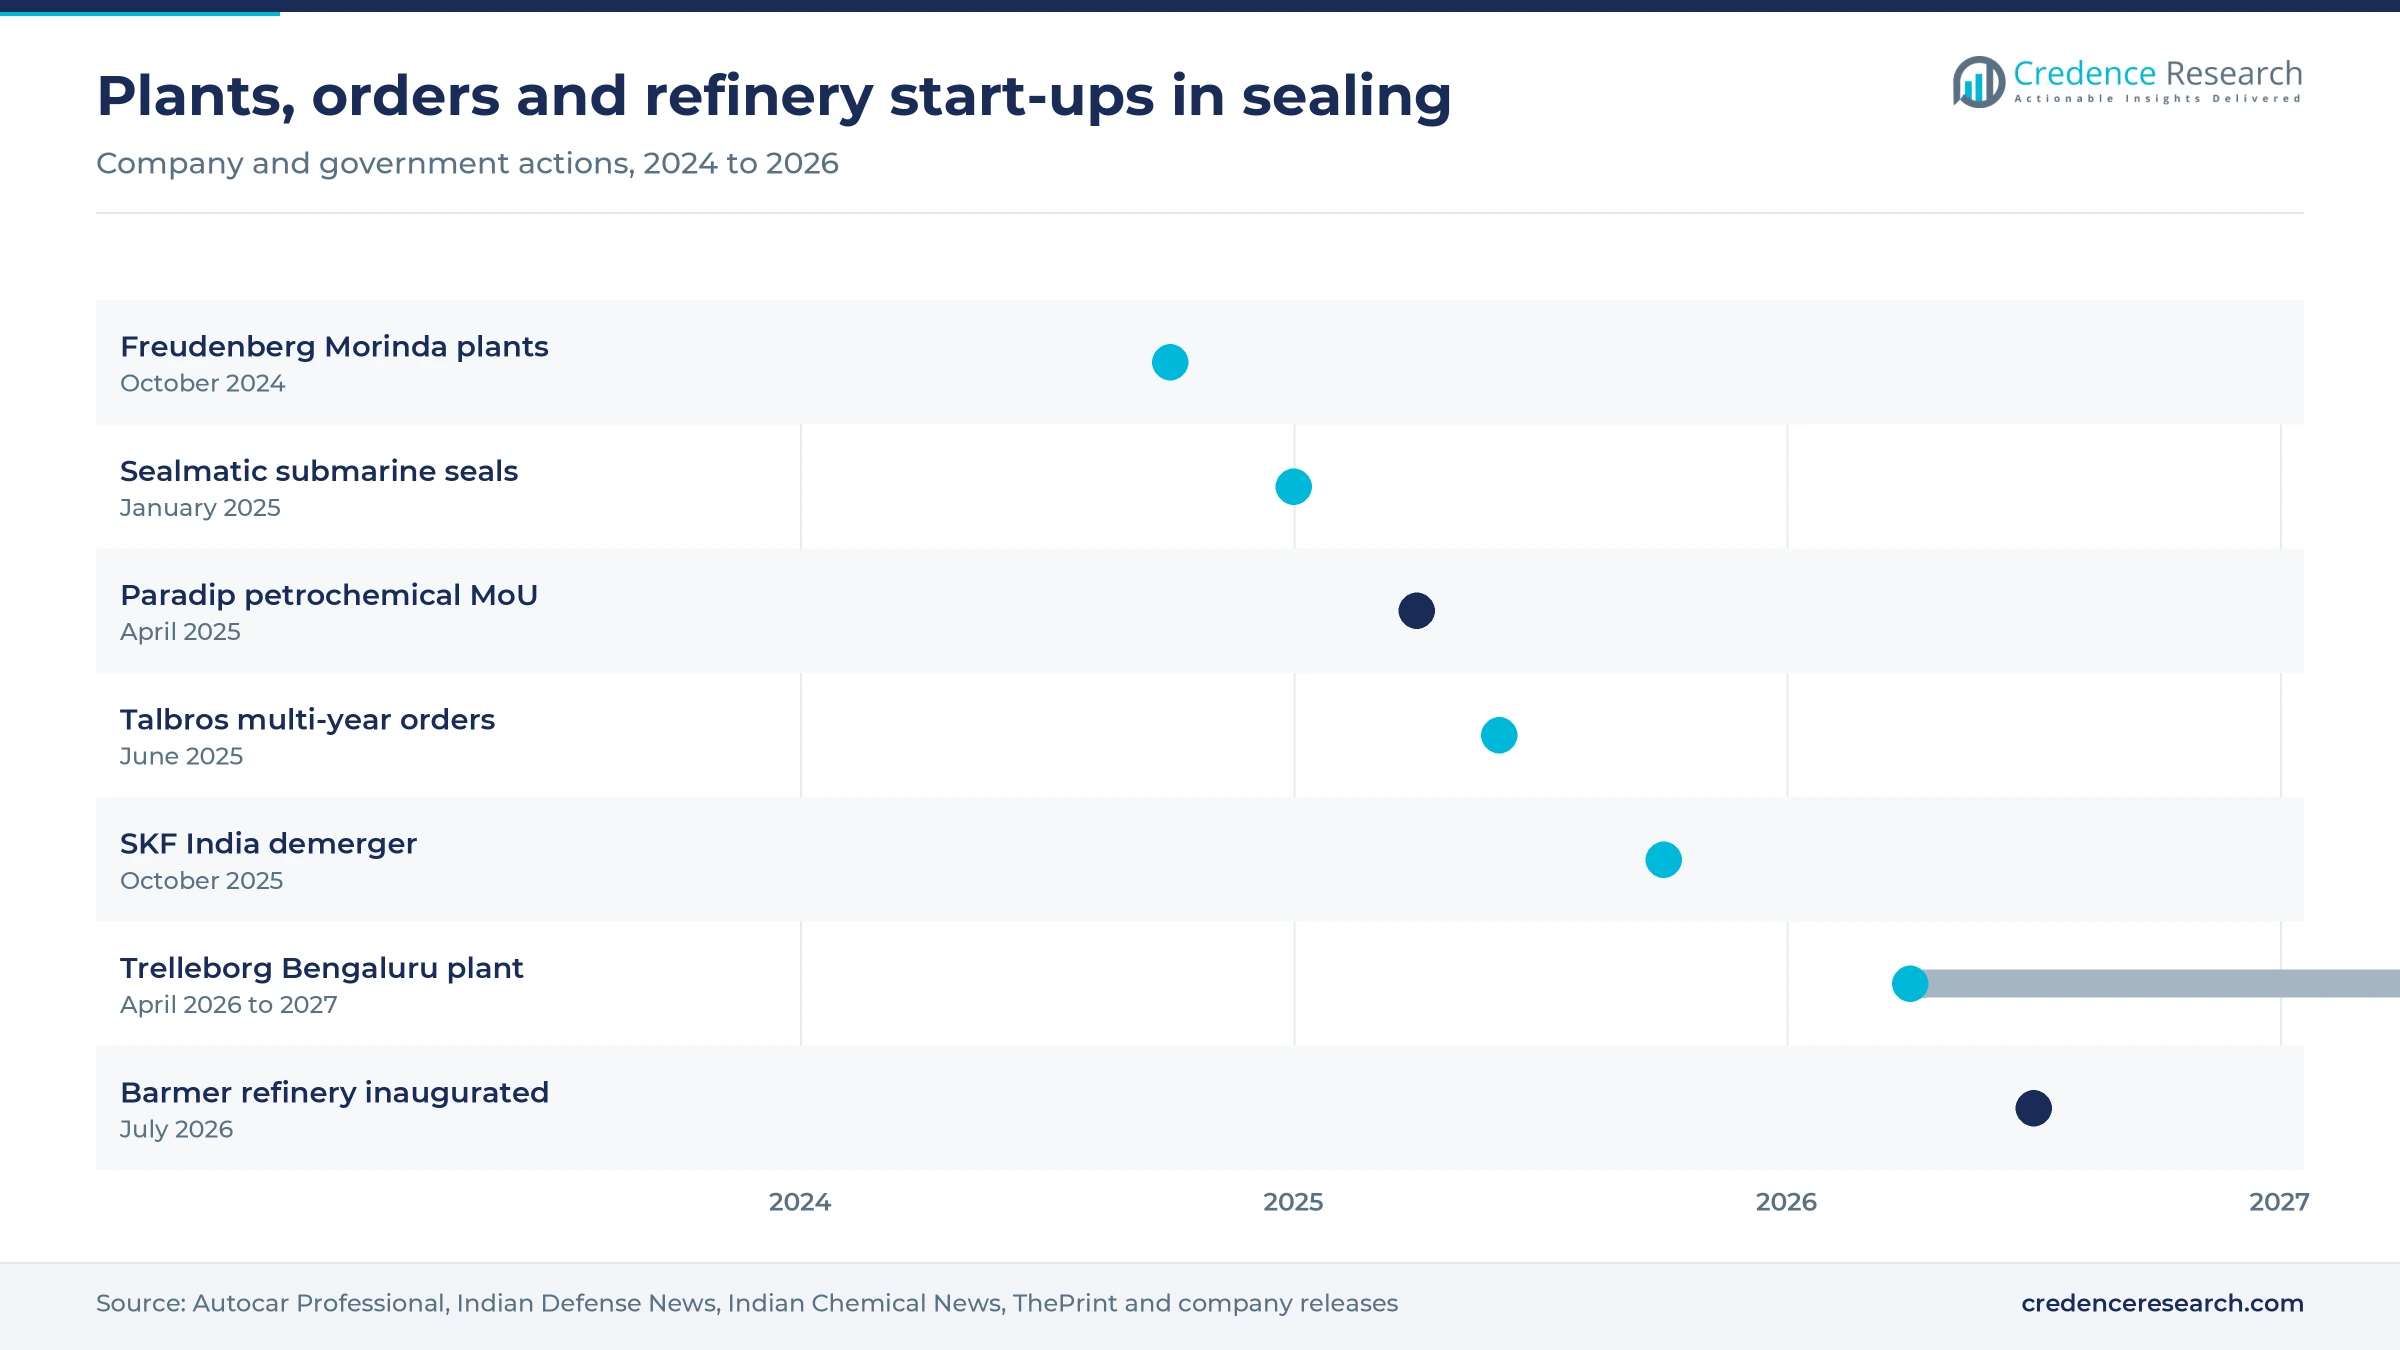
Plants, orders and refinery start-ups, 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In October 2024, Freudenberg commissioned two plants in Morinda, Punjab, worth about Rs 385 crore, including a Freudenberg-NOK India unit for seals, gaskets and O-rings. | Completed investment; production moved from leased sites to the new plants. |
| In January 2025, Sealmatic India said it had supplied mechanical seals for India's midget submarine program. | Supply completed; supports its defense qualification record. |
| In June 2025, Talbros Automotive Components announced about Rs 580 crore of multi-year orders, including about Rs 180 crore for gaskets and heat shields. | Orders received; execution runs over five years. |
| In April 2026, Trelleborg Sealing Solutions broke ground on a 50,000 square meter greenfield plant in Bengaluru. | Construction started; completion and a 30% capacity rise are expected in 2027. |
| In July 2026, HPCL Rajasthan Refinery, a 9 million metric ton refinery with petrochemical units, was inaugurated in Rajasthan. | Operational launch; adds a large new buyer of gaskets and pump seals. |
Engineered gaskets, cartridge seals and EV sealing
- Spiral wound and kammprofile gaskets seal high-pressure, high-temperature flanges in refineries and chemical plants, and their graphite or PTFE facings recover after thermal cycling.
- Cartridge mechanical seals arrive preassembled and pressure tested, which cuts installation errors on pumps and suits the API seal plans that refiners specify.
- Dry gas and separation seals reduce process leaks on compressors and agitators, and John Crane says its coaxial separation design cuts nitrogen use by up to 80%.
- Battery pack and e-axle gaskets keep water and dust out of electric vehicle enclosures and motors, a sealing position that grows as engine gasket content declines.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
OEM approvals and service reach decide positions
Competition in the India gasket and seals market splits by application. In vehicles, Talbros supplies engine and exhaust gaskets to Maruti Suzuki, Tata Motors and Bajaj Auto, while Freudenberg-NOK India and SKF supply oil and shaft seals, and Toyoda Gosei supplies weatherstrips to Suzuki Motor Gujarat. In process industries, EagleBurgmann India, John Crane India and Sealmatic compete for refinery, chemical and pump seals, and win on API qualification, test benches and service response. Trelleborg serves both groups with PTFE, shaft and face seals. Banco and Uni Klinger supply jointing sheets and gaskets for industrial flanges. Buyers judge suppliers on part approval history, delivery reliability and field support, which favors companies with Indian plants and service centers.
How is the supply side organized?
The supply side runs in three distinct tiers of companies. Global sealing groups with Indian plants, including Freudenberg-NOK, Trelleborg, EagleBurgmann and John Crane, lead engineered seals for vehicle makers and process plants. Listed Indian specialists such as Talbros, Sealmatic and Banco compete in gaskets and mechanical seals, often with export business. A long tail of small gasket cutters in Ahmedabad, Mumbai, Vadodara and Chennai sells standard flange gaskets from list prices. Entry barriers sit in OEM part approvals, API seal qualification and compound know-how, and margins are highest in engineered seals with service.
Sealing suppliers buyers shortlist in India
| Company | Type | Role in the market |
|---|---|---|
| Talbros Automotive Components Ltd. | Local manufacturer | Makes engine, exhaust and heat shield gaskets for vehicle makers and export programs |
| Freudenberg-NOK India (Freudenberg Sealing Technologies) | Full-line supplier | Makes automotive seals, gaskets and O-rings at its Morinda, Punjab plant |
| Trelleborg Sealing Solutions India (Trelleborg AB) | Full-line supplier | Makes PTFE products, rotary shaft seals and mechanical face seals in Bengaluru |
| EagleBurgmann India (Freudenberg–EKK joint venture) | Specialist | Makes mechanical seals and metal bellows seals for pumps and process plants |
| John Crane India (Smiths Group) | Specialist | Supplies mechanical and gas seals with local engineering and service |
| Sealmatic India Ltd. | Local manufacturer | Makes mechanical seals and seal supply systems, including defense supply |
| Toyoda Gosei Uno Minda India Pvt. Ltd. | Automotive joint venture | Makes weatherstrip sealing parts alongside airbags and fuel caps |
| SKF India Ltd. (SKF Group) | Full-line supplier | Supplies radial shaft seals and oil seals to vehicle makers and the replacement market |
| Banco Products (India) Ltd. | Local manufacturer | Makes jointing gasket sheets and sealing gaskets in Vadodara for OEMs |
| Uni Klinger Ltd. (KLINGER Group) | Local manufacturer | Makes fiber jointing sheets and industrial gaskets under the UniSIL brand |
Process plants will add more value than car volume
Credence Research's view is that process plants, not car volume, will decide how much value the India gasket and seals market adds by 2035. Vehicle output keeps the base large, but electric powertrains remove engine gaskets as they add battery seals, so value per vehicle grows slowly. Refineries, petrochemical complexes and chemical plants buy engineered gaskets and mechanical seals that cost far more per position and need replacement at every turnaround. Suppliers that combine API-qualified designs with local service should gain the most share.
Estimates rest on industry, trade and company data
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, and the regional, product, application and end user splits are Credence Research estimates informed by public data. Sources include ACMA and SIAM industry data, MoSPI survey results, parliamentary replies, trade statistics, company announcements and Indian business publishers. Seller listings were used only to show typical price ranges. No official statistic tracks gasket and seal output in India, so the product split rests on component, trade and company data. No interviews or surveys were used to build these estimates.
Petrochemical and export demand lift value to 2035
Credence Research expects India gasket and seal value to reach USD 4.43 billion by 2035 as vehicle programs, refinery expansions and petrochemical complexes add sealing positions. East and Central India should keep the fastest pace, while West India remains the largest source of value. Chemicals and petrochemicals grow at 8.8% a year during 2026–2035, ahead of automotive, as new crackers and polymer units start. The main risks are rubber costs near record levels and refinery delays, while export programs offer the clearest upside.
Refinery timing and rubber costs set the range of outcomes
The range to 2035 depends mainly on whether refinery and petrochemical projects reach commissioning on time and on how fast seal makers recover rubber costs from customers. Vehicle volumes support every case, but the mix between engine gaskets and EV sealing decides how much value each vehicle carries. Export programs add upside if global buyers keep moving orders to Indian suppliers.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 6.1% | USD 3.84 billion | Refinery projects slip by two years and rubber costs stay near record levels |
| Base | 7.78% | USD 4.43 billion | Refining reaches about 309 million metric tons by 2030 and vehicle output grows steadily |
| Upside | 9.2% | USD 4.98 billion | Export programs scale and EV sealing content offsets lost engine gasket value |
Frequently Asked Questions
How big is the India gaskets and seals market?
Which type of gasket leads demand in India?
What drives demand for automotive door seals in India?
Which region leads gasket and seal demand?
Which application grows fastest?
How do electric vehicles change seal demand?
What are the main challenges for suppliers?
Who are the main companies in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Non-metallic Gaskets
- 1.2.2 Molded Packing & Seals
- 1.2.3 Shaft Seals
- 1.2.4 Motor Vehicle Body Seals
- 1.2.5 Semi-metallic Gaskets
- 1.2.6 Metallic Gaskets
- 1.3 By Application
- 1.3.1 Automotive
- 1.3.2 Industrial & Manufacturing
- 1.3.3 Oil & Gas
- 1.3.4 Chemicals & Petrochemicals
- 1.3.5 Electrical & Electronics
- 1.3.6 Marine & Rail
- 1.3.7 Others
- 1.4 By End User
- 1.4.1 Original Equipment Manufacturer (OEM)
- 1.4.2 Aftersales Market
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.09 billion → 2035: USD 4.43 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Gasket and Seals Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Gasket and Seals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Gasket and Seals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Gasket and Seals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Gasket and Seals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Gasket and Seals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Gasket and Seals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Gasket and Seals Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.09 billion → 2035: USD 4.43 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Gasket and Seals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Non-metallic Gaskets
- 12.3.7.2 Molded Packing & Seals
- 12.3.7.3 Shaft Seals
- 12.3.7.4 Motor Vehicle Body Seals
- 12.3.7.5 Semi-metallic Gaskets
- 12.3.7.6 Metallic Gaskets
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Industrial & Manufacturing
- 12.4.7.3 Oil & Gas
- 12.4.7.4 Chemicals & Petrochemicals
- 12.4.7.5 Electrical & Electronics
- 12.4.7.6 Marine & Rail
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Original Equipment Manufacturer (OEM)
- 12.5.7.2 Aftersales Market
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 India Gasket and Seals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Gasket and Seals Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Gasket and Seals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Gasket and Seals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Talbros Automotive Components Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Freudenberg-NOK India (Freudenberg Sealing Technologies)
- 18.4 Trelleborg Sealing Solutions India (Trelleborg AB)
- 18.5 EagleBurgmann India (Freudenberg–EKK joint venture)
- 18.6 John Crane India (Smiths Group)
- 18.7 Sealmatic India Ltd.
- 18.8 Toyoda Gosei Uno Minda India Pvt. Ltd.
- 18.9 SKF India Ltd. (SKF Group)
- 18.10 Banco Products (India) Ltd.
- 18.11 Uni Klinger Ltd. (KLINGER Group)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

