
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Industrial Catalyst Market Size 2024 | USD 926.89 million |
| India Industrial Catalyst Market, CAGR | 8.29% |
| India Industrial Catalyst Market Size 2032 | USD 1752.41 million |
Market Overview:
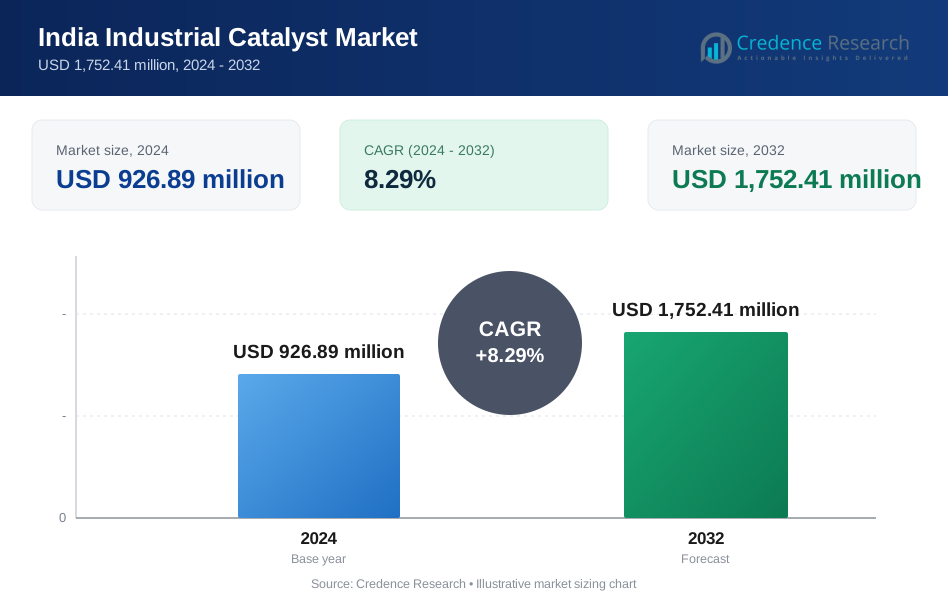
The India Industrial Catalyst Market is projected to grow from USD 926.89 million in 2024 to an estimated USD 1752.41 million by 2032, with a compound annual growth rate (CAGR) of 8.29% from 2024 to 2032.
The key growth drivers for the India industrial catalyst market include the rapid expansion of the chemical and petrochemical industries, increased focus on energy efficiency, and a transition toward cleaner and greener technologies. Industrial catalysts play a pivotal role in optimizing production processes, improving yield, and reducing energy consumption, making them essential across a wide range of industrial applications. As demand for specialty chemicals, polymers, and fuels continues to rise, especially in sectors like automotive, agriculture, and pharmaceuticals, the need for advanced catalytic solutions intensifies. Furthermore, government initiatives such as “Make in India” and increased foreign direct investment (FDI) in chemical processing sectors are encouraging domestic manufacturing, thereby amplifying the consumption of industrial catalysts. Environmental regulations focused on emission reduction and sustainable industrial processes have also compelled industries to adopt more efficient and environmentally friendly catalytic technologies.
Regionally, India represents a critical hub within the Asia-Pacific industrial catalyst market, which dominates globally due to strong industrial infrastructure and increasing consumption. Within India, western and southern regions-including Maharashtra, Gujarat, and Tamil Nadu-host a concentration of chemical and petrochemical manufacturing clusters, significantly driving regional demand for catalysts. Gujarat, in particular, stands out with its extensive refinery network and industrial corridors that heavily utilize catalytic processes in operations. Moreover, the rising establishment of industrial zones, special economic zones (SEZs), and research centers across states such as Andhra Pradesh, Karnataka, and Haryana contributes to regional diversification and sustained catalyst demand. As India continues to emphasize renewable energy, emission control, and sustainable growth, regional investments in catalyst-driven processes are expected to grow steadily, further strengthening the market across diverse geographies.
Market Insights:
- The market is projected to grow from USD 926.89 million in 2024 to USD 1,752.41 million by 2032, at a CAGR of 29%, driven by rising industrial demand.
- The global industrial catalyst market is projected to grow from USD 31.56 billion in 2024 to USD 51.15 billion by 2032, with a CAGR of 6.22% from 2024 to 2032.
- Rapid expansion of India’s chemical and petrochemical sectors is a key growth engine, especially in Gujarat, Maharashtra, and Tamil Nadu.
- Increasing environmental regulations and a shift toward energy-efficient technologies are boosting the demand for greener catalyst solutions.
- Government initiatives like “Make in India” and PLI schemes are fostering domestic manufacturing and reducing dependency on imports.
- Advances in nanotechnology and hybrid catalyst systems are enhancing catalyst performance and lifecycle, supported by R&D investments.
- Market growth is challenged by high raw material costs and limited domestic availability of key metals like platinum and palladium.
- Western and Southern India dominate the regional market due to dense industrial clusters, while other regions show emerging potential through SEZs and infrastructure development.
Report scope
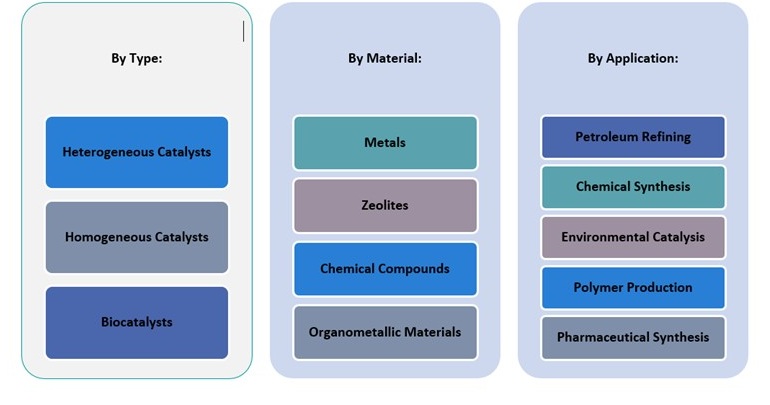
This report segment the India Industrial Catalyst Market as follows
Market Drivers:
Expansion of the Chemical and Petrochemical Industry
The rapid growth of India’s chemical and petrochemical sector is a primary driver of the industrial catalyst market. Catalysts are vital in facilitating complex chemical reactions efficiently, thereby enhancing output and process optimization. India is emerging as a global hub for chemical manufacturing, with significant investments pouring into both bulk and specialty chemicals. For example, Indian government and major petrochemical companies have committed nearly USD 45 billion to petrochemical projects, with an additional USD 100 billion projected to meet rising demand. As companies aim to increase production capacity to meet domestic and export demands, the integration of advanced catalysts into manufacturing systems becomes imperative. This growth trajectory is further reinforced by government incentives and industrial policy reforms supporting the expansion of downstream chemical processing units, especially in Gujarat, Maharashtra, and Tamil Nadu.
Emphasis on Sustainable and Energy-Efficient Processes
A growing focus on environmental sustainability and energy efficiency across industries is further propelling the demand for industrial catalysts. Industries are increasingly under pressure to reduce their environmental footprint, which has resulted in the adoption of catalytic technologies that lower energy consumption and reduce emissions. Catalysts enable cleaner chemical reactions by promoting selective conversion and minimizing byproducts. This is especially relevant in India, where stringent environmental regulations are being enforced to combat industrial pollution. The use of emission control catalysts in refineries, cement plants, and chemical factories aligns with the national commitment to meet global sustainability standards and reduce greenhouse gas emissions.
Supportive Government Policies and Industrial Initiatives
Policy support and favorable industrial initiatives have played a crucial role in accelerating catalyst adoption in India. Government programs such as ‘Make in India’ and Production Linked Incentive (PLI) schemes for chemical manufacturing are encouraging domestic production, creating substantial opportunities for catalyst manufacturers and suppliers. For example, PLI benefits have spurred companies to expand production capacities and innovate sustainable chemical products. Moreover, the push for self-reliance in chemical intermediates and specialty chemicals has amplified investments in new production facilities, where catalysts are essential for process efficiency. Regulatory bodies are also facilitating ease of doing business by simplifying compliance frameworks and improving infrastructure, further strengthening the investment climate for catalyst-intensive industries.
Technological Advancements and R&D Investments
Technological innovation and increased investments in research and development have significantly influenced the evolution of the industrial catalyst market in India. Indian companies and research institutions are collaborating to develop more selective, durable, and environmentally benign catalysts to improve process performance and meet the unique demands of various end-use sectors. The rising adoption of nanotechnology, zeolites, and hybrid catalyst systems is enabling more efficient reaction mechanisms and longer catalyst life cycles. Additionally, international partnerships and technology transfers are equipping Indian manufacturers with advanced capabilities, helping bridge the gap between domestic and global standards in catalyst performance.
Market Trends:
Rising Demand for Green Catalysts
A notable trend in the India industrial catalyst market is the increasing preference for green and environmentally friendly catalysts. As industries align with global sustainability goals, there is a shift toward using catalysts that enable cleaner chemical processes, lower waste generation, and minimal environmental impact. Green catalysts, such as biocatalysts and photocatalysts, are gaining traction in sectors like pharmaceuticals, agrochemicals, and biofuel production. These catalysts not only reduce the use of hazardous chemicals but also allow processes to occur under milder conditions, thereby conserving energy. The Indian government’s focus on sustainable industrial development and circular economy principles has further accelerated the adoption of eco-efficient catalytic technologies across multiple verticals.
Growth in Specialty Catalyst Applications
The Indian market is experiencing an upsurge in demand for specialty catalysts that are tailored to specific industrial processes. Unlike general-purpose catalysts, specialty catalysts are designed for high selectivity and improved yield in niche applications, such as polymerization, hydrocracking, and fine chemical synthesis. With the rising production of polymers, synthetic rubbers, and specialty chemicals, industries are increasingly investing in high-performance catalysts to enhance productivity and product quality. For instance, Clariant's AmoMax catalyst optimizes energy use in fertilizer production while enhancing yields, demonstrating the industry's focus on improving productivity and sustainability. The specialty catalyst segment is benefiting from India’s expanding downstream industries and growing export demand for advanced materials. As manufacturing processes become more complex and performance-oriented, the role of specialty catalysts will continue to grow significantly.
Integration of Digital Technologies in Catalyst Development
An emerging trend reshaping the catalyst industry in India is the integration of digital technologies into catalyst design and performance monitoring. Advanced modeling, artificial intelligence (AI), and machine learning (ML) are being utilized to simulate reaction environments, optimize catalyst formulations, and predict performance outcomes. These technologies accelerate research and reduce development costs by minimizing trial-and-error experimentation. Several Indian research institutes and catalyst producers are adopting data-driven approaches to improve product lifecycle and operational efficiency. The digital transformation in catalyst development is not only reducing time-to-market but also enabling the customization of catalysts for specific industrial challenges.
Increased Collaboration Between Industry and Academia
Collaboration between industry players and academic institutions is gaining momentum in the Indian industrial catalyst market. These partnerships are focused on innovating new catalyst materials, improving synthesis techniques, and scaling up lab-based solutions to industrial levels. For example, Emerson partnered with IITB-Monash Research Academy to develop prototypes for energy-efficient reactor designs and carbon capture technologies. This collaborative ecosystem has led to the development of catalysts suited to Indian manufacturing conditions, reducing dependency on imports and fostering domestic innovation. Such alliances are expected to play a critical role in the long-term competitiveness and self-sufficiency of India’s catalyst industry.
Market Challenges Analysis:
High Raw Material Costs and Supply Chain Constraints
One of the major restraints in the India industrial catalyst market is the high cost and limited availability of raw materials required for catalyst production. Precious metals such as platinum, palladium, and rhodium, commonly used in catalytic applications, are subject to global price volatility and supply limitations. India, being heavily dependent on imports for these raw materials, faces risks associated with fluctuating foreign exchange rates and international trade disruptions. For instance, over 60% of India's petrochemical feedstock is imported, leaving the industry vulnerable to international trade fluctuations and foreign exchange risks. These factors not only elevate production costs but also impact the pricing and profitability of catalyst manufacturers, making it challenging for smaller domestic players to compete.
Lack of Advanced Manufacturing Infrastructure
India’s industrial catalyst sector continues to face challenges related to technological infrastructure and manufacturing capabilities. While there is significant progress in R&D, the ability to scale up high-performance catalyst technologies remains limited. The lack of specialized production facilities, pilot plants, and testing equipment hampers the commercialization of innovative catalyst solutions. Additionally, limited access to process automation and quality control systems affects the consistency and efficiency of domestically produced catalysts, creating a dependency on imported alternatives for high-end applications.
Regulatory Compliance and Environmental Concerns
Compliance with evolving environmental and safety regulations presents an additional challenge for catalyst producers. As India strengthens its environmental policies to align with international standards, manufacturers are required to adopt cleaner production processes and meet stringent emission norms. However, the high cost of transitioning to sustainable practices, along with the complexity of obtaining regulatory clearances, often delays project implementation. This can hinder new market entrants and discourage investment in innovative catalyst technologies.
Market Opportunities:
The India industrial catalyst market presents significant growth opportunities driven by the country’s expanding industrial base and evolving focus on sustainability. With the chemical and petrochemical sectors projected to grow at a rapid pace, there is rising demand for high-performance catalysts that can enhance process efficiency and product quality. Government initiatives such as “Make in India” and the Production Linked Incentive (PLI) schemes have created a favorable environment for domestic manufacturing, encouraging investments in new catalyst production units. Additionally, the shift toward clean energy, green chemistry, and low-emission manufacturing presents a compelling opportunity for the adoption of advanced and environmentally friendly catalysts. As companies seek to comply with stricter environmental norms and improve energy efficiency, the market for emission control, hydrogenation, and oxidation catalysts is expected to expand significantly.
Moreover, there is untapped potential in research-driven innovation and the localization of catalyst production. The growing collaboration between academia and industry, along with increased R&D spending, is opening avenues for the development of customized catalysts suited to India’s unique industrial requirements. Emerging sectors such as biofuels, electric vehicle battery manufacturing, and waste-to-energy are creating new demand segments for specialized catalysts. Furthermore, India’s strategic focus on reducing import dependency and building domestic capabilities in key manufacturing sectors supports the development of an indigenous catalyst ecosystem. These dynamics offer long-term opportunities for both global and local players to invest in product innovation, technology transfer, and regional expansion within the Indian industrial catalyst landscape.
Market Segmentation Analysis:
The India industrial catalyst market is segmented by type, application, and material, each contributing distinctly to the market's structure and growth potential.
By type, heterogeneous catalysts dominate the market due to their extensive use in large-scale industrial processes such as petroleum refining and chemical synthesis. Their ease of separation and recyclability make them a preferred choice for continuous operations. Homogeneous catalysts, although less prevalent, are gaining attention in fine chemical and pharmaceutical applications for their high selectivity and efficiency. Biocatalysts are an emerging segment, increasingly used in environmentally friendly processes, especially within pharmaceutical and agrochemical industries, aligning with India’s growing emphasis on green chemistry.
By application, petroleum refining holds a major share, driven by India’s expansive refinery network and the continuous need for process optimization. Chemical synthesis and polymer production are also significant segments, supported by the growth of specialty chemicals and plastics manufacturing. Environmental catalysis is witnessing rapid growth, fueled by stricter emission norms and sustainability targets. Pharmaceutical synthesis continues to expand due to increased demand for cost-efficient and high-purity production methods.
By material, metals such as platinum, palladium, and nickel are widely used due to their catalytic efficiency, particularly in refining and automotive applications. Zeolites are favored in petrochemical processes for their structural stability and effectiveness. Chemical compounds, including oxides and sulfides, find broad utility in base chemical production. Organometallic materials are specialized but increasingly important for homogeneous and fine chemical catalysis.
Segmentation:
By Type Segment
- Heterogeneous Catalysts
- Homogeneous Catalysts
- Biocatalysts
By Application Segment
- Petroleum Refining
- Chemical Synthesis
- Environmental Catalysis
- Polymer Production
- Pharmaceutical Synthesis
By Material Segment
- Metals
- Zeolites
- Chemical Compounds
- Organometallic Materials
Regional Analysis:
The India industrial catalyst market demonstrates a regionally diverse distribution, with western and southern regions dominating the landscape due to their strong industrial infrastructure and presence of key manufacturing hubs. Western India holds the largest market share, accounting for nearly 38% of the total market. This dominance is attributed to the concentration of petrochemical and chemical industries in states such as Gujarat and Maharashtra. Gujarat, in particular, stands out as a critical contributor due to its extensive refinery operations, fertilizer plants, and industrial corridors. The state’s integrated ecosystem, comprising raw material availability, robust transportation networks, and export-friendly ports, makes it a focal point for catalyst demand.
Southern India follows closely, contributing approximately 27% of the market share. States like Tamil Nadu, Karnataka, and Andhra Pradesh have emerged as industrial powerhouses, with significant activities in the automotive, pharmaceutical, and specialty chemical sectors. The region also benefits from the presence of technology parks and R&D institutions, which foster innovation in catalyst development and application. Tamil Nadu’s focus on green technology and process optimization, along with Karnataka’s growing biotech and pharmaceutical sectors, are key drivers for catalyst demand in the south.
Northern India holds a 20% market share and is gradually expanding, supported by the growth of industrial clusters in Haryana, Punjab, and Uttar Pradesh. The increase in fertilizer production, agrochemical manufacturing, and the emergence of new SEZs in this region have created fresh demand for catalysts used in chemical synthesis and environmental applications. Government investments in industrial infrastructure and improved connectivity across North India are expected to further strengthen its role in the national market.
Eastern India currently represents the smallest share, estimated at 15%, but it is witnessing steady growth due to resource availability and infrastructure development. States like Odisha, Jharkhand, and West Bengal are seeing increased industrial activity, particularly in steel, cement, and refining sectors, which rely on catalytic processes for emissions control and energy efficiency. With initiatives focused on mining, power generation, and downstream chemical processing, eastern India has the potential to emerge as a high-growth region in the long term.
Key Player Analysis:
- Mitsubishi Chemical Corporation
- LG Chem
- R. Grace (Asia-Pacific operations)
- BASF SE (Regional)
- Reliance Industries Limited
- Sinopec Catalyst Co., Ltd.
- Johnson Matthey (Asia-Pacific operations)
- India National Petroleum Corporation (CNPC)
- Sumitomo Chemical Co., Ltd.
- Toray Industries, Inc.
Competitive Analysis:
The India industrial catalyst market is moderately consolidated, with a mix of global leaders and domestic manufacturers competing across various segments. Key international players such as BASF SE, Clariant AG, Johnson Matthey, and Haldor Topsoe maintain a strong presence through strategic partnerships, localized manufacturing, and advanced product offerings tailored to the Indian market. These companies leverage their R&D capabilities and global expertise to address complex industrial requirements. On the domestic front, firms like Sud-Chemie India, Deepak Nitrite, and EIL (Engineers India Limited) are gaining market traction by offering cost-effective and application-specific catalyst solutions. Competitive intensity is rising due to increased demand for sustainable and energy-efficient catalysts, prompting companies to invest in innovation, capacity expansion, and after-sales support. As India pushes for self-reliance in specialty chemicals and industrial inputs, local players are expected to strengthen their market position through indigenous development and strategic collaborations with research institutions.
Recent Developments:
- In January 2025, Mitsubishi Chemical Group announced plans to expand its operations in India's green specialty sector, focusing on semiconductor and EV supply chain materials. The company is exploring new business opportunities in mono methyl acrylate (MMA) production and may collaborate with partners or establish greenfield units for these ventures.
- On October 29, 2024, W.R. Grace partnered with Nayara Energy Limited to successfully launch a new 450 KTA polypropylene process technology plant in Vadinar, Gujarat. Utilizing Grace’s non-phthalate CONSISTA catalysts and UNIPOL process technology, the plant aims to produce high-quality polypropylene resins for pharmaceutical, health, and hygiene applications.
- On October 18, 2024, Johnson Matthey opened a new engineering center in Mumbai to enhance its capacity for delivering low-carbon technology projects globally. This facility focuses on hydrogen, sustainable fuels, and specialty chemicals while leveraging India's engineering expertise
Market Concentration & Characteristics:
The India industrial catalyst market exhibits moderate to high market concentration, with a few dominant multinational corporations controlling a significant share, particularly in high-performance and specialty catalyst segments. These global firms, equipped with advanced R&D infrastructure and proprietary technologies, set industry benchmarks in product innovation and quality. However, the market also includes a growing base of domestic manufacturers and mid-sized enterprises, particularly in commodity and process-specific catalysts. The market is characterized by a strong emphasis on technological advancement, regulatory compliance, and customization to meet diverse industrial requirements. Demand is primarily driven by sectors such as petrochemicals, fertilizers, pharmaceuticals, and environmental applications. Additionally, the market reflects a shift towards sustainability, with increasing focus on green and energy-efficient catalysts. Product differentiation, long-term client relationships, and technical service support are critical factors influencing competitiveness. Overall, the industry combines global expertise with emerging domestic capabilities, creating a dynamic and evolving market environment.
Report Coverage:
The research report offers an in-depth analysis based on Type Segment, Application Segment and Material Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is projected to grow steadily, supported by increasing demand from the expanding chemical and petrochemical industries.
- Rising environmental regulations will drive the adoption of emission-reducing and energy-efficient catalysts.
- Domestic manufacturing initiatives are expected to reduce dependency on imported catalyst technologies.
- Advanced catalyst research will be fueled by greater collaboration between industry and academic institutions.
- The specialty catalyst segment will witness strong growth due to demand from pharmaceuticals and fine chemical industries.
- Technological integration, including AI and data analytics, will enhance catalyst design and process optimization.
- Eastern and northern regions are anticipated to emerge as new growth hubs due to infrastructure development.
- Global players will continue to invest in India through joint ventures and local production facilities.
- The bio-based and green catalyst segments will gain momentum in response to sustainability goals.
- Increased government funding for clean energy and industrial innovation will create long-term growth opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of the Chemical and Petrochemical Industry
India's rapid growth in chemical and petrochemical manufacturing, especially in Gujarat, Maharashtra, and Tamil Nadu, is driving demand for industrial catalysts to optimize production and meet rising domestic and export needs.
Emphasis on Sustainable and Energy-Efficient Processes
Stricter environmental regulations and a national focus on sustainability are pushing industries to adopt advanced catalysts that reduce emissions and energy consumption, particularly in refineries and chemical plants.
Supportive Government Policies and Industrial Initiatives
Government programs like 'Make in India' and Production Linked Incentive (PLI) schemes are encouraging domestic catalyst production, reducing import dependency, and fostering investment in new manufacturing facilities.
Technological Advancements and R&D Investments
Increased collaboration between industry and academia, along with adoption of nanotechnology and hybrid catalyst systems, is leading to the development of more efficient, selective, and durable catalysts tailored for Indian industrial needs.
Growth in Specialty and Green Catalyst Applications
Rising demand for specialty and environmentally friendly catalysts in pharmaceuticals, agrochemicals, and biofuels is expanding the market, as industries seek higher selectivity, improved yields, and compliance with sustainability goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Industrial Catalyst Market?
What factors are driving the growth of the India Industrial Catalyst Market?
What are some challenges faced by the India Industrial Catalyst Market?
Who are the major players in the India Industrial Catalyst Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Heterogeneous Catalysts
- 1.2.2 Homogeneous Catalysts
- 1.2.3 Biocatalysts
- 1.3 By Material
- 1.3.1 Metals
- 1.3.2 Zeolites
- 1.3.3 Chemical Compounds
- 1.3.4 Organometallic Materials
- 1.4 By Application
- 1.4.1 Petroleum Refining
- 1.4.2 Chemical Synthesis
- 1.4.3 Environmental Catalysis
- 1.4.4 Polymer Production
- 1.4.5 Pharmaceutical Synthesis
- 1.5 By Region (India)
- 1.5.1 Western India
- 1.5.2 Southern India
- 1.5.3 Northern India
- 1.5.4 Eastern India
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 926.89 million → 2032: USD 1,752.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Industrial Catalyst Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Industrial Catalyst Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Industrial Catalyst Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Industrial Catalyst Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Industrial Catalyst Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Industrial Catalyst Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Industrial Catalyst Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Industrial Catalyst Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 926.89 million → 2032: USD 1,752.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Industrial Catalyst Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Heterogeneous Catalysts
- 12.3.7.2 Homogeneous Catalysts
- 12.3.7.3 Biocatalysts
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metals
- 12.4.7.2 Zeolites
- 12.4.7.3 Chemical Compounds
- 12.4.7.4 Organometallic Materials
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Petroleum Refining
- 12.5.7.2 Chemical Synthesis
- 12.5.7.3 Environmental Catalysis
- 12.5.7.4 Polymer Production
- 12.5.7.5 Pharmaceutical Synthesis
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Region (India) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Western India
- 12.6.7.2 Southern India
- 12.6.7.3 Northern India
- 12.6.7.4 Eastern India
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Industrial Catalyst End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Industrial Catalyst Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Industrial Catalyst Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Industrial Catalyst Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mitsubishi Chemical Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Chem
- 18.4 W. R. Grace & Co.
- 18.5 BASF SE
- 18.6 Reliance Industries Limited
- 18.7 Sinopec Catalyst Co., Ltd.
- 18.8 Johnson Matthey
- 18.9 Sumitomo Chemical Co., Ltd.
- 18.10 Toray Industries, Inc.
- 18.11 Clariant AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

