
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Thermic Fluids Market Size 2023 | USD 455.38 million |
| India Thermic Fluids Market, CAGR | 9.12% |
| India Thermic Fluids Market Size 2032 | USD 1171.05 million |
Market Overview:
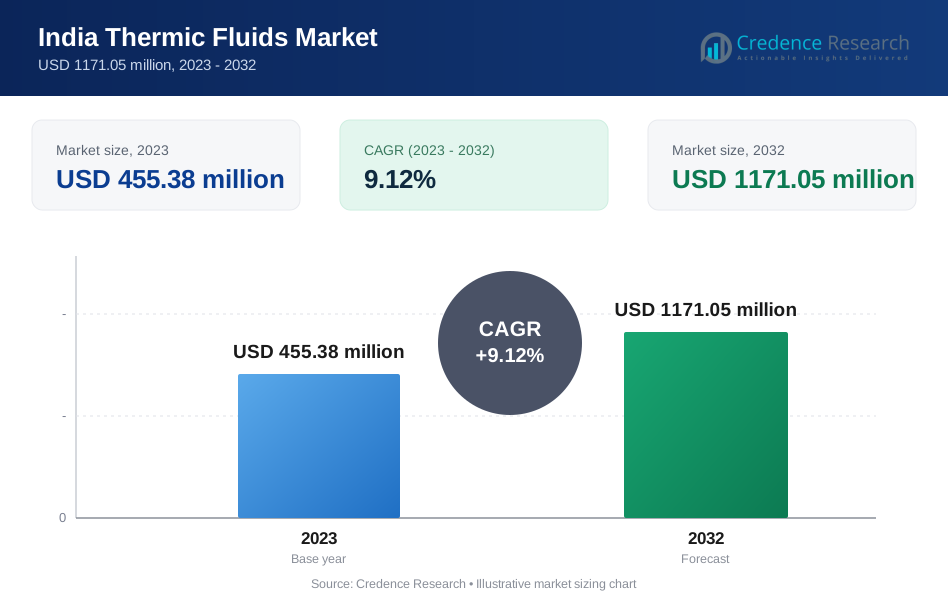
The thermic fluids market in India was valued at USD 455.38 million in 2023 and is projected to reach USD 1171.05 million by 2032. This market is expected to experience a compound annual growth rate (CAGR) of 9.12% from 2024 to 2032. The demand for thermic fluids is robust across various industrial sectors in India, driven by rapid industrial expansion, especially in segments like chemicals, pharmaceuticals, and food processing. Thermic fluids are preferred for their efficient heat transfer capabilities compared to traditional methods like steam heating.
Key drivers of the market's expansion include an increased focus on energy efficiency amidst rising energy costs and environmental concerns. Industries are turning to thermic fluids for their superior heat transfer efficiency, which leads to significant energy savings. Additionally, government initiatives promoting the "Make in India" campaign and infrastructure development are expected to boost demand for thermic fluids across industries, further fueling market growth. Continuous technological advancements in thermic fluid technology are also expanding the application scope of these fluids, enhancing their performance characteristics and safety features.
However, the Indian thermic fluids market faces challenges such as fluctuating raw material prices, stringent environmental regulations demanding eco-friendly solutions, and a need for increased awareness among potential users. Addressing these challenges will be crucial for sustained market growth. Despite these obstacles, the Indian thermic fluids market remains poised for significant expansion, playing a vital role in supporting industrial growth, promoting energy efficiency, and contributing to India's transition towards a more sustainable future.
Segmentation Analysis:
By Type
The thermic fluids market is characterized by various types catering to diverse industrial applications. Mineral oil, a traditional segment, retains a significant share owing to its cost-effectiveness and established applications. However, concerns regarding environmental impact and flash point limitations may prompt a gradual shift towards synthetic options. Synthetic thermic fluids, including glycol-based and silicone-based variants, are anticipated to witness significant growth due to their wider operating temperature ranges, improved thermal stability, and environment-friendly properties. Other options, such as heat transfer fluids based on organic esters and molten salts, cater to specific niche applications.
By Applications
Thermic fluids play a vital role across a spectrum of industries. In power generation, they facilitate efficient heat transfer in solar, thermal, and biomass power plants. The chemical and pharmaceutical sectors rely on thermic fluids for heating and cooling processes, while the food processing industry utilizes them to maintain consistent temperatures during frying, drying, and baking. Similarly, in the textile industry, thermic fluids are crucial for drying, dyeing, and finishing processes. Additionally, they find application in sectors like rubber and plastics, paints and coatings, and oil and gas, reflecting their versatility and utility across diverse industries.
By End-User Industries
Process industries, encompassing chemicals, pharmaceuticals, food processing, and textiles, constitute major consumers of thermic fluids due to their extensive heating and cooling requirements. In the power and energy sector, thermic fluids play a pivotal role in solar thermal and biomass power generation. Additionally, infrastructure development projects may incorporate thermic fluids for specific applications, such as asphalt heating. These fluids are available in various temperature ranges, including low, medium, and high, catering to a wide array of industrial processes with different operating temperature requirements.
Segmentations:
By Type
- Mineral Oil
- Water (under pressure)
- PAG and Glycol-based Fluids
- Steam (saturated and superheated)
- Molten Salt
- Others
By Source
- Oxidation
- Thermal Cracking
By Application
- Crude Oil Extraction and Processing Industries
- Natural Gas Processing Plants
- Metal Fabrication and Finishing Plants
- Food Processing Industries
- Rubber and Plastic Industries
- Paper Industries
- Printing Industries
- Textile Industries
- Chemical Industries
- Automobile
- Pharmaceuticals
- Building Materials
- Plywood and laminates
Market Drivers:
Expanding Industrial Base and Infrastructure Development
India’s industrial sector, which includes power, chemicals, pharmaceuticals, food processing, and textiles, is a significant driver for thermic fluids. These industries depend on efficient heat transfer processes for various applications, like heating reactors and drying products. With the expansion of production capacities and the establishment of new facilities, the demand for thermic fluids is expected to rise significantly. For example, in January 2024, industrial production in India increased by 3.8% year over year. Additionally, the gross value added grew by 8.8% in current prices in the years 2020–21 and by 26.6% in the years 2021–22 over the respective previous years. The government’s focus on infrastructure development, including projects in roads, railways, and renewable energy, creates further demand for thermic fluids used in asphalt plants and concrete curing processes. The government of India has embarked on an ambitious journey to revolutionize the country’s infrastructure landscape, aiming to bolster economic growth, enhance connectivity, and improve the quality of life for its citizens.
Growing Adoption in the Renewable Energy Sector
India’s ambitious renewable energy targets are driving the adoption of thermic fluids in solar thermal power plants. These plants utilize thermic fluids to transfer heat captured from sunlight to generate electricity. As India strives to enhance its renewable energy capacity, we anticipate a steady growth in the demand for thermic fluids in this sector, offering substantial prospects for market expansion. For example, India stands 4th globally in renewable energy installed capacity (including large hydro), 4th in wind power capacity, and 4th in solar power capacity. The country has set an enhanced target at COP26 of 500 GW of non-fossil fuel-based energy by 2030. This is the world’s largest expansion plan in renewable energy. India’s installed non-fossil fuel capacity has increased 396% in the last 8.5 years and stands at more than 190.97 GW (including large hydro and nuclear), about 44% of the country’s total capacity (as of February 2024).
Stringent Environmental Regulations and Shift Towards Sustainable Solutions
Increasingly stringent environmental regulations are encouraging industries to transition from conventional fuels like coal to cleaner alternatives. Thermic fluids offer a more eco-friendly heating solution with lower emissions and improved combustion efficiency. This regulatory push for cleaner operations is expected to drive the adoption of thermic fluids across various industries seeking to reduce their environmental footprint.
Rising Focus on Energy Efficiency and Technological Advancements
Thermic fluids provide superior heat transfer efficiency compared to traditional mediums like steam or water, leading to significant energy savings and reduced operational costs for industries. Continuous technological advancements in thermic fluid formulations, including higher thermal stability and wider operating temperature ranges, contribute to their increasing adoption. Moreover, the introduction of synthetic and bio-based thermic fluids offers more sustainable options, aligning with the growing emphasis on environmental consciousness among businesses. This focus on energy efficiency and technological innovation is expected to further propel the market growth of thermic fluids in India.
Market Trends:
- Expanding Industrial Base and Infrastructure Development: The ongoing expansion of India’s industrial sector is driving the demand for efficient and reliable heat transfer solutions. For instance, India’s industrial production increased to 8% in December 2023, up from 2.4% in November. This growth is particularly noticeable in sectors like power, chemicals, pharmaceuticals, and food processing. Thermic fluids, which offer advantages such as precise temperature control and energy efficiency, are becoming a preferred choice for a variety of industrial heating applications.
- Focus on energy efficiency and sustainability: Rising energy costs and growing environmental concerns are prompting industries to adopt energy-efficient technologies. Thermic fluids, compared to traditional heating methods like steam boilers, offer significant energy savings. For example, India, being the world’s third-largest energy-consuming country, has seen its energy use double since 2000, with 80% of demand still being met by coal, oil, and solid biomass. Additionally, the availability of synthetic thermic fluids with lower environmental impact is gaining traction as sustainability considerations become more prominent. This is reflected in the fact that India’s energy development has seen a massive expansion in renewable sources of energy, led by solar power.
- Government Initiatives and Policies: The Indian government's focus on infrastructure development and initiatives promoting "Make in India" are creating favorable conditions for the thermic fluids market. Additionally, government regulations aimed at reducing industrial emissions and promoting energy efficiency are expected to further propel the adoption of thermic fluids.
- Technological Advancements and Product Diversification: Manufacturers are continuously developing new and improved thermic fluids with enhanced properties like wider operating temperature ranges, improved thermal stability, and better compatibility with different heating systems. This diversification caters to the specific needs of various industries, leading to wider market penetration.
- Growing Adoption in the Renewable Energy Sector: The increasing focus on renewable energy sources like solar and thermal power plants is creating new opportunities for thermic fluids. These fluids play a crucial role in heat transfer processes within these renewable energy systems, contributing to their overall efficiency.
Market Restraints and Challenges:
- Price Fluctuations of Raw Materials: Thermic fluids are derived from various raw materials like crude oil, natural gas, and glycols. The Indian market is heavily reliant on imports for these base materials. Fluctuations in global oil prices and supply chain disruptions can significantly impact the cost of thermic fluids, making them less affordable for end users in certain sectors. This price volatility can create uncertainty and discourage investment in thermic fluid-based heating systems.
- Lack of Awareness and Knowledge Gaps: Although thermic fluids offer several advantages over traditional heating methods, there is a lack of widespread awareness about their benefits, particularly among smaller and medium-sized enterprises (SMEs). Additionally, knowledge gaps regarding the selection, operation, and maintenance of thermic fluid systems can be a barrier to adoption. Overcoming these knowledge gaps requires targeted educational initiatives by industry stakeholders to promote the understanding and benefits of thermic fluids.
- Stringent Environmental Regulations and Disposal Challenges: Environmental regulations regarding emissions and waste disposal are becoming increasingly stringent in India. Thermic fluids, if not managed properly, can pose environmental concerns related to potential leaks and improper disposal. Developing cost-effective and environmentally friendly methods for thermic fluid disposal and ensuring adherence to evolving regulations are crucial aspects of market growth. Investment in research and development of biodegradable or recyclable thermic fluids would be a significant step forward.
- Competition from Established Heating Technologies: Thermic fluids face competition from well-established heating technologies such as electrical resistance heating, steam boilers, and furnaces. These traditional methods often have lower upfront costs, creating a hurdle for thermic fluids, especially for price-sensitive industries. Highlighting the long-term cost benefits, energy efficiency, and improved process control offered by thermic fluids can help overcome this challenge.
- Skilled Workforce Shortage: The operation and maintenance of thermic fluid systems require a skilled workforce with proper training and knowledge. A lack of readily available skilled professionals can pose challenges for industries considering adopting thermic fluid systems. Initiatives to develop training programs and educational pathways focused on thermic fluid technology can help address this workforce gap.
Key player:
- Bharat Petroleum Corporation Limited (India)
- Dow (U.S.)
- Eastman Chemical Company (U.S.)
- Huntsman International LLC (U.S.)
- Paras Lubricants Ltd. (India)
- Chevron Corporation (U.S.)
- Indian Oil Corporation Limited (India)
- Exxon Mobil Corporation (U.S.)
- HP Lubricants (India)
- Thermotech Systems Ltd. (India)
Recent Developments:
- In September 2022, Bozzler Energy Pvt. Ltd. announced that the company would be showcasing its new designs of thermal fluid heaters at the Boiler India 2022 exhibition organized by Orange Beak Technologies, which was to be held at the CIDCO Exhibition Centre, Navi Mumbai. The new designs are expected to be highly suitable for environmental health and eco-friendly.
- In August 2022, Shell Lubricants announced that the company would launch electric vehicle battery coolants (heat transfer fluids) in India after being attracted by the country's electric vehicle market. As stated, the company will initially import electric vehicle thermic fluids but manufacture the product locally later in the country.
Regional Analysis:
Western Region (Maharashtra, Gujarat): This region is anticipated to hold the largest market share due to the presence of a well-established industrial base, particularly in chemicals, pharmaceuticals, and textiles. Additionally, government initiatives promoting industrial development in this region are expected to further propel thermic fluid demand.
Northern Region (Delhi, Haryana, Punjab): The Northern region is another key market driven by the presence of strong automotive and manufacturing sectors. Growing investments in infrastructure development are also anticipated to contribute to market growth in this region.
Southern Region (Tamil Nadu, Karnataka, and Andhra Pradesh): The Southern region is expected to experience significant growth due to the flourishing presence of automotive, aerospace, and food processing industries. Increasing focus on renewable energy generation in this region might also drive demand for thermic fluids used in solar thermal power plants.
Eastern Region (West Bengal, Odisha, and Jharkhand): The Eastern region is projected to witness steady growth, fueled by the development of coal-fired power plants and increasing investments in infrastructure projects. However, the growth pace might be slightly slower compared to the other regions due to a relatively less developed industrial base.
Future Outlook:
- Expanding Industrial Base: The ongoing growth and diversification of the Indian manufacturing sector, particularly in sectors like chemicals, pharmaceuticals, food processing, and textiles, will propel the demand for thermic fluids for efficient process heating.
- Government Initiatives: Government initiatives promoting "Make in India" and infrastructure development are expected to create new avenues for thermic fluid applications, further stimulating market growth.
- Rising Focus on Energy Efficiency: Growing emphasis on energy conservation and cost reduction in industries will drive the adoption of energy-efficient thermic fluids, creating opportunities for advanced synthetic thermic fluid products.
- Stringent Environmental Regulations: Increasingly stringent environmental regulations regarding emissions will encourage the use of cleaner-burning thermic fluids, such as synthetic and bio-based fluids, impacting market dynamics.
- Technological Advancements: Advancements in thermic fluid formulations with improved heat transfer efficiency, wider operating temperature ranges, and enhanced thermal stability will lead to the development of more application-specific thermic fluids.
- Enhanced Customer Awareness: Growing awareness among industries regarding the benefits of thermic fluids, including operational efficiency, safety, and lifecycle costs, will influence market growth positively.
- E-commerce and Online Sales: The increasing adoption of e-commerce platforms for thermic fluid sales is expected to improve market reach and accessibility for both suppliers and customers.
- Focus on After-Sales Services: Increased emphasis on providing comprehensive after-sales services, including equipment maintenance and technical support, will be crucial for market players to gain a competitive edge.
- Growing Demand for Bio-Based Thermic Fluids: Rising environmental concerns and the push for sustainable solutions will likely increase the demand for bio-based thermic fluids, presenting an opportunity for market expansion.
- Consolidation in the Market: The market may witness consolidation as established players expand their product portfolios and regional presence, while niche players focus on specialized applications and innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Indian Thermic Fluids market between 2023 and 2032?
What factors are driving the growth of the Indian thermic fluids market?
Who are the major players in the Indian thermal fluid market?
How is the availability of thermal fluids expanding, and through what channels?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Thermic Fluids Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Thermic Fluids Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 455.38 million → 2032: USD 1171.05 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Thermic Fluids Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Thermic Fluids Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Thermic Fluids Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Thermic Fluids Market Drivers
- 3.3 India Thermic Fluids Market Restraints & Challenges
- 3.4 India Thermic Fluids Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Thermic Fluids Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Thermic Fluids Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Thermic Fluids category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Thermic Fluids Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Thermic Fluids Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Thermic Fluids market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Thermic Fluids Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Thermic Fluids Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Thermic Fluids Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Thermic Fluids (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Thermic Fluids Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Thermic Fluids Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Thermic Fluids Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Thermic Fluids Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Thermic Fluids Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Thermic Fluids Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Thermic Fluids Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Thermic Fluids Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Thermic Fluids Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
