| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Screen Printing Market Size 2024 | USD 671.23 Million |
| Industrial Screen Printing Market, CAGR | 7.50% |
| Industrial Screen Printing Market Size 2032 | USD 1,286.91 Million |
Market Overview
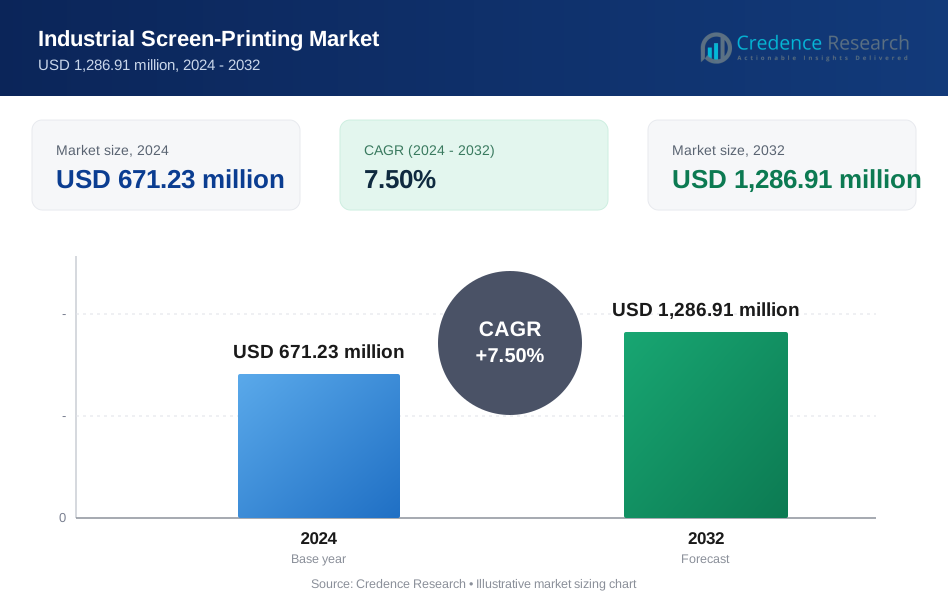
The Industrial Screen Printing Market is projected to grow from USD 671.23 million in 2024 to an estimated USD 1,286.91 million by 2032, with a compound annual growth rate (CAGR) of 7.50% from 2025 to 2032. This growth is driven by increasing demand across various industries, including automotive, electronics, and packaging, where screen printing is used for its precision, versatility, and cost-effectiveness in producing high-quality prints on different surfaces.
Key drivers of the market include the growing demand for custom and high-quality printed materials, the expansion of the electronics industry, and the increasing adoption of screen printing in packaging applications. Additionally, advancements in screen printing technology, such as automated and digital printing systems, are improving operational efficiency and reducing costs, further propelling market growth. The rising trend for environmentally friendly and sustainable printing methods is also influencing the market, with a growing preference for eco-friendly inks and materials.
Geographically, North America and Europe are the dominant regions in the industrial screen printing market due to the strong presence of key manufacturers and a growing demand for high-quality prints in industries such as automotive and electronics. Meanwhile, the Asia Pacific region is expected to experience the highest growth rate, driven by the rapid industrialization, increased manufacturing activities, and rising demand for screen printing in packaging, textiles, and electronics. Key players in this market include DuPont, Epson, and Screen USA.
Market Insights
- The Industrial Screen Printing Market is projected to grow from USD 671.23 million in 2024 to USD 1,286.91 million by 2032, with a CAGR of 7.50% from 2025 to 2032, driven by increasing demand in industries like automotive, electronics, and packaging.
- The growth in demand for high-quality, customized prints, particularly in automotive and electronics, is a key driver of market expansion. Advancements in screen printing technology also contribute to greater efficiency and reduced operational costs.
- High initial costs of equipment and maintenance expenses pose significant barriers to market growth, especially for smaller businesses or startups looking to adopt screen printing technology.
- North America holds a significant share of the market due to strong manufacturing sectors and high demand for precision printing solutions in industries such as automotive and electronics.
- Europe follows closely with a robust industrial base and a high demand for sustainable printing solutions, driven by increasing environmental regulations and the growth of eco-friendly packaging solutions.
- Asia Pacific is expected to experience the highest growth, driven by rapid industrialization, rising manufacturing activities, and a growing demand for screen printing in textiles, packaging, and electronics.
- The increasing shift towards sustainable practices, including the use of eco-friendly inks and materials, is positively impacting the industrial screen printing market, aligning with global environmental trends and regulations.
Report Scope
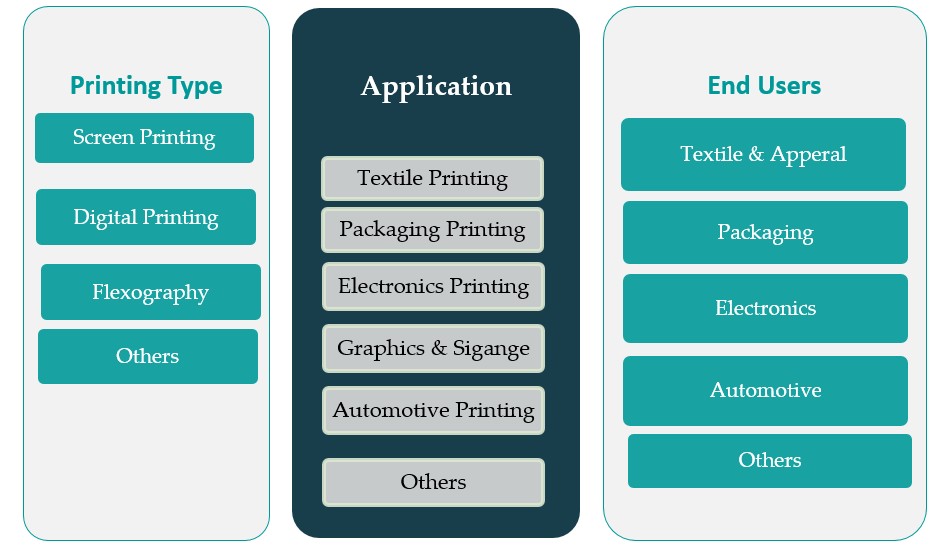
This report segments the Global Industrial Screen Printing Market as follows:
Market Drivers
Growing Demand for Customization and High-Quality Prints
The increasing demand for customized and high-quality printed materials across various industries is one of the primary drivers fueling the growth of the industrial screen printing market. According to a survey, 59% of internet buyers are more likely to purchase a brand or merchant if product customization is available. Additionally, 75% of Gen Z consumers are inclined to buy products that can be customized. For instance, industrial screen printing provides the capability to print on a wide variety of substrates, including glass, metal, plastics, and textiles, making it ideal for producing customized designs. This is particularly significant in industries such as automotive, electronics, and packaging, where branding and aesthetics are essential. Furthermore, screen printing can achieve high resolution and intricate designs, which are vital for product differentiation and consumer appeal. As companies increasingly prioritize product personalization to stand out in competitive markets, the demand for advanced screen printing solutions is expected to grow.
Technological Advancements in Screen Printing Equipment
Technological advancements in screen printing equipment are playing a significant role in driving the industrial screen printing market. For instance, automated printing systems have been shown to reduce human error by up to 30% while increasing production capacity. Digital screen printing technology offers the flexibility to print on a wide range of substrates and to handle smaller batch sizes, making it an attractive option for businesses that require both high-quality and cost-effective solutions. These technological innovations are lowering operational costs, enhancing productivity, and improving overall print quality, thus driving the adoption of industrial screen printing across different sectors.
Expanding Applications in Electronics and Automotive Industries
The growing demand for screen printing in the electronics and automotive industries is a crucial driver for the market. In the electronics industry, screen printing is extensively used for printing conductive inks on printed circuit boards (PCBs), display screens, and touch panels. The increasing complexity of electronic devices and the continuous advancements in electronics manufacturing technologies are driving the demand for precise and high-quality printing solutions. Similarly, the automotive industry relies heavily on screen printing for producing durable and high-quality prints on various automotive components such as dashboards, displays, and control panels. As the demand for electronics and automobiles continues to rise globally, the need for industrial screen printing solutions in these industries is expected to grow at a significant pace.
Sustainability and Eco-Friendly Printing Solutions
Sustainability is a growing concern in many industries, and this trend is also influencing the industrial screen printing market. With increasing consumer demand for eco-friendly and sustainable products, manufacturers are increasingly focusing on reducing their environmental footprint. Industrial screen printing offers several advantages in this regard, as it supports the use of environmentally friendly inks, such as water-based and UV-curable inks, which have low volatile organic compound (VOC) emissions compared to traditional solvent-based inks. Additionally, screen printing processes are known for their minimal waste generation and energy efficiency, further contributing to sustainability efforts. As governments and regulatory bodies implement stricter environmental regulations, businesses are being forced to adopt more sustainable production methods. This shift towards eco-friendly printing solutions is driving the demand for screen printing technologies that minimize environmental impact while maintaining high-quality output.
Market Trends
Adoption of Digital and Hybrid Printing Technologies
The integration of digital and hybrid printing technologies into industrial screen printing processes is one of the key trends driving market evolution. Hybrid screen printing combines traditional analog techniques with digital technologies, offering the flexibility of digital printing while maintaining the durability and vibrancy of screen printing. For instance, a study by the European Printing Association in 2024 revealed that 68% of packaging companies in Europe adopted hybrid printing technologies to enhance production efficiency and design flexibility. Digital technologies allow for direct-to-substrate printing, which reduces setup times and enhances printing accuracy, making it an attractive option for small to medium-sized production runs. This hybrid approach also improves design flexibility, enabling the printing of more intricate and customized designs on a wider range of substrates. As the demand for personalized and short-run products continues to grow, the adoption of digital and hybrid printing solutions is expected to accelerate, enabling manufacturers to meet diverse customer needs while optimizing efficiency and reducing costs.
Shift Toward Eco-Friendly and Sustainable Inks
Sustainability continues to be a significant trend in the industrial screen printing market, with a growing emphasis on eco-friendly inks and materials. Traditional screen printing often involves the use of solvent-based inks, which can have a detrimental environmental impact. For example, a report by the Global Ink Manufacturers Association in 2025 highlighted that 72% of industrial screen printing companies worldwide transitioned to water-based and UV-curable inks to reduce VOC emissions and comply with stricter environmental regulations. These inks are low in volatile organic compounds (VOCs), reducing emissions and improving air quality during production. Additionally, the growing emphasis on reducing waste and energy consumption is prompting screen printing companies to adopt more sustainable production methods. The shift toward these greener alternatives is not only helping to reduce environmental impact but also responding to market demand for products that are environmentally conscious, which is a key selling point in industries such as packaging, textiles, and consumer goods.
Advancements in Automation and Smart Manufacturing
The trend of automating screen printing processes is reshaping the market by increasing production efficiency, reducing costs, and improving precision. Automation in screen printing involves the integration of robotic arms, automated presses, and advanced curing systems to streamline the printing process. These innovations help to reduce labor costs, minimize human error, and improve repeatability, ensuring consistent high-quality outputs for mass production. Smart manufacturing, including the use of Internet of Things (IoT) technologies, is also gaining traction in industrial screen printing. IoT-enabled systems allow for real-time monitoring, predictive maintenance, and remote operation, helping manufacturers to optimize production and minimize downtime. As demand for faster production and improved operational efficiency rises, the adoption of automated and smart manufacturing technologies is expected to continue growing, making industrial screen printing more cost-effective and scalable.
Increased Focus on Customization and Personalized Products
As consumer demand for unique and personalized products continues to rise, customization is becoming a prominent trend in the industrial screen printing market. This shift is driven by industries such as apparel, packaging, and consumer electronics, where companies are increasingly focusing on providing tailored solutions to meet specific customer preferences. Industrial screen printing offers the flexibility to produce intricate, high-quality designs on a wide range of substrates, including textiles, plastics, metals, and glass. The ability to print complex designs, logos, and custom graphics with high precision makes screen printing ideal for personalized products, from custom-printed clothing and promotional items to specialized packaging. As businesses seek ways to differentiate themselves and enhance brand identity, the demand for industrial screen printing services that offer unique and customizable print solutions is expected to grow, further driving innovation and market expansion in this area.
Market Challenges
High Operational Costs and Equipment Maintenance
One of the key challenges facing the industrial screen printing market is the high operational costs associated with the technology. While screen printing offers high-quality, durable prints, the equipment and materials involved in the process can be costly, particularly for large-scale operations. For instance, industry reports indicate that the cost of advanced automated screen printing machines can range from $50,000 to $250,000, depending on the features and capabilities. Additionally, ongoing maintenance and repairs are essential to ensure the smooth operation of the equipment, which adds to the total cost of production. Regular calibration and replacement of parts like screens, squeegees, and curing units are necessary to maintain consistent quality, with annual maintenance costs often exceeding $5,000 for mid-sized operations. For smaller businesses or startups, these high capital expenditures can present a significant financial barrier, making it difficult for them to compete with larger, more established players. Furthermore, labor costs associated with managing and operating screen printing systems, especially in environments requiring a high level of technical skill, can add significantly to the overall cost burden. As businesses strive to maintain profitability while managing these costs, the challenge remains to optimize the efficiency of screen printing systems to reduce expenses while still delivering high-quality results.
Limited Flexibility in Substrate Variety and Design Complexity
Another significant challenge for the industrial screen printing market is the limitation in substrate versatility and design complexity. Although screen printing is capable of producing high-quality, durable prints on various materials, it is not always suitable for every type of substrate. The technology is best suited for flat or relatively simple shapes, and it faces challenges when attempting to print on uneven surfaces, such as cylindrical or irregularly shaped objects. This limits its application in industries that require a more diverse range of materials and designs, such as aerospace or certain consumer electronics, where precision and adaptability are crucial. Additionally, while screen printing can produce intricate designs, it is often limited by the resolution and detail that can be achieved, especially in comparison to other technologies such as digital printing. This challenge can affect industries where extremely fine, detailed images are required, such as in high-end packaging or microelectronics. As demand for more complex and multi-layered designs increases, companies may find it necessary to invest in complementary technologies to overcome the limitations of traditional screen printing, thereby increasing costs and reducing the technology’s competitive edge in certain applications.
Market Opportunities
Expansion in Emerging Markets
One of the key opportunities in the industrial screen printing market lies in the expansion of manufacturing activities in emerging markets, particularly in Asia-Pacific, Latin America, and Africa. As these regions experience rapid industrialization, there is a growing demand for high-quality, cost-effective printing solutions across various industries such as automotive, electronics, textiles, and packaging. The increasing shift towards mass production in these markets presents significant growth opportunities for screen printing companies. Furthermore, the adoption of industrial screen printing technology in these regions is being driven by the need for precision printing on a variety of materials, such as plastics, metals, and textiles. As businesses in these regions aim to enhance their manufacturing processes and meet global quality standards, industrial screen printing offers a versatile, efficient, and environmentally friendly option. This expansion in emerging markets is expected to fuel the demand for advanced screen printing solutions, presenting an opportunity for both local players and global companies to establish a stronger presence and tap into the growing market potential.
Advancements in Eco-Friendly Printing Solutions
Another significant opportunity in the industrial screen printing market lies in the growing demand for eco-friendly and sustainable printing solutions. As consumers and industries alike place greater emphasis on environmental sustainability, there is an increasing demand for printing technologies that minimize waste and reduce environmental impact. Industrial screen printing, with its ability to use water-based and UV-curable inks, offers a viable solution for meeting these sustainability demands. Companies that invest in the development and adoption of eco-friendly inks, along with energy-efficient printing processes, can differentiate themselves in the market by appealing to environmentally conscious consumers and businesses. Moreover, with stricter regulations on emissions and waste management, the transition to greener printing solutions presents an opportunity for screen printing companies to align with global sustainability trends and capture new customer segments. This shift toward eco-friendly practices is not only beneficial for the environment but also positions companies to stay ahead of evolving regulatory and market demands.
Market Segmentation Analysis
By Printing Type
The industrial screen printing market is segmented by printing type into screen printing, digital printing, flexography, and others. Screen printing holds the largest share in the market due to its versatility, high-quality output, and cost-effectiveness, especially for large-volume production runs. It is commonly used for printing on various substrates, including textiles, plastics, and metals. Digital printing has gained traction in the market due to its ability to offer high-quality, intricate designs and customization for smaller batch sizes. This technology is especially favored in industries that require precise and detailed graphics, such as packaging and promotional products. Flexography, although primarily used in packaging, is also increasingly being adopted in the screen printing market due to its efficiency in handling high-speed and high-volume production. Other printing methods, such as pad printing, are used in niche applications but account for a smaller share of the market.
By Application
The industrial screen printing market is divided by application into textile printing, packaging printing, electronics printing, graphics & signage, automotive printing, and others. Textile printing is one of the largest applications of industrial screen printing, driven by the demand for high-quality, durable prints on garments, home textiles, and promotional products. Packaging printing is also a significant segment, as screen printing is widely used for printing labels, cartons, and flexible packaging materials. In electronics, screen printing is employed for applications such as printed circuit boards (PCBs) and displays, where precision and high resolution are crucial. The graphics & signage segment benefits from the ability of screen printing to produce vibrant and long-lasting prints on various materials, including vinyl, metal, and glass. Automotive printing is another growing segment, with screen printing being used for dashboards, control panels, and other vehicle components. The 'others' category includes niche applications such as medical devices, ceramics, and promotional items.
Segments
Based on Printing Type
- Screen-Printing
- Digital Printing
- Flexography
- Others
Based on Application
- Textile Printing
- Packaging Printing
- Electronics Printing
- Graphics & Signage
- Automotive Printing
- Others
Based on End User
- Textile & Apparel
- Industrial
- Electronics
- Automotive
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (35%)
North America dominates the industrial screen printing market, holding the largest market share of approximately 35%. This is largely attributed to the region’s established manufacturing base and the high demand for precision printing in industries such as electronics, automotive, and packaging. The United States, in particular, is home to numerous manufacturers who require high-quality, durable printed materials, making screen printing a vital part of their production processes. Additionally, the trend toward automation and the adoption of eco-friendly printing technologies are driving the growth of the market in this region. Investments in research and development and the presence of leading printing equipment manufacturers further contribute to North America’s dominance in the market.
Europe (30%)
Europe follows North America, holding around 30% of the global market share. The demand for industrial screen printing in Europe is driven by its mature industries, particularly in electronics, automotive, and textiles. Countries like Germany, the UK, and France are leading contributors, with strong automotive and electronics sectors that heavily rely on screen printing for creating intricate designs and functional components. The growing trend for sustainable and eco-friendly printing methods also boosts the adoption of screen printing in this region, especially in packaging applications. Furthermore, the presence of several well-established screen printing equipment manufacturers in Europe supports market growth.
Key players
- M&R Printing Equipment
- Vastex International
- R. Screen-Printing Supplies
- Uflex Ltd
- Riley Hopkins
- MHM Maschinenbau
- Sias Print
- GCC LaserPro
- Klieverik
- Lawson Screen & Digital Products
- DECO Technology Group
Competitive Analysis
The industrial screen printing market is characterized by intense competition, with key players focusing on innovation, product quality, and technological advancements to maintain their market share. M&R Printing Equipment and Vastex International are leading manufacturers, offering a wide range of high-performance screen printing equipment. These companies are known for their advanced automation features, improving production efficiency and reducing operational costs. Uflex Ltd stands out in the packaging segment with its robust portfolio of printing solutions tailored to flexible packaging. Meanwhile, MHM Maschinenbau and Riley Hopkins have a strong presence in textile printing, focusing on high-quality, durable prints for the fashion and apparel industries. In the emerging digital segment, companies like Lawson Screen & Digital Products and Sias Print are leading the adoption of digital screen printing solutions, expanding their capabilities for customized, small-batch production. As technological innovations continue, the competition in this market is expected to intensify.
Recent Developments
- In March 2025, M&R announced the release of the POLARIS S4 Digital Pretreat Unit, powered by Xaar’s inkjet technology, as an integral component of the POLARIS S4 industrial DTG platform.
- In June 2024, Vastex introduced two new conveyor dryers designed specifically for Direct-to-Film (DTF) printing applications. These dryers are engineered to remove toxic ethylene glycol vapors emitted during the curing process, thereby enhancing workplace safety and ensuring compliance with health regulations.
- In February 2025, Lawson Screen & Digital Products merged with Workhorse Products. This strategic merger combined the strengths of both companies to expand product offerings, enhance customer service, and foster innovation in the screen and digital printing industry.
Market Concentration and Characteristics
The industrial screen printing market exhibits a moderate to high level of concentration, with several leading players dominating key segments such as equipment manufacturing, ink production, and printing services. Companies like M&R Printing Equipment, Vastex International, and MHM Maschinenbau hold significant market shares, offering a wide range of high-quality, specialized products tailored to various industries including textiles, automotive, electronics, and packaging. These key players are continuously innovating to improve efficiency, reduce costs, and meet the growing demand for customized and eco-friendly printing solutions. However, the market also features a considerable number of small and medium-sized enterprises (SMEs) that provide specialized solutions, especially in niche applications. The market is characterized by technological advancements, such as the integration of automation, digital printing capabilities, and environmentally sustainable practices, which are reshaping the competitive landscape and pushing companies to invest in R&D to maintain their market position.
Report Coverage
The research report offers an in-depth analysis based on Printing Type, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The industrial screen printing market will continue to witness significant advancements in automation and digital integration, improving production efficiency and print precision.
- As consumer demand for personalized products increases, screen printing will play a vital role in producing high-quality, tailored designs for a variety of industries.
- With growing environmental concerns, the adoption of eco-friendly inks and sustainable practices in screen printing will expand, aligning with stricter regulations and consumer preferences for green solutions.
- Rapid industrialization and urbanization in emerging markets, especially in Asia Pacific, will drive increased demand for industrial screen printing solutions, particularly in packaging and textiles.
- The integration of hybrid screen printing systems, combining digital and traditional methods, will cater to both high-volume and custom orders, improving flexibility and reducing lead times.
- The demand for high-precision printing in the electronics and automotive sectors will continue to grow, with screen printing being essential for manufacturing components like circuit boards and dashboards.
- The rise of Industry 4.0 and smart manufacturing will lead to the adoption of IoT-enabled screen printing systems, improving operational efficiency, real-time monitoring, and predictive maintenance.
- The demand for smaller batch sizes, driven by the growth of e-commerce and customization trends, will encourage more businesses to adopt screen printing for cost-effective, small-run production.
- Companies will continue to invest heavily in research and development to improve screen printing technologies, focusing on enhancing printing accuracy, substrate versatility, and ink quality.
- As competition intensifies, there may be increased consolidation in the market, with smaller players merging or being acquired by larger companies to gain access to advanced technologies and expand market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Customization and High-Quality Prints
Industries such as automotive, electronics, and packaging increasingly require customized and high-quality printed materials for branding, differentiation, and consumer appeal. Screen printing's versatility in handling various substrates and producing intricate designs makes it a preferred solution for these needs.
Technological Advancements in Screen Printing Equipment
The introduction of automated and digital screen printing systems has improved operational efficiency, reduced human error, and enabled cost-effective production of both large and small batches. These advancements are making screen printing more accessible and attractive to a wider range of industries.
Expanding Applications in Electronics and Automotive Industries
Screen printing is essential for producing precise, durable prints on electronic components like PCBs and automotive parts such as dashboards and control panels. As these industries grow and require more complex, high-resolution prints, the demand for industrial screen printing rises.
Sustainability and Eco-Friendly Printing Solutions
With increasing regulatory and consumer focus on sustainability, the adoption of eco-friendly inks and energy-efficient screen printing processes is accelerating. This shift not only helps companies comply with environmental standards but also appeals to environmentally conscious customers, driving further market growth.
Expansion in Emerging Markets
Rapid industrialization and manufacturing growth in regions like Asia Pacific, Latin America, and Africa are creating new opportunities for industrial screen printing. These markets are adopting advanced printing technologies to meet global quality standards and support mass production, fueling overall market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Industrial Screen Printing Market in 2023 and 2032?
What are the key drivers of the Industrial Screen Printing Market?
How are technological advancements impacting the Industrial Screen Printing Market?
Which regions are expected to lead the Industrial Screen Printing Market?
What are some key players in the Industrial Screen Printing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Textile & Apparel
- 1.2.2 Industrial
- 1.2.3 Electronics
- 1.2.4 Automotive
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Textile Printing
- 1.3.2 Packaging Printing
- 1.3.3 Electronics Printing
- 1.3.4 Graphics & Signage
- 1.3.5 Automotive Printing
- 1.3.6 Others
- 1.4 By Printing Type
- 1.4.1 Screen-Printing
- 1.4.2 Digital Printing
- 1.4.3 Flexography
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 671.23 million → 2032: USD 1,286.91 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industrial Screen-Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industrial Screen-Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industrial Screen-Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industrial Screen-Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industrial Screen-Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industrial Screen-Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industrial Screen-Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industrial Screen-Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 671.23 million → 2032: USD 1,286.91 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industrial Screen-Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Textile & Apparel
- 12.3.7.2 Industrial
- 12.3.7.3 Electronics
- 12.3.7.4 Automotive
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Textile Printing
- 12.4.7.2 Packaging Printing
- 12.4.7.3 Electronics Printing
- 12.4.7.4 Graphics & Signage
- 12.4.7.5 Automotive Printing
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Printing Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Screen-Printing
- 12.5.7.2 Digital Printing
- 12.5.7.3 Flexography
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industrial Screen-Printing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Industrial Screen-Printing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Industrial Screen-Printing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Industrial Screen-Printing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 M&R Printing Equipment
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vastex International
- 18.4 Uflex Ltd
- 18.5 Riley Hopkins
- 18.6 MHM Maschinenbau
- 18.7 Sias Print
- 18.8 GCC LaserPro
- 18.9 Klieverik
- 18.10 Lawson Screen & Digital Products
- 18.11 DECO Technology Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.