
Market Overview:
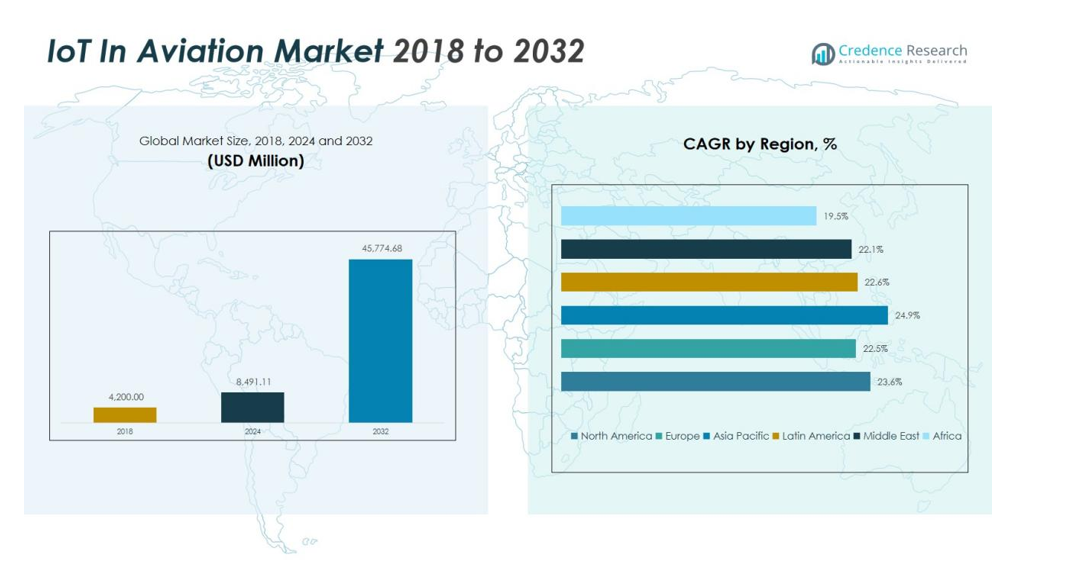
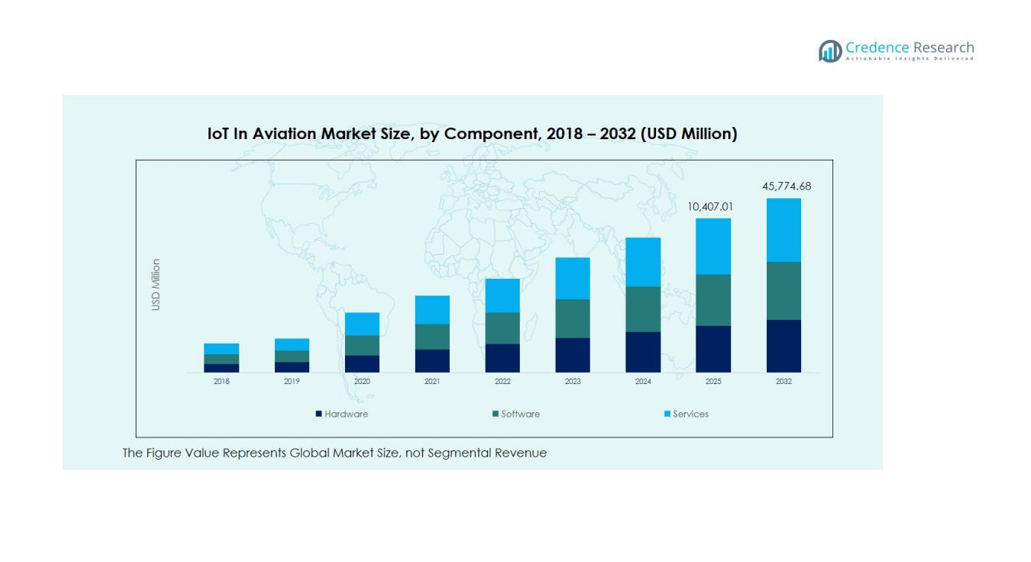
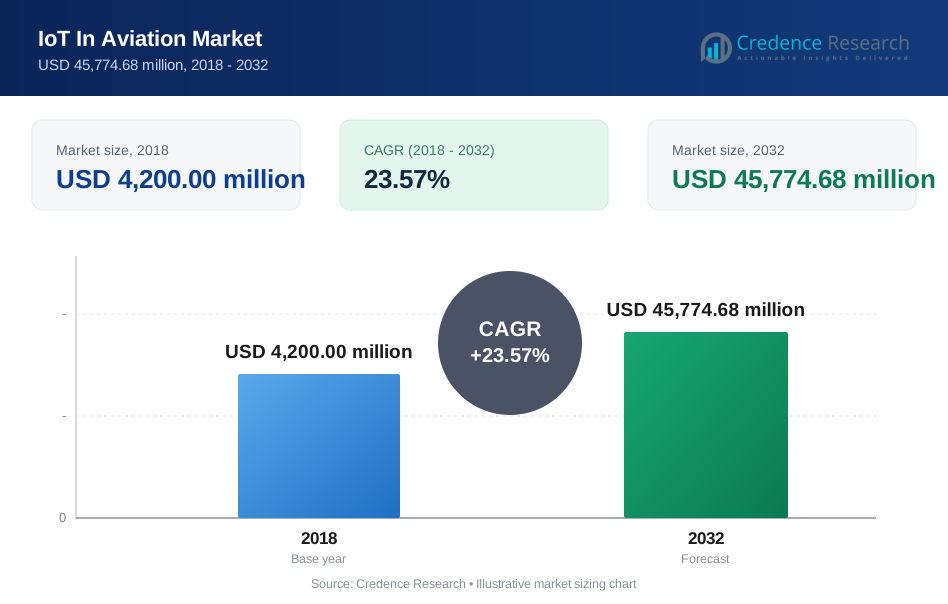
The Global IoT In Aviation Market size was valued at USD 4,200.00 million in 2018 to USD 8,491.11 million in 2024 and is anticipated to reach USD 45,774.68 million by 2032, at a CAGR of 23.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| IoT in Aviation Market Size 2024 | USD 8,491.11 million |
| IoT in Aviation Market, CAGR | 23.57% |
| IoT in Aviation Market Size 2032 | USD 45,774.68 million |
Key factors fueling the market include rising demand for real-time monitoring, predictive maintenance, and optimized asset utilization. Airlines are increasingly adopting IoT-based systems for improved flight safety, fuel efficiency, and ground operations. The growing use of 5G networks, artificial intelligence, and cloud platforms enhances the scalability and performance of IoT solutions. Continuous investment in smart airport infrastructure further accelerates technology penetration across aviation operations.
North America dominates the market due to its advanced aviation infrastructure and strong presence of IoT solution providers. Europe follows, supported by early adoption of digital technologies and extensive smart airport programs. The Asia-Pacific region is expected to record the fastest growth, driven by rising passenger traffic, expanding airline fleets, and increased investments in aviation modernization across India, China, and Southeast Asia.
Market Insights:
- The Global IoT in Aviation Market was valued at USD 4,200.00 million in 2018, reached USD 8,491.11 million in 2024, and is projected to achieve USD 45,774.68 million by 2032, growing at a CAGR of 23.57% during the forecast period.
- North America holds the largest share of about 35% due to advanced aviation infrastructure, early IoT adoption, and strong presence of global technology providers.
- Europe accounts for nearly 25% of the market, driven by established aviation hubs, digital transformation in air traffic management, and leading aircraft manufacturers such as Airbus and Rolls-Royce.
- Asia Pacific represents around 28% and is the fastest-growing region, supported by rising air passenger traffic, rapid airport modernization, and growing government investments in digital aviation across China, India, and Japan.
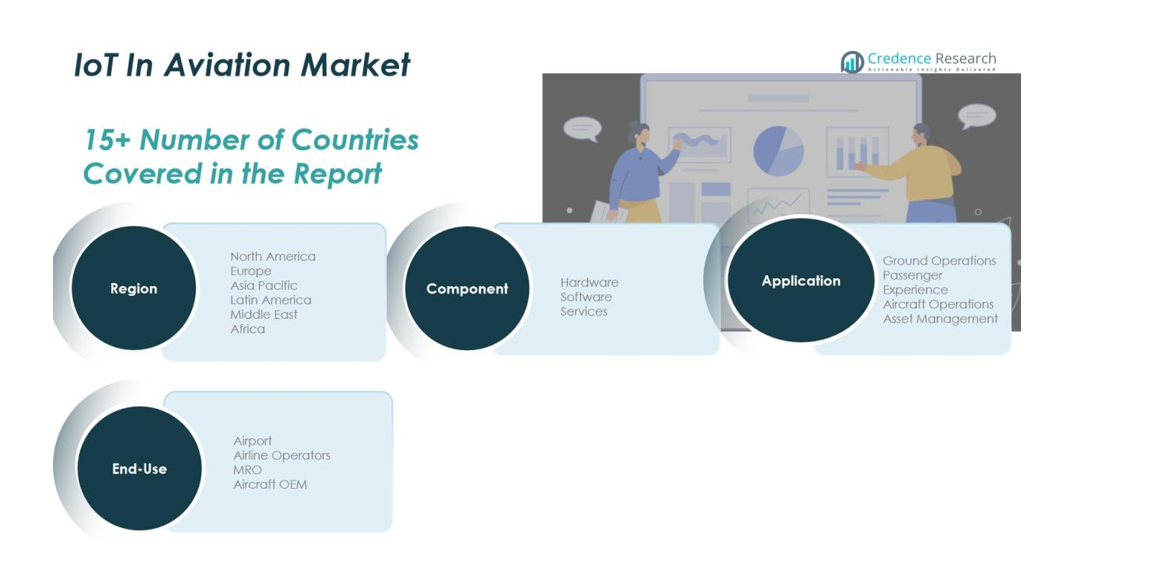
- Hardware leads the component segment with over 45% share, followed by software and services, while airports dominate the end-use segment with nearly 40% share due to large-scale smart infrastructure investments.
Market Drivers:
Rising Demand for Real-Time Data and Predictive Maintenance
The Global IoT in Aviation Market is driven by the growing adoption of connected systems that enable real-time data collection, monitoring, and analysis. Airlines use IoT technologies to track aircraft performance and identify maintenance needs before failures occur. This predictive maintenance approach reduces downtime, improves safety, and optimizes operational efficiency. It helps airlines minimize costs associated with unscheduled repairs and ensures better asset utilization across fleets.
- For instance, Delta Air Lines integrated Airbus’s Skywise platform across its A320 and A330 fleets for real-time monitoring of aircraft data, enabling predictive maintenance.
Expansion of Smart Airport Infrastructure and Passenger Experience Solutions
Airports are investing heavily in IoT-based smart infrastructure to enhance operational control and passenger satisfaction. Smart sensors, automated baggage systems, and connected terminals improve flow management and reduce delays. The integration of IoT with biometric and mobile systems also streamlines security checks and boarding procedures. It strengthens airport management capabilities and supports a seamless passenger experience across terminals and gates.
- For Instance, Dubai International Airport has implemented an IoT-enabled crowd monitoring system as part of ongoing technology initiatives, which has been shown to reduce wait times in waiting areas by 30%. The airport features a total of 127 smart gates across all terminals.
Integration of Advanced Connectivity and Artificial Intelligence
The deployment of 5G networks and AI-driven analytics accelerates the evolution of IoT applications in aviation. Enhanced network speed and lower latency enable faster data transfer between aircraft, ground systems, and cloud platforms. AI algorithms process large datasets from connected devices to optimize fuel consumption and flight scheduling. It ensures faster decision-making and strengthens situational awareness in critical aviation operations.
Growing Emphasis on Safety, Efficiency, and Sustainability Goals
Airlines and airports are adopting IoT technologies to meet global safety and sustainability targets. Connected sensors help monitor aircraft systems, runway conditions, and environmental factors in real time. These insights support safer flight operations and efficient energy usage. It also enables aviation companies to align with international emission-reduction standards while maintaining profitability and reliability.
Market Trends:
Adoption of Smart and Connected Aircraft Systems
The Global IoT in Aviation Market is witnessing a strong shift toward smart aircraft systems that enable seamless data exchange between onboard and ground operations. Airlines are deploying advanced IoT sensors to monitor engine health, fuel consumption, and environmental conditions. These connected systems improve flight safety and operational reliability by providing real-time insights. The integration of IoT platforms with digital twins enhances aircraft design, maintenance, and predictive performance modeling. It helps manufacturers and operators reduce operating costs and extend aircraft life cycles. The use of in-flight connectivity solutions also supports better communication between pilots, crew, and control centers.
- For Instance, Delta Air Lines partnered with Airbus to implement the Skywise predictive maintenance platform on its A320 and A330 aircraft fleets, covering approximately 400 airplanes.
Growing Focus on Passenger-Centric IoT Applications and Sustainability
Airlines are emphasizing IoT-based passenger engagement tools to improve travel experiences and operational efficiency. Smart seats, digital cabin management, and mobile-connected services provide personalized travel options and comfort. IoT-enabled tracking of luggage, check-in, and boarding systems ensures smoother and faster airport operations. It allows airlines to deliver real-time updates to passengers and minimize service delays. The growing demand for sustainable aviation practices is pushing companies to deploy IoT for optimizing resource use and reducing carbon emissions. Energy-efficient IoT systems are helping airports and airlines track electricity, fuel, and water consumption. It reinforces the industry’s commitment to environmental responsibility and technological advancement.
- For instance, Lufthansa implemented the IoT-powered RIMOWA Electronic Tag that enables passengers to check in their luggage via mobile devices, reducing average check-in times significantly. The system, first launched in March 2016 after trials in late 2015, allowed bags to be dropped off at automated stations in seconds, with one report mentioning an average bag drop time of just 20 seconds, avoiding long check-in lines.
Market Challenges Analysis:
High Implementation Costs and Complex Integration Requirements
The Global IoT in Aviation Market faces major challenges due to high implementation and integration costs. Deploying IoT systems across aircraft and airport operations requires advanced sensors, communication networks, and analytics infrastructure. Many small and mid-sized airlines struggle to afford large-scale IoT upgrades due to tight budgets. Compatibility issues between legacy aviation systems and new IoT platforms further delay adoption. It increases project complexity and demands specialized technical expertise. The lack of uniform standards across aviation technology providers also limits interoperability and slows system deployment.
Cybersecurity Risks and Data Privacy Concerns
Rising connectivity in aviation increases vulnerability to cyber threats and data breaches. Airlines and airports handle large volumes of sensitive passenger and operational data that must remain secure. Any system intrusion can disrupt flight operations, compromise safety, or cause financial losses. It requires continuous investment in encryption, network monitoring, and cybersecurity frameworks. Regulatory compliance with global data protection laws adds to operational challenges. Building trust among passengers and industry stakeholders depends on strong data governance and transparent security practices.
Market Opportunities:
Expansion of Smart Airports and Digital Aviation Ecosystems
The Global IoT in Aviation Market presents strong opportunities through the development of smart airports and connected infrastructure. Governments and private operators are investing in IoT-driven automation to manage passenger flow, cargo, and maintenance more efficiently. Smart sensors, AI-based analytics, and edge computing enhance decision-making across terminals and airfields. It supports seamless communication between aircraft, ground staff, and airport systems, improving safety and service delivery. The integration of IoT with cloud and 5G networks creates new avenues for real-time analytics and operational intelligence. Growing demand for contactless and digital airport experiences further strengthens market potential.
Adoption of Predictive Maintenance and Green Aviation Technologies
IoT-based predictive maintenance solutions offer airlines the ability to anticipate technical faults and optimize fleet performance. The technology helps reduce operational downtime and extend the life span of critical components. It also supports energy efficiency by minimizing unnecessary fuel consumption and emissions. The global shift toward sustainable aviation encourages adoption of IoT systems that track carbon output and optimize resource use. Increasing collaborations between IoT solution providers and aircraft manufacturers open new business opportunities. These advancements create long-term value for both commercial and defense aviation sectors.
Market Segmentation Analysis:
By Component
The Global IoT in Aviation Market is segmented into hardware, software, and services. Hardware holds a major share due to the growing deployment of sensors, communication modules, and connected devices in aircraft and airports. Software solutions are expanding rapidly, driven by the need for analytics platforms and data integration tools that enhance decision-making. It supports predictive maintenance, asset tracking, and real-time monitoring. Service providers play a vital role in system integration, consulting, and maintenance, ensuring seamless IoT operations across aviation ecosystems.
- For Instance, SITA's broader aircraft data management systems process approximately 2 million ACARS messages daily. SITA's e-Aircraft DataHub is a neutral, cloud-based data-brokering and transformation service that allows for effective data sharing between operators and partners, used by select customers.
By Application
The market covers applications such as ground operations, passenger experience, aircraft operations, and asset management. Ground operations lead the segment due to the adoption of IoT-based systems for baggage handling, traffic control, and logistics optimization. Passenger experience is another key segment, supported by the rise in smart cabins, biometric boarding, and personalized services. It helps airlines improve comfort, efficiency, and customer engagement. Aircraft operations leverage IoT for real-time monitoring of flight systems and fuel management.
- For instance, Hong Kong International Airport implemented RFID technology across its entire baggage handling system, processing over 100,000 bags daily with baggage identification accuracy reaching 100% at selected sortation checkpoints.
By End-Use
End-use segments include airports, airline operators, MROs, and aircraft OEMs. Airports represent the dominant share owing to large-scale investment in smart infrastructure and automation. Airline operators increasingly use IoT to enhance operational visibility and flight safety. It strengthens efficiency across maintenance, logistics, and flight scheduling. MROs and OEMs adopt IoT for predictive maintenance and component optimization, reducing downtime and costs.
Segmentations:
By Component:
- Hardware
- Software
- Services
By Application:
- Ground Operations
- Passenger Experience
- Aircraft Operations
- Asset Management
By End-Use:
- Airport
- Airline Operators
- MRO (Maintenance, Repair & Overhaul)
- Aircraft OEM
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America IoT in Aviation Market size was valued at USD 1,625.40 million in 2018, increased to USD 3,248.65 million in 2024, and is anticipated to reach USD 17,490.59 million by 2032, at a CAGR of 23.6% during the forecast period. North America holds the largest market share of 35% in the Global IoT in Aviation Market Market. Strong digital infrastructure, early adoption of IoT technologies, and presence of major players such as Honeywell International and Microsoft drive regional growth. The United States leads the region, supported by high investments in smart airports and connected aircraft systems. It benefits from widespread use of predictive maintenance and AI-enabled analytics to enhance flight efficiency. Canada and Mexico are also expanding adoption, driven by modernization initiatives and regional airline network upgrades.
Europe
The Europe IoT in Aviation Market size was valued at USD 894.60 million in 2018, increased to USD 1,721.77 million in 2024, and is projected to reach USD 8,640.09 million by 2032, growing at a CAGR of 22.5%. Europe accounts for 25% of the global market share. The region benefits from established aviation hubs and leading aircraft manufacturers such as Airbus and Rolls-Royce. Strong regulatory support for digital transformation across airports and air traffic management enhances adoption. It focuses on improving passenger experience and reducing operational delays through smart infrastructure. The UK, Germany, and France remain key contributors, while Eastern Europe is catching up with modernization projects.
Asia Pacific
The Asia Pacific IoT in Aviation Market size was valued at USD 1,146.60 million in 2018, increased to USD 2,410.17 million in 2024, and is anticipated to reach USD 14,203.92 million by 2032, at a CAGR of 24.9%. Asia Pacific holds 28% of the total market share, making it the fastest-growing regional market. Expanding air passenger traffic and government-led initiatives for airport digitalization drive growth across China, Japan, India, and Southeast Asia. It benefits from large-scale investments in smart airport development and aircraft maintenance technologies. The rising presence of regional low-cost carriers further encourages adoption of IoT for efficiency and cost control. Growing partnerships between telecom firms and aviation companies strengthen technological capabilities in this region.
Latin America
The Latin America IoT in Aviation Market size was valued at USD 306.60 million in 2018, increased to USD 614.67 million in 2024, and is projected to reach USD 3,106.73 million by 2032, registering a CAGR of 22.6%. Latin America contributes 6% of the global market share. The region’s growth is supported by modernization of airports and increased airline investments in connected systems. Brazil and Mexico dominate regional adoption, focusing on passenger safety and operational transparency. It faces infrastructure challenges but continues to attract international partnerships for digital aviation solutions. Rising adoption of IoT for baggage handling and fleet management supports long-term regional expansion.
Middle East
The Middle East IoT in Aviation Market size was valued at USD 172.20 million in 2018, rose to USD 327.70 million in 2024, and is expected to reach USD 1,606.94 million by 2032, at a CAGR of 22.1%. The region holds 4% of the global market share. Growth is driven by large-scale airport infrastructure investments in the UAE, Saudi Arabia, and Qatar. Leading airlines such as Emirates and Qatar Airways are integrating IoT to enhance service efficiency and aircraft connectivity. It benefits from government-backed digital transformation plans and rising passenger demand. Ongoing projects for smart terminals and automated ground handling systems further support regional market growth.
Africa
The Africa IoT in Aviation Market size was valued at USD 54.60 million in 2018, grew to USD 168.16 million in 2024, and is anticipated to reach USD 726.41 million by 2032, at a CAGR of 19.5%. Africa represents 2% of the global market share. The market is gradually expanding with growing air traffic and modernization of airport systems in South Africa, Egypt, and Kenya. It faces challenges related to limited infrastructure and connectivity gaps but holds potential for future adoption. Governments are encouraging private investment to improve aviation safety and operations through IoT solutions. Rising interest in predictive maintenance and smart logistics supports the region’s steady progress.
Key Player Analysis:
- Honeywell International, Inc.
- Tata Communications
- Cisco Systems, Inc.
- Huawei Technologies Co. Ltd.
- IBM Corporation
- Aeris Communications
- Microsoft Corporation
- Tech Mahindra Ltd.
- Wind River Systems, Inc.
- SAP SE
Competitive Analysis:
The Global IoT in Aviation Market is highly competitive, driven by technological innovation and strategic collaborations among leading players. Key participants include Honeywell International, Inc., Tata Communications, Cisco Systems, Inc., Huawei Technologies Co. Ltd., IBM Corporation, and Aeris Communications. These companies focus on expanding their IoT platforms, integrating advanced analytics, and enhancing connectivity solutions for aviation operations. It emphasizes real-time monitoring, predictive maintenance, and passenger experience optimization through connected systems. Strategic mergers, partnerships, and product launches strengthen market positioning and global reach. Continuous investment in AI, edge computing, and cybersecurity enables these firms to deliver scalable and secure IoT solutions to airlines and airports worldwide.
Recent Developments:
- In October 2025, Honeywell announced a partnership with Gulfstream to certify the JetWave X high-speed in-flight connectivity system for integration into Gulfstream aircraft, enhancing cabin internet services for business aviation.
- In October 2025, Tata Communications announced a strategic partnership with NiCE to enhance AI-powered customer engagement via integration of Tata’s Kaleyra AI suite with NiCE’s CXone Mpower platform.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application, End-Use And Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global IoT in Aviation Market will witness accelerated adoption of AI-driven analytics for operational optimization.
- Airlines will increasingly deploy predictive maintenance systems to minimize downtime and improve safety.
- Smart airport infrastructure will expand globally, supported by government investments and digital transformation initiatives.
- Edge computing will gain prominence, enabling faster data processing and real-time decision-making across aviation networks.
- IoT-enabled passenger experience platforms will enhance comfort, personalization, and journey transparency.
- Cybersecurity will become a critical focus area to safeguard interconnected systems and sensitive aviation data.
- Integration of 5G networks will enhance communication speed, reliability, and system scalability for connected aircraft.
- Collaboration between aviation OEMs, IoT providers, and software developers will drive innovation in smart aviation ecosystems.
- Sustainability goals will influence IoT deployment, emphasizing energy efficiency and emission monitoring.
- Emerging economies in Asia Pacific, the Middle East, and Africa will present strong growth potential through infrastructure modernization and rising air travel demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Real-Time Monitoring and Predictive Maintenance
Airlines and airports are increasingly deploying IoT systems to enable real-time data collection and predictive maintenance, which reduces unplanned downtime, improves safety, and optimizes fleet utilization. This proactive approach helps minimize operational costs and enhances reliability across aviation operations.
Expansion of Smart Airport Infrastructure
Significant investments in smart airport infrastructure, including automated baggage handling, connected terminals, and biometric systems, are driving IoT adoption. These technologies streamline passenger flow, improve operational control, and enhance the overall travel experience.
Integration of 5G Networks and AI Analytics
The rollout of 5G connectivity and advanced AI analytics enables faster, more reliable data transfer and processing between aircraft, ground systems, and cloud platforms. This supports real-time decision-making, optimizes flight scheduling, and enhances situational awareness for safer and more efficient operations.
Focus on Safety, Efficiency, and Sustainability
IoT solutions are being adopted to meet stringent safety standards, improve operational efficiency, and support sustainability initiatives. Connected sensors monitor aircraft systems and environmental conditions, helping airlines and airports reduce emissions, optimize resource use, and comply with global environmental regulations.
Passenger-Centric Digital Solutions
The demand for enhanced passenger experiences is fueling the adoption of IoT-enabled services such as smart cabins, digital check-in, and real-time luggage tracking. These solutions improve comfort, reduce wait times, and provide personalized services, strengthening customer loyalty and operational efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global IoT in Aviation Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global IoT in Aviation Market expected to grow between 2024 and 2032?
Which market segment held the largest share of the Global IoT in Aviation Market in 2024?
What are the primary factors fueling the growth of the Global IoT in Aviation Market?
Who are the leading companies in the Global IoT in Aviation Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Airport
- 1.2.2 Airline Operators
- 1.2.3 MRO (Maintenance, Repair & Overhaul)
- 1.2.4 Aircraft OEM
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 Ground Operations
- 1.4.2 Passenger Experience
- 1.4.3 Aircraft Operations
- 1.4.4 Asset Management
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,200.00 million → 2032: USD 45,774.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global IoT In Aviation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global IoT In Aviation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global IoT In Aviation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global IoT In Aviation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global IoT In Aviation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global IoT In Aviation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global IoT In Aviation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global IoT In Aviation Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,200.00 million → 2032: USD 45,774.68 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global IoT In Aviation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Airport
- 12.3.7.2 Airline Operators
- 12.3.7.3 MRO (Maintenance, Repair & Overhaul)
- 12.3.7.4 Aircraft OEM
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ground Operations
- 12.5.7.2 Passenger Experience
- 12.5.7.3 Aircraft Operations
- 12.5.7.4 Asset Management
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global IoT In Aviation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global IoT In Aviation Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global IoT In Aviation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global IoT In Aviation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tata Communications
- 18.4 Cisco Systems, Inc.
- 18.5 Huawei Technologies Co. Ltd.
- 18.6 IBM Corporation
- 18.7 Aeris Communications
- 18.8 Microsoft Corporation
- 18.9 Tech Mahindra Ltd.
- 18.10 Wind River Systems, Inc.
- 18.11 SAP SE
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

