
Market Overview:
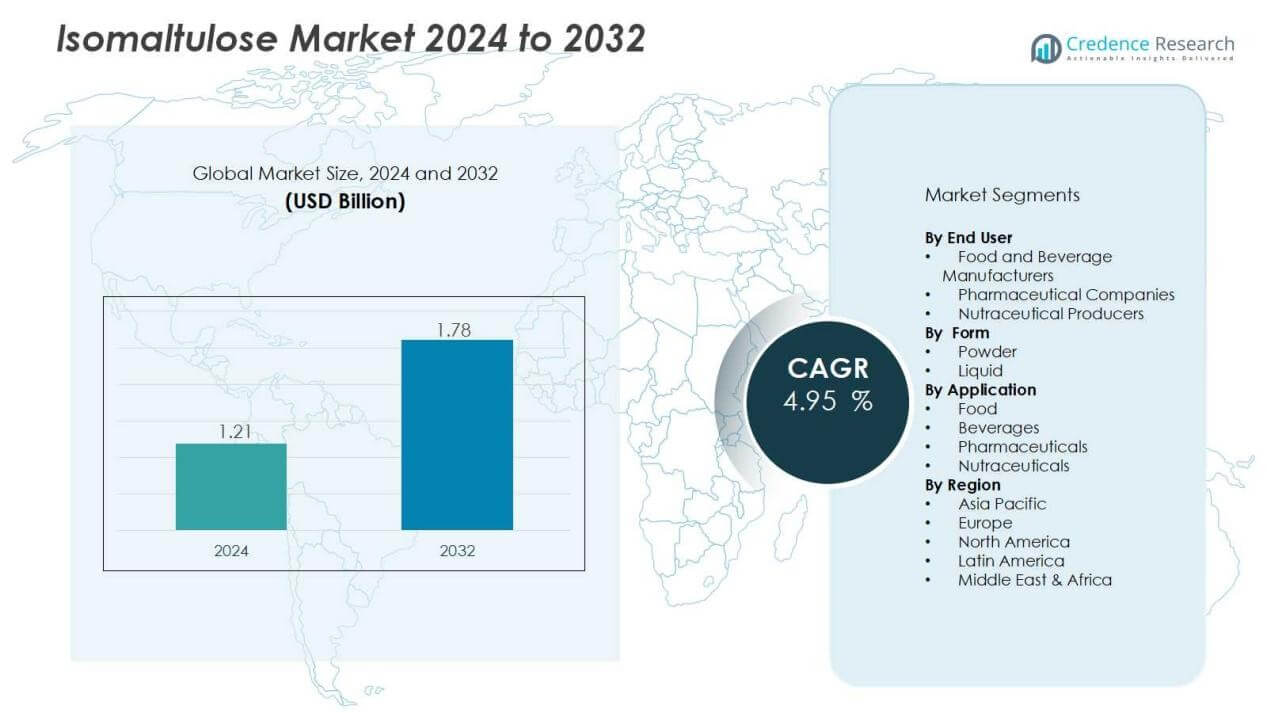
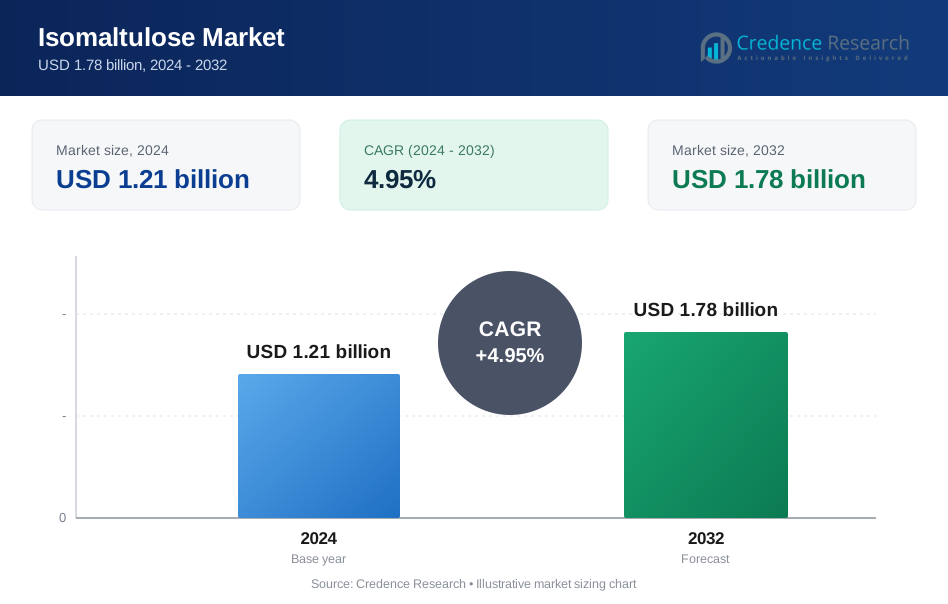
The isomaltulose market size was valued at USD 1.21 billion in 2024 and is anticipated to reach USD 1.78 billion by 2032, at a CAGR of 4.95 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Isomaltulose Market Size 2024 | USD 1.21 Billion |
| Isomaltulose Market, CAGR | 4.95% |
| Isomaltulose Market Size 2032 | USD 1.78 Billion |
The market growth is supported by several key drivers. Rising health awareness and consumer preference for low-glycemic index sweeteners are central factors. Food manufacturers are increasingly using isomaltulose for energy drinks, sports nutrition, and confectionery, given its slow glucose release and dental-friendly properties. Additionally, growing demand in pharmaceutical formulations and functional foods adds further momentum, as companies focus on product innovation to meet consumer needs.
Regionally, Europe leads the isomaltulose market due to its established food processing sector and strong adoption of functional ingredients. North America follows, supported by high consumer awareness and a growing sports nutrition industry. Asia-Pacific is emerging as the fastest-growing region, fueled by rising disposable incomes, rapid urbanization, and increasing demand for healthier food options in China, India, and Southeast Asia. Latin America and the Middle East & Africa also show potential, driven by expanding food and beverage industries.
Market Insights:
- The isomaltulose market was valued at USD 1.21 billion in 2024 and is expected to reach USD 1.78 billion by 2032, growing at a CAGR of 4.95%.
- Rising health awareness and consumer preference for low-glycemic index sweeteners remain central drivers of growth.
- Food manufacturers are using isomaltulose in energy drinks, sports nutrition, and confectionery for steady glucose release and dental benefits.
- Growing demand in pharmaceutical formulations and functional foods adds momentum, supported by product innovation and regulatory approvals.
- Europe led with 38% market share in 2024, supported by a strong food processing sector and high adoption of functional sweeteners.
- North America held 27% share, driven by consumer health awareness, sports nutrition demand, and expanding e-commerce networks.
- Asia-Pacific accounted for 22% share and is the fastest-growing region, fueled by rising incomes, urbanization, and growing demand for healthier food options.
Market Drivers:
Rising Demand for Low-Glycemic Index Sweeteners:
The isomaltulose market benefits from increasing consumer preference for low-glycemic index products. It provides a steady energy release without sharp spikes in blood sugar, making it suitable for diabetics and health-conscious individuals. Food and beverage companies are actively positioning isomaltulose as a healthier alternative to sucrose and high-fructose corn syrup. Growing awareness about metabolic health continues to support demand across multiple product categories.
- For instance, Beneo's Palatinose® isomaltulose, a long-established product, has a proven glycemic index (GI) value of 32 in human clinical trials.
Expanding Applications in Functional Foods and Sports Nutrition:
The isomaltulose market is driven by its wide adoption in functional foods, sports nutrition, and energy beverages. It enhances endurance performance by providing sustained glucose supply, which appeals to athletes and fitness enthusiasts. Manufacturers incorporate it into sports drinks, protein bars, and dietary supplements to strengthen their health-focused product lines. The versatility of isomaltulose ensures its relevance across several high-growth segments.
- For instance, Stefan Schlegel, a professional German cyclist, completed the Race Across America (RAAM) consuming about 800 g/day of isomaltulose as 53-59% of his total carbohydrate intake through sports drinks and soups, noting stable energy levels without hunger pangs throughout the race where he finished 10th among 42 solo racers.
Increasing Focus on Dental Health and Preventive Nutrition:
The isomaltulose market gains traction from its non-cariogenic properties, which help prevent dental decay. Dentists and health experts recognize it as a safer sugar alternative, influencing consumer choices in confectionery and chewing gum. Preventive nutrition trends encourage food companies to reformulate products with functional sweeteners that protect oral health. Rising parental concerns about children’s sugar intake also support greater usage of isomaltulose in everyday foods.
Supportive Regulatory Environment and Product Innovation:
The isomaltulose market is supported by favorable regulations and approvals across major economies. It has received safety validation from global food authorities, which strengthens manufacturer confidence and market penetration. Producers are investing in research and development to improve production efficiency and expand application areas. The growing focus on natural and science-backed sweeteners continues to foster product innovation and broader adoption.
 Market Trends:
Growing Integration into Clean-Label and Health-Oriented Products:
The isomaltulose market reflects a clear shift toward clean-label and natural ingredients. Consumers increasingly demand transparency in food formulations, favoring products with recognizable and functional sweeteners. Isomaltulose aligns with this preference due to its natural enzymatic production process and proven health benefits. It is gaining traction in sports nutrition, functional beverages, and bakery items positioned as wholesome and better-for-you. Food brands actively market isomaltulose-based products with emphasis on steady energy release, digestive tolerance, and dental safety. This trend highlights the growing synergy between consumer health awareness and product innovation.
- For instance, BENEO’s Palatinose™ sports drink enabled 20 trained cyclists to complete a 90-minute endurance time trial one full minute faster when consuming 750 mL of a 10% Palatinose™ beverage.
Rising Popularity in Asia-Pacific and Expansion into Emerging Categories:
The isomaltulose market is experiencing strong momentum in Asia-Pacific, where rising disposable incomes and changing lifestyles drive demand for functional foods. It is increasingly included in dairy products, nutritional supplements, and fortified beverages targeting younger and aging populations alike. Companies are expanding applications beyond traditional confectionery into medical nutrition, weight management, and infant formula. This broadening scope highlights its ability to address diverse health needs and market niches. The rise of e-commerce platforms in emerging economies accelerates product accessibility and consumer adoption. These factors position Asia-Pacific as a leading growth engine for global market expansion.
- For Instance, BENEO GmbH developed an infant follow-on formula containing 2.1 grams of isomaltulose per serving. A 2016 clinical trial of 50 healthy infants aged 4 to 8 months demonstrated that the formula was well-tolerated and safely accepted by infants.
Market Challenges Analysis:
High Production Costs and Limited Raw Material Availability:
The isomaltulose market faces challenges due to its relatively high production costs compared to conventional sweeteners. Specialized enzymatic processes and limited raw material sources restrict large-scale manufacturing efficiency. It often struggles to compete on price with alternatives like sucrose, high-fructose corn syrup, and artificial sweeteners. Cost sensitivity among food manufacturers and consumers in developing regions further limits rapid adoption. Expanding production capacity and improving process efficiency remain critical to lowering costs. Without addressing these constraints, market penetration may stay concentrated in premium and niche product categories.
Low Consumer Awareness and Competitive Sweetener Landscape:
The isomaltulose market also encounters barriers from low consumer awareness in many parts of the world. It is often overshadowed by more established natural sweeteners such as stevia and monk fruit. Limited marketing initiatives and lack of broad retail availability hinder visibility among mainstream consumers. Food and beverage companies remain cautious about reformulation when consumer knowledge is low. Growing competition from newer low-calorie sweeteners adds pressure to differentiate isomaltulose. Strengthening education campaigns and building partnerships with health organizations can help overcome these challenges and widen adoption.
Market Opportunities:
Expanding Role in Functional and Specialized Nutrition:
The isomaltulose market holds strong opportunities in functional nutrition and health-driven product categories. It is increasingly suited for diabetic-friendly foods, sports nutrition, and weight management solutions due to its low-glycemic benefits. Manufacturers can expand its use in dietary supplements, medical nutrition, and fortified beverages to meet rising health demands. The global focus on preventive healthcare creates a favorable environment for innovative product launches. Partnerships with nutrition brands and fitness companies can accelerate visibility and adoption. By highlighting science-backed benefits, producers can secure a stronger foothold across premium and mainstream markets.
Growth Potential in Emerging Economies and Plant-Based Applications:
The isomaltulose market is set to benefit from rising disposable incomes and lifestyle changes in Asia-Pacific, Latin America, and the Middle East. It fits well into plant-based and clean-label product portfolios, where consumers seek natural yet functional alternatives. Expanding applications in dairy alternatives, energy bars, and plant-based beverages open new growth avenues. E-commerce and digital marketing further enhance consumer reach in these high-growth regions. Food companies can tap into local tastes while integrating isomaltulose into globally aligned health-focused products. Its adaptability across cultures and product types positions it as a strong driver of future demand.
Market Segmentation Analysis:
By End User
The isomaltulose market serves diverse end users, including food and beverage manufacturers, pharmaceutical companies, and nutraceutical producers. Food and beverage companies dominate due to strong demand for functional sweeteners in sports drinks, bakery products, and confectionery. Pharmaceutical and nutraceutical industries also adopt it for diabetic-friendly formulations and dietary supplements. It strengthens value for manufacturers targeting preventive health and consumer wellness.
- For example, Cargill, Inc. has developed isomaltulose-based sweeteners with a low glycemic index of 32, effectively reducing postprandial glucose levels in diabetic-friendly products tested in trials with over 100 participants.
By Form
The isomaltulose market is segmented into powder and liquid forms, with powder holding a larger share. It is preferred for ease of storage, transport, and integration into solid foods like bakery items and energy bars. Liquid form is gaining ground in beverage applications, where solubility and ease of blending are critical. The form flexibility supports broader adoption across industrial and consumer-focused applications.
- For instance, Südzucker AG’s isomaltulose syrup used in isotonic beverages shows acid stability at pH 2.3 with no hydrolysis after 3 months, unlike sucrose which inverts 98% in the same period. This superior stability enhances shelf-life and product consistency in drinks.
By Application
The isomaltulose market finds applications in food, beverages, pharmaceuticals, and nutraceuticals. It is widely used in sports nutrition, energy drinks, and functional foods due to its low-glycemic properties. Confectionery and bakery sectors utilize it for sweetness without compromising dental health. Pharmaceutical applications highlight its role in diabetic care and controlled energy release products. This wide application base ensures sustained growth across multiple industries.
Segmentations:
By End User:
- Food and Beverage Manufacturers
- Pharmaceutical Companies
- Nutraceutical Producers
By Form:
- Powder
- Liquid
By Application:
- Food
- Beverages
- Pharmaceuticals
- Nutraceuticals
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Europe:
Europe accounted for 38% market share in 2024, supported by a mature food and beverage industry. The isomaltulose market benefits from strict regulatory approvals and consumer trust in functional sweeteners. It is widely used in sports nutrition, confectionery, and bakery products across leading European economies. Health-conscious consumers in Germany, France, and the U.K. drive sustained adoption of low-glycemic sweeteners. Food producers leverage isomaltulose to meet demand for clean-label and preventive nutrition products. Government-backed campaigns promoting healthy diets further strengthen its regional presence and market expansion.
North America:
North America captured 27% market share in 2024, driven by rising interest in functional and low-glycemic ingredients. The isomaltulose market is supported by the region’s strong sports nutrition and dietary supplement industries. It is increasingly integrated into beverages, energy bars, and diabetic-friendly foods. Manufacturers in the U.S. and Canada emphasize natural sweetener benefits to cater to health-conscious consumers. Strong marketing strategies and product innovations highlight its role in sustained energy release. The region’s advanced distribution networks, including e-commerce, improve accessibility and boost adoption rates.
Asia-Pacific:
Asia-Pacific held 22% market share in 2024, reflecting its fast-growing adoption in functional foods. The isomaltulose market benefits from rising disposable incomes, urbanization, and growing health awareness in China, India, and Southeast Asia. It is increasingly present in fortified beverages, medical nutrition, and plant-based alternatives. Regional food and beverage companies actively invest in product innovation to meet consumer demand. Expanding retail channels and digital platforms enhance visibility and accelerate penetration. The region is expected to become the fastest-growing market segment, supported by evolving dietary habits and population size.
Key Player Analysis:
- MGP Ingredients
- Ingredion
- Cargill
- Fujicco
- Tate and Lyle
- Crown Ingredients
- Roquette
- Emsland Group
- Nexira
- Agrana
- Mitsubishi Shokuhin
- Naturally Sweet
- Beneo
Competitive Analysis:
The isomaltulose market is characterized by steady competition among global and regional players. Leading companies include MGP Ingredients, Ingredion, Cargill, Fujicco, Tate and Lyle, Crown Ingredients, Roquette, Emsland Group, and Nexira. It is shaped by strategies that focus on innovation, production efficiency, and expansion of application areas in food, beverages, pharmaceuticals, and nutraceuticals. Players invest in research to highlight the health benefits of isomaltulose and secure regulatory approvals across key markets. Partnerships with food and nutrition brands strengthen distribution networks and expand consumer reach. Strong emphasis on clean-label, natural positioning, and functional properties helps companies differentiate their offerings. The competitive landscape continues to evolve as producers scale capacity, adopt sustainable practices, and target emerging economies with rising health-conscious populations.
Recent Developments:
- In May 2025, Ingredion and Amyris ended their RealSweet joint venture, with Amyris taking full ownership of the Brazilian precision fermentation plant and Ingredion obtaining exclusive rights to use Amyris' fermented Reb M technology.
- In March 2025, Cargill showcased new food ingredient innovations at the AAHAR 2025 event, including a trans fat-free vanaspati fat launched in Kerala, India, and other bakery and confectionery ingredients.
Report Coverage:
The research report offers an in-depth analysis based on End User, Form, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The isomaltulose market is expected to gain momentum through rising demand for functional and low-glycemic sweeteners.
- It will see wider integration in sports nutrition, energy drinks, and endurance-focused dietary supplements.
- Manufacturers are likely to expand applications in medical nutrition and diabetic-friendly food products.
- Growing use in children’s food and beverages is expected to strengthen long-term consumer adoption.
- The market will benefit from increasing alignment with clean-label and natural ingredient trends.
- Producers are anticipated to invest in scaling enzymatic production technologies to reduce costs.
- E-commerce platforms will continue to play a central role in improving global product accessibility.
- Asia-Pacific is projected to emerge as a leading growth driver due to rising health awareness.
- Collaborations with fitness brands and healthcare providers will expand product visibility and credibility.
- Sustained regulatory support and scientific validation will reinforce consumer trust and encourage innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Isomaltulose Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Isomaltulose Market projected to grow between 2024 and 2032?
Which Isomaltulose Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Isomaltulose Market?
Who are the leading companies in the Isomaltulose Market?
Which region commanded the largest share of the Isomaltulose Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Isomaltulose Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Isomaltulose Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.21 billion → 2032: USD 1.78 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Isomaltulose Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Isomaltulose Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Isomaltulose Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Isomaltulose Market Drivers
- 3.3 Isomaltulose Market Restraints & Challenges
- 3.4 Isomaltulose Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Isomaltulose Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Isomaltulose Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Isomaltulose category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Isomaltulose Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Isomaltulose Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Isomaltulose market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Isomaltulose Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Isomaltulose Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Isomaltulose Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Isomaltulose (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Isomaltulose Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Isomaltulose Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Isomaltulose Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Isomaltulose Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Isomaltulose Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Isomaltulose Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Isomaltulose Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Isomaltulose Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Isomaltulose Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
