
Shiitake prices offset fewer satoyama growers
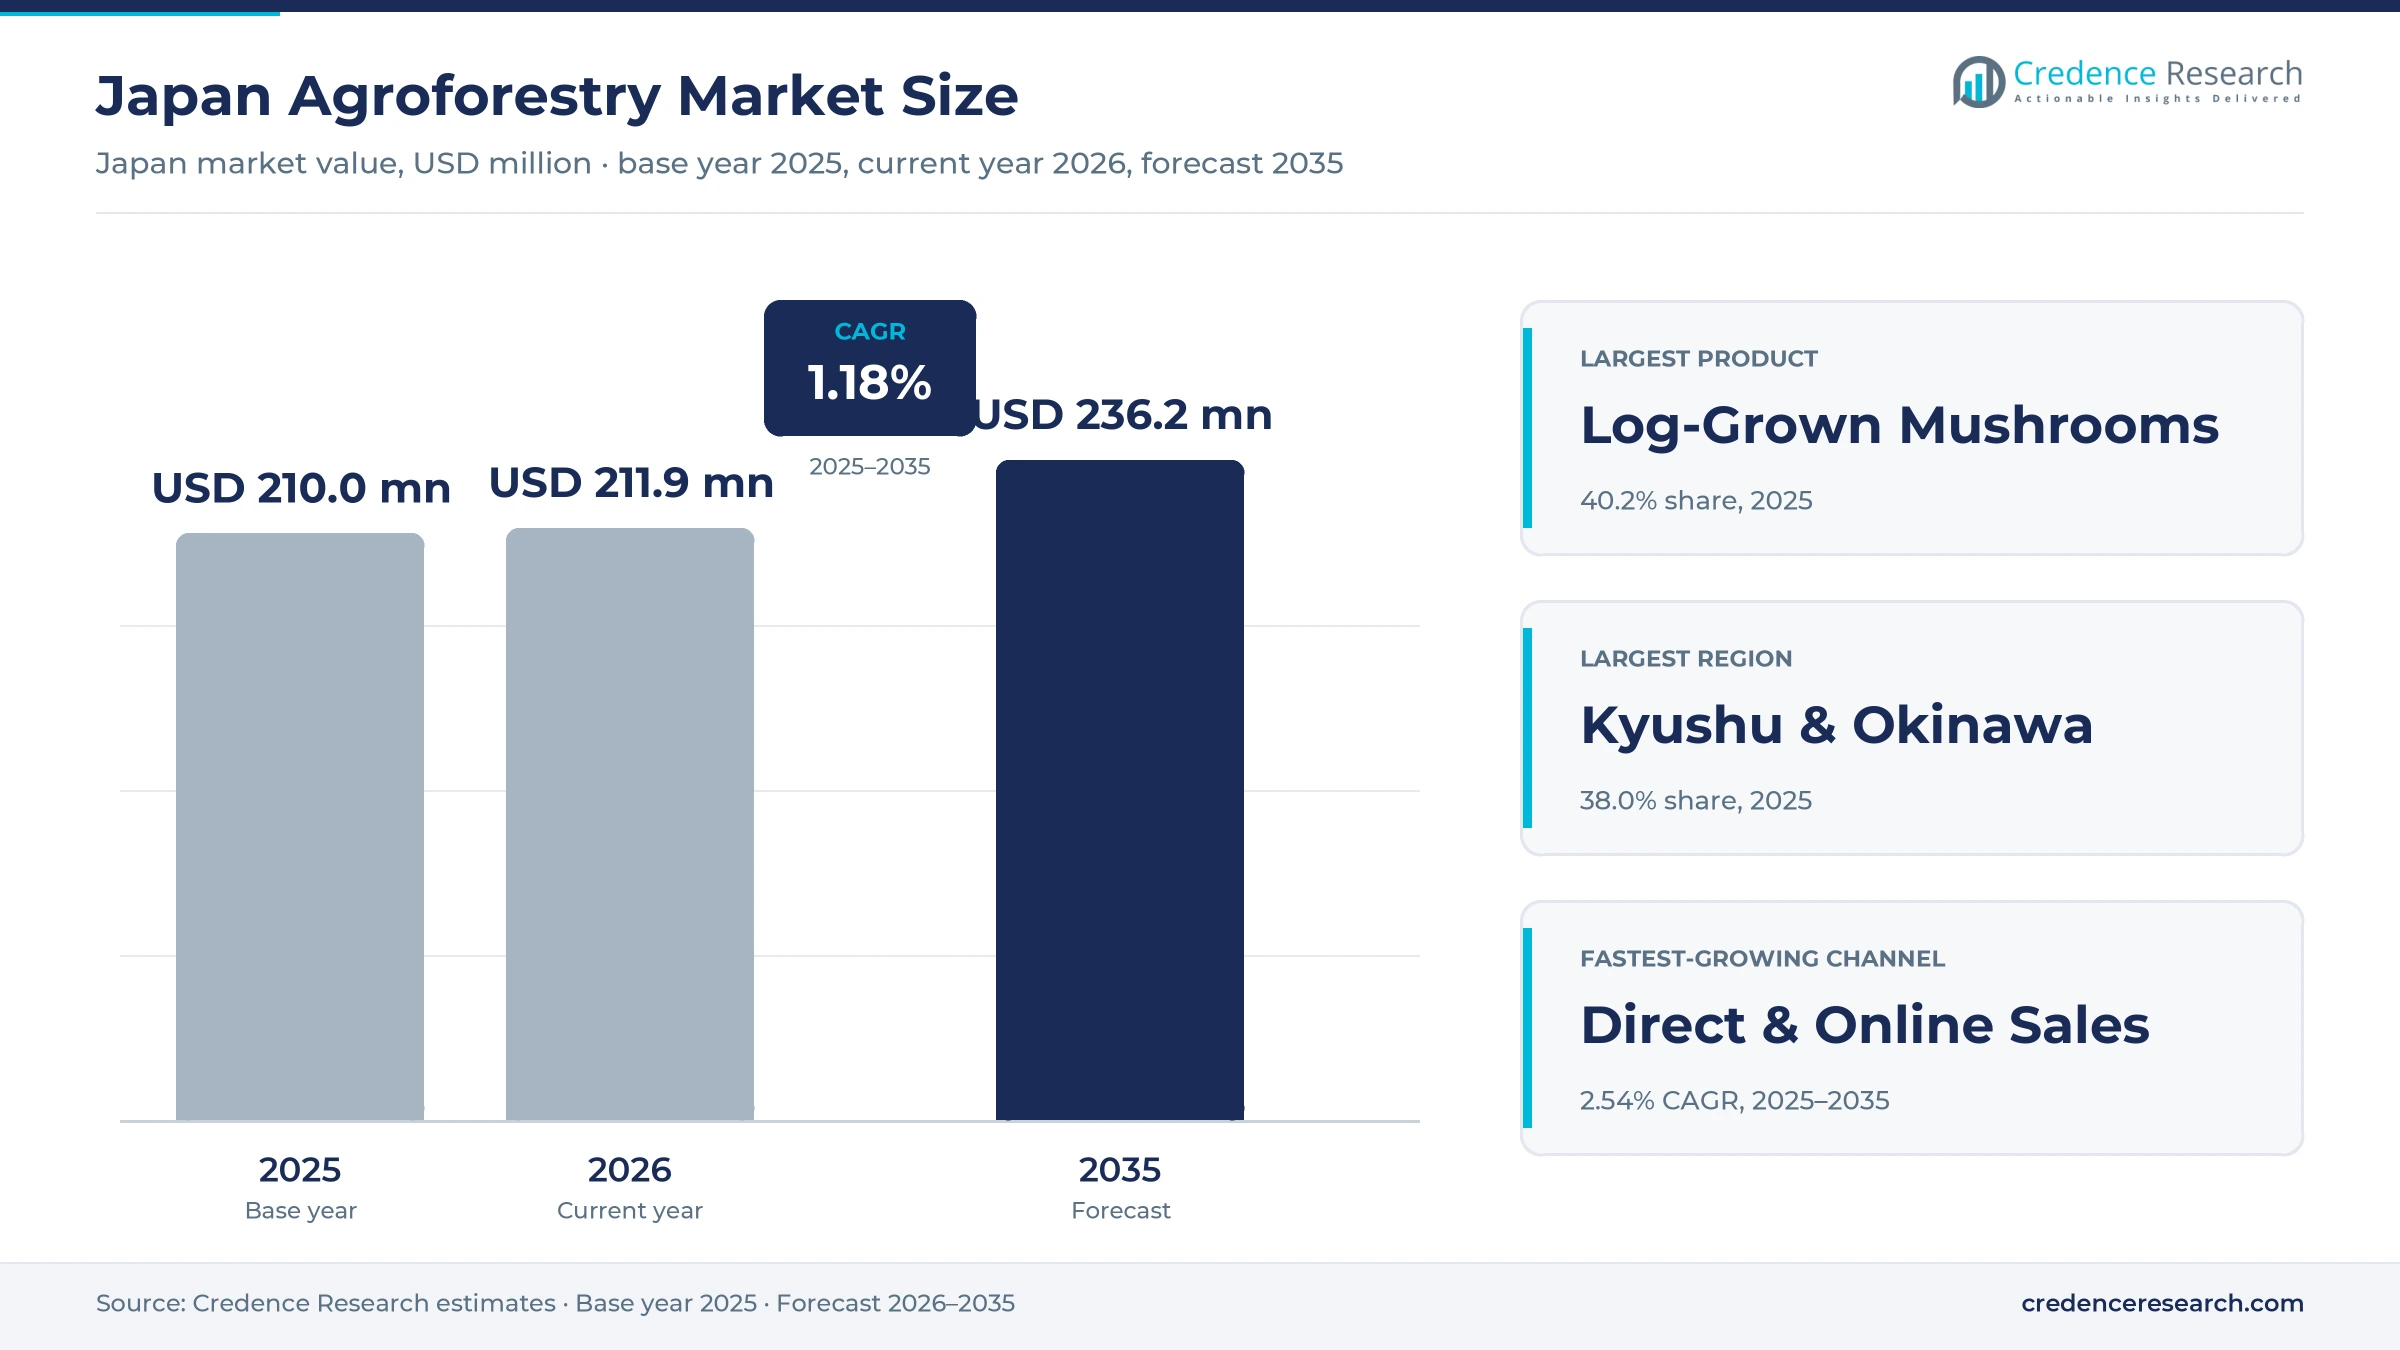
The Japan agroforestry market was valued at USD 210.0 million in 2025 and is projected to increase from USD 211.9 million in 2026 to USD 236.2 million by 2035, registering a CAGR of 1.18% during 2025–2035. Japan's version of agroforestry is the satoyama landscape, where farmers tend woodland beside fields. Growth is slow because the grower base is aging, and only about 10,000 households still grow log shiitake, half the number of 10 years earlier. Premium prices hold value up, as dried shiitake reached JPY 5,766 per kilogram in 2024, the highest since 1983, and demand for bamboo shoots, binchotan and domestic lacquer holds. Kyushu and Okinawa held the largest regional share, 38.0% in 2025, led by dried shiitake in Oita and Miyazaki, and grow fastest at 1.41% a year. The main structural change is policy, as the forest environment tax, introduced in fiscal 2024 at JPY 1,000 per resident a year, now funds thinning and coppicing of the woodland these growers depend on.
What counts as agroforestry in Japan's satoyama woodland?
Japan's statistics do not use the word agroforestry, but the Food and Agriculture Organization describes it as integrating trees with crop and animal farming, a definition that satoyama forest farming fits. Growers inoculate konara and kunugi oak logs with shiitake spawn, harvest shoots from managed bamboo groves, coppice broadleaf woodland for charcoal and gather nuts, wild vegetables and lacquer. Special forest products, the official category, were worth JPY 243.7 billion in 2024, but cultivated mushrooms made up JPY 232.3 billion of that, most of them grown indoors.
The market counts only woodland-grown output at producer prices, so it excludes mushrooms grown indoors on sawdust beds, which made up 95.1% of fresh shiitake output in 2025, as well as timber and pulpwood, single-crop chestnut orchards and forest carbon credits. That boundary explains why the market is small next to headline forestry figures, as it measures a premium niche sold on quality and origin.
Japan Agroforestry Market Insights
- The Japan agroforestry market is projected to rise from USD 211.9 million in 2026 to USD 236.2 million by 2035, a 1.18% CAGR, as premium prices offset a shrinking grower base.
- Kyushu and Okinawa held 38.0% of 2025 value, the largest regional share, because Oita and Miyazaki lead dried shiitake and Fukuoka and Kagoshima lead bamboo shoots.
- Log-grown mushrooms accounted for 40.2% of 2025 value, the largest product, as dried log-grown shiitake reached JPY 5,766 per kilogram in 2024.
- About 10,000 households grew log shiitake in 2024, half the number of a decade earlier, so output is shifting to fewer, larger growers and branded sellers.
- Direct and online sales grow fastest through 2035 at 2.54% a year, so growers and branded processors are shifting sales toward roadside stations and e-commerce.
Log shiitake leads while lacquer and direct sales grow
Log-grown mushrooms lead by product while lacquer and wild foods grow fastest
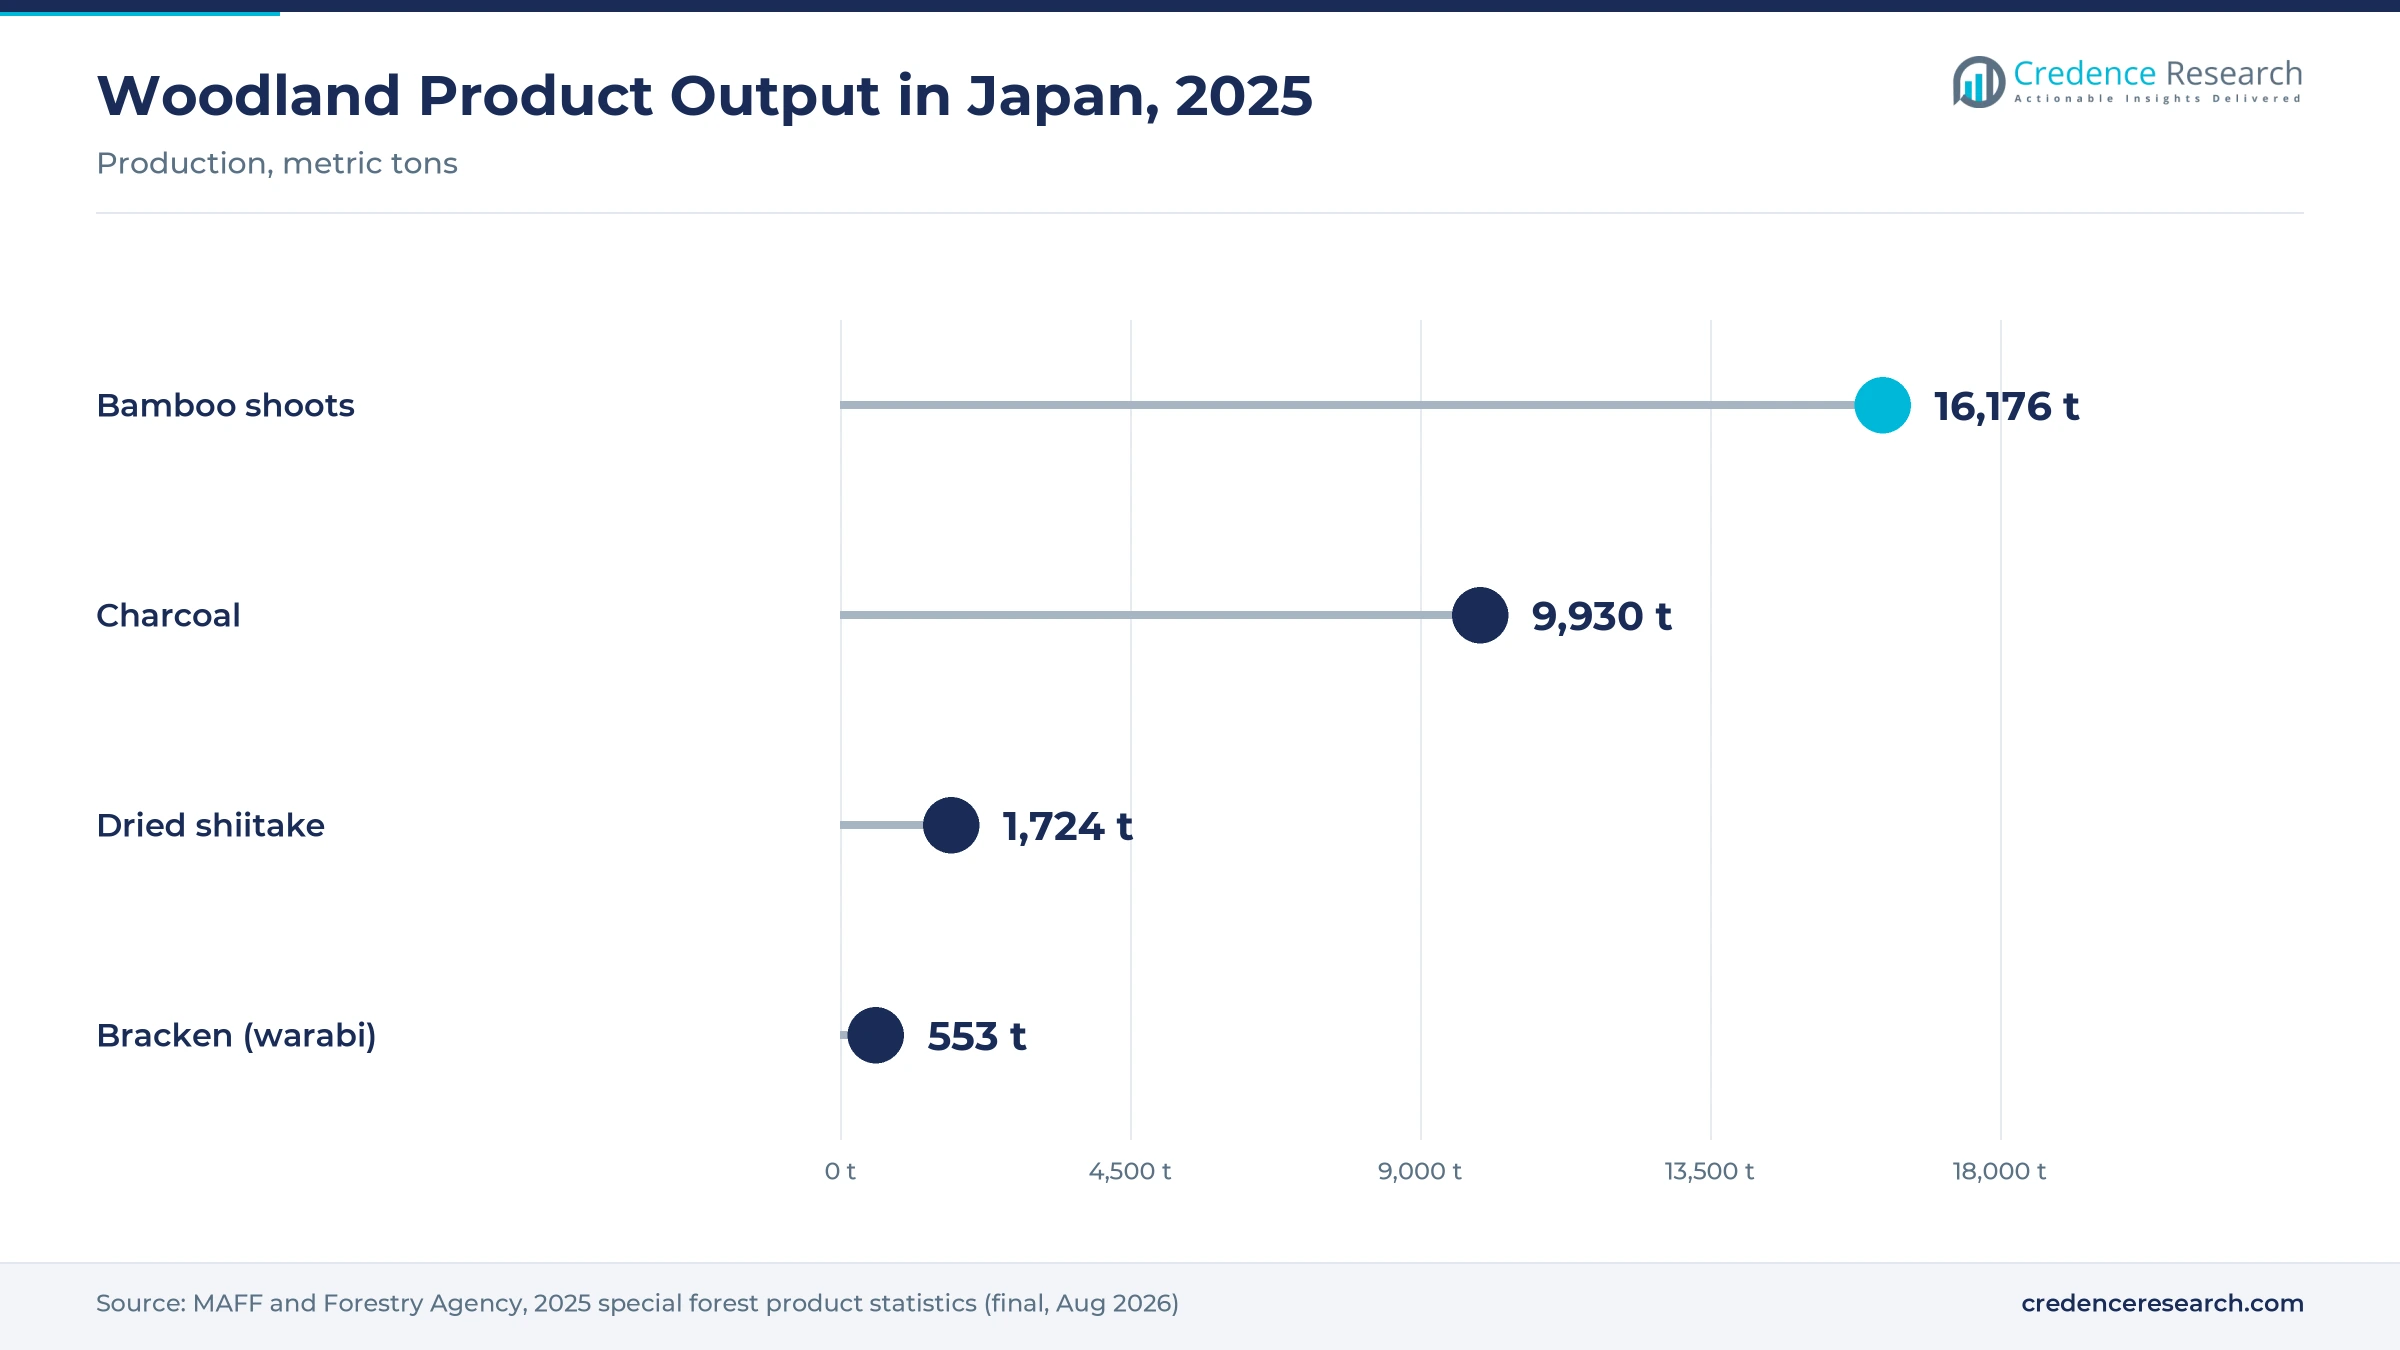
Based on product, the market is categorized into log-grown mushrooms, bamboo shoots and bamboo, charcoal and fuelwood, and nuts, wild vegetables and lacquer. Log-grown mushrooms led with 40.2% of 2025 value, because dried shiitake grown on oak logs commands premium prices; its 2025 output rose 9.5% to 1,724 metric tons. Nuts, wild vegetables and lacquer grow fastest at 2.01% a year, helped by restoration demand for domestic lacquer, whose 2025 output rose 5.2% to 1,885 kilograms.
Cooperatives lead by sales channel as direct and online sales grow fastest
Based on sales channel, the market is categorized into wholesale markets and cooperatives, direct and online sales, and processors and food service. Wholesale markets and cooperatives led with 58.0% of 2025 value, because cooperative auctions grade and price most dried shiitake and charcoal from small family growers. Direct and online sales grow fastest at 2.54% a year as growers sell through roadside stations, farmers' markets and e-commerce and keep more of the retail price.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Product | Log-Grown Mushrooms | 40.2% | Nuts, Wild Vegetables & Lacquer | 2.01% |
| By Sales Channel | Wholesale Markets & Cooperatives | 58.0% | Direct & Online Sales | 2.54% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Shiitake prices and a forest tax drive satoyama demand
Record dried shiitake prices reward log growers
Buyers pay more for shiitake grown on konara and kunugi oak logs in open woodland, prized for firm texture and aroma in stock and temple cooking. Dried shiitake output fell 13.4% in 2024 on fewer growers and poor autumn weather, and the price jumped 27.3% to JPY 5,766 per kilogram, the highest since 1983, according to the Forestry Agency's annual white paper. Output then rose 9.5% in 2025, according to MAFF special forest product statistics. As a result, higher prices sustain the lead held by log-grown mushrooms through the late 2020s.
The forest environment tax pays for woodland care
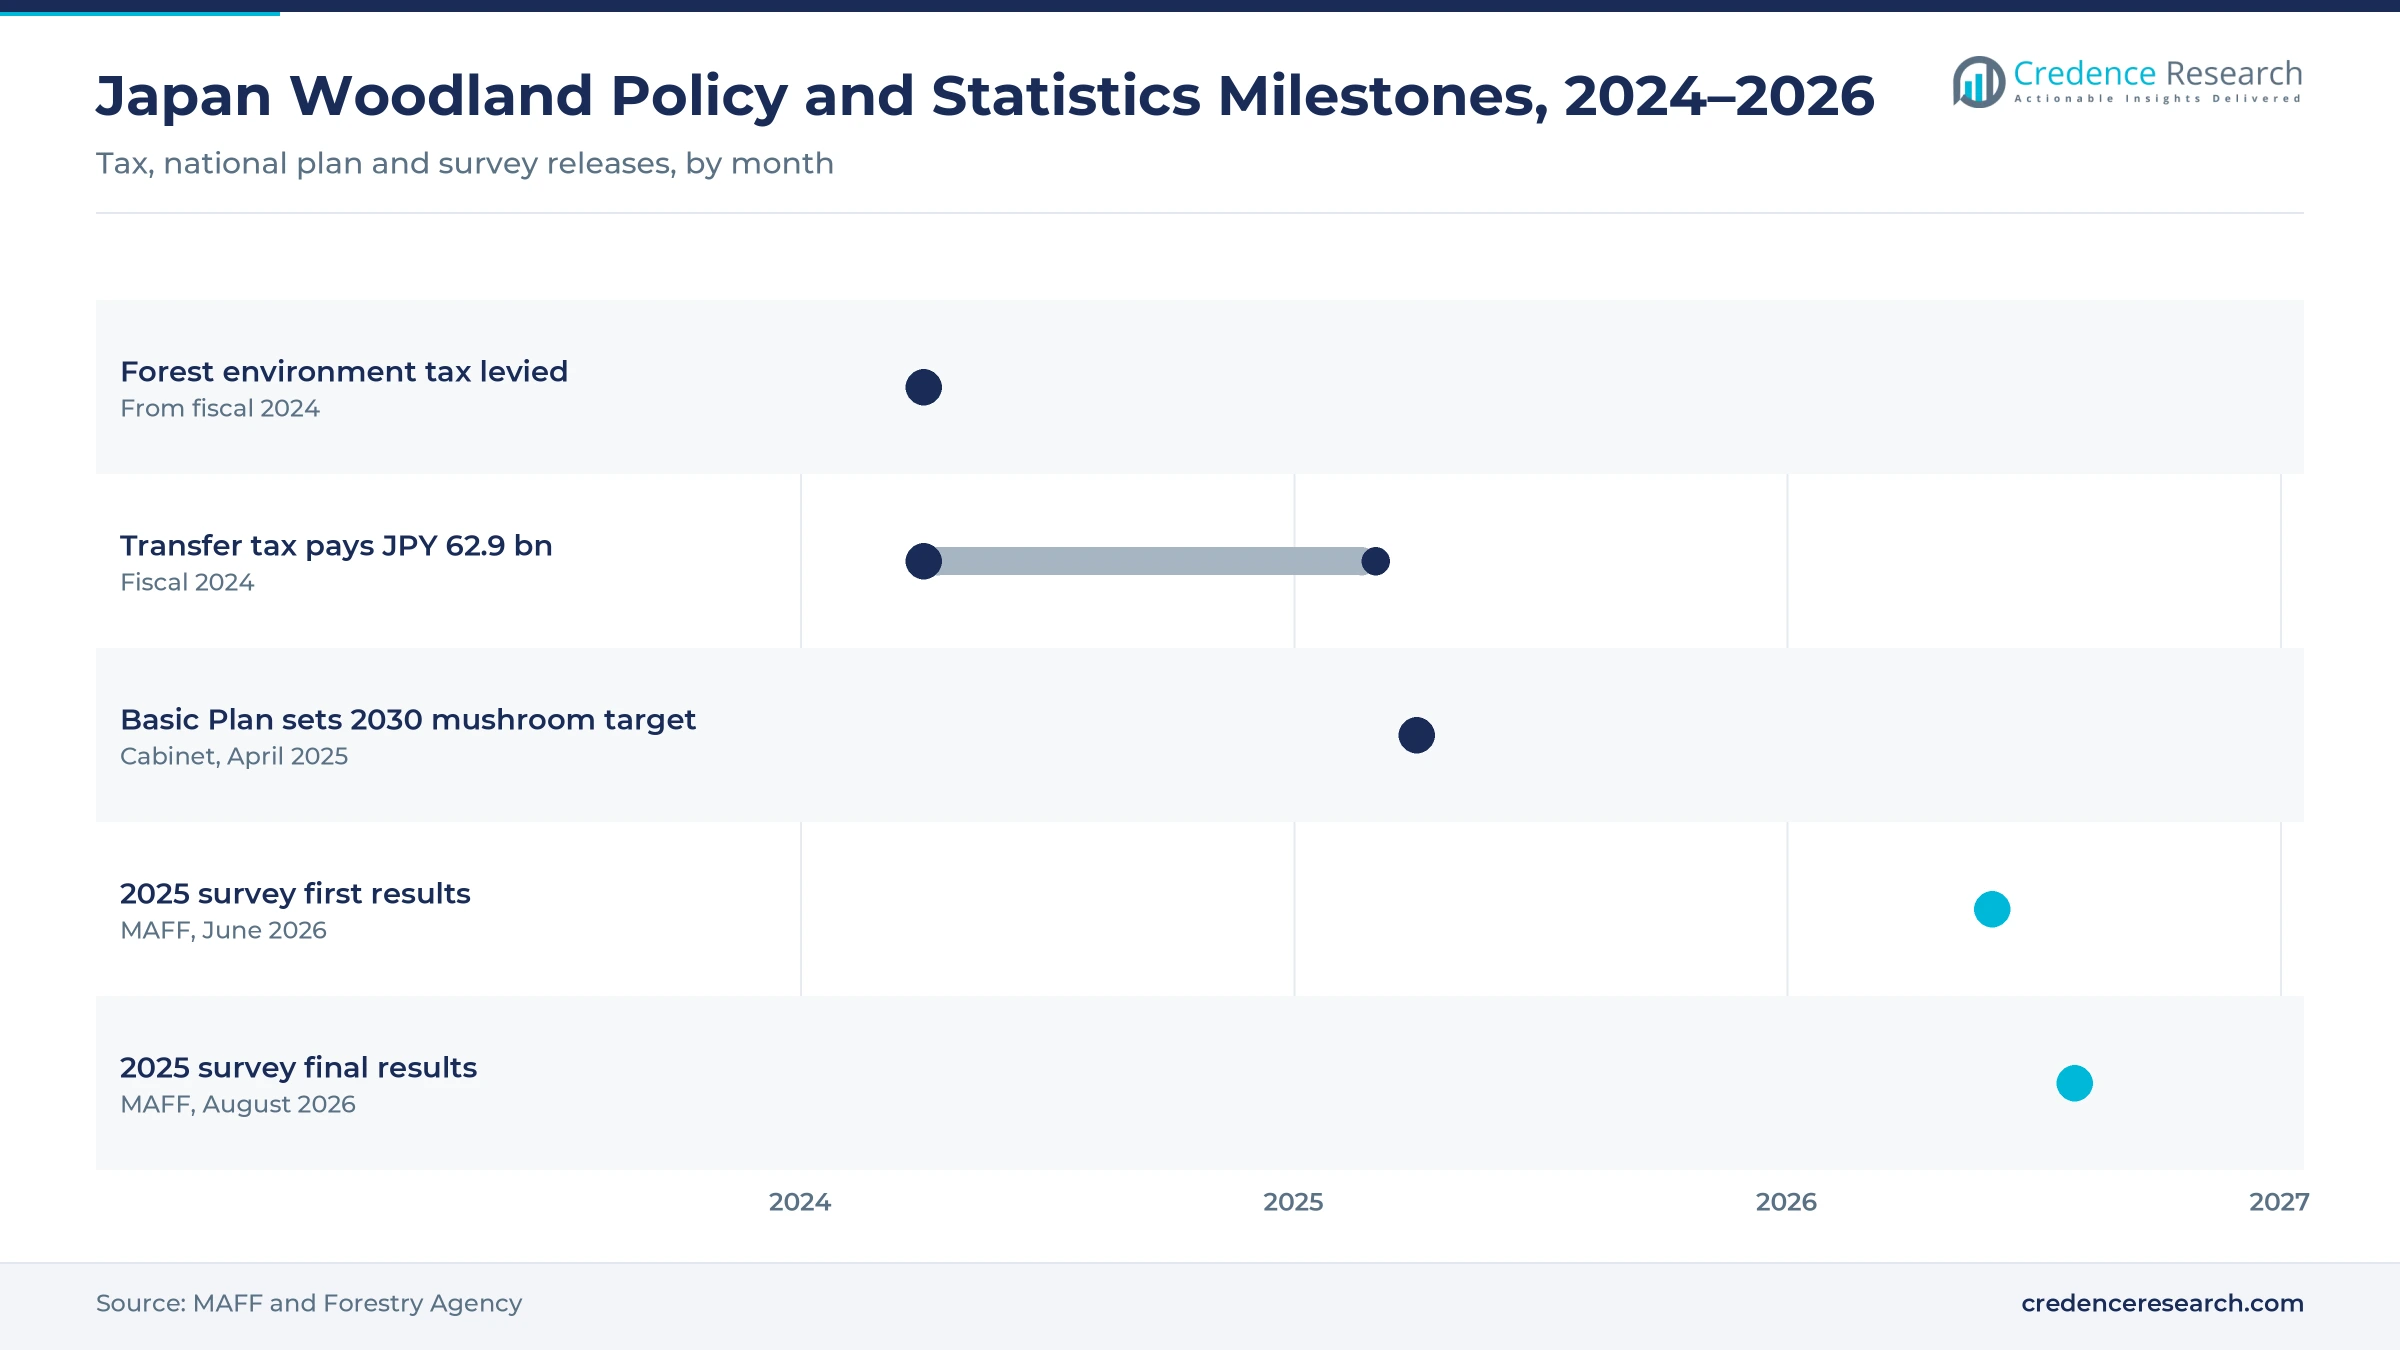
Public money now flows into neglected woodland after Japan introduced the national forest environment tax in fiscal 2024, collecting JPY 1,000 per resident a year through municipalities. The related transfer tax distributed JPY 62.9 billion to municipalities and prefectures in fiscal 2024. In turn, thinning, coppicing and bamboo grove clearing funded this way improve the woodland that log growers, bamboo shoot farmers and charcoal makers use, with effects building over the next decade across all seven regions.
Restoration rules lift demand for domestic lacquer
Domestic urushi lacquer is scarce, as 93% of Japan's lacquer consumption is imported, mostly from China and domestic output was only 1,885 kilograms in 2025, led by Iwate, Ibaraki and Tochigi. In 2018, the Agency for Cultural Affairs introduced a rule requiring domestic lacquer for repairs of national treasures and important cultural properties, which supports prices for lacquer tapped in Iwate. That long-term restoration demand therefore helps make nuts, wild vegetables and lacquer the fastest-growing product group.
Rural visitors and outdoor cooking add direct buyers
Tourists and outdoor users add buyers, as roadside stations, farm stays and woodland tourism let growers sell bamboo shoots, wild vegetables and charcoal at the source, and fuelwood output rose 5.5% in 2025 to 104,618 stacked cubic meters on demand for pizza ovens, wood stoves and outdoor cooking. Visitors who try log-grown shiitake or fresh shoots often become repeat online buyers, which is why direct and online sales are the fastest-growing channel.
Larger log yards and origin brands reshape satoyama output
Trend toward fewer growers running larger log yards
Mushroom grower households fell 5.0% in 2024 to about 20,000, and log shiitake growers, about 10,000 households, have halved in 10 years as farmers retire and suitable logs become harder to source. Remaining growers run larger log yards, sign supply agreements with log producers and, among younger growers, use digital tools to manage cultivation. The shift concentrates output in Kyushu, the largest producing region, and favors cooperatives that can absorb retiring growers' yards.
Origin brands and direct sales lift price per kilogram
Producers in Oita, Miyazaki and other prefectures sell dried shiitake under regional brands, and Kishu binchotan from Wakayama and Tosa binchotan from Kochi carry strong names with yakitori and unagi restaurants. That branding lets small volumes earn premium prices, and growers increasingly sell through roadside stations and e-commerce. White charcoal, the binchotan type, accounted for 2,456 metric tons of Japan's 9,930 metric tons of charcoal output in 2025.
Dried shiitake, binchotan and urushi exports open an opportunity
Japan's mushroom exports fell 15.3% in 2025 to 978 metric tons, worth about JPY 1.0 billion, because fresh mushrooms are hard to keep fresh in transit, but dried shiitake exports rose. Dried shiitake, binchotan and urushi have strong reputations in Hong Kong, other Asian markets and North America. Branded processors that handle grading and export paperwork can therefore earn more than domestic wholesale.
Bamboo grove restoration and coppice carbon offer an opportunity
Neglected bamboo groves spread into farmland and forest, and municipalities and volunteer groups now fund grove thinning, which revives shoot harvests and supplies culms; bamboo culm output was 863,000 bundles in 2025, mainly from Kagoshima, Kumamoto and Yamaguchi. Managed coppice and groves also store carbon, so if credit schemes reward this, growers could gain a second income stream, though credits are not counted in the market today.
Aging growers, wildlife and scarce oak logs limit output
An aging grower base shrinks output year after year
Log shiitake work is heavy, since logs must be cut, inoculated, moved and turned by hand, and most log growers, charcoal makers and bamboo farmers are older. Log shiitake grower numbers have halved in 10 years, and without successors woodlots fall out of use and output declines. Cooperatives, the main buyers of this produce, face thinner auction volumes. Consolidating yards under younger growers, log supply agreements and mechanized handling help, but labor will remain the binding constraint through 2035.
Wildlife and weather make harvests volatile
Deer and wild boar damage bamboo shoots and young trees, and hot, dry summers cut mushroom fruiting on outdoor logs. Bamboo shoot output fell 22.5% in 2025 to 16,176 metric tons, and dried shiitake fell 13.4% in 2024 after poor autumn weather. Such swings hit grower income and leave wholesale buyers and restaurants short of supply. Fencing, shade netting, watering systems and wider sourcing across prefectures reduce the damage but add cost per kilogram.
Indoor sawdust-bed mushrooms and imports undercut prices
Indoor sawdust-bed shiitake is cheaper and available all year, and it already made up 95.1% of fresh shiitake output in 2025, while imported dried shiitake competes on price in processing and food service. Log growers must justify a premium through taste, origin and traceability, which limits volume growth in the mass market. Regional brands, origin labeling and direct sales to restaurants and households are the main ways log growers defend the price gap.
Scarce oak logs limit shiitake expansion
Log growers need konara and kunugi oak logs of the right size, and supply has tightened. Some areas of Tohoku still face restrictions on log use after the 2011 nuclear accident, and neglect elsewhere has left oak stands overgrown. Tohoku, which holds 15.0% of 2025 value, grows slowest at 0.81% a year partly for this reason. Supply agreements with log producers and coppicing funded by the forest environment tax are the main mitigations for growers.
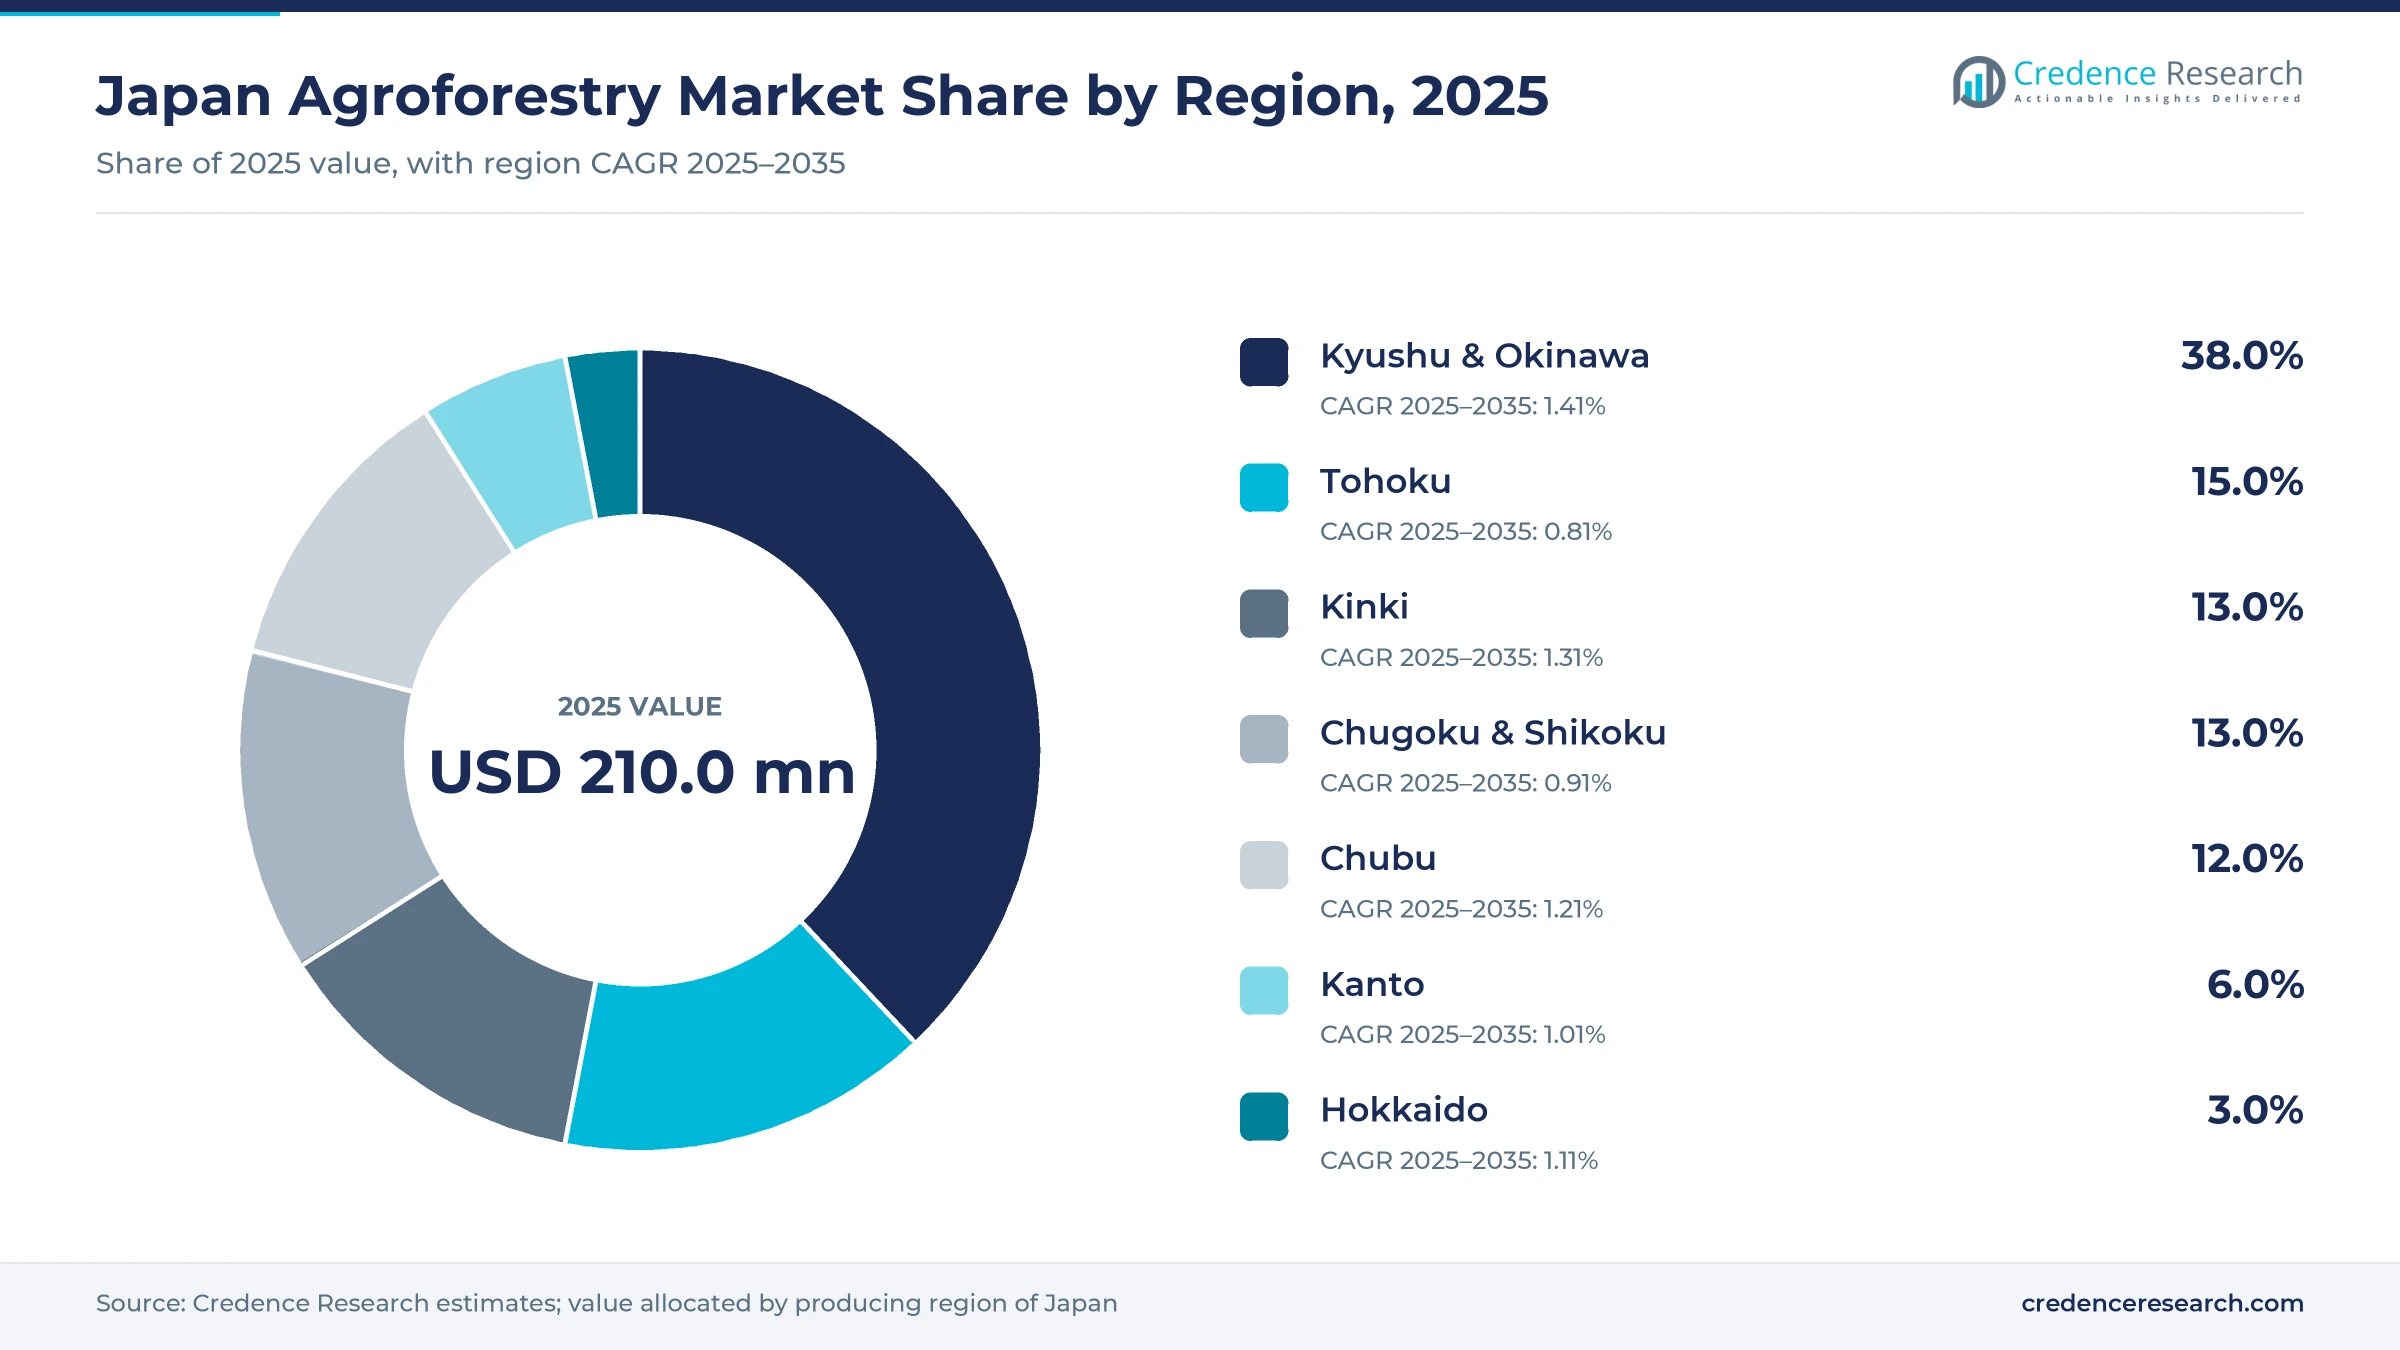
Kyushu leads on shiitake as Tohoku and Kinki specialize
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Kyushu & Okinawa | 38.0% | 1.41% |
| Tohoku | 15.0% | 0.81% |
| Kinki | 13.0% | 1.31% |
| Chugoku & Shikoku | 13.0% | 0.91% |
| Chubu | 12.0% | 1.21% |
| Kanto | 6.0% | 1.01% |
| Hokkaido | 3.0% | 1.11% |
Kyushu & Okinawa form the shiitake and bamboo shoot heartland
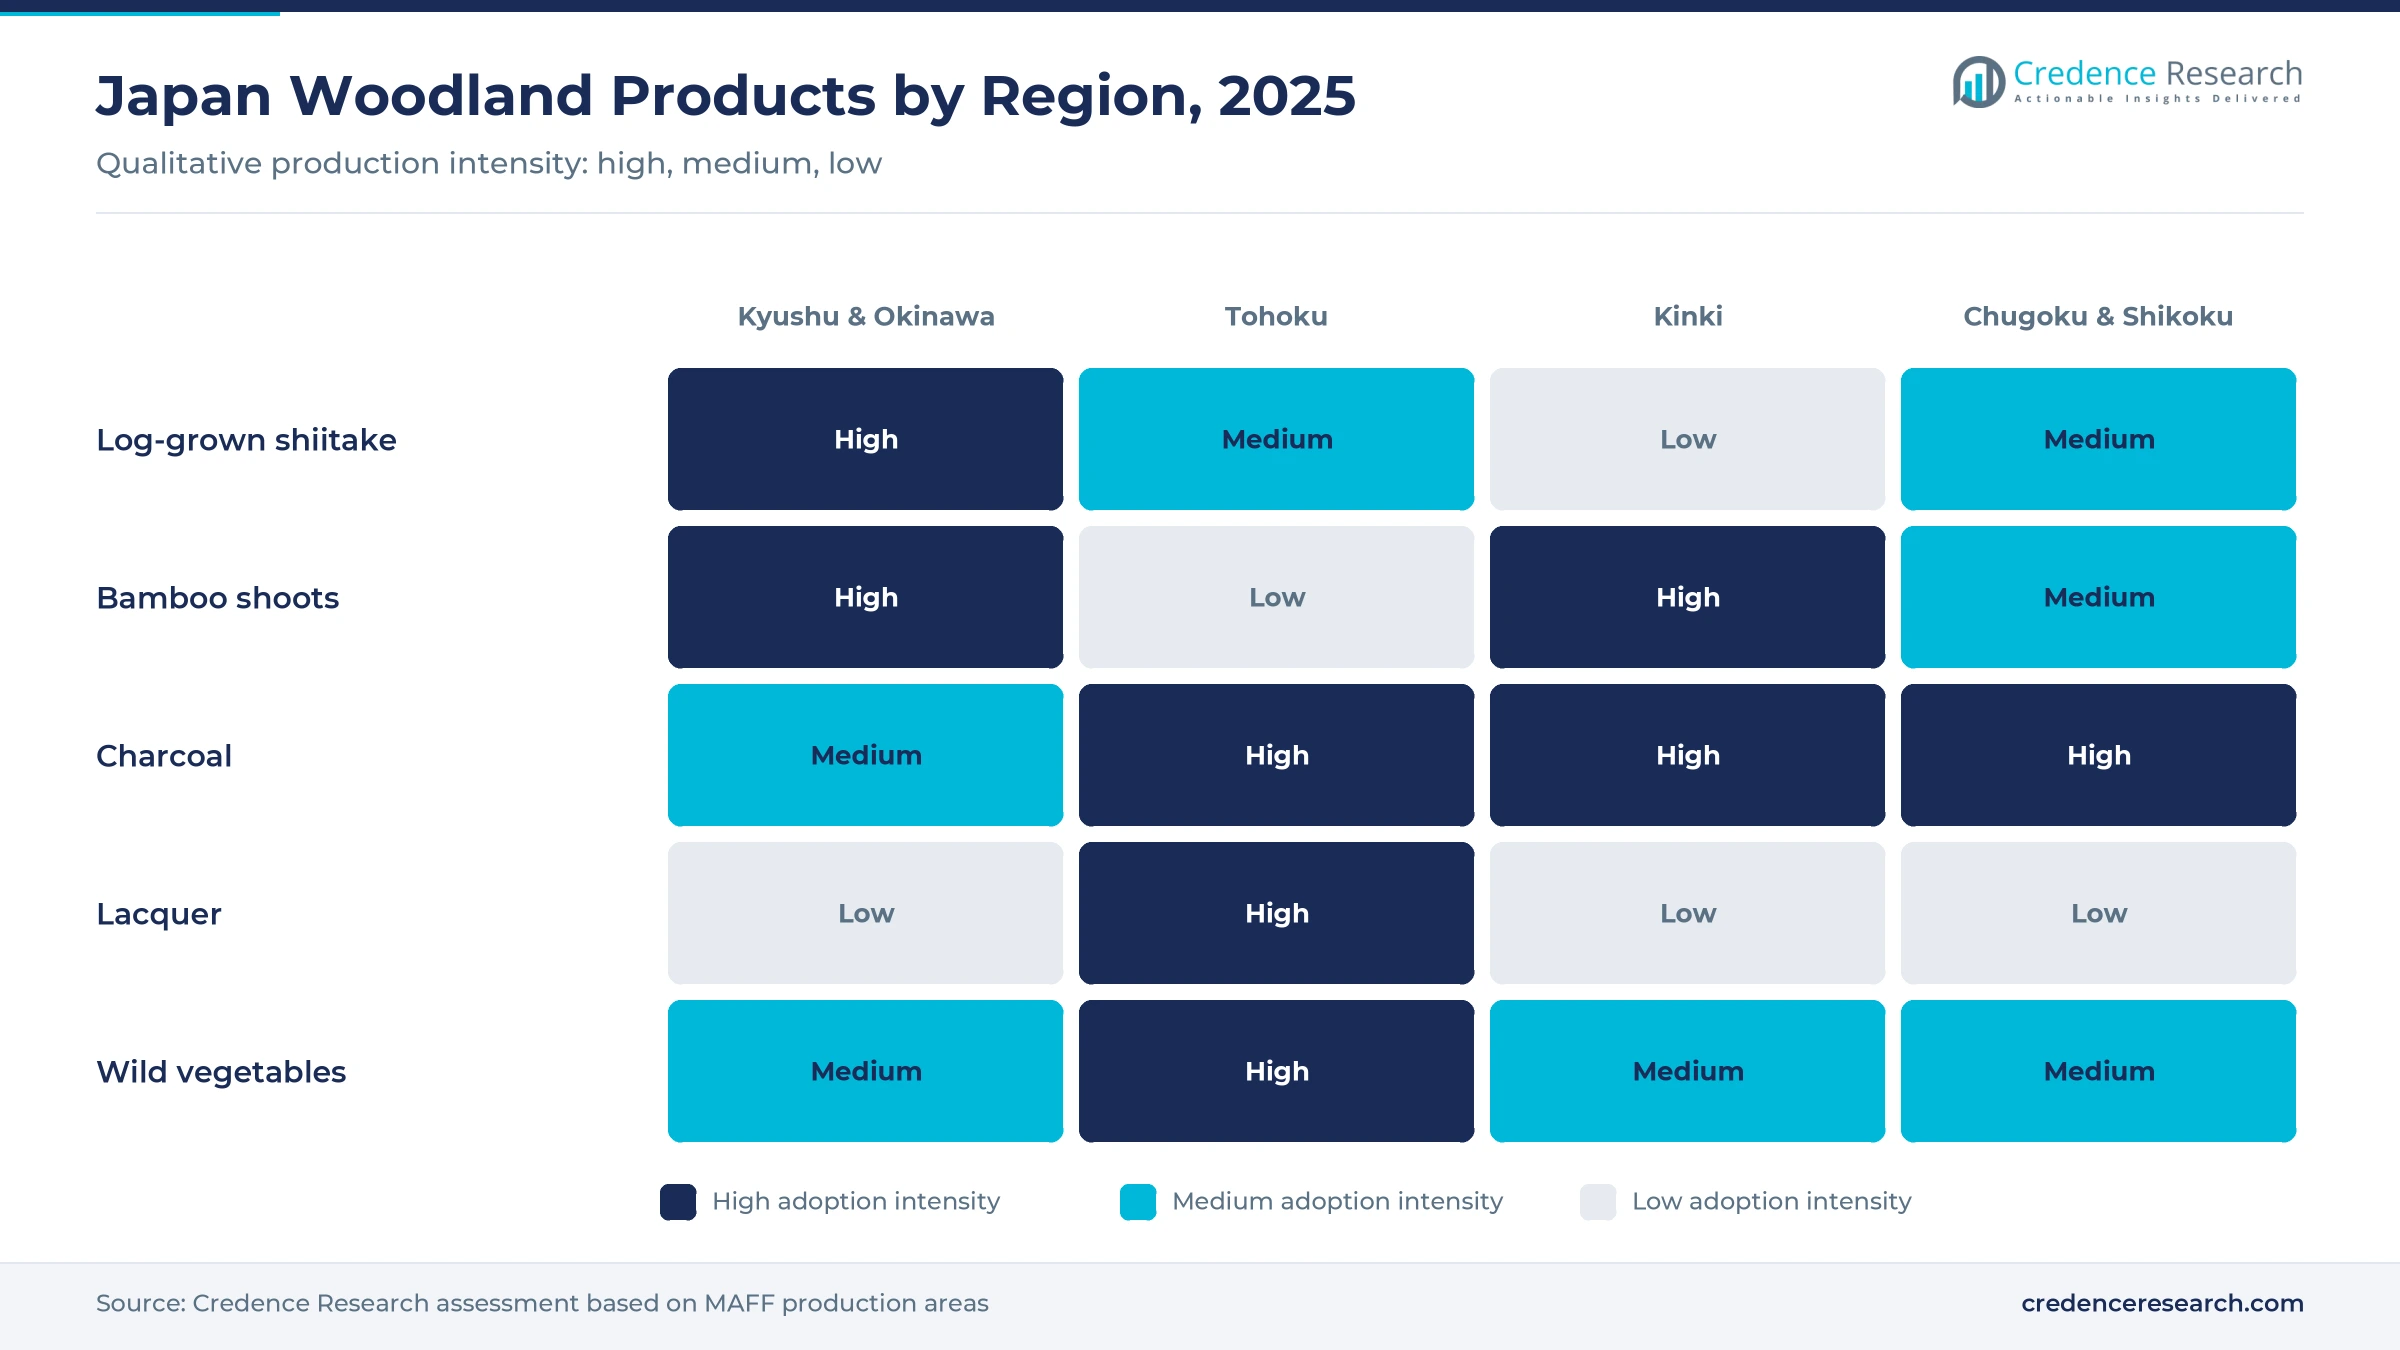
Kyushu and Okinawa held 38.0% of 2025 value and are the fastest-growing region at 1.41% a year. Oita, Miyazaki and Kumamoto are the main dried shiitake producers, and Fukuoka, Kagoshima and Kumamoto lead bamboo shoot output, while Kagoshima and Kumamoto also lead bamboo culm production. Cooperative auctions in Oita and processors such as Sugimoto Co. in Miyazaki give the region the strongest grading, branding and export channels in the market, which supports its premium prices.
Tohoku's lacquer and charcoal are held back by log restrictions
Tohoku held 15.0% of 2025 value and grows at 0.81% a year, the slowest of the seven regions. Iwate leads domestic lacquer tapping and wood vinegar output and is a major charcoal producer. Log mushroom growing in parts of the region is still constrained by restrictions on logs after 2011, which holds back the log-grown share. Lacquer demand for cultural property repairs is the region's clearest source of growth, though tapping requires skilled, scarce labor.
Kinki produces Kishu binchotan and Kyoto bamboo shoots
Kinki held 13.0% of 2025 value and grows at 1.31% a year. Wakayama's Kishu binchotan is Japan's best-known white charcoal, sold to yakitori and unagi restaurants at premium prices, and Kyoto's spring bamboo shoots are a seasonal delicacy for restaurants and gift buyers. Woodland tourism in the region also supports direct sales of these products. The region's value depends on a small number of aging charcoal makers, so succession among those makers will shape its output through 2035.
Chugoku & Shikoku, Chubu, Kanto and Hokkaido host smaller, specialized producers
Chugoku and Shikoku held 13.0% and grow at 0.91% a year; Kochi makes Tosa binchotan and Ehime grows log shiitake. Chubu held 12.0% and grows at 1.21% a year, with log-grown shiitake and mountain vegetables in Shizuoka and Gifu and fuelwood from Nagano. Kanto held 6.0% and grows at 1.01% a year, as Tochigi and Gunma grow log mushrooms and Ibaraki and Tochigi tap lacquer. Hokkaido held 3.0% and grows at 1.11% a year on wild vegetables, fuelwood and charcoal.
A forest tax, a mushroom target and 2025 survey releases
| Development | Status and market relevance |
|---|---|
| In August 2026, MAFF announced final 2025 special forest product statistics, showing dried shiitake output up 9.5% to 1,724 metric tons. | Final data. Confirms resilience in the premium log-grown segment. |
| In June 2026, MAFF published first results of its 2025 special forest product survey, including a 22.5% fall in bamboo shoot output to 16,176 metric tons. | First release. Shows how weather swings woodland volumes. |
| In April 2025, the Cabinet adopted the Basic Plan for Food, Agriculture and Rural Areas, which introduced a 2030 mushroom output target of 470,000 metric tons. | Adopted. Sets the national production goal for mushrooms. |
| In April 2024, Japan began levying the national forest environment tax for fiscal 2024, at JPY 1,000 per resident a year collected by municipalities. | In force. Funds woodland care that supports log, bamboo and charcoal producers. |
Log craft, spawn strains and grove care shape technology
- Log cultivation by younger growers uses shade netting, watering systems and digital monitoring to steady log shiitake yields as hot summers become more common.
- Spawn strains from suppliers such as Mori Sangyo and Akiyama Mushroom Research set fruiting timing and quality on inoculated oak logs.
- Grove and coppice care through thinning funded by the forest environment tax restores oak coppice for logs and charcoal and revives neglected bamboo groves.
- Traceability through origin labels, grading and regional brands lets buyers verify log-grown and binchotan products and pay a premium for them.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Cooperatives and processors organize thousands of growers
The Japan agroforestry market is highly fragmented, as thousands of family growers produce most output, while cooperatives and a few branded companies handle grading, marketing and sales. The Oita Prefecture Shiitake Agricultural Cooperative runs one of Japan's largest dried shiitake auctions, and JA Zen-Noh handles farm produce nationally, though its role in woodland products is not confirmed. Branded processors such as Sugimoto Co. in Miyazaki sell and export dried shiitake. Spawn suppliers Mori & Company (Mori Sangyo) and Akiyama Mushroom Research provide the critical input for log growers. Members of JForest, the National Federation of Forest Owners' Cooperative Associations, manage woodland used for mushroom logs and bamboo, and Kishu and Tosa binchotan makers sell through their own associations. Players compete on quality, origin and reliable supply rather than price, and slow consolidation favors firms with strong brands and export channels. No company reports comparable sales, so no share ranking is given.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Oita Prefecture Shiitake Agricultural Cooperative | Cooperative | Runs one of the largest dried shiitake auctions in Japan |
| Sugimoto Co. | Branded processor | Dried shiitake processing and export, Miyazaki |
| Mori & Company (Mori Sangyo) | Spawn supplier | Shiitake spawn and growing supplies for log growers |
| Akiyama Mushroom Research | Spawn supplier | Shiitake spawn for log cultivation |
| JForest (National Federation of Forest Owners Cooperative Associations) | Forest owners federation | Members manage woodland used for mushroom logs and bamboo |
| JA Zen-Noh | Agricultural cooperative federation | National farm produce marketing; woodland product role not confirmed |
Prices, not volumes, set Japan woodland farm value
Credence Research's view is that Japan woodland farming is a price-led niche, not a volume business, and that dried shiitake prices, more than acreage, set the market's value through 2035. The largest new revenue lies in branded dried shiitake, binchotan for restaurants, domestic lacquer for restoration and direct sales. Cooperatives and processors that consolidate retiring growers' log yards and build export channels are best positioned. The main risk is the grower base shrinking faster than prices rise. Buyers should watch MAFF output data, grower counts and log supply.
How Credence Research sized woodland-grown output in Japan
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built product by product from MAFF special forest product statistics by growing method; segment and regional splits are Credence Research estimates. Supporting evidence comes from MAFF and Forestry Agency statistics, the Forestry Agency's annual white paper and prefectural production records. However, sparse price data for wild products limits the estimate's precision.
Fewer growers and higher prices shape the outlook to 2035
Through 2035, Japan's woodland farm output will come from fewer, larger growers selling more under regional brands and directly to buyers. Dried shiitake prices will stay high as supply tightens, bamboo shoot volumes will keep swinging with weather, and lacquer will gain from restoration demand. Kyushu and Okinawa will strengthen their lead, while Tohoku recovers slowly. Investment will flow to log yard consolidation, grove thinning and export channels. The pace will depend on how quickly growers retire and on oak log supply.
Frequently Asked Questions
What was the size of the Japan agroforestry market in 2025?
What is the forecast value and CAGR of the Japan agroforestry market?
What drives Japan agroforestry value?
Which region of Japan holds the largest share?
Which product leads the Japan agroforestry market?
Who are the main players in Japan agroforestry?
Which sales channel grows fastest?
Why is growth in Japan agroforestry slow?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Log-Grown Mushrooms
- 1.2.2 Bamboo Shoots & Bamboo
- 1.2.3 Charcoal & Fuelwood
- 1.2.4 Nuts, Wild Vegetables & Lacquer
- 1.3 By Sales Channel
- 1.3.1 Wholesale Markets & Cooperatives
- 1.3.2 Direct & Online Sales
- 1.3.3 Processors & Food Service
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 210.0 million → 2035: USD 236.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Agroforestry Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Agroforestry Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Agroforestry Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Agroforestry Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Agroforestry Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Agroforestry Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Agroforestry Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Agroforestry Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 210.0 million → 2035: USD 236.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Agroforestry Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Log-Grown Mushrooms
- 12.3.7.2 Bamboo Shoots & Bamboo
- 12.3.7.3 Charcoal & Fuelwood
- 12.3.7.4 Nuts, Wild Vegetables & Lacquer
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wholesale Markets & Cooperatives
- 12.4.7.2 Direct & Online Sales
- 12.4.7.3 Processors & Food Service
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Agroforestry Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Agroforestry Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Agroforestry Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Oita Prefecture Shiitake Agricultural Cooperative
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Sugimoto Co.
- 17.4 Mori & Company (Mori Sangyo)
- 17.5 Akiyama Mushroom Research
- 17.6 JForest (National Federation of Forest Owners Cooperative Associations)
- 17.7 JA Zen-Noh
- 17.8 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

