
Market Overview:
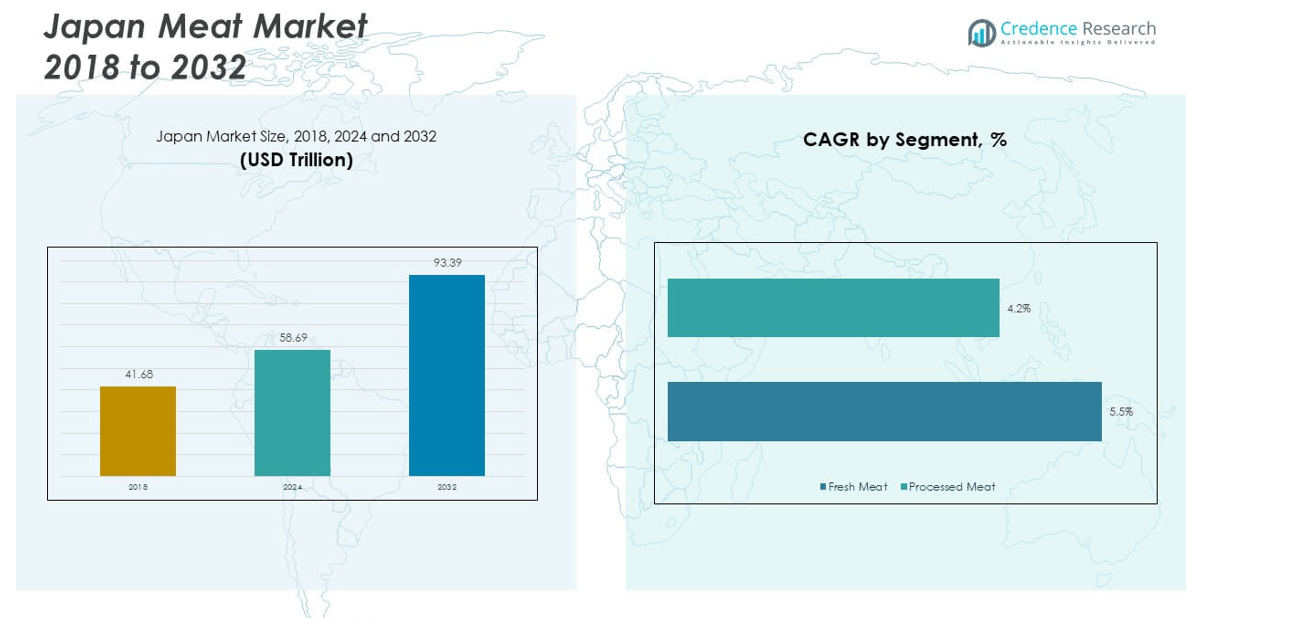
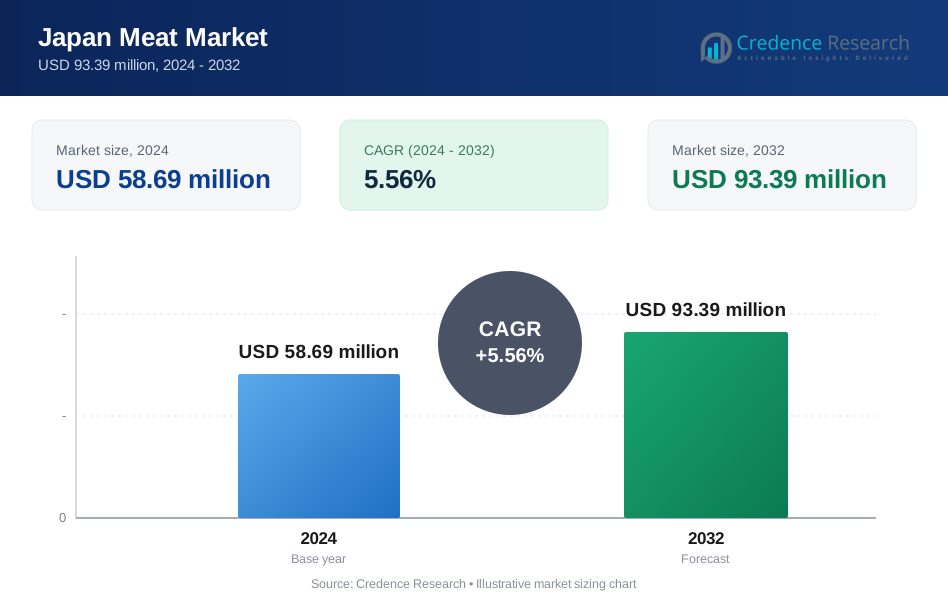
The Japan Meat Market size was valued at USD 41.68 million in 2018 to USD 58.69 million in 2024 and is anticipated to reach USD 93.39 million by 2032, at a CAGR of 5.56% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Meat Market Size 2024 | USD 58.69 million |
| Japan Meat Market, CAGR | 5.56% |
| Japan Meat Market Size 2032 | USD 93.39 million |
Growth in the Japan Meat Market is supported by rising demand for protein-rich diets, premiumization of meat categories, and technological advancements in processing. Consumers are showing stronger preference for high-quality beef, pork, and poultry products, while convenience-driven lifestyles boost adoption of processed and ready-to-cook meat. It also benefits from government support for food safety regulations, strict quality checks, and traceability systems that increase consumer trust. Expanding retail networks, including supermarkets and online platforms, further drive accessibility and availability across demographics.
Regionally, the market reflects strong dominance of urban hubs with higher consumption patterns and advanced retail penetration. Kanto leads with its dense population and metropolitan demand, while Kansai gains strength through premium beef offerings such as Kobe beef, which hold global recognition. Kyushu and surrounding regions serve as important production bases for poultry and pork, ensuring domestic supply stability. Emerging cities across Japan are witnessing stronger adoption of processed and convenience-based meat formats. It highlights a balance between traditional dietary preferences and modern consumption trends across regions.
Market Insights
- The Japan Meat Market size was valued at USD 41.68 million in 2018, grew to USD 58.69 million in 2024, and is projected to reach USD 93.39 million by 2032, expanding at a CAGR of 5.56%.
- Kanto holds 38%, Kansai 27%, and Kyushu 35% of the market, with Kanto leading due to metropolitan demand, Kansai supported by premium beef brands, and Kyushu driven by pork and poultry production hubs.
- Kyushu emerges as the fastest-growing subregion with its 35% share, supported by domestic farming strength, pork exports, and strong government support for supply chain resilience.
- Fresh meat accounts for 62% of the market, reflecting strong consumer preference for authenticity, natural taste, and traditional culinary use.
- Processed meat contributes 38%, showing momentum in urban markets where convenience, ready-to-cook meals, and packaging innovation drive demand.
Market Drivers
Rising Demand For High Quality And Protein-Rich Meat Products Among Health-Conscious Consumers
The Japan Meat Market benefits from increasing demand for high-protein diets driven by urban lifestyles. Consumers prefer lean cuts and premium categories such as wagyu beef, supported by rising income levels. It reflects strong consumer focus on health, nutrition, and food safety. Awareness campaigns about protein benefits accelerate product adoption across different demographics. Modern retail formats and specialty stores expand access to diverse meat products. Foodservice operators strengthen this growth by offering premium meat dishes in restaurants and hotels. The shift toward functional foods and balanced nutrition further strengthens the role of meat. Continuous product innovation by suppliers sustains consumer confidence.
- For example, in April 2025, IntegriCulture unveiled seven prototypes of cultivated duck liver at a Tokyo event, including restaurant dishes and packaged products, supported by Japan’s Ministry of Agriculture, Forestry and Fisheries. This milestone showcased Japan’s progress in premium alternative meats for foodservice and retail.
Government Support And Strict Food Safety Regulations Enhancing Consumer Trust
The Japan Meat Market gains momentum from strict government regulations that ensure product safety and traceability. Authorities emphasize monitoring systems covering slaughtering, packaging, and retail operations. It builds higher trust among consumers who are conscious of food origins. Advanced inspection frameworks improve quality consistency and market transparency. Certification programs increase appeal for premium and organic meat categories. Retailers benefit from clear compliance standards that help reassure customers. Food processors align with government norms to expand market credibility. Industry collaborations on safety practices reinforce long-term growth stability.
Technological Advancements In Processing And Packaging Improving Shelf Life And Efficiency
Technological innovation plays a major role in driving expansion across the Japan Meat Market. Advanced processing machinery enhances yield while reducing manual intervention. It ensures consistent quality across large-scale production units. Modified atmosphere packaging and vacuum sealing improve product shelf life. Automated storage and cold-chain logistics enhance supply reliability. These developments support the growth of ready-to-eat and convenience-based meat categories. Manufacturers use smart labeling for transparency on nutrition and sourcing. Continuous R&D investment creates sustainable and efficient processing solutions. Integration of robotics further optimizes hygiene and throughput levels.
Expansion Of Retail Networks And Changing Consumer Preferences Toward Convenient Formats
The Japan Meat Market benefits from retail modernization and expansion of supermarkets and online channels. Consumers increasingly prefer convenient formats such as pre-cut, marinated, and ready-to-cook meat. It reflects lifestyle changes influenced by urbanization and smaller household sizes. E-commerce platforms create new growth avenues by offering doorstep delivery. Food delivery services expand access to premium meat products for busy consumers. Modern packaging ensures safety and convenience during transport. Retailers adapt assortments to meet varied consumer preferences in different cities. These developments strengthen market penetration across traditional and modern channels.
- For instance, in April 2025, AEON launched three new “TOPVALU Best Price” frozen one-plate meals featuring ready-to-eat Japanese and Western dishes, available at approximately 2,900 stores nationwide including AEON, AEON Style, and MaxValu outlets. The line was specifically designed for household convenience and immediate microwave preparation, reflecting the retailer’s response to changing lifestyles and demand for accessible premium meat meal options.
Market Trends
Growth In Plant-Based Alternatives Complementing Traditional Meat Consumption Patterns
The Japan Meat Market observes a rise in demand for plant-based meat alternatives alongside traditional categories. Urban consumers seek balance between sustainability and taste preferences. It reflects the influence of global dietary trends within domestic markets. Major retailers introduce hybrid products that mix plant proteins with meat. Foodservice operators innovate with plant-based menus appealing to younger demographics. This trend complements rather than replaces core meat demand. Investments in R&D enhance taste and texture of substitutes. The dual growth path strengthens overall protein market development.
Increasing Focus On Premiumization And Niche Meat Segments Across Foodservice Sector
Premiumization strongly influences the Japan Meat Market, with demand for wagyu beef and heritage pork rising. Consumers value authenticity, traceability, and regional branding. It strengthens local farmers who highlight specialty breeds and unique flavors. High-end restaurants use storytelling to create stronger connections with diners. Specialty meat imports diversify offerings beyond domestic supply. This trend supports higher margins for suppliers catering to premium customers. Chefs experiment with niche meats to expand menu creativity. Long-term focus remains on quality over quantity in consumer decision-making.
- For instance, in July 2025, Starzen Co., Ltd. launched the AOMORI GOLD Japanese wagyu beef brand, graded A4 or higher and processed at the Sannohe Beef Center in Aomori Prefecture, for export. This brand maintains rigorous artisanal and hygiene standards, and represents a new addition to Starzen’s export offerings. The brand launch is verified through Starzen’s own press documentation.
E-Commerce Expansion Creating New Sales Channels For Fresh And Frozen Meat Products
The Japan Meat Market experiences strong momentum from online grocery platforms and digital delivery models. Consumers embrace subscription services offering regular meat deliveries. It reduces dependence on traditional wet markets and small shops. Cold-chain improvements enable secure transport of fresh and frozen products. It provides flexibility for households in urban areas with limited time. Online reviews and ratings influence consumer choice of meat brands. Retailers expand into regional markets through online sales channels. This trend accelerates convenience-driven consumption across the country.
- For example, in August 2024, Rakuten Group, Inc. announced the rebranding of its online grocery service to “Rakuten Mart,” offering fresh, frozen, and refrigerated foods. Its temperature-controlled fulfillment centers in the Tokyo metropolitan and Kansai regions can process up to 70,000 orders per day, as confirmed in the company’s official press release.
Innovation In Ready-To-Eat And Convenience-Based Meat Products For Busy Urban Consumers
Ready-to-eat innovations reshape the Japan Meat Market by meeting demand from working professionals. Packaged meals include grilled meats, skewers, and high-protein snacks. It reflects the strong influence of urban lifestyle and long working hours. Food manufacturers expand product ranges for lunchbox-friendly portions. Convenience stores stock innovative meat options for quick purchases. Packaging technology ensures freshness while enhancing portability. This trend drives strong loyalty among young and middle-aged consumers. Suppliers use product differentiation to target niche groups like fitness enthusiasts.
Market Challenges Analysis
Rising Import Dependence And Vulnerability To Global Supply Chain Disruptions
The Japan Meat Market faces structural challenges due to its reliance on imported beef, pork, and poultry. It exposes the sector to risks linked with currency fluctuations and global trade disputes. Import disruptions from key suppliers such as the U.S. and Australia create instability. It pressures local processors and retailers to manage volatile pricing. Domestic production cannot fully meet growing demand. Rising transportation costs also strain profitability across the value chain. Dependence on external sources limits flexibility in market strategy. Maintaining balance between imports and domestic supply remains complex.
High Production Costs And Labor Shortages Affecting Local Meat Industry Competitiveness
The Japan Meat Market encounters difficulties linked with rising production costs and limited workforce availability. It challenges small and medium-scale farmers operating under tight margins. Feed costs, energy prices, and compliance requirements increase overall expenses. Modernization requires large capital investment that not all producers can manage. Labor shortages impact efficiency in processing plants and farms. It restricts growth capacity despite rising consumer demand. Rural depopulation reduces available workforce for agriculture and meat production. This structural challenge demands long-term solutions for industry resilience.
Expanding Export Potential For Specialty And Premium Meat Categories In Global Markets
The Japan Meat Market holds strong opportunities through export of wagyu beef and premium cuts. International demand for Japanese meat products continues to rise in Asia, Europe, and North America. It benefits from the reputation of quality, taste, and traceability associated with Japanese farming practices. Trade agreements enhance access to global buyers. Suppliers position wagyu as a luxury product appealing to high-income groups. Expanding certifications build trust among overseas consumers. Tourism promotion also enhances brand image for Japanese meat abroad. Export growth diversifies revenue streams for local farmers.
Integration Of Digital Platforms And Smart Supply Chains To Enhance Efficiency And Reach
The Japan Meat Market has opportunities in adopting digital tools and advanced logistics for greater efficiency. E-commerce integration expands market access for both domestic and global consumers. It enables better customer engagement through data-driven insights. Smart cold-chain systems reduce waste and ensure consistent quality. Automation within warehouses supports faster deliveries. Cloud-based platforms connect farmers, processors, and retailers seamlessly. These developments support scalable operations for future growth. It helps the industry align with changing consumer expectations in an increasingly digital economy.
Market Segmentation Analysis
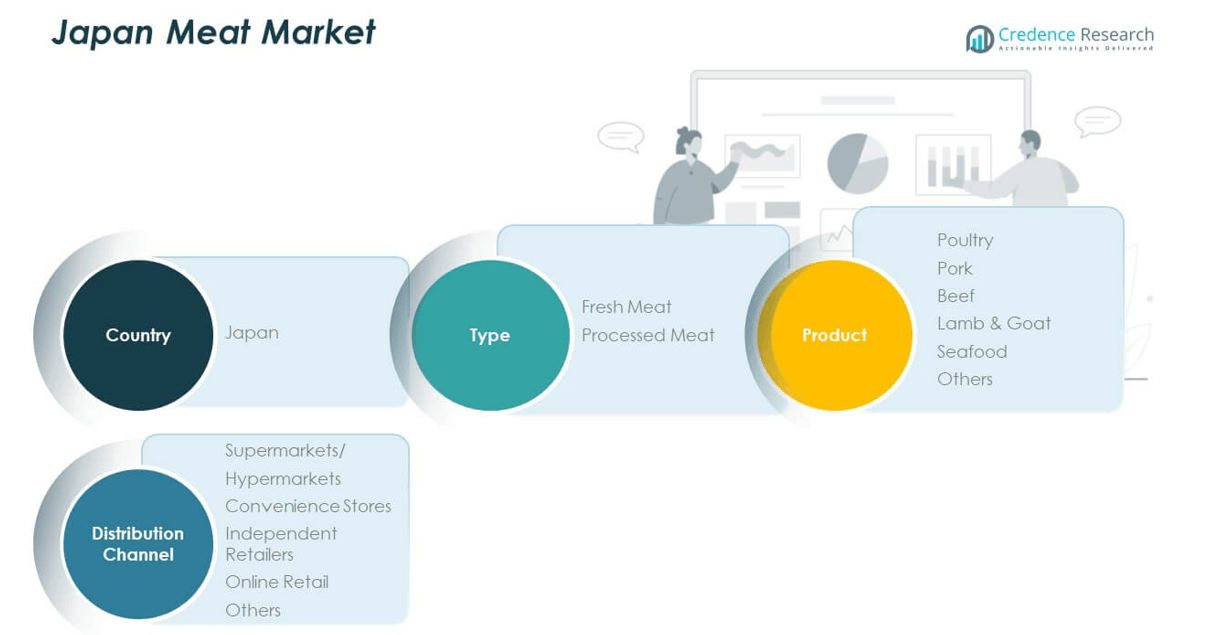
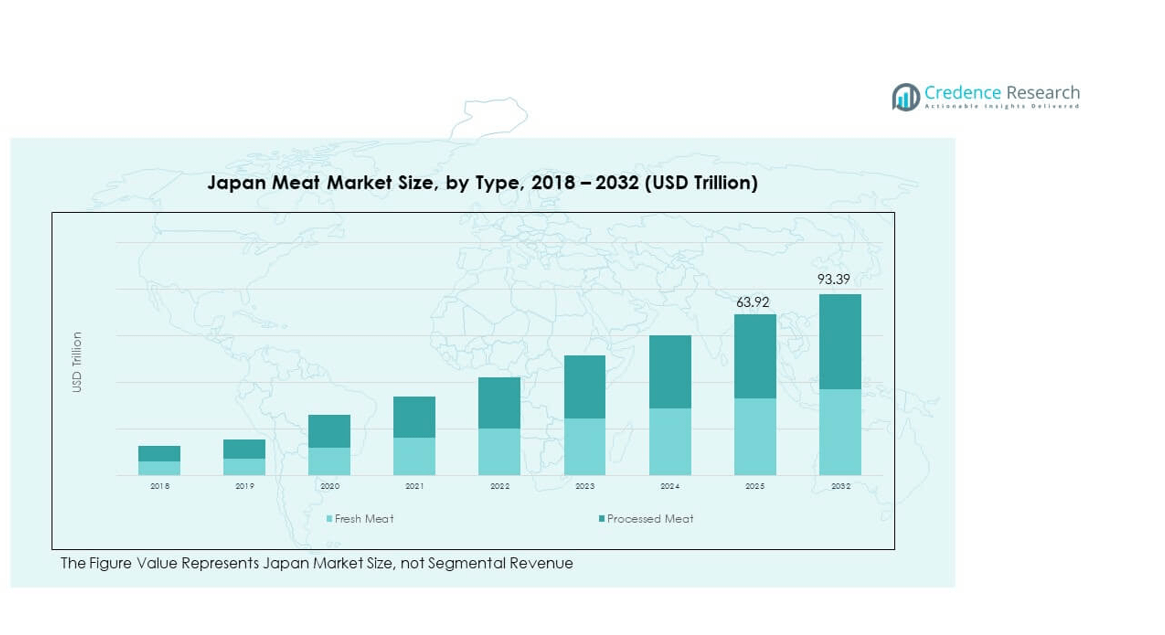
By type, the Japan Meat Market is divided into fresh meat and processed meat. Fresh meat dominates household consumption due to cultural preference for authenticity and natural taste, while processed meat shows strong growth in urban centers where ready-to-cook and convenience categories align with fast-paced lifestyles. It benefits from continuous innovation in packaging that extends shelf life and ensures quality.
- For instance, NH Foods the largest supplier of fresh and processed meat in Japan-reported that its business profit increased to ¥44.9 billion in fiscal 2023 (ending March 2024), up from ¥25.6 billion the previous year, credited in part to product mix enhancement and investments in processing and packaging technologies.
By product, poultry holds a leading position, supported by affordability and consistent demand across foodservice and retail. Pork remains a traditional favorite, particularly in dishes unique to Japanese cuisine, while beef, especially wagyu, drives premiumization trends across domestic and international markets. Seafood retains a vital role in balanced diets, reflecting Japan’s deep culinary heritage, while lamb, goat, and other proteins appeal to niche consumer groups. It showcases a diverse product structure catering to multiple demographics and consumption occasions.
- For instance, Jukuho Farm won the Gold Medal at the World Steak Challenge 2024 in Europe for its Japanese beef, signifying international recognition for technological achievement in meat processing and freshness standards that meet rigorous export criteria.
By distribution channel, supermarkets and hypermarkets remain dominant due to extensive availability and strong trust in branded supply chains. Convenience stores capture significant share by offering ready-to-eat and pre-packed options for urban consumers. Independent retailers maintain presence in regional markets where personalized service attracts loyal customers. Online retail grows rapidly, supported by cold-chain expansion and rising consumer comfort with digital platforms. It reflects the market’s shift toward hybrid distribution models that balance tradition and technology.
Segmentation
By Type
- Fresh Meat
- Processed Meat
By Product
- Poultry
- Pork
- Beef
- Lamb & Goat
- Seafood
- Others
By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Independent Retailers
- Online Retail
- Others
By Country
- Japan
Regional Analysis
Kanto Region
The Kanto region dominates the Japan Meat Market, holding 38% share due to its large population base and concentration of urban centers such as Tokyo and Yokohama. Consumer demand is driven by diverse culinary preferences, with strong traction for premium beef, pork, and poultry. It benefits from advanced cold-chain logistics and the presence of major supermarkets and convenience stores. Restaurants and foodservice operators in metropolitan areas heavily influence meat consumption trends. High disposable incomes support growing demand for imported premium meat varieties. Retail and e-commerce channels play a crucial role in expanding reach within this subregion.
Kansai Region
he Kansai region contributes 27% share of the Japan Meat Market, supported by cities such as Osaka, Kyoto, and Kobe. Local preferences highlight beef, particularly Kobe beef, which holds global recognition for quality and authenticity. It reflects strong consumer attachment to heritage meat products. Modern retail formats are well established, enhancing access to fresh and processed meat categories. Regional branding initiatives support premium positioning, particularly for wagyu. Food tourism also strengthens demand, with Kansai’s cuisine culture influencing both domestic and international consumption patterns.
Kyushu and Other Regions
Kyushu and other regions collectively account for 35% share of the Japan Meat Market, with Kyushu recognized as a key production hub for pork and poultry. It benefits from proximity to domestic farming clusters, ensuring a reliable supply base. Consumer demand in these regions is shaped by a mix of traditional diets and modern convenience-oriented meat products. Regional exporters play a growing role in supplying international markets, particularly wagyu and pork. Online retail penetration is expanding across smaller cities, creating fresh demand opportunities. Strong domestic farming support policies sustain regional competitiveness against imports.
Key Player Analysis
- Prima Meat Packers Group
- Japanmeat Co., Ltd.
- Nippon Ham Co., Ltd.
- Itoham Foods Inc.
- NH Foods Ltd.
- Mitsubishi Shokuhin Co., Ltd.
- Kanematsu Corporation
- Marudai Food Co., Ltd.
- Nishi-Nippon Best Packer Co., Ltd.
- Kamifurano Farm Ltd.
Competitive Analysis
The Japan Meat Market is characterized by a mix of established domestic companies and diversified conglomerates. Leading players such as NH Foods Ltd., Nippon Ham Co., Ltd., and Itoham Foods Inc. dominate market share with extensive distribution networks and broad product portfolios. It reflects strong competition across fresh, processed, and premium meat categories. Companies focus on maintaining brand loyalty through quality assurance, product innovation, and traceability programs. International trade agreements create opportunities for expansion of premium exports like wagyu beef. Key players also invest in digital platforms and automation to strengthen supply chains. Competition intensifies as regional processors and niche producers highlight specialty meats, reinforcing a dynamic and evolving market landscape.
Recent Developments
- In August 2025, Itoham Yonekyu Holdings demonstrated significant momentum in Japan’s processed meat sector, reporting powerful first-quarter fiscal 2026 results with revenue of JP¥297.1 billion and a net income of JP¥6.38 billion, strengthening its position in both fresh and processed meats for supermarket and retailer distribution channels.
- In August 2025, Japanese beef bowl chain Sukiya announced its first price cuts in 11 years, reducing the price of beef bowls and related dishes starting September 4, 2025, across all its convenience and independent retail outlets, in response to changing market conditions and consumer demand.
Report Coverage
The research report offers an in-depth analysis based on Type, Product and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan Meat Market will experience strong growth driven by rising demand for premium categories such as wagyu beef.
- It will see wider adoption of processed meat supported by evolving consumer lifestyles and convenience-driven diets.
- E-commerce and digital retail platforms will expand distribution reach and reshape consumer purchasing behavior.
- Technological advancements in cold-chain logistics and packaging will strengthen product safety and freshness.
- Export opportunities will increase, especially for high-value segments like wagyu, boosting international presence.
- Sustainability and traceability programs will gain importance, reinforcing consumer trust and brand loyalty.
- Urbanization and smaller household structures will expand demand for ready-to-eat and portioned meat products.
- Rising food tourism will enhance visibility for regional specialties and further elevate premium branding.
- Strategic investments in automation and robotics will improve processing efficiency and reduce labor dependency.
- Collaborations between domestic producers and global players will create new growth channels across the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Premiumization and Demand for High-Quality Meat
Japanese consumers are increasingly seeking premium meat products such as wagyu beef and heritage pork, driven by rising incomes, health consciousness, and a focus on food safety and traceability. This trend supports higher margins and stimulates innovation in specialty and branded meat categories.
Technological Advancements in Processing and Packaging
Investments in advanced processing machinery, modified atmosphere packaging, and cold-chain logistics are improving product shelf life, safety, and efficiency. These innovations enable the growth of ready-to-eat and convenience-based meat products, catering to urban and busy consumers.
Expansion of Retail and E-Commerce Channels
Modern retail networks, including supermarkets, convenience stores, and rapidly growing online platforms, are increasing accessibility and availability of meat products across demographics. E-commerce and digital delivery models are reshaping consumer purchasing behavior and expanding market reach.
Government Support and Stringent Food Safety Regulations
Strict government regulations and traceability systems enhance consumer trust in meat products, ensuring high standards for safety and quality. Certification programs and inspection frameworks support the growth of premium and organic meat segments, reinforcing market stability.
Shifting Consumer Lifestyles and Convenience Trends
Urbanization, smaller household sizes, and busy lifestyles are driving demand for processed, ready-to-cook, and portioned meat products. Retailers and manufacturers are responding with innovative packaging and product formats that align with evolving consumption habits.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Meat Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Meat Market projected to grow between 2024 and 2032?
Which Japan Meat Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Japan Meat Market?
Who are the leading companies in the Japan Meat Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Fresh Meat
- 1.2.2 Processed Meat
- 1.3 By Product
- 1.3.1 Poultry
- 1.3.2 Pork
- 1.3.3 Beef
- 1.3.4 Lamb & Goat
- 1.3.5 Seafood
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 58.69 million → 2032: USD 93.39 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Meat Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Meat Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Meat Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Meat Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Meat Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Meat Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Meat Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Meat Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 58.69 million → 2032: USD 93.39 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Meat Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fresh Meat
- 12.3.7.2 Processed Meat
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Poultry
- 12.4.7.2 Pork
- 12.4.7.3 Beef
- 12.4.7.4 Lamb & Goat
- 12.4.7.5 Seafood
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Meat Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Meat Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Meat Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 NH Foods Ltd.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Nippon Ham Co., Ltd.
- 17.4 Itoham Foods Inc.
- 17.5 Prima Meat Packers Group
- 17.6 Japanmeat Co., Ltd.
- 17.7 Mitsubishi Shokuhin Co., Ltd.
- 17.8 Kanematsu Corporation
- 17.9 Marudai Food Co., Ltd.
- 17.10 Nishi-Nippon Best Packer Co., Ltd.
- 17.11 Kamifurano Farm Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

