
Market Overview:
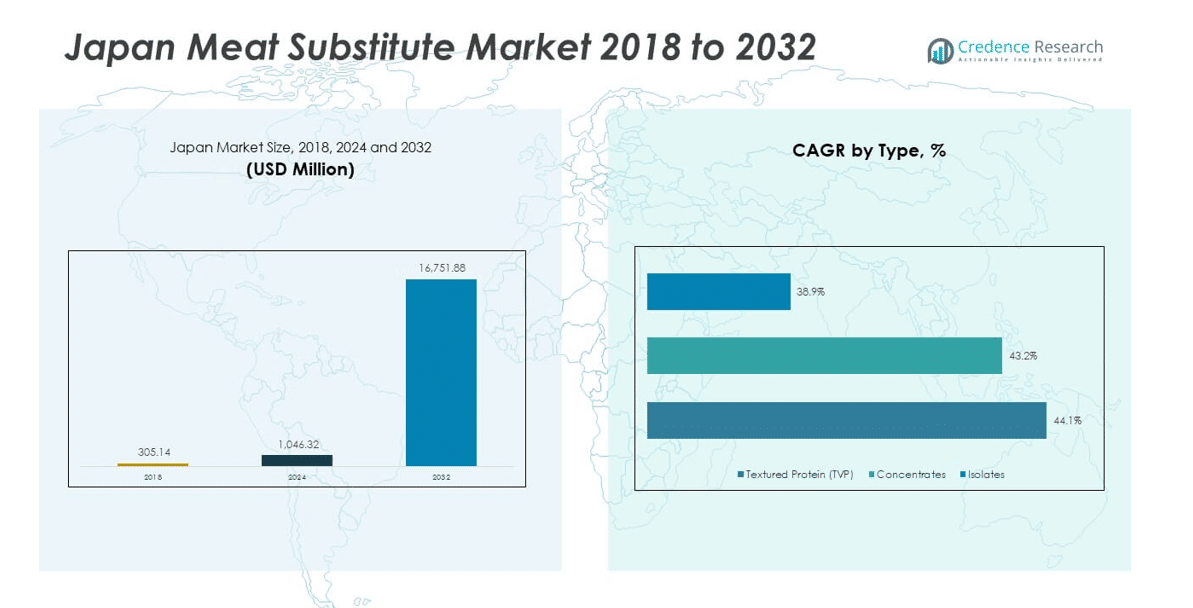
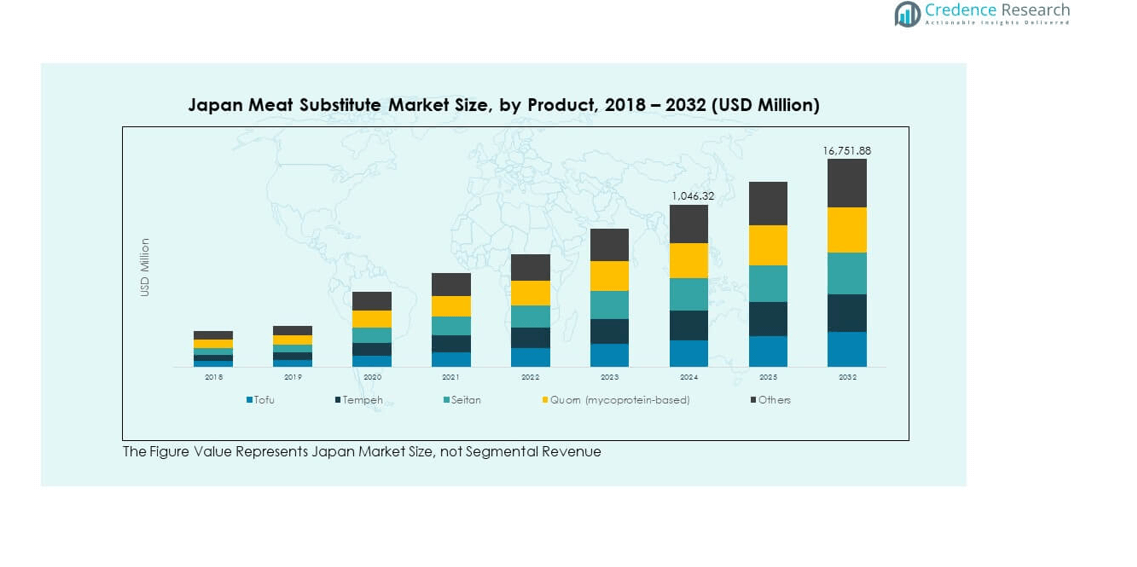
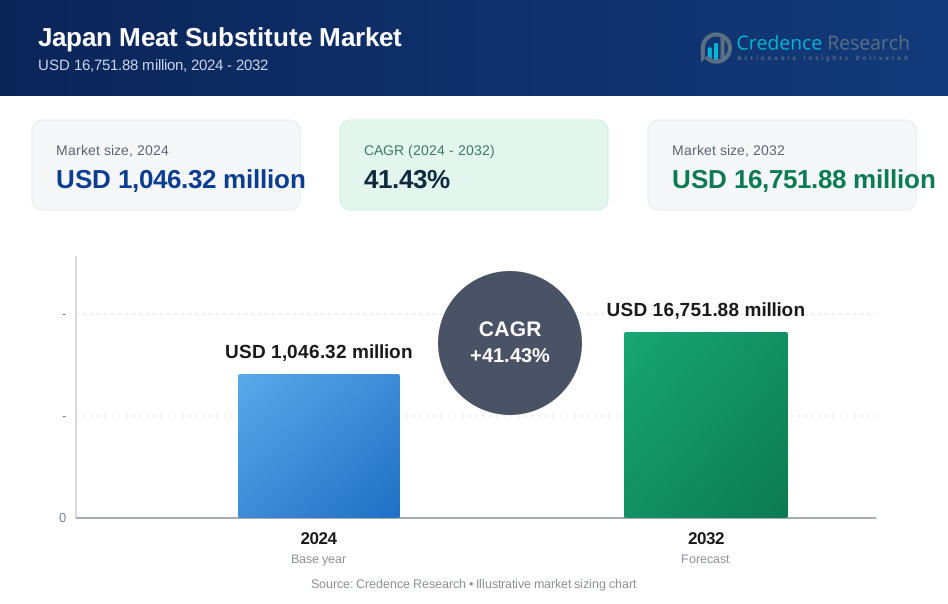
The Japan Meat Substitute Market size was valued at USD 305.14 million in 2018, rising to USD 1,046.32 million in 2024, and is anticipated to reach USD 16,751.88 million by 2032, at a CAGR of 41.43% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Meat Substitute Market Size 2024 | USD 1,046.32 million |
| Japan Meat Substitute Market, CAGR | 41.3% |
| Japan Meat Substitute Market Size 2032 | USD 16,751.88 million |
The Japan Meat Substitute Market is being driven by growing consumer awareness of health and wellness, particularly the demand for plant-based proteins as healthier alternatives to animal meat. Rising concerns about lifestyle diseases and obesity have pushed consumers to seek nutrient-rich and low-fat options. Younger demographics and urban populations are adopting flexitarian diets, which emphasize reduced meat consumption. Environmental sustainability is another strong driver, as consumers associate meat substitutes with lower carbon footprints and animal welfare. Increasing innovation in taste and texture has also strengthened consumer acceptance. Government and institutional support for sustainable food solutions further accelerates demand. Expanding retail networks and online platforms make these products more accessible. Together, these factors are shaping rapid adoption across the market.
Within Asia-Pacific, Japan plays a key role in the adoption of meat substitutes due to its developed food culture, advanced retail distribution, and openness to innovative food technologies. Urban centers like Tokyo and Osaka are leading adoption because of higher disposable incomes and health-conscious populations. While Japan shows significant growth, neighboring countries such as South Korea and China are emerging markets with expanding middle-class consumers and rising awareness of plant-based diets. Southeast Asian countries, although smaller in scale, are also seeing growth due to increasing vegan and vegetarian populations. Japan’s strong food innovation ecosystem positions it as both a leader and influencer in regional market dynamics.
Market Insights:
- The Japan Meat Substitute Market was valued at USD 305.14 million in 2018, reached USD 1,046.32 million in 2024, and is projected to hit USD 16,751.88 million by 2032, expanding at a CAGR of 41.43%.
- The Kanto region holds 38% share, driven by Tokyo’s large urban population and advanced retail infrastructure; Kansai follows with 26%, supported by Osaka’s vibrant foodservice sector; Chubu contributes 18%, anchored by Nagoya’s steady adoption.
- Kyushu and Hokkaido together represent 18% and are the fastest-growing regions, fueled by rising awareness, health campaigns, and expanding retail penetration.
- By product, tofu dominates with over 30% share in 2024, maintaining strong cultural acceptance and daily consumption patterns across Japan.
- Tempeh and seitan collectively account for nearly 25% share, reflecting growing popularity among younger, health-conscious consumers seeking high-protein and versatile alternatives.
Market Drivers:
Growing Health Awareness and Shift Toward Nutritious Food Choices
Rising health consciousness is reshaping consumer preferences across Japan. Growing numbers of consumers are reducing red meat intake due to concerns about obesity and cardiovascular diseases. The Japan Meat Substitute Market benefits directly from this lifestyle transition toward healthier diets. It is supported by flexitarian eating habits that balance traditional meals with sustainable protein alternatives. Demand is rising for products that offer high protein, lower fat, and added nutrition. Younger generations in urban centers are leading this shift, prioritizing fitness and wellness. Companies are responding by developing substitutes aligned with these health-focused consumer needs.
- For instance, in April 2021, Next Meats, a Tokyo-based company, introduced its soy-based plant-based yakiniku products in Singapore through a limited-time partnership with the restaurant chain Aburi-En. While Next Meats described the products as having nutritional advantages like higher protein and lower fat than regular meat, these were marketing claims based on the company's own information.
Environmental Concerns and Emphasis on Sustainability in Food Production
Climate concerns are playing a major role in shaping food choices. The Japan Meat Substitute Market is gaining momentum as consumers recognize the environmental cost of livestock farming. It is supported by eco-friendly campaigns highlighting reduced water use and lower emissions from plant-based substitutes. Government initiatives to promote sustainable food production also influence demand. Producers are introducing technologies that minimize waste and resource consumption. Ethical sourcing and cruelty-free branding are further driving consumer trust. Sustainability has become both a social and economic advantage for plant-based producers.
- For instance, Azuma Foods launched its plant-based seafood range 'Future Fish' in March 2024, featuring vegan tuna, salmon, and squid made from konjac, and reported a reduction in water usage compared to conventional seafood processing methods.
Advancements in Food Technology and Product Innovation Enhancing Acceptance
Technological innovation is transforming the taste and texture of substitutes. Early products often lacked authenticity in flavor and consistency. The Japan Meat Substitute Market now benefits from advanced formulations that replicate meat-like qualities. It is supported by research collaborations between global companies and Japanese food innovators. Continuous improvements in texture, shelf life, and nutrient retention increase consumer confidence. New product launches are also tailored to local cuisine preferences. These advancements reduce resistance and make substitutes viable for daily use.
Expansion of Retail Channels and Growth of Online Distribution Platforms
Availability is improving through diversified distribution channels. Major supermarket chains are expanding their plant-based offerings across Japan. The Japan Meat Substitute Market is also gaining traction through strong e-commerce platforms. It is reinforced by digital marketing campaigns that highlight product benefits and sustainable production methods. Subscription models are emerging, ensuring steady consumer access. Convenience and visibility in both physical and online stores normalize substitute consumption. Wider retail access is enabling consistent adoption across varied demographic groups.
Market Trends:
Rise of Premium Plant-Based Products Targeting Affluent Urban Consumers
Premiumization is emerging as a key trend in the evolving market. The Japan Meat Substitute Market is experiencing rising demand for gourmet substitutes with superior quality. It is supported by higher-income consumers in cities who value authenticity and taste. Premium brands focus on positioning substitutes as lifestyle products rather than basic alternatives. Restaurants and cafes are also adopting premium substitutes to attract health-conscious diners. Enhanced packaging and branding strategies emphasize exclusivity. This premium trend allows companies to differentiate and capture loyal audiences.
- For instance, Wayback Burgers Asia launched 'Next Restaurant' in Tokyo in October 2024, offering vegan bento and gourmet burgers that include dishes containing up to 30 grams of plant-based protein per serving, catering to upscale consumers seeking premium dining experiences.
Integration of Local Ingredients and Cultural Preferences in Product Innovation
Localization is shaping product strategies across Japan. The Japan Meat Substitute Market is adapting by incorporating familiar ingredients such as soy, konjac, and mushrooms. It is designed to align with Japanese food traditions while offering modern nutrition. These culturally adapted substitutes resonate with consumers seeking familiarity and trust. Companies are blending global innovation with regional tastes to ensure acceptance. The balance of tradition and innovation strengthens product appeal. Local ingredient integration builds authenticity and increases consumer loyalty.
- For instance, at the Expo 2025 Osaka in August 2025, Fuji Oil introduced a plant-based, tonkotsu-style ramen broth made using soy milk and its proprietary MIRACORE® technology. The new broth was featured at a limited-time event at the ORA Dining Pavilion and was well-received by international food professionals for its rich, creamy flavor.
Growing Role of Foodservice Sector in Normalizing Meat Substitute Consumption
Restaurants, fast-food outlets, and cafes are playing a vital role in adoption. The Japan Meat Substitute Market is expanding through foodservice integration. It is supported by major chains introducing plant-based burgers, nuggets, and set meals. Fine dining establishments are experimenting with creative menus featuring substitutes. This visibility encourages trial among hesitant consumers. Younger generations often discover substitutes first in foodservice before retail. Partnerships with foodservice providers amplify awareness and accelerate mainstream acceptance.
Collaborations, Investments, and Research Partnerships Strengthening Market Growth
Collaborative ecosystems are shaping future expansion strategies. The Japan Meat Substitute Market is benefiting from partnerships between startups, manufacturers, and universities. It is supported by venture capital investment in innovative technologies. Collaborations focus on scaling production, enhancing flavors, and improving affordability. Domestic producers are also working with global brands to share expertise. This partnership-driven ecosystem accelerates commercialization and consumer outreach. The trend ensures the market remains dynamic and competitive.
Market Challenges Analysis:
High Production Costs and Price Sensitivity Among Japanese Consumers
Cost remains a primary barrier for mass adoption across Japan. The Japan Meat Substitute Market faces limitations in competing with affordable animal-based products. It is burdened by expensive raw materials and advanced production technologies. Many consumers remain sensitive to higher prices, especially in rural regions. Achieving economies of scale is still a challenge for smaller producers. Companies must balance affordability with innovation to expand reach. Until price gaps are reduced, substitutes will struggle to achieve wider penetration.
Cultural Barriers and Limited Awareness in Non-Urban Populations
Cultural traditions present hurdles in market expansion. The Japan Meat Substitute Market is influenced by long-standing culinary habits that favor seafood and meat. It is hindered by perceptions that substitutes are overly processed. Limited consumer education reduces acceptance outside major cities. Resistance is stronger in older demographics who prefer traditional diets. Awareness campaigns and targeted education are required to overcome skepticism. Without stronger cultural integration, adoption may remain concentrated in metropolitan regions.
Market Opportunities:
Expanding Export Potential and Positioning Japan as a Regional Innovator
Export opportunities are growing as global demand rises for premium substitutes. The Japan Meat Substitute Market has the potential to serve as a hub of innovation for Asia. It is supported by Japan’s expertise in food processing and high product quality. Regional markets such as South Korea and Southeast Asia offer strong demand potential. Strategic trade partnerships can amplify cross-border opportunities. Japan can position itself as a leader in premium plant-based exports.
Development of Functional and Nutrient-Enhanced Plant-Based Alternatives
Functional foods are emerging as a promising growth area. The Japan Meat Substitute Market can capture new demand by offering fortified substitutes. It is aligned with consumer interest in foods that provide added health benefits. Products enriched with vitamins, minerals, and probiotics attract health-focused demographics. Companies can differentiate themselves by marketing substitutes as wellness-enhancing products. This opportunity supports brand growth and long-term consumer loyalty.
Market Segmentation Analysis:
By Type
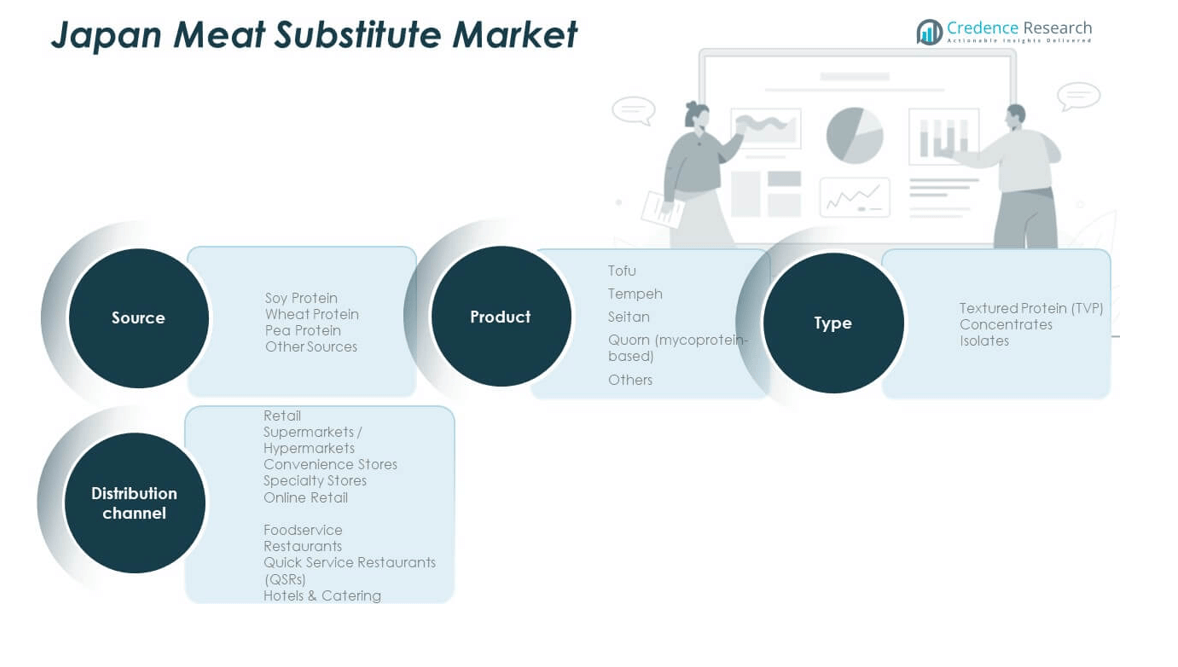
The Japan Meat Substitute Market is segmented into textured protein (TVP), concentrates, and isolates. TVP leads the type category due to its wide application in processed foods and its affordability. Concentrates offer a balance between cost and functionality, gaining traction in mainstream diets. Isolates, though premium, are valued for high protein purity and are increasingly used in functional and fortified foods. Each type addresses specific consumer needs ranging from everyday meals to specialized nutrition.
- For instance, NH Foods Ltd. sells TVP-based meat alternatives for burger and sausage applications, which are part of its broader plant-based product offerings. Similarly, Marudai Food Co. is known to supply various formulations to the food industry.
By Source
Sources include soy protein, wheat protein, pea protein, and other plant-based ingredients. Soy protein dominates the Japan Meat Substitute Market given its cultural acceptance and versatility in Japanese cuisine. Wheat protein maintains demand through its texture that resembles traditional meat dishes. Pea protein is expanding rapidly, supported by its allergen-free profile and sustainable sourcing. Other sources are emerging in niche products and innovation-driven launches.
- For instance, Amano Enzyme, a leading Japanese enzyme manufacturer, filed 12 patents for innovations in wheat and pea protein processing in April 2024, resulting in improved digestibility and texture for finished meat substitute products.
By Product
Product segmentation includes tofu, tempeh, seitan, Quorn, and others. Tofu retains strong dominance due to its deep-rooted presence in Japanese diets. Tempeh is gaining appeal among younger consumers seeking fermented, protein-rich alternatives. Seitan is valued for its texture and adaptability in recipes. Quorn and other innovative products are entering through premium and health-focused retail channels. This mix of traditional and modern options strengthens market depth.
By Distribution Channel
Distribution spans retail and foodservice outlets. Retail dominates, with supermarkets and hypermarkets offering wide visibility and variety. Convenience stores extend reach to daily shoppers across urban centers. Specialty stores attract premium buyers, while online retail grows with younger consumers seeking convenience. Foodservice adoption is expanding, with restaurants, QSRs, and hotels introducing plant-based menu innovations.
Segmentation:
- By Type
- Textured Protein (TVP)
- Concentrates
- Isolates
- By Source
- Soy Protein
- Wheat Protein
- Pea Protein
- Other Sources
- By Product
- Tofu
- Tempeh
- Seitan
- Quorn (mycoprotein-based)
- Others
- By Distribution Channel
- Retail
- Supermarkets / Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Foodservice
- Restaurants
- Quick Service Restaurants (QSRs)
- Hotels & Catering
Regional Analysis:
Kanto Region Leading With Strong Consumer Base
The Kanto region dominates the Japan Meat Substitute Market, accounting for about 38% share. Tokyo’s dense urban population and advanced retail infrastructure make it the core hub for adoption. Consumers in this region are highly health-conscious, driving demand for substitutes across retail and foodservice. Product launches often begin here due to high acceptance and influence on nationwide trends. Strong e-commerce penetration further strengthens accessibility and awareness. It is the most influential region for shaping overall industry growth.
Kansai Region Growing as a Secondary Demand Center
The Kansai region holds close to 26% share, led by Osaka, Kyoto, and Kobe. Rising disposable incomes and evolving dietary habits are supporting adoption of substitutes. The Japan Meat Substitute Market benefits from Kansai’s vibrant food culture that blends modern and traditional influences. Retail and restaurant networks are actively promoting plant-based menus in Osaka. Young professionals and students are contributing to a steady rise in product demand. It is quickly emerging as a secondary hub complementing Kanto’s dominance.
Chubu, Kyushu, and Hokkaido Showing Expanding Potential
The Chubu region, centered around Nagoya, contributes around 18% share, with steady adoption supported by retail growth. Kyushu and Hokkaido together represent another 18% share, showing increasing awareness through targeted marketing and distribution expansion. The Japan Meat Substitute Market in these regions is driven by consumer education and availability in local supermarkets. While adoption is slower compared to Kanto and Kansai, opportunities remain strong in urban centers. Rising focus on sustainability and health in smaller cities is gradually broadening acceptance. It is positioning these regions for faster growth over the forecast period.
Key Player Analysis:
- Unicharm Corporation
- Otsuka Foods (Soy Meat)
- NH Foods Ltd.
- Marukome Co., Ltd.
- Fuji Oil Holdings Inc.
- Kikkoman Corporation
- Ajinomoto Co., Inc.
- Nippon Ham (NH Foods Group – plant-based division)
- AEON Co., Ltd. (private label plant-based foods)
- Next Meats Co.
Competitive Analysis:
The Japan Meat Substitute Market is characterized by strong competition among domestic companies and global players entering the region. Leading firms such as Otsuka Foods, NH Foods Ltd., Fuji Oil Holdings Inc., and Next Meats Co. are expanding portfolios with innovative product lines. It is shaped by strategies that focus on cultural adaptation, taste authenticity, and nutritional benefits. Partnerships between local producers and global innovators are strengthening product diversity. Private label expansion by AEON Co., Ltd. enhances competitive intensity in retail channels. Continuous product innovation, branding, and distribution expansion are the primary tools companies use to secure market presence. The Japan Meat Substitute Market is evolving into a dynamic ecosystem driven by rapid innovation and consumer demand.
Recent Developments:
- In August 2025, Ajinomoto Co., Inc. formed a strategic partnership with Australian plant-based meat leader v2food and participated in the acquisition of Daring Foods, a US-based plant protein brand. This partnership aims to co-create next-generation plant-based products and accelerate the global scale of sustainable protein solutions, reflecting Ajinomoto’s leadership in food innovation and sustainability.
- In August 2025, Otsuka Foods announced the relaunch of its flagship “Sugoi Daizu” product line with refreshed packaging and introduced a new “Unprocessed Type 200ml” soy-based beverage to be available nationwide starting September 1, 2025. This relaunch reflects Otsuka’s commitment to innovating Japan’s soy meat and beverage category for broader consumer accessibility.
- In March 2025, Fuji Oil Holdings Inc. advanced its global expansion plans by leveraging their proprietary MIRACORE™ technology to produce new plant-based food ingredients for various international markets, including collaborations with renowned Japanese restaurants such as Ippudo for plant-based ramen broth. This highlights Fuji Oil’s position at the forefront of plant-based food technology in Japan.
Report Coverage:
The research report offers an in-depth analysis based on type, source, product, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise with increased adoption of flexitarian and plant-forward diets in Japan.
- Foodservice integration will accelerate acceptance through restaurants and quick-service chains.
- Retail expansion will strengthen visibility in supermarkets, convenience stores, and online platforms.
- Innovation in taste and texture will remain critical to improve consumer loyalty.
- Premium plant-based substitutes will capture high-income urban consumers seeking gourmet products.
- Soy protein will maintain dominance, but pea protein will gain ground with allergen-free positioning.
- Traditional products like tofu and tempeh will coexist with modern offerings such as Quorn.
- Collaborations between startups, research institutions, and global firms will fuel product innovation.
- Regional growth beyond Kanto and Kansai will expand market penetration in Chubu, Kyushu, and Hokkaido.
- Sustainability initiatives will strengthen consumer trust and shape long-term competitive advantage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Health Awareness and Shift Toward Nutritious Food Choices
Japanese consumers are increasingly reducing red meat intake due to concerns about obesity and cardiovascular diseases, driving demand for plant-based meat substitutes that offer high protein and lower fat. Younger, urban populations are especially adopting flexitarian diets, fueling market growth.
Environmental Concerns and Emphasis on Sustainability in Food Production
Rising awareness of the environmental impact of livestock farming is prompting consumers to choose meat substitutes with lower carbon footprints and reduced water usage. Government and industry campaigns promoting sustainable food production further accelerate adoption.
Advancements in Food Technology and Product Innovation
Continuous improvements in taste, texture, and nutritional value - driven by collaborations between Japanese innovators and global companies - are making meat substitutes more appealing and acceptable for daily consumption. This technological progress reduces consumer resistance and expands the market.
Expansion of Retail Channels and Online Distribution
The increasing availability of meat substitutes in supermarkets, convenience stores, and online platforms is making these products more accessible to a wider demographic. Enhanced visibility and convenience are normalizing substitute consumption across Japan.
Premiumization and Localization of Products
The emergence of premium plant-based products targeting affluent urban consumers, along with the integration of local ingredients and flavors, is attracting new customer segments. This trend supports higher margins and strengthens consumer loyalty by aligning with Japanese culinary preferences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Meat Substitute Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Meat Substitute Market projected to grow between 2024 and 2032?
Which Japan Meat Substitute Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Japan Meat Substitute Market?
Who are the leading companies in the Japan Meat Substitute Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Textured Protein (TVP)
- 1.2.2 Concentrates
- 1.2.3 Isolates
- 1.3 By Source
- 1.3.1 Soy Protein
- 1.3.2 Wheat Protein
- 1.3.3 Pea Protein
- 1.3.4 Other Sources
- 1.4 By Product
- 1.4.1 Tofu
- 1.4.2 Tempeh
- 1.4.3 Seitan
- 1.4.4 Quorn (mycoprotein-based)
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,046.32 million → 2032: USD 16,751.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Meat Substitute Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Meat Substitute Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Meat Substitute Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Meat Substitute Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Meat Substitute Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Meat Substitute Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Meat Substitute Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Meat Substitute Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,046.32 million → 2032: USD 16,751.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Meat Substitute Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Textured Protein (TVP)
- 12.3.7.2 Concentrates
- 12.3.7.3 Isolates
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Soy Protein
- 12.4.7.2 Wheat Protein
- 12.4.7.3 Pea Protein
- 12.4.7.4 Other Sources
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tofu
- 12.5.7.2 Tempeh
- 12.5.7.3 Seitan
- 12.5.7.4 Quorn (mycoprotein-based)
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Meat Substitute Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Meat Substitute Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Meat Substitute Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Unicharm Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Otsuka Foods (Soy Meat)
- 17.4 NH Foods Ltd.
- 17.5 Marukome Co., Ltd.
- 17.6 Fuji Oil Holdings Inc.
- 17.7 Kikkoman Corporation
- 17.8 Ajinomoto Co., Inc.
- 17.9 Nippon Ham (NH Foods Group – plant-based division)
- 17.10 AEON Co., Ltd.
- 17.11 Next Meats Co.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

