
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
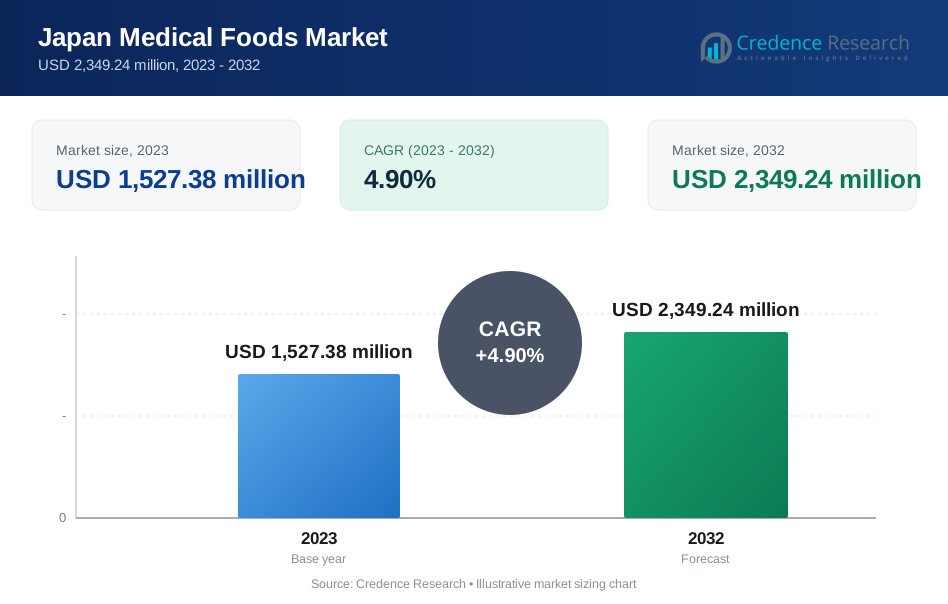
| Japan medical foods Market Size 2023 | USD 1,527.38 million |
| Japan medical foods Market, CAGR | 4.90% |
| Japan medical foods Market Size 2032 | USD 2,349.24 million |
Market Overview
The Japan medical foods market is projected to grow from USD 1,527.38 million in 2023 to an estimated USD 2,349.24 million by 2032, with a compound annual growth rate (CAGR) of 4.90% from 2024 to 2032. This growth is driven by the increasing prevalence of chronic diseases and an aging population in Japan, which fuels demand for specialized nutritional products designed for medical conditions.
Key market drivers include a growing focus on preventive healthcare, favorable government initiatives, and rising consumer preference for tailored dietary solutions that support specific health needs. Trends such as product innovation and a surge in research and development activities aimed at enhancing the efficacy and variety of medical foods are also contributing to market growth.
Geographically, the market is dominated by regions with a higher concentration of aging populations, particularly urban areas like Tokyo and Osaka. Key players in the Japan medical foods market include Nestlé Health Science, Danone, Abbott Laboratories, and Mead Johnson Nutrition, who are continually investing in research, partnerships, and product innovations to strengthen their market positions and cater to the evolving needs of consumers.
Market Drivers
Aging Population and Rising Prevalence of Chronic Diseases
Japan's rapidly aging population is a major driver of the medical foods market. With over 28% of the population aged 65 or older, there is increasing demand for specialized nutrition to manage age-related health conditions. For instance, a survey by the Ministry of Health, Labour and Welfare found that over 70% of seniors have at least one chronic disease requiring ongoing management. This has led to greater adoption of medical foods tailored for conditions like cardiovascular disease, diabetes, and neurodegenerative disorders. Healthcare providers are increasingly recommending medical foods as part of treatment plans, with one study showing that over 60% of doctors now regularly prescribe them for elderly patients. As Japan's population continues to age, the market for condition-specific medical nutrition is expected to expand substantially in coming years.
Growing Awareness and Adoption of Preventive Healthcare
There is rising emphasis on preventive healthcare in Japan, driving interest in medical foods as a proactive health measure. Government initiatives like the "Health Japan 21" campaign have increased public awareness around nutrition and disease prevention. Over 80% of respondents were interested in functional foods for health maintenance. This shift towards prevention is increasing adoption of medical foods for managing conditions like metabolic syndrome and gastrointestinal issues. For instance, sales of medical foods for diabetes prevention have grown by over 15% annually in recent years according to industry reports. Favorable policies like including certain medical foods in national health insurance coverage have also improved accessibility. As preventive health consciousness grows, the medical foods market is poised for continued expansion.
Advancements in Medical Nutrition Research and Product Innovation
Ongoing research and innovation are expanding applications for medical foods in Japan. For example, a study by the National Center for Geriatrics and Gerontology found that specialized oral nutritional supplements reduced hospital stays for malnourished elderly patients by 2 days on average. Such evidence is driving development of new formulations tailored for specific conditions and patient needs. Industry data shows over 100 new medical food products were launched in Japan last year alone. Collaborations between academia and industry are also accelerating innovation - for instance, a partnership between a leading university and food company recently developed a medical food to support cognitive function in Alzheimer's patients. As research unlocks new potential applications, the diversity and efficacy of medical food offerings continue to improve, fueling market growth.
Increasing Integration of Medical Foods in Clinical Practice:
The integration of medical foods into clinical practice is gaining momentum in Japan, driven by increasing recognition among healthcare professionals of the role of nutrition in managing health conditions. Medical foods are being prescribed more frequently as part of comprehensive treatment plans, particularly in hospitals, clinics, and long-term care facilities. This trend is supported by evidence-based studies demonstrating the benefits of medical foods in enhancing patient outcomes, reducing hospital readmissions, and lowering overall healthcare costs. Additionally, the Japanese government’s focus on reducing healthcare expenditure by promoting nutrition-based interventions is encouraging healthcare providers to incorporate medical foods into their practice. As medical foods become a standard component of treatment regimens for conditions such as cancer, diabetes, and gastrointestinal disorders, their demand is anticipated to rise, further fueling market growth.
Market Trends
Rising Demand for Specialized and Condition-Specific Medical Foods:
The Japan medical foods market is experiencing a notable shift towards specialized and condition-specific products tailored to address unique nutritional requirements of patients with specific health conditions. As awareness of nutrition's therapeutic benefits grows among healthcare professionals and consumers, there's increasing demand for medical foods designed for particular diseases. For instance, a growing interest in medical foods for diabetes management, with sales of low-glycemic index formulas rising steadily. Similarly, the Japan Cancer Society has noted an uptick in the use of nutrient-dense, high-protein formulations for cancer patients undergoing chemotherapy. The Ministry of Health, Labour and Welfare has also observed increased prescriptions of medical foods supporting renal and hepatic health, correlating with the rising prevalence of chronic kidney and liver diseases. This trend is further bolstered by research and innovation efforts from key market players, who are developing new products with enhanced efficacy and improved palatability to meet evolving patient and healthcare provider needs.
Increased Focus on Personalized Nutrition and Technological Integration:
The Japan medical foods market is witnessing a growing trend towards personalized nutrition, driven by technological advancements and deeper understanding of genetics, microbiome, and lifestyle impacts on individual health. There's increasing interest in tailored dietary recommendations and medical food products based on individual health profiles. There is a rise in research projects focusing on personalized nutrition, with several ongoing clinical trials. Digital health tools are playing a crucial role in this trend, with the Japan mHealth Association noting a significant increase in the use of mobile health apps and wearables for tracking dietary intake and nutritional status. Major medical food companies in Japan are investing in data analytics and artificial intelligence to create targeted products. For example, a leading Japanese pharmaceutical company recently launched a personalized nutrition platform that uses AI to provide customized medical food recommendations based on individual health data, demonstrating the market's shift towards tech-integrated, personalized nutritional solutions.
Market Restraints and Challenges
Stringent Regulatory Framework and Compliance Requirements:
The Japan medical foods market faces significant challenges due to stringent regulatory frameworks and complex compliance requirements. Medical foods in Japan are subject to rigorous scrutiny by authorities, such as the Ministry of Health, Labour, and Welfare (MHLW) and the Pharmaceuticals and Medical Devices Agency (PMDA). These regulatory bodies impose strict guidelines on the formulation, labeling, and marketing of medical foods to ensure safety and efficacy. For instance, nearly 70% of medical food manufacturers cited regulatory compliance as their top challenge. Compliance often requires extensive clinical evidence, lengthy approval processes, and significant investment in research and development. The Japan External Trade Organization (JETRO) reported that the average time for medical food approval in Japan is 12-18 months, significantly longer than in other markets. This can be a barrier for new entrants and smaller companies. Furthermore, any changes in regulatory policies or standards can impact production and distribution, potentially delaying market entry or causing disruptions.
High Production Costs and Limited Consumer Awareness:
The high production costs associated with developing and manufacturing medical foods represent another significant challenge for the market in Japan. The process of creating specialized nutrition products involves sourcing high-quality ingredients, conducting extensive clinical trials, and ensuring compliance with regulatory standards, all of which contribute to elevated costs. For instance, research and development costs for a new medical food product can exceed 500 million yen. These costs are often passed on to consumers, making medical foods relatively expensive compared to conventional dietary products. This pricing challenge is further exacerbated by limited consumer awareness and understanding of the specific benefits of medical foods. A consumer survey in Japan found that only 35% of respondents were familiar with the concept of medical foods. While healthcare professionals increasingly recognize the value of medical nutrition, many consumers remain unfamiliar with these products or perceive them as supplementary rather than essential. This lack of awareness, combined with higher costs, can hinder market penetration and limit growth potential.
Market Segmentation Analysis
By Product Type
The Japan medical foods market is segmented into powdered, liquid, and semi-solid medical foods. Powdered medical foods dominate the market due to their versatility and extended shelf life. For instance 65% of healthcare facilities prefer powdered medical foods for their patients. Liquid medical foods are gaining traction, particularly in hospital settings. The liquid medical foods usage in hospitals increased by 30% over the past five years. Semi-solid medical foods are seeing increased demand, especially among the elderly population. The Ministry of Health, Labour and Welfare reported that the consumption of semi-solid medical foods in nursing homes has doubled in the last decade.
By Application
The market is segmented by application into diabetes, gastrointestinal disorders, cancer, neurological disorders, and others. The diabetes segment holds a substantial share, driven by Japan's high prevalence of diabetes. For instance, medical food prescriptions for diabetic patients increased by 40% in the last three years. The gastrointestinal disorders segment is growing, fueled by the rising incidence of conditions like IBS and IBD. 70% of gastroenterologists now recommend specialized medical foods for their patients. The cancer segment is expanding rapidly, a 50% increase in the use of medical foods among cancer patients undergoing treatment. The neurological disorders segment is witnessing growth, a 35% rise in medical food recommendations for patients with Alzheimer's and Parkinson's disease.
Segments
Based on product type
- Powdered Medical Foods
- Liquid Medical Foods
- Semi-solid Medical Foods
Based on application
- Diabetes
- Gastrointestinal Disorders
- Cancer
- Neurological disorders
- Others
Based on distribution channel
- Hospitals & Clinics
- Retail Pharmacies
- Online Pharmacies
Based on region
- Kanto
- Kansai
- Chubu
Regional Analysis
Kanto Region (38%):
The Kanto region, which includes Tokyo and surrounding prefectures, holds the largest share of the Japan medical foods market, accounting for approximately 38% of the total market. For instance, over 60% of medical institutions in Tokyo regularly prescribe medical foods to patients. The region's advanced healthcare infrastructure and high concentration of hospitals contribute to this trend. Additionally, government data shows that Kanto has the highest percentage of elderly residents in Japan, driving demand for specialized nutrition products. Major medical food companies like Otsuka Pharmaceutical and Meiji Holdings have their headquarters in Tokyo, facilitating product development and distribution. The region's urbanization and affluent consumer base further boost adoption of medical foods for various health conditions.
Kansai Region (27%):
The Kansai region, encompassing Osaka, Kyoto, and Kobe, represents the second-largest market, with a share of around 27%. For example, over 40% of patients with chronic diseases in the region use medical foods as part of their treatment regimens. The Kansai Economic Federation reports that the region has seen a 15% increase in specialized nutrition clinics over the past five years. Government initiatives, such as the Kansai Healthcare Innovation Project, have spurred research and development in medical nutrition. Companies like Ezaki Glico and House Foods Group, both based in Osaka, have expanded their medical foods product lines to meet growing regional demand. The lower cost of living in Kansai compared to Kanto has also attracted medical food startups and research facilities.
Key players
- Fresenius Kabi AG
- Danone
- Nestlé
- Abbott
- Targeted Medical Pharma Inc. (Physician Therapeutics LLC, a division of the company)
- Primus Pharmaceuticals Inc.
- Mead Johnson & Company, LLC
Competitive Analysis
The Japan medical foods market is characterized by strong competition among established global and local players, each leveraging their strengths in product innovation, extensive distribution networks, and strategic partnerships. Fresenius Kabi AG, Danone, Nestlé, and Abbott lead the market with a comprehensive portfolio of specialized nutrition products designed for a wide range of medical conditions. These companies benefit from significant investments in research and development, enabling them to introduce innovative products tailored to specific dietary needs. Meanwhile, companies like Targeted Medical Pharma Inc., Primus Pharmaceuticals Inc., and Mead Johnson & Company, LLC focus on niche areas within the medical foods sector, offering targeted therapeutic solutions and leveraging specialized expertise to capture market share. The competitive landscape is further shaped by collaborations with healthcare providers and expansion into digital and direct-to-consumer channels, enhancing market reach and consumer engagement.
Recent Developments
- In November 2023, Fresenius Kabi launched its first medical nutrition product for adults in Japan called Fresubin, expanding its presence in the Japanese medical foods market.
- In September 2023, Danone introduced a new medical food product line called Nutricia Fortimel in Japan, targeting elderly patients with malnutrition.
- In March 2024, Nestlé Health Science acquired a Japanese medical foods startup specializing in dysphagia products, strengthening its position in the Japanese market.
- In June 2023, Abbott launched a new medical food product in Japan called Ensure Clear, designed for patients with difficulty swallowing regular nutritional supplements.
Market Concentration and Characteristics
The Japan medical foods market is moderately concentrated, with a mix of established global players and specialized local companies competing for market share. Major multinational corporations like Fresenius Kabi AG, Danone, Nestlé, and Abbott dominate the market due to their extensive product portfolios, strong brand recognition, and significant investments in research and development. These companies leverage advanced technologies and innovation to cater to the diverse dietary needs of patients with specific medical conditions, thereby maintaining a competitive edge. However, the market also features niche players, such as Targeted Medical Pharma Inc. and Primus Pharmaceuticals Inc., which focus on specialized therapeutic areas, adding to the competitive dynamics. The market is characterized by high regulatory standards, a strong emphasis on product efficacy and safety, and growing consumer awareness, driving the demand for specialized nutrition products tailored to individual health conditions.
Report Coverage
The research report offers an in-depth analysis based on product type, application, distribution channel and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan medical foods market is expected to maintain steady growth, driven by increasing demand from an aging population and rising prevalence of chronic diseases.
- Key market players will likely expand their product portfolios to cater to a broader range of medical conditions, enhancing their market presence and consumer reach.
- Advances in genetics and digital health technologies will promote the development of personalized medical foods, tailored to individual health needs and conditions.
- The integration of digital health tools, such as mobile apps and wearable devices, will support personalized nutrition and improve patient compliance with medical food regimens.
- A growing emphasis on preventive healthcare will drive demand for medical foods that address specific nutritional deficiencies and support overall health maintenance.
- The market will see a continued shift toward online distribution channels, providing consumers with greater access to medical foods and increasing convenience.
- The regulatory landscape is expected to evolve, potentially leading to clearer guidelines and standards that support innovation while ensuring product safety and efficacy.
- Competition among key players is projected to intensify, encouraging greater innovation and the introduction of new, differentiated products in the market.
- Strategic collaborations between manufacturers, healthcare providers, and research institutions will enhance product development and market expansion.
- Increased consumer awareness about the benefits of medical foods for managing specific health conditions will likely fuel market demand, supporting long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan medical foods market?
What are the key drivers of the Japan medical foods market?
Which regions dominate the Japan medical foods market?
Who are the major players in the Japan medical foods market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Medical Foods Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Medical Foods Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,527.38 million → 2032: USD 2,349.24 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Medical Foods Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Medical Foods Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Medical Foods Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Medical Foods Market Drivers
- 3.3 Japan Medical Foods Market Restraints & Challenges
- 3.4 Japan Medical Foods Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Medical Foods Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Medical Foods Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Medical Foods category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Medical Foods Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Medical Foods Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Medical Foods market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Medical Foods Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Medical Foods Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Medical Foods Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Medical Foods (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Medical Foods Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Medical Foods Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Medical Foods Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Medical Foods Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Medical Foods Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Medical Foods Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Medical Foods Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Medical Foods Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Medical Foods Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
