
Kids Eyewear Market Overview:
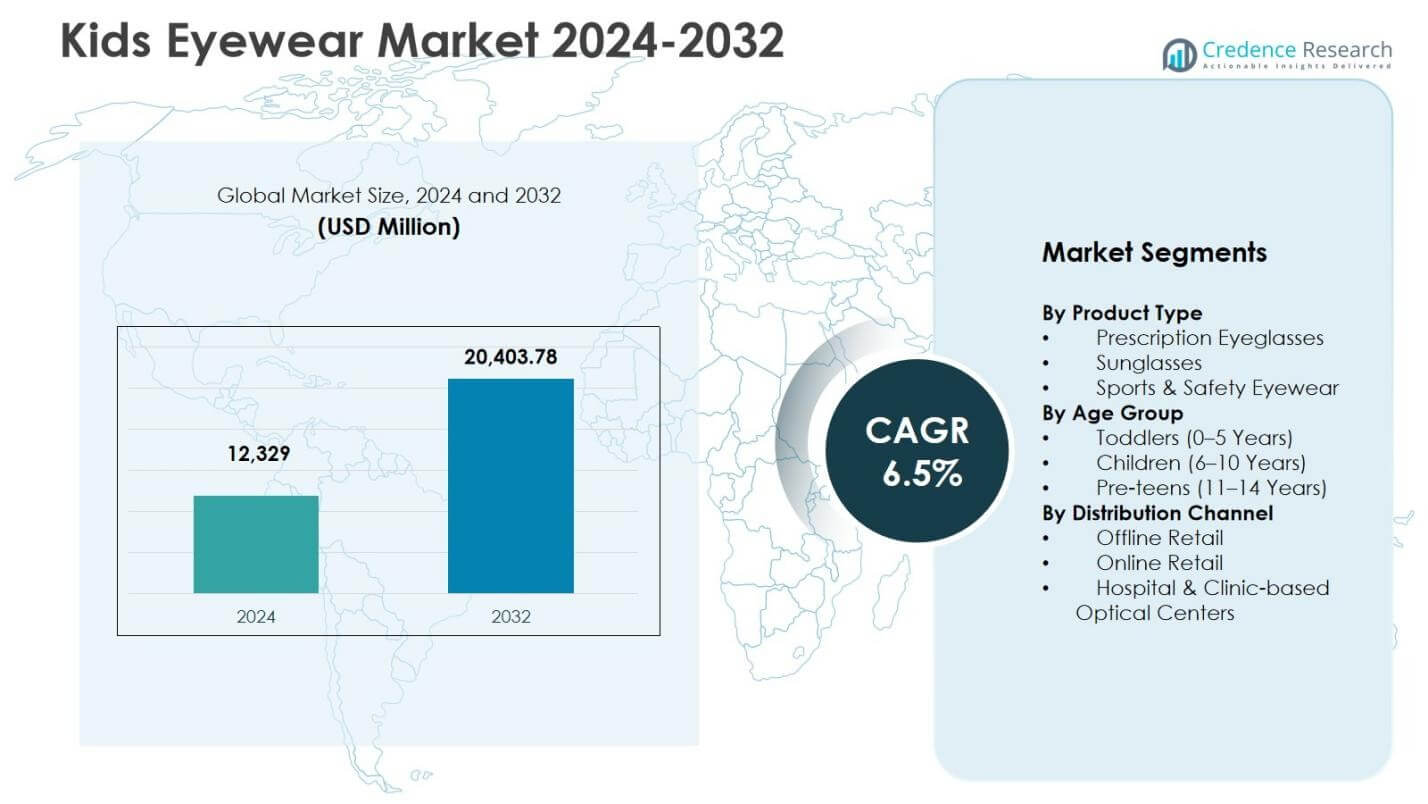
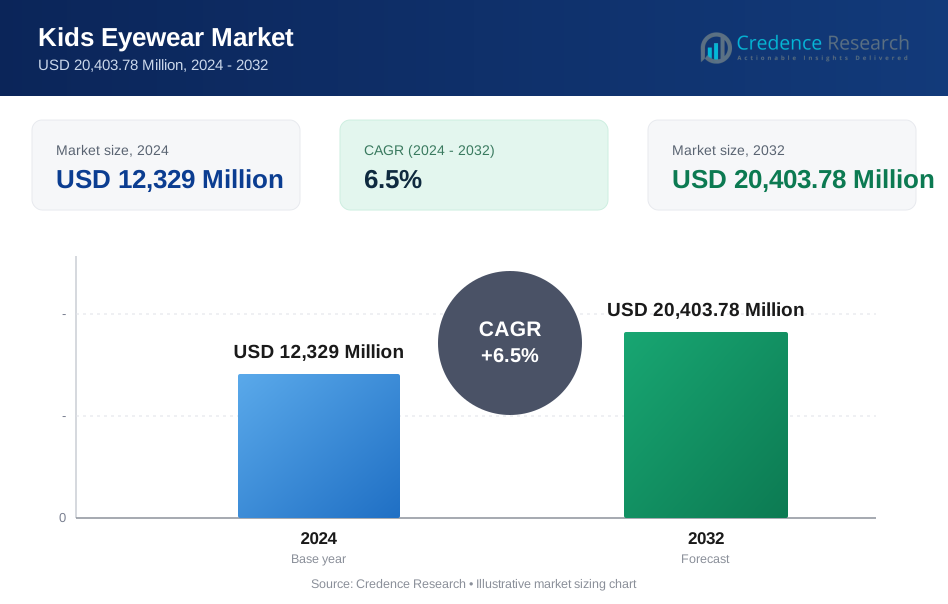
Kids Eyewear Market size was valued USD 12,329 Million in 2024 and is anticipated to reach USD 20,403.78 Million by 2032, at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Kids Eyewear Market Size 2024 | USD 12,329 million |
| Kids Eyewear Market , CAGR | 6.5% |
| Kids Eyewear Market Size 2032 | USD 20,403.78 million |
Market Insights
- Market overview highlights rising demand for prescription eyewear among school-age children due to increasing screen exposure and higher diagnosis of refractive errors, with Prescription Eyeglasses accounting for 54.2% share in 2024.
- Market driver includes growth in parental awareness of pediatric eye health, expanding school vision screening programs, and product innovations such as lightweight frames, blue-light protection lenses, and durable child-safe designs.
- Competetitive analysis shows key players focusing on flexible materials, lifestyle-oriented eyewear, and broader age-group coverage, while brands strengthen presence through omni-channel retail strategies and value-added pediatric lens technologies.
- Regional analysis indicates North America leading the Kids Eyewear Market with 32.6% share in 2024, followed by Asia-Pacific with 28.9% share and Europe with 26.4% share, while Latin America and Middle East & Africa contribute emerging growth opportunities through improving access to optical care.
Kids Eyewear Market Segmentation Analysis:
By Product Type
The Kids Eyewear Market by product type is led by Prescription Eyeglasses, which accounted for 54.2% share in 2024, driven by the rising prevalence of myopia among school-age children, increasing screen exposure, and growing parental focus on early vision correction. The segment benefits from advancements in lightweight, flexible frames and blue-light protection lenses designed specifically for pediatric comfort and safety. Sunglasses hold a significant share due to growing awareness of UV protection, while Sports & Safety Eyewear gains traction as participation in outdoor and athletic activities increases among young users.
- For instance, EssilorLuxottica introduced the Stellest™ lenses, clinically proven to slow myopia progression in children by up to 67%, addressing the rising demand for early intervention solutions.
By Age Group
In the Kids Eyewear Market by age group, the Children (6–10 Years) category dominated the market with 47.6% share in 2024, supported by higher diagnosis rates of refractive errors during primary schooling and increased adoption of prescription eyewear for classroom and digital learning use. Demand is further fueled by increasing optometric screening programs and the availability of durable, kid-friendly frame designs. The Pre-teens (11–14 Years) segment shows growing uptake due to lifestyle eyewear and fashion-driven preferences, while Toddlers (0–5 Years) primarily reflect medical-need-based usage.
- For instance, Warby Parker introduced its Kids Collection with polycarbonate lenses and bendable acetate frames designed to endure rough wear common in this age group.
By Distribution Channel
The Kids Eyewear Market by distribution channel is dominated by Offline Retail, which captured 62.8% share in 2024, as parents prefer in-store eye testing, professional fitting support, and personalized product consultation for children. Optical stores and specialty eyewear outlets remain the primary purchase points due to trust, trial convenience, and after-sales services. Online Retail is expanding rapidly, driven by e-commerce penetration, virtual try-on tools, and cost-effective pricing, while Hospital & Clinic-based Optical Centers maintain steady demand linked to prescription-driven purchases and clinical eye-care guidance.
Key Growth Drivers
Rising Incidence of Vision Disorders Among Children
The Kids Eyewear Market grows significantly due to the increasing prevalence of myopia, hyperopia, and astigmatism in school-age children. Greater exposure to digital screens, prolonged indoor activities, and academic pressure drive higher rates of vision impairment, resulting in stronger demand for prescription eyewear. Governments and healthcare programs are expanding school-based eye screening initiatives, which improve early diagnosis and boost eyewear adoption. Parents are becoming more aware of the long-term importance of pediatric eye health, supporting regular eye examinations and corrective lens use. In addition, manufacturers are introducing pediatric-friendly frames and lenses that enhance comfort, safety, and durability, further accelerating market expansion across both developed and emerging regions.
- For instance, Essilor's Stellest lenses for children aged 6-12 slow myopia progression by 71% over two years compared to single-vision lenses, via peripheral lenslets that reduce eye elongation by 53%.
Increasing Consumer Preference for Fashion-Oriented and Lifestyle Eyewear
The Kids Eyewear Market experiences strong growth as eyewear increasingly evolves from a purely corrective solution to a lifestyle and fashion accessory. Children and pre-teens actively prefer trendy, colorful, and personalized frames inspired by animation characters, sports themes, and youth fashion trends. Brands respond by launching lightweight, stylish, and customizable frames that appeal to both children and parents. Premium material innovation, flexible frame technology, and ergonomic designs enhance product adoption and replacement cycles. The rising influence of social media, children’s fashion marketing, and retail brand positioning strengthens consumer buying behavior. Growing disposable incomes among urban families further supports spending on aesthetically appealing and higher-value eyewear products.
Expansion of Organized Retail and Digital Commerce Channels
The expansion of organized optical retail networks and rapid growth of e-commerce significantly strengthen the Kids Eyewear Market. Modern optical chains, exclusive brand outlets, and specialty pediatric eyewear stores enhance accessibility and professional eye-care support for parents. Online platforms offer wide product visibility, virtual try-on features, home delivery, and competitive pricing, increasing purchase convenience. Omni-channel strategies enable seamless integration of digital browsing with in-store fittings and eye-testing services. Insurance coverage and healthcare financing options further support corrective eyewear adoption. Strategic collaborations between eyewear brands, optometrists, and clinics expand consumer outreach, while subscription-based eyewear plans and replacement programs promote recurring purchases among pediatric users.
- For instance, Lenskart accelerated its optical retail growth by adding 203 net new stores in H1 FY26, expanding from 399 to 431 cities across India, including Tier 2+ markets like Gurdaspur and Shivpuri.
Key Trends & Opportunities
Growing Adoption of Blue-Light Protection and Specialized Pediatric Lenses
A major opportunity in the Kids Eyewear Market emerges from rising demand for blue-light protection lenses, anti-fatigue lenses, and myopia-control eyewear designed specifically for children. Increased screen exposure from online learning, gaming, and digital entertainment raises concerns about digital eye strain, driving parents toward protective lens technologies. Manufacturers are investing in advanced coatings, UV-blocking technology, and clinically supported myopia-management lenses that ensure long-term visual comfort and eye-health safety. Partnerships between eyewear brands and eye-care professionals enhance awareness of preventive eye-care solutions. This trend opens pathways for premium, value-added pediatric eyewear segments and creates differentiation opportunities for brands focused on health-centric innovation and pediatric optical wellness.
- For instance, EssilorLuxottica launched its Stellest™ lenses, proven in a two-year clinical study to slow myopia progression in children by an average of 67% compared to single-vision lenses.
Rising Popularity of Eco-Friendly, Lightweight, and Flexible Frame Materials
Sustainability and material innovation present significant opportunities in the Kids Eyewear Market as brands increasingly introduce eco-friendly, hypoallergenic, and recyclable frame materials. Parents prefer lightweight, impact-resistant, and flexible frames that ensure durability and child safety during active use. Bio-based plastics, TR-90 polymer, silicone frames, and rubberized components enhance comfort and reduce breakage risks, improving product acceptance among younger age groups. Manufacturers emphasize environmental responsibility through sustainable sourcing, recyclable packaging, and ethical production practices, strengthening brand loyalty among environmentally aware consumers. This trend also supports product premiumization, enabling companies to position eco-friendly eyewear as both a functional and responsible purchase choice for modern households.
- For instance, Zoobug London, a child-specific eyewear brand, offers frames manufactured with BPA-free, medical-grade silicone to enhance comfort and resilience for daily wear.
Key Challenges
Price Sensitivity and Limited Affordability in Developing Markets
Price sensitivity remains a major challenge in the Kids Eyewear Market, particularly across developing economies where household income levels restrict spending on premium eyewear products. Many parents prioritize low-cost frames and lenses, limiting adoption of advanced optical technologies, specialty coatings, or branded pediatric eyewear. Out-of-pocket healthcare costs and limited insurance coverage for pediatric vision care further restrict corrective eyewear purchases. Informal and unorganized eyewear markets offer cheaper alternatives, creating strong price competition for organized brands. Manufacturers must balance affordability with durability, safety standards, and product quality, while also expanding budget-friendly product lines and financing solutions to improve accessibility among cost-conscious consumer groups.
Limited Awareness and Irregular Pediatric Eye-Care Compliance
Limited awareness of routine pediatric eye-examinations and delayed diagnosis of vision disorders create a significant barrier to Kids Eyewear Market growth. In many regions, parents seek vision testing only after visible symptoms appear, resulting in under-diagnosis among early-age children. Cultural perceptions, lack of screening programs, and inadequate access to optometric services in rural areas further weaken eyewear adoption levels. Irregular compliance with prescription eyewear use among children leads to replacement delays and inconsistent demand cycles. Strengthening educational programs, school-based screening initiatives, and parental awareness campaigns remains essential to improving early detection, treatment adherence, and sustained usage of corrective eyewear among pediatric populations.
Regional Analysis
North America
North America held a strong position in the Kids Eyewear Market and accounted for 32.6% share in 2024, supported by high awareness of pediatric vision care, widespread optometric screening programs, and strong adoption of prescription eyewear among school-age children. The region benefits from well-established optical retail chains, insurance coverage for eye-care services, and premium consumer spending on branded and fashion-oriented kids eyewear. Growing screen exposure, digital learning environments, and lifestyle eyewear preferences further stimulate demand. Product innovation in blue-light protection lenses and lightweight pediatric frames continues to drive replacement purchases and strengthens growth momentum across the United States and Canada.
Europe
Europe captured 26.4% share in 2024 in the Kids Eyewear Market, driven by strong emphasis on preventive eye-health programs, structured school vision screening initiatives, and rising prescription eyewear adoption among children across major economies such as Germany, France, Italy, and the United Kingdom. The region shows steady demand for premium pediatric eyewear supported by fashion-focused designs, eco-friendly frame materials, and durable safety eyewear for sports activities. Robust presence of specialized optical retailers and pediatric eyewear brands strengthens market penetration. Increasing digital device exposure and parental awareness of corrective lens benefits continue to enhance purchase frequency and overall revenue contribution across European markets.
Asia-Pacific
Asia-Pacific accounted for 28.9% share in 2024 and represents one of the fastest-growing regions in the Kids Eyewear Market due to rising prevalence of myopia among school-age children, rapid urbanization, and expanding access to organized optical retail networks. Growing middle-class income, heightened parental focus on early vision correction, and increasing adoption of affordable prescription eyewear solutions contribute to strong demand across China, India, Japan, and Southeast Asia. Government-led school screening programs and expanding e-commerce distribution further support market expansion. Manufacturers increasingly introduce budget-friendly, flexible, and durable pediatric frames tailored to regional affordability needs, strengthening eyewear adoption across urban and semi-urban households.
Latin America
Latin America secured 7.3% share in 2024 in the Kids Eyewear Market, supported by gradual improvements in eye-care awareness, expansion of optical retail distribution, and rising diagnosis of refractive errors among school-age children. Markets such as Brazil, Mexico, and Argentina show increasing demand for prescription eyewear, influenced by growing access to optometric services and urban lifestyle changes. However, price sensitivity and limited insurance coverage encourage preference for cost-effective frames and lenses. Manufacturers and retailers focus on durable, value-driven pediatric eyewear offerings, while government-supported screening initiatives and NGO-driven eye-health programs continue to improve adoption rates across low- and middle-income consumer segments.
Middle East & Africa
The Middle East & Africa region accounted for 4.8% share in 2024 in the Kids Eyewear Market, driven by increasing investments in healthcare infrastructure, expansion of optical retail outlets, and rising awareness of pediatric vision disorders in urban centers across the Gulf states and parts of Africa. Demand is mainly concentrated in prescription eyewear linked to clinical eye-care consultations, while lifestyle and fashion eyewear segments remain at a developing stage. Affordability constraints and limited rural access to optometric services continue to restrain broader penetration. Ongoing school vision programs, pediatric health awareness campaigns, and expanding private eye-care networks are gradually enhancing eyewear adoption across the region.
Kids Eyewear Market Segmentations:
By Product Type
- Prescription Eyeglasses
- Sunglasses
- Sports & Safety Eyewear
By Age Group
- Toddlers (0–5 Years)
- Children (6–10 Years)
- Pre-teens (11–14 Years)
By Distribution Channel
- Offline Retail
- Online Retail
- Hospital & Clinic-based Optical Centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Kids Eyewear Market features leading players such as Miraflex, Zenni Optical, Jonas Paul Eyewear, Nano Vista, Ray-Ban Junior, Oakley Youth, SwissFlex Kids, Babiators, Pitt & Mitt, and JCPenney Optical. These companies compete through product design innovation, durable pediatric frame materials, and expanded prescription eyewear offerings tailored to different age groups. The market reflects a balanced mix of specialized children-focused brands and global eyewear manufacturers with dedicated junior product lines. Companies emphasize lightweight, flexible, and hypoallergenic frames, along with blue-light protection and myopia-control lenses to address growing pediatric vision needs. Strategic initiatives include omni-channel retail expansion, collaborations with eye-care professionals, and launch of fashionable, customizable frame collections that appeal to both parents and children. Pricing differentiation and regional distribution partnerships also shape competitive positioning, while premium lifestyle eyewear and sustainable material innovation increasingly influence brand perception and market share dynamics across key global regions.
Key Player Analysis
- Miraflex
- Zenni Optical
- Jonas Paul Eyewear
- Nano Vista
- JCPenney Optical
- Ray-Ban Junior (EssilorLuxottica)
- Oakley Youth
- SwissFlex Kids
- Babiators
- Pitt & Mitt
Recent Developments
- In October 2025, Design Eyewear Group acquired six eyewear brands from KNCO, including children's brands Karavan Kids and Kaliboo, along with 15 KNCO employees to support development.
- In April 2025, Alternative Eyewear and East Optical launched the “IndiiPro Package,” combining Indi kids’ frames with MyoPro® myopia-management lenses for enhanced pediatric vision solutions.
- In 2025, Specsmakers launched “Jugnoo,” India’s first glow-in-the-dark kids eyewear collection, enhancing fun and visibility for children’s frames.
- In October 2024, Lenskart launched Hooper Creatr, a customizable kids' eyewear collection with adjustable temple tips, changeable nose pads, and Flexi hinges designed for comfort and myopia-control lenses.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Kids Eyewear Market will witness sustained growth as early vision screening and pediatric eye-health awareness continue to increase across global regions.
- Manufacturers will focus on lightweight, flexible, and child-safe frame designs to enhance comfort, durability, and long-term usage among young users.
- Demand for blue-light protection lenses, myopia-control solutions, and digital-eye-strain eyewear will rise with continued exposure to screens and online learning environments.
- Fashion-driven and personalized eyewear styles for children and pre-teens will gain traction, supporting premium and lifestyle-oriented product segments.
- Omni-channel retail expansion will strengthen market accessibility through integrated online platforms, optical chains, and clinic-based dispensing networks.
- Brands will increasingly adopt eco-friendly materials and sustainable manufacturing practices to appeal to environmentally conscious consumers.
- Emerging markets will experience faster adoption as organized optical retail and school vision screening programs expand.
- Strategic partnerships between eyewear brands, optometrists, and healthcare providers will enhance awareness and prescribing confidence.
- Technological innovation such as virtual try-on tools and AI-based fitting solutions will improve purchasing experience for parents and children.
- Competitive differentiation will intensify as companies invest in product customization, design aesthetics, and value-added lens technologies to strengthen brand loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Vision Disorders Among Children
Increasing prevalence of myopia, hyperopia, and astigmatism among school-age children, driven by greater screen exposure and academic pressures, is fueling demand for prescription eyewear. Early diagnosis through expanded school screening programs and heightened parental awareness are accelerating market growth.
Growth in Parental Awareness and Pediatric Eye Health Initiatives
Parents are increasingly prioritizing regular eye examinations and corrective eyewear for their children due to greater understanding of long-term eye health. Government and healthcare initiatives, such as school vision screening programs, are supporting early intervention and boosting eyewear adoption.
Product Innovation in Pediatric Eyewear
Manufacturers are introducing lightweight, flexible, and child-safe frames, as well as advanced lens technologies like blue-light protection and myopia-control solutions. These innovations enhance comfort, safety, and visual health, encouraging parents to invest in higher-quality eyewear for their children.
Expansion of Organized Retail and Digital Commerce
The growth of organized optical retail chains and rapid adoption of e-commerce platforms have improved accessibility and convenience for parents purchasing kids' eyewear. Omni-channel strategies, virtual try-on tools, and professional fitting services are making it easier for families to access and select appropriate eyewear.
Increasing Demand for Fashion-Oriented and Lifestyle Eyewear
Eyewear is evolving into a fashion and lifestyle accessory for children and pre-teens, with brands offering trendy, customizable, and colorful frames. The influence of youth fashion trends and social media is driving higher replacement rates and premium segment growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Kids Eyewear Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Kids Eyewear Market projected to grow between 2024 and 2032?
Which Kids Eyewear Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Kids Eyewear Market?
Who are the leading companies in the Kids Eyewear Market?
Which region commanded the largest share of the Kids Eyewear Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age Group
- 1.2.1 Toddlers (0–5 Years)
- 1.2.2 Children (6–10 Years)
- 1.2.3 Pre-teens (11–14 Years)
- 1.3 By Product Type
- 1.3.1 Prescription Eyeglasses
- 1.3.2 Sunglasses
- 1.3.3 Sports & Safety Eyewear
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,329 Million → 2032: USD 20,403.78 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Kids Eyewear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Kids Eyewear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Kids Eyewear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Kids Eyewear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Kids Eyewear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Kids Eyewear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Kids Eyewear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Kids Eyewear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,329 Million → 2032: USD 20,403.78 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Kids Eyewear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age Group - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Toddlers (0–5 Years)
- 12.3.7.2 Children (6–10 Years)
- 12.3.7.3 Pre-teens (11–14 Years)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Prescription Eyeglasses
- 12.4.7.2 Sunglasses
- 12.4.7.3 Sports & Safety Eyewear
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Kids Eyewear Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Kids Eyewear Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Kids Eyewear Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Miraflex
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Zenni Optical
- 17.4 Jonas Paul Eyewear
- 17.5 Nano Vista
- 17.6 Ray-Ban Junior (EssilorLuxottica)
- 17.7 Oakley Youth
- 17.8 SwissFlex Kids
- 17.9 Babiators
- 17.10 JCPenney Optical
- 17.11 Pitt & Mitt
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

