
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| KSA Digital Radiography Market Size 2023 | USD 4.43 Million |
| KSA Digital Radiography Market, CAGR | 1.85% |
| KSA Digital Radiography Market Size 2032 | USD 5.22 Million |
Market Overview
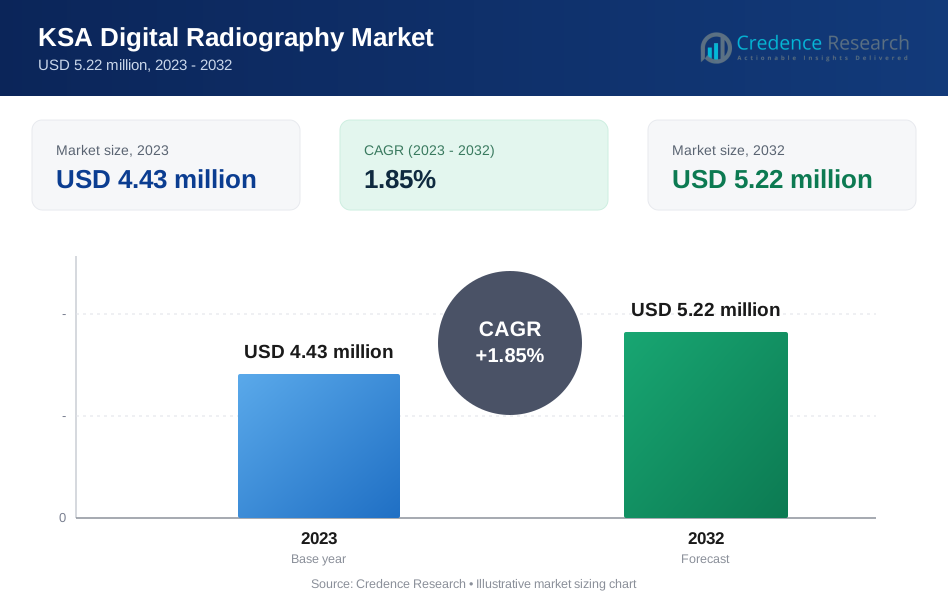
The KSA Digital Radiography Market is projected to grow from USD 4.43 million in 2023 to USD 5.22 million by 2032, with a compound annual growth rate (CAGR) of 1.85%.
The KSA Digital Radiography market is driven by increasing demand for advanced medical imaging solutions, fueled by the country’s growing healthcare infrastructure and the adoption of modern diagnostic technologies. The shift towards digital radiography offers numerous benefits, including enhanced image quality, reduced radiation exposure, and faster diagnostic capabilities, contributing to improved patient care. Additionally, the government's initiatives to modernize healthcare facilities and invest in cutting-edge medical equipment are further propelling market growth. The rising prevalence of chronic diseases and the need for early diagnosis also support the demand for efficient diagnostic tools. Trends in the market include the integration of artificial intelligence (AI) for automated image analysis and advancements in portable and compact digital radiography systems, making them more accessible in various healthcare settings. As healthcare professionals seek more efficient and accurate diagnostic methods, the KSA Digital Radiography market is expected to continue its steady expansion.
The digital radiography market in Saudi Arabia (KSA) is experiencing growth driven by advancements in healthcare infrastructure and the increasing demand for high-quality diagnostic imaging. Key players in the KSA digital radiography market include global and regional companies such as GE Healthcare, FUJIFILM, and Carestream Health, offering innovative solutions and high-performance systems. These companies, along with local players like Attieh Medico, are strategically positioned to cater to the rising healthcare needs across the country. Saudi Arabia’s emphasis on improving healthcare standards and expanding hospitals and diagnostic centers further boosts the demand for digital radiography solutions. Additionally, the government's initiatives to enhance healthcare facilities and the adoption of advanced technologies are playing a significant role in shaping the market dynamics. With a growing preference for more efficient and less invasive diagnostic tools, these key players are poised to capitalize on the expanding opportunities in KSA.
Market Insights
- The KSA digital radiography market is valued at USD 300 million in 2024, expected to grow at a CAGR of 8% from 2024 to 2032.
- Increasing healthcare expenditure and government initiatives to modernize healthcare infrastructure are driving market growth.
- There is a growing demand for advanced imaging technologies, particularly in hospitals and diagnostic centers.
- A shift towards portable and wireless digital radiography solutions is emerging as a key trend.
- The market is highly competitive, with key players like GE Healthcare, FUJIFILM, and Carestream Health leading the market.
- High cost of equipment and limited reimbursement policies pose challenges for market expansion.
- Regional growth is primarily concentrated in urban areas like Riyadh and Jeddah, where healthcare facilities are expanding rapidly.
Market Drivers
Advancements in Healthcare Infrastructure
Saudi Arabia’s commitment to expanding and modernizing its healthcare infrastructure is a key driver for the growth of the Digital Radiography market. The government’s Vision 2030 initiative emphasizes enhancing the quality of healthcare services across the country, with significant investments in state-of-the-art medical technologies. For instance, the Saudi government has allocated nearly SR180 billion (US$50.3 billion) for healthcare and social development in 2023, focusing on digital health initiatives. This focus on modernization is leading to the adoption of digital radiography systems in hospitals, clinics, and diagnostic centers, as they offer better imaging capabilities, faster results, and improved patient care.
Technological Advancements and AI Integration
Technological advancements, particularly the integration of artificial intelligence (AI) into digital radiography systems, are fueling market growth. AI-powered systems offer automated image analysis, which reduces the time required for radiologists to interpret results and improves diagnostic accuracy. For instance, the Saudi Data and Artificial Intelligence Authority (SDAIA) and King Abdullah University of Science and Technology (KAUST) have developed the MiniGPT-Med model, an AI system designed to enhance diagnostic accuracy and efficiency in radiology. Furthermore, advancements in portable and compact digital radiography equipment make it easier to implement these solutions in a variety of healthcare settings, including remote and underserved areas, thus broadening the market's scope.
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic diseases such as cancer, cardiovascular conditions, and musculoskeletal disorders in Saudi Arabia has driven the demand for more accurate and efficient diagnostic tools. Digital radiography provides faster and more detailed images compared to traditional methods, allowing for quicker diagnoses and improved patient outcomes. For instance, a report by the Saudi Public Health Authority highlights that cardiovascular diseases, diabetes, and cancer are among the leading causes of morbidity and mortality in the country. As healthcare providers strive to meet the needs of a growing patient base with complex conditions, the demand for digital radiography solutions continues to rise.
Government Initiatives and Healthcare Reforms
The Saudi government is actively investing in healthcare reforms aimed at improving medical care and expanding access to modern diagnostic technologies. Initiatives under Vision 2030, such as the development of new hospitals and upgrading existing facilities, are encouraging the adoption of digital radiography systems. These reforms aim to provide better healthcare services while reducing the burden on the country’s healthcare system, driving the need for more efficient diagnostic tools like digital radiography.
Market Trends
Growing Adoption in Diagnostic Imaging Centers
Diagnostic imaging centers are becoming key players in the growth of the digital radiography market in Saudi Arabia. These centers are increasingly adopting digital radiography systems due to their ability to offer superior image quality and faster processing times compared to traditional radiographic equipment. For instance, the Saudi Arabia Diagnostic Imaging Market report indicates that the adoption of digital imaging systems and Picture Archiving and Communication Systems (PACS) enables seamless storage, retrieval, and sharing of medical images, facilitating collaboration among healthcare professionals. The convenience of digital data storage and retrieval also allows for better patient management and more streamlined workflows. As diagnostic imaging centers expand across the country, the demand for digital radiography systems is expected to rise significantly.
Shift Towards Portable Digital Radiography Systems
A significant trend in the KSA Digital Radiography market is the increasing demand for portable radiography systems. With healthcare facilities striving to enhance accessibility and efficiency, portable digital radiography equipment is gaining popularity. These systems offer the flexibility to perform imaging procedures at the patient’s bedside or in remote locations, making them ideal for hospitals, outpatient clinics, and even field hospitals. The growing preference for these portable systems is a response to the need for more convenient and immediate diagnostic solutions, particularly in emergency care settings.
Integration of Artificial Intelligence (AI)
The integration of artificial intelligence (AI) into digital radiography systems is another key trend reshaping the market. AI technologies, such as machine learning and deep learning algorithms, are being utilized to enhance image quality, automate image analysis, and aid in the early detection of conditions such as cancer, fractures, and cardiovascular diseases. These innovations are improving diagnostic accuracy and reducing the time required for image interpretation. As healthcare providers seek more efficient workflows, the integration of AI is expected to become increasingly prominent in the KSA Digital Radiography market.
Focus on Enhanced Image Quality and Resolution
A continued trend in the KSA Digital Radiography market is the focus on improving image quality and resolution. Healthcare providers are prioritizing systems that offer high-definition imaging capabilities to ensure precise diagnostics. Enhanced image resolution helps radiologists detect subtle abnormalities that may be missed with lower-quality images, leading to more accurate diagnoses and treatment planning. As the need for superior image quality becomes more critical in patient care, manufacturers are developing digital radiography systems with increasingly advanced features to meet these expectations.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
One of the significant challenges facing the KSA Digital Radiography market is the high initial cost of digital radiography systems, which can deter smaller healthcare facilities and clinics from adopting these advanced technologies. The upfront investment in digital imaging equipment, along with the associated infrastructure and installation expenses, can be a barrier for institutions with limited budgets. For instance, a report by the Saudi Healthcare Technology Association highlights that the average cost of implementing digital radiography systems can be a significant financial burden for many institutions. Additionally, the cost of ongoing maintenance and upgrades for these systems can be considerable. As a result, many healthcare providers may struggle to justify the expense, particularly when budget constraints are a factor. This challenge may slow the widespread adoption of digital radiography in some regions of Saudi Arabia, despite its long-term benefits.
Need for Skilled Personnel and Training
Another challenge in the KSA Digital Radiography market is the need for skilled personnel to operate and interpret the advanced imaging systems. While digital radiography offers numerous advantages, its effectiveness depends on the expertise of radiologists and technicians who are trained to use the technology proficiently. The shortage of skilled professionals in the country, particularly in remote or rural areas, presents a hurdle to maximizing the potential of digital radiography. Furthermore, continuous training and professional development are required to keep pace with evolving technologies, adding to the overall cost and operational complexity for healthcare providers. Addressing this skill gap is essential for ensuring the successful implementation and use of digital radiography systems across Saudi Arabia.
Market Opportunities
Expansion of Healthcare Infrastructure
A major opportunity for the KSA Digital Radiography market lies in the ongoing expansion and modernization of the country’s healthcare infrastructure. As Saudi Arabia invests heavily in healthcare reforms under Vision 2030, there is a growing demand for advanced medical technologies, including digital radiography. The establishment of new hospitals, diagnostic centers, and healthcare facilities, along with the upgrading of existing ones, creates a significant opportunity for digital radiography manufacturers to expand their market presence. As the healthcare sector continues to evolve, particularly in underserved and rural areas, there is an increasing need for high-quality, accessible imaging solutions, positioning digital radiography systems as a key component of this transformation.
Technological Advancements and AI Integration
The integration of artificial intelligence (AI) in digital radiography presents another substantial opportunity for growth in the KSA market. AI-powered radiography systems can enhance diagnostic accuracy, automate image analysis, and expedite image interpretation, making them highly attractive to healthcare providers seeking efficiency improvements. With the increasing focus on precision medicine and early detection of diseases, AI-driven technologies have the potential to revolutionize diagnostic workflows and improve patient outcomes. As Saudi Arabia continues to embrace technological advancements, the demand for AI-enhanced digital radiography solutions is expected to rise, creating new avenues for innovation and market expansion. Furthermore, the growing acceptance of portable and mobile radiography systems offers additional opportunities, particularly in remote areas, further extending the reach of digital radiography.
Market Segmentation Analysis:
By Product:
The KSA Digital Radiography market is categorized into several product types, each catering to specific needs in healthcare facilities. The fixed digital radiography system holds a dominant position due to its ability to provide high-quality imaging in a variety of settings, including hospitals and clinics. Ceiling-mounted systems are gaining traction for their ability to save space while offering precise and stable imaging, making them ideal for high-volume diagnostic environments. Mobile systems are increasingly preferred for their flexibility, enabling imaging procedures to be performed at the patient’s bedside or in emergency situations. The floor-to-ceiling mounted systems are also gaining popularity, offering a balanced combination of space efficiency and advanced imaging features. Furthermore, portable digital radiography systems are experiencing growth due to their adaptability in remote locations and emergency care units. These diverse product options provide healthcare providers with the flexibility to choose solutions based on their specific operational requirements and patient needs.
By Application:
The KSA Digital Radiography market is also segmented based on applications, with key segments including chest imaging, orthopedic imaging, cardiovascular imaging, pediatric imaging, and others. Chest imaging remains the most significant application due to the high prevalence of respiratory diseases and the need for efficient diagnostic tools. Orthopedic imaging is another crucial application, driven by the increasing number of musculoskeletal disorders in the population. Cardiovascular imaging is expanding rapidly, as the rise in heart-related conditions calls for advanced diagnostic tools to facilitate early detection. Pediatric imaging, with its specialized requirements for handling young patients, is also gaining attention, as healthcare providers seek systems capable of delivering precise diagnostics while minimizing radiation exposure. These applications drive the demand for various digital radiography systems tailored to meet the specific diagnostic needs of different patient groups.
Segments:
Based on Product:
- Fixed Digital Radiography System
- Ceiling-Mounted System
- Mobile System
- Floor-To-Ceiling Mounted System
- Portable Digital Radiography Systems
Based on Application:
- Chest Imaging
- Orthopedic Imaging
- Cardiovascular Imaging
- Pediatric Imaging
- Application 5
Based on End-user:
- Hospitals
- Diagnostic Imaging Center
- Orthopedic Clinics
- Other End Users
- End-user 5
Based on Technology:
- Technology 1
- New Digital System
- Technology 3
- Technology 4
- Technology 5
Based on Distribution Channel:
- Distribution Channel 1
- Distribution Channel 2
- Distribution Channel 3
- Distribution Channel 4
- Distribution Channel 5
Based on the Geography:
- Central Region
- Eastern Region
- Western Region
- Southern Region
Regional Analysis
Central Region
The Central Region of Saudi Arabia holds the largest market share in the Digital Radiography market, accounting for approximately 35% of the total market. This dominance can be attributed to the presence of Riyadh, the capital city, which houses numerous state-of-the-art healthcare facilities, diagnostic centers, and hospitals. Riyadh is a hub for medical innovation and technological advancements, driving the demand for advanced diagnostic tools like digital radiography. The government's substantial investments in healthcare infrastructure and the high concentration of healthcare professionals in this region contribute to the rapid adoption of digital radiography systems. Additionally, the region's proximity to research institutions and the presence of international medical equipment suppliers further support the growth of the market. As the central hub for both healthcare services and technological development, this region is poised to maintain its leadership in the digital radiography market for the foreseeable future.
Eastern Region
The Eastern Region of Saudi Arabia is another key market, contributing around 27% to the overall market share of digital radiography. This region's growth can be attributed to its industrial base, including the oil and gas sector, which drives economic development and healthcare demands. Cities such as Dammam and Khobar have seen an increase in healthcare infrastructure development, especially with the region’s growing population and need for medical services. The healthcare sector in the Eastern Region is experiencing rapid modernization, with healthcare facilities upgrading their diagnostic equipment to meet global standards. The region's strategic location near the Gulf countries also facilitates the import of advanced medical technologies. As the region's healthcare system continues to evolve and expand, the adoption of digital radiography systems is expected to grow steadily, supported by both public and private investments in medical infrastructure.
Western Region
The Western Region, which includes key cities like Jeddah and Mecca, is witnessing a rise in the adoption of digital radiography, contributing approximately 21% to the market share. Jeddah, being a commercial and healthcare center, has seen increased investment in medical technologies, driven by both the local population and the influx of pilgrims during the Hajj season. Healthcare providers in the region are increasingly integrating digital radiography systems to enhance diagnostic accuracy and patient care. Moreover, the region's healthcare infrastructure is undergoing continuous expansion, with several new hospitals and diagnostic centers being established to meet the needs of a growing population. The trend toward modernizing healthcare facilities, coupled with the region’s strategic location for international medical suppliers, positions the Western Region for continued growth in the digital radiography market.
Southern Region
The Southern Region of Saudi Arabia, contributing about 17% to the digital radiography market, is an emerging market with considerable growth potential. This region, which includes cities such as Abha and Khamis Mushait, has historically lagged behind the other regions in terms of healthcare infrastructure development. However, recent efforts by the Saudi government to improve healthcare access and services in less urbanized areas are creating opportunities for digital radiography adoption. The Southern Region's healthcare system is gradually modernizing, with more hospitals and diagnostic centers upgrading their equipment to digital technologies. As the demand for high-quality medical imaging increases due to a rising population and the growing prevalence of chronic diseases, the Southern Region is expected to experience rapid growth in digital radiography adoption in the coming years.
Key Player Analysis
- Agfa Radiology Solutions
- Carestream Health
- GE Healthcare
- FUJIFILM
- Applus
- Hologic, Inc.
- Koninklijke Philips
- Esaote SpA
- Hitachi Ltd
- Attieh Medico
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The KSA digital radiography market is highly competitive, with several global and regional players driving innovation and expansion. Leading companies include GE Healthcare, FUJIFILM, Carestream Health, Koninklijke Philips, Hologic, Inc., Hitachi Ltd, Esaote SpA, and local players such as Attieh Medico. The market sees a blend of global and regional players offering a range of products, from traditional to wireless and portable systems, to meet the evolving needs of healthcare facilities in Saudi Arabia. Innovation is a significant factor, with companies focusing on enhancing image resolution, integrating with hospital management systems, and providing mobile solutions to address space constraints. Additionally, the demand for efficient, user-friendly systems that can reduce diagnostic times and improve patient outcomes is pushing the adoption of advanced radiography technologies. Companies are also focusing on providing comprehensive after-sales services, including installation, training, and maintenance, which play a crucial role in building long-term relationships with healthcare providers. The competitive landscape is further influenced by price sensitivity and the need for cost-effective solutions, especially in the public healthcare sector. For instance, the Saudi Healthcare Technology Association emphasizes the importance of cost-effective healthcare solutions to meet the needs of the public sector. As digital radiography technology becomes more widely accepted, competition intensifies, leading to continuous innovation and improvements in product offerings.
Recent Developments
- In July 2023, Canon Medical Systems introduced the Zexira i9 Digital X-ray RF System, featuring a versatile table with numerous new functions and a compact design. In May 2023, Carestream Health launched the DRX-Rise Mobile X-ray System, which is a new mobile X-ray system designed to enhance patient care and boost diagnostic confidence.
- In July 2023, Shimadzu introduced a new mobile X-ray system featuring serial radiography and static image display capabilities. This system integrates digital radiography, catering to international demand beyond Japan.
Market Concentration & Characteristics
The market concentration of digital radiography in Saudi Arabia (KSA) is moderately fragmented, with a mix of global and regional players vying for market share. The market is characterized by the presence of both well-established multinational companies and local players, each catering to the growing demand for advanced imaging technologies in the healthcare sector. While large multinational firms dominate the market, local companies are crucial in providing region-specific support, maintenance, and service, ensuring the accessibility of these technologies across the country. The KSA digital radiography market is defined by the increasing preference for high-resolution imaging systems that offer faster diagnostic capabilities and better patient outcomes. This has led to a strong focus on innovation, with companies investing heavily in research and development to enhance the functionality of radiography equipment. The market also exhibits a shift towards portable, wireless, and cost-effective digital radiography solutions, driven by the need for flexibility in both hospital and remote healthcare settings. Despite strong competition, the market remains characterized by high barriers to entry due to the significant capital investment required for research, development, and establishing a service network. Furthermore, regulatory approvals and compliance with Saudi healthcare standards add another layer of complexity to market entry. These factors ensure that the market remains concentrated around a few key players, although opportunities exist for local and emerging companies.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-user, Technology, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The KSA digital radiography market is expected to continue growing at a robust pace due to the increasing demand for advanced healthcare technologies.
- Government initiatives to modernize healthcare infrastructure will drive the adoption of digital radiography systems across the country.
- The shift towards portable and wireless imaging solutions will become more prominent, especially in remote healthcare settings.
- Technological advancements in image quality and diagnostic speed will enhance the efficiency of digital radiography systems.
- Rising healthcare expenditures and the expansion of healthcare facilities will contribute to a higher adoption rate of digital radiography equipment.
- The demand for integrated systems that can connect with hospital information systems will rise, improving workflow efficiency.
- The market will see increased competition as more players, both regional and international, enter the market to capture emerging opportunities.
- Price sensitivity in the public healthcare sector will continue to drive demand for cost-effective digital radiography solutions.
- There will be greater emphasis on after-sales services, including maintenance and training, to ensure the effective utilization of digital radiography systems.
- The overall market dynamics will be shaped by the government’s regulatory framework, which will continue to support the growth of advanced healthcare technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the KSA Digital Radiography market?
What factors are driving the growth of the KSA Digital Radiography market?
What are the key segments within the KSA Digital Radiography market?
What are some challenges faced by the KSA Digital Radiography market?
Who are the major players in the KSA Digital Radiography market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 KSA Digital Radiography Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global KSA Digital Radiography Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 4.43 million → 2032: USD 5.22 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 KSA Digital Radiography Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. KSA Digital Radiography Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 KSA Digital Radiography Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 KSA Digital Radiography Market Drivers
- 3.3 KSA Digital Radiography Market Restraints & Challenges
- 3.4 KSA Digital Radiography Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 KSA Digital Radiography Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 KSA Digital Radiography Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, KSA Digital Radiography category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 KSA Digital Radiography Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. KSA Digital Radiography Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the KSA Digital Radiography market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 KSA Digital Radiography Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 KSA Digital Radiography Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 KSA Digital Radiography Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in KSA Digital Radiography (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New KSA Digital Radiography Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global KSA Digital Radiography Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America KSA Digital Radiography Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe KSA Digital Radiography Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific KSA Digital Radiography Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America KSA Digital Radiography Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East KSA Digital Radiography Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa KSA Digital Radiography Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. KSA Digital Radiography Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
