
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Leak Testing Market Size 2024 | USD 6602 Million |
| Leak Testing Market, CAGR | 8.1% |
| Leak Testing Market Size 2032 | USD 12310 Million |
Market Overview:
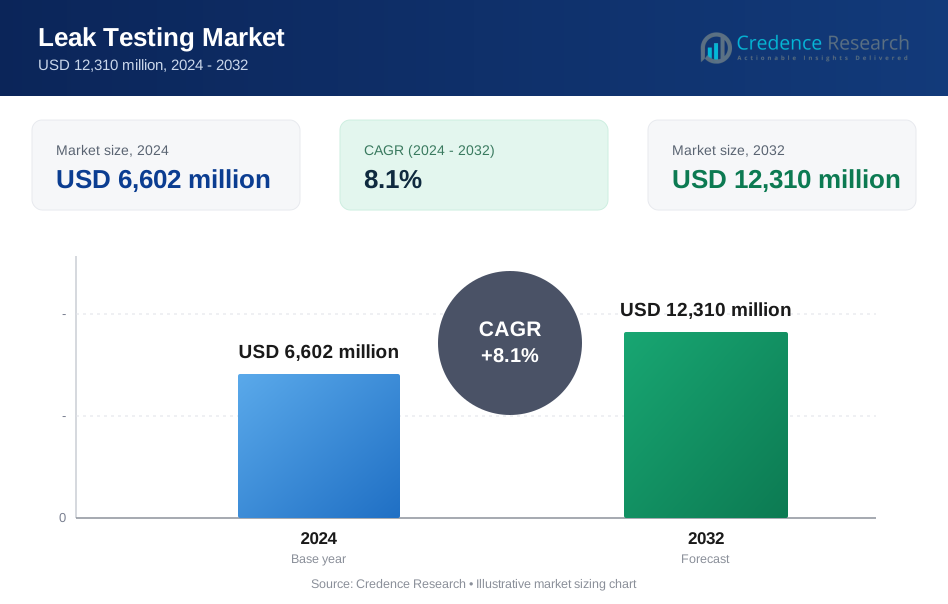
The Leak Testing Market is projected to grow from USD 6602 million in 2024 to an estimated USD 12310 million by 2032, with a compound annual growth rate (CAGR) of 8.1% from 2024 to 2032.
The leak testing market benefits from a range of strong drivers. Regulatory compliance across sectors such as automotive fuel systems, aerospace hydraulic components, and sterile medical packaging mandates the use of certified leak detection procedures. Leak testing ensures product safety, environmental protection, and extended system lifespan by identifying minute leaks in critical assemblies. The shift toward electric mobility has introduced new demand for leak testing in battery packs, power electronics, and cooling circuits. Medical applications require precise micro-leak detection to guarantee the safety of disposable and implantable devices. Industries are investing in integrated, automated, and sensor-based systems that deliver repeatable results with minimal operator intervention. The growing focus on Industry 4.0, predictive maintenance, and data-driven process control further supports the adoption of intelligent leak testing solutions that offer remote diagnostics, real-time monitoring, and cloud connectivity.
Regionally, the leak testing market is led by Asia-Pacific, which accounts for approximately 38% of global revenue. The region's dominance is supported by strong automotive, electronics, and industrial production bases in China, Japan, South Korea, and India. Rising adoption of electric vehicles, expansion of renewable energy infrastructure, and increasing export quality standards all reinforce market growth. North America holds about 30% of the global market, led by the United States where demand is high in aerospace, medical devices, and advanced manufacturing. Europe commands roughly 25% market share, with countries like Germany and France enforcing strict product quality and environmental regulations. The region remains a stronghold for automotive testing, pharmaceutical compliance, and industrial machinery validation. Latin America and the Middle East & Africa together contribute less than 10% of total market value but are experiencing steady development due to infrastructure projects, oil and gas sector needs, and broader industrial safety requirements. This diverse regional landscape highlights both the maturity of traditional markets and the untapped potential in emerging economies.
Market Insights:
- The leak testing market is expected to grow from USD 6,602 million in 2024 to USD 12,310 million by 2032, at a CAGR of 8.1%, driven by stricter regulations and expanding applications.
- Automotive and electric vehicle industries significantly contribute to market expansion by requiring leak-proof components such as battery packs and cooling systems.
- Environmental sustainability efforts, including emission control in oil and gas and HVAC sectors, continue to boost demand for accurate leak detection technologies.
- Integration of leak testing systems with smart manufacturing platforms supports real-time monitoring, traceability, and predictive maintenance in production environments.
- High capital costs and operational complexity limit adoption in small to mid-sized enterprises and in regions with limited technical expertise or infrastructure.
- Diverse application needs and inconsistent global standards challenge market players to develop flexible, industry-specific testing solutions.
- Asia-Pacific leads in growth rate, North America leads in technology and compliance adoption, and Europe advances with sustainable, quality-centric manufacturing environments.
Market Drivers:
Stringent Regulatory Compliance and Safety Standards Accelerate Adoption:
Governments and international regulatory bodies are enforcing strict product quality, safety, and environmental guidelines. These mandates require manufacturers across sectors to ensure leak-proof systems in components ranging from fuel lines to sterile medical devices. The leak testing market benefits from such regulatory pressures, as companies adopt precise and reliable detection tools to avoid fines, recalls, and reputational damage. Organizations such as the FDA, EPA, ISO, and EU agencies require comprehensive leak validation during both development and production stages. The growing complexity of devices in sectors like healthcare and aerospace further increases the need for accurate and repeatable testing. This compliance-driven demand ensures consistent investment in advanced leak detection technologies across global markets.
- For instance, the FDA mandates leak testing for medical devices to ensure patient safety, with compliance rates above 95% in surveyed companies. EPA regulations require leak detection in industrial emissions, with a 20% reduction in leaks reported after enforcement.
Surge in Demand from Automotive and EV Industries:
The automotive sector plays a critical role in driving the leak testing market, with growing use in internal combustion engine components, batteries, transmissions, and fuel delivery systems. With the rise of electric vehicles, manufacturers face new challenges in ensuring leak-tightness in high-voltage battery enclosures, cooling systems, and hydrogen fuel cells. Leak testing supports early detection of fluid leakage, which could otherwise compromise safety and performance. The integration of electronic systems in vehicles also raises the need for airtight compartments to prevent moisture damage. As OEMs and suppliers adopt tighter tolerances and quality expectations, automated and high-throughput leak testers become essential tools. The market continues to expand alongside the evolution of cleaner and more complex mobility platforms.
- For instance, Automated leak testing systems are now standard in major OEM production lines, and the adoption of dry, vacuum-based detection systems has become integral to quality assurance in EV battery assembly.
Growing Focus on Environmental Sustainability and Emission Reduction:
Leak detection systems are central to environmental protection efforts in sectors such as oil and gas, chemicals, HVAC, and energy. Companies face pressure to reduce emissions of harmful gases, including methane, refrigerants, and volatile organic compounds (VOCs). The leak testing market supports this shift by offering instruments that identify and quantify leaks early, preventing environmental contamination and energy waste. In oil refineries and pipelines, accurate detection of pressurized leaks helps operators maintain compliance with environmental standards and avoid catastrophic failures. Sustainability targets adopted by companies across industries reinforce the need for leak testing as a standard part of preventive maintenance and green operations. It enables proactive management of fluid systems, lowering operational risks and environmental impact.
Integration with Smart Manufacturing and Automation Platforms:
Industry 4.0 is reshaping quality control practices, and leak testing technologies are evolving to match. Smart leak testers with digital interfaces, IoT connectivity, and data analytics capabilities are gaining popularity across modern manufacturing lines. These systems allow real-time process feedback, traceable data logging, and predictive maintenance integration. The leak testing market gains traction as producers seek to minimize downtime, boost productivity, and ensure consistent product performance. Advanced automation reduces human error and enhances the repeatability of testing procedures. Adoption of machine vision and robotics within leak testing workflows supports continuous, high-speed inspections without compromising accuracy.
Market Trends:
Adoption of Helium and Hydrogen-Based Detection Methods:
Industries are increasingly turning to tracer gas methods using helium or hydrogen due to their superior sensitivity and accuracy. These methods enable the detection of micro-leaks in critical applications such as medical devices, aerospace components, and semiconductor packaging. The leak testing market benefits from this shift as traditional pressure decay and bubble tests often fall short in detecting ultra-fine leaks. Helium leak detectors, in particular, are becoming standard in applications where contamination or failure poses high risks. Hydrogen-based systems offer a more cost-effective alternative while still achieving acceptable sensitivity levels. The expanding use of these gases aligns with industries demanding non-destructive and precise leak testing solutions.
- For instance, Hydrogen as a tracer gas is also gaining traction, especially in packaging and electronics, due to its lower cost and high sensitivity, with systems like Sensistor Sentrac enabling rapid and accurate detection of microleaks in food and medical packaging.
Integration of Data Analytics and IoT Capabilities:
Digital transformation across industries is reshaping leak detection technologies. The leak testing market is seeing a surge in demand for systems that integrate IoT sensors, real-time monitoring, and cloud-based analytics platforms. Manufacturers now require leak testers that not only perform inspections but also capture, process, and analyze test data for traceability and process improvement. Predictive maintenance and automated alerts driven by AI models reduce downtime and help prevent quality failures. This data-driven approach allows quality control teams to track leak rate trends, machine performance, and compliance metrics over time. Integration with manufacturing execution systems (MES) and ERP software is becoming standard across automated production environments.
- For instance, Predictive maintenance powered by AI has reduced leak-related downtime by up to 25% in industrial operations, and integration with MES and ERP systems is now reported by 40% of automated production facilities.
Growth in Medical and Pharmaceutical Sector Applications:
The healthcare sector is becoming a major contributor to the leak testing market due to increasing demand for sterile and sealed environments. Devices such as catheters, syringes, IV bags, and implantable devices require rigorous leak validation to prevent contamination and ensure safety. Regulatory expectations from bodies like the FDA and EMA further mandate high-integrity testing of packaging and medical containers. Leak testing instruments tailored for cleanroom environments are gaining traction, including vacuum-based and pressure decay systems with sterile material compatibility. The pandemic has amplified focus on leak-proof packaging for diagnostic kits, vaccines, and biologics. It underscores the critical role of leak testing in ensuring patient safety and regulatory compliance.
Advancement in Non-Destructive and Automated Leak Testing Systems:
Manufacturers seek methods that preserve the integrity of tested products while ensuring accuracy and efficiency. Non-destructive testing (NDT) is becoming more prevalent, especially in sectors like electronics, food packaging, and automotive. The leak testing market is responding with solutions such as mass flow, optical, and ultrasonic testing that eliminate waste while maintaining reliability. Automation in these systems allows continuous operation with minimal human intervention, improving throughput in high-volume facilities. Compact, portable devices with intuitive user interfaces are also expanding adoption in field-based applications. This trend supports sustainable practices while aligning with evolving production needs.
Market Challenges Analysis:
High Equipment Costs and Operational Complexity Limit Adoption:
Leak detection systems with advanced features such as tracer gas technologies, automated sensors, and data integration often involve high capital expenditure. Small and medium-sized enterprises face barriers when investing in such systems due to budget constraints and uncertain return on investment. The leak testing market struggles to gain traction in price-sensitive regions and industries, particularly where manual testing methods still suffice. Operational complexity further hinders widespread adoption, as these systems require skilled technicians to calibrate, operate, and interpret results. Errors in setup or interpretation can lead to false positives or overlooked defects, reducing reliability. Companies must weigh cost, training needs, and production efficiency before switching to advanced solutions.
Lack of Standardization and Varied Application Needs Create Inconsistencies:
Different industries demand distinct testing standards and validation protocols, making it difficult to standardize leak detection methods. The leak testing market must cater to a wide array of requirements, from pharmaceutical micro-leak detection to high-pressure automotive components. This variability complicates the design of universal testing solutions and increases the need for customization. Inconsistencies in global regulatory frameworks further add to the challenge, especially for manufacturers operating across multiple regions. Variations in test media, detection thresholds, and acceptable leakage rates can lead to compliance issues. Harmonizing test methodologies without compromising accuracy remains a persistent obstacle.
Market Opportunities:
Growth in Electric Vehicles and Battery Safety Demands Advanced Testing:
The global shift toward electric vehicles creates a strong opportunity for the leak testing market. EV batteries, fuel cells, and thermal management systems require precise and repeatable leak detection to ensure safety and efficiency. Manufacturers must verify the integrity of battery enclosures, coolant circuits, and gas containment systems to prevent hazardous failures. It benefits from increasing demand for non-destructive testing methods that ensure zero-defect delivery in a high-growth sector. As battery complexity grows, OEMs prioritize automated, high-sensitivity leak testers integrated into production lines. The market gains from investments in EV manufacturing and evolving safety regulations worldwide.
Rising Need for Quality Assurance in Healthcare and Pharmaceuticals:
The healthcare sector presents strong growth potential due to rising regulatory scrutiny and demand for sterile, contamination-free packaging. The leak testing market addresses these requirements by offering equipment capable of detecting micro-leaks in blister packs, vials, syringes, and sealed containers. It supports quality assurance for vaccines, biologics, and high-risk pharmaceuticals that must maintain integrity throughout the supply chain. Adoption of non-invasive, high-precision test methods aligns with industry trends toward automation and traceability. Pharmaceutical companies seek reliable leak detection to meet FDA, EMA, and WHO compliance. The market gains from expanding production capacity and stringent global standards.
Market Segmentation Analysis:
By Testing Method/Technology
The leak testing market is dominated by pressure decay testing due to its cost-effectiveness and suitability for high-volume production. Vacuum and mass flow testing follow closely, offering enhanced sensitivity for specialized environments. Helium tracer gas testing, despite higher costs, remains critical in aerospace and medical applications requiring ultra-high precision. Ultrasonic and bubble emission testing serve industrial needs, while emerging technologies like laser absorption and optical gas imaging target niche, high-accuracy requirements.
- For instance, Vacuum decay testing, recognized by the FDA and ASTM F2338, offers unmatched sensitivity for micro-leak detection and is now widely adopted in pharmaceutical and food packaging, detecting leaks as small as 5 µm.
By Component
Detectors represent the core of leak testing systems, especially pressure and tracer gas detectors. Their role in accuracy and reliability ensures consistent demand. Probes, sensors, valves, and pumps are essential supporting components. They enable integration into automated systems and enhance the performance of both fixed and portable setups.
- For example, pressure decay detectors are specified in FDA and ASTM standards for medical and pharmaceutical packaging, and helium detectors are required in ISO 14644-7 for cleanroom applications.
By Equipment Type
Fixed leak testing equipment holds the majority share in large-scale production settings, offering efficiency and consistency. Portable equipment is gaining traction in maintenance, repair, and field inspection applications, particularly in the automotive and oil & gas sectors.
By End-User Industry/Vertical
Automotive leads due to stringent emission and safety standards. Aerospace and defense emphasize system integrity, driving demand for high-sensitivity methods. Medical devices and pharmaceuticals require leak-free packaging and instruments. HVAC/R and industrial manufacturing rely on testing for system reliability, while packaging, electronics, and oil & gas benefit from advancements in detection technologies.
By Service
Leak testing equipment continues to drive revenue, supported by software innovation and system automation. Leak testing services cater to firms without in-house capabilities and help meet regulatory compliance.
Segmentation:
By Testing Method/Technology- Pressure Decay Testing
- Vacuum Testing
- Mass Flow Testing
- Helium (Tracer Gas) Testing
- Ultrasonic Testing
- Bubble Emission Testing
- Other Methods (acoustic, optical gas imaging, laser absorption spectroscopy, underwater leak testing)
- Detectors (pressure, gas, tracer gas detectors)
- Probes
- Sensors
- Valves
- Pumps
- Fixed Leak Testing Equipment
- Portable Leak Testing Equipment
- Automotive
- Aerospace and Defense
- Medical Devices and Pharmaceuticals
- HVAC/R (Heating, Ventilation, Air Conditioning, and Refrigeration)
- Industrial/Manufacturing
- Packaging
- Electronics
- Oil & Gas
- Leak Testing Equipment (hardware, software)
- Leak Testing Services
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Dominates with Technological Leadership and Regulatory Enforcement
North America accounts for approximately 34% of the global leak testing market, driven by strong industrial bases, safety regulations, and technological advancements. The United States leads the region with widespread adoption of leak detection systems in automotive, aerospace, pharmaceuticals, and energy sectors. Regulatory agencies such as the FDA and EPA enforce strict quality and environmental standards, creating consistent demand for precision leak testing. Manufacturers in the region invest heavily in automation, IoT-enabled testing platforms, and high-throughput inspection systems. The market benefits from early adoption of helium mass spectrometry and vacuum decay methods across critical industries. Strong R&D infrastructure and a focus on workplace and environmental safety continue to reinforce North America’s leading market position.
Europe Advances with Sustainability and Quality-Centric Manufacturing
Europe holds a market share of nearly 29% in the leak testing market, supported by robust manufacturing sectors and sustainability-driven policies. Germany, France, Italy, and the UK lead in deploying advanced leak detection across automotive, packaging, and industrial applications. The region’s push for green manufacturing and reduced emissions aligns with the adoption of non-destructive, accurate leak testing systems. European manufacturers integrate leak detection into automated production lines to meet quality certification standards like ISO 9001 and CE marking. The presence of several established leak testing equipment manufacturers strengthens local availability and customization capabilities. Continuous investment in electric mobility, medical devices, and energy infrastructure expands market applications.
Asia-Pacific Emerges as the Fastest-Growing Region
Asia-Pacific commands approximately 25% of the global leak testing market and is projected to grow at the highest CAGR through 2032. China, Japan, South Korea, and India are the primary growth drivers due to rising automotive production, electronics manufacturing, and industrialization. The region's large-scale investments in battery production, semiconductor fabrication, and consumer goods manufacturing create strong demand for leak testing systems. Government initiatives to improve quality standards and environmental compliance boost adoption across regulated sectors. Domestic manufacturers increasingly adopt cost-effective, automated leak testing tools to stay competitive in export markets. It benefits from the region’s scale, rapid industrial growth, and shift toward quality-driven production.
Key Player Analysis:
- ATEQ Corporation
- INFICON
- Drägerwerk
- Honeywell International
- Emerson Electric
- TASI Group
- MSA Safety
- SGS SA
- Uson
- Testo
- Vacuum Instruments Corporation
- CETA TESTSYSTEME GmbH
- Helium Leak Testing
- Pfeiffer Vacuum
- LACO Technologies
- Fortest
- CTS Cincinnati
- InterTech Development Company
- Cosmo Instruments Co., Ltd.
Competitive Analysis:
The leak testing market features a competitive landscape marked by innovation, strategic partnerships, and diversified offerings across sectors. Leading players include INFICON, ATEQ, Pfeiffer Vacuum, TASI Group, and COSMO Instruments. These companies focus on developing high-precision, automated, and IoT-integrated solutions to meet evolving quality control standards in automotive, aerospace, medical devices, and packaging industries. The leak testing market favors firms with strong engineering capabilities, global service networks, and scalable product lines. It witnesses increasing competition from regional manufacturers in Asia-Pacific that offer cost-effective solutions for high-growth markets. Companies invest in R&D to enhance sensitivity, speed, and versatility of testing systems, while targeting emerging applications such as electric vehicle batteries and microelectronics. The presence of niche players offering customized technologies also shapes competition. Market leaders maintain their edge through product reliability, compliance with international standards, and robust customer support. Continuous innovation remains a critical factor for sustaining market share in this precision-driven domain.
Recent Developments:
- In February 2025, Honeywell International introduced a new line of portable leak detectors aimed at industrial safety applications.
- In April 2025, MSA Safety announced a strategic partnership with a global chemical company to develop integrated leak detection and safety monitoring solutions.
- In April 2025, Cosmo Instruments Co., Ltd. introduced a new compact leak detector designed for electronics manufacturing quality control.
Market Concentration & Characteristics:
The leak testing market shows moderate to high concentration, with a mix of established global players and specialized regional manufacturers. It operates in a precision-focused environment where accuracy, compliance, and customization drive competition. The market favors companies with advanced engineering capabilities, scalable automation solutions, and strong after-sales support. It serves a diverse customer base across automotive, medical, aerospace, and industrial sectors. Product differentiation stems from sensitivity range, testing speed, software integration, and adaptability to production lines. The leak testing market remains technology-driven, with firms investing in non-destructive testing innovations and data-enabled systems. High entry barriers exist due to stringent performance requirements and certification standards.
Report Coverage:
The research report offers an in-depth analysis based on By Testing Method/Technology, By Component, By Equipment Type, By End-User Industry/Vertical, By Service and By Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of Industry 4.0 practices will increase demand for automated and smart leak testing systems.
- Growth in electric vehicle production will expand applications for battery and component leak detection.
- Regulatory pressure in medical and pharmaceutical sectors will sustain demand for high-precision testing.
- Expansion of hydrogen fuel infrastructure will drive need for ultra-sensitive leak testers.
- Increasing investment in aerospace safety systems will support advanced leak detection technologies.
- Integration of IoT and real-time data analytics will enhance predictive maintenance and process control.
- Emerging economies will invest in leak testing to meet global export quality standards.
- Miniaturization of components will push development of compact, high-sensitivity testers.
- Sustainability initiatives will promote leak testing in HVAC and energy-efficient systems.
- Mergers and acquisitions will shape competitive dynamics and expand global footprints.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Compliance and Safety Standards
Governments and international agencies require manufacturers to implement certified leak detection procedures to ensure product safety and environmental protection, especially in automotive, aerospace, and medical sectors. This regulatory pressure drives consistent investment in advanced leak testing technologies to avoid fines, recalls, and reputational damage.
Growth in Automotive and Electric Vehicle Production
The shift toward electric mobility and the increasing complexity of automotive components, such as battery packs and cooling systems, have heightened the need for precise and automated leak testing. OEMs and suppliers are adopting high-throughput, automated leak testers to meet tighter tolerances and evolving quality expectations.
Environmental Sustainability and Emission Reduction
Industries such as oil & gas, chemicals, and HVAC are under pressure to reduce emissions of harmful gases and prevent environmental contamination. Leak testing systems enable early detection and quantification of leaks, supporting compliance with environmental standards and sustainability initiatives.
Integration with Smart Manufacturing and Industry 4.0
The adoption of Industry 4.0 practices is driving demand for leak testing systems with IoT connectivity, real-time monitoring, and data analytics. These intelligent solutions support predictive maintenance, process optimization, and traceability, enhancing productivity and reducing downtime in modern manufacturing environments.
Expansion of Medical and Pharmaceutical Applications
Rising regulatory scrutiny and the need for sterile, leak-proof packaging in medical devices and pharmaceuticals are increasing demand for high-precision leak testing. The sector requires micro-leak detection to ensure patient safety and compliance with FDA and EMA standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Leak Testing Market?
What factors are driving the growth of the Leak Testing Market?
What are the key segments within the Leak Testing Market?
What are some challenges faced by the Leak Testing Market?
Who are the major players in the Leak Testing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Detectors (pressure, gas, tracer gas detectors)
- 1.2.2 Probes
- 1.2.3 Sensors
- 1.2.4 Valves
- 1.2.5 Pumps
- 1.3 By Equipment Type
- 1.3.1 Fixed Leak Testing Equipment
- 1.3.2 Portable Leak Testing Equipment
- 1.4 By Testing Method/Technology
- 1.4.1 Pressure Decay Testing
- 1.4.2 Vacuum Testing
- 1.4.3 Mass Flow Testing
- 1.4.4 Helium (Tracer Gas) Testing
- 1.4.5 Ultrasonic Testing
- 1.4.6 Bubble Emission Testing
- 1.4.7 Other Methods (acoustic, optical gas imaging, laser absorption spectroscopy, underwater leak testing)
- 1.5 By End-User Industry/Vertical
- 1.5.1 Automotive
- 1.5.2 Aerospace and Defense
- 1.5.3 Medical Devices and Pharmaceuticals
- 1.5.4 HVAC/R
- 1.5.5 Industrial/Manufacturing
- 1.5.6 Packaging
- 1.5.7 Electronics
- 1.5.8 Oil & Gas
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,602 million → 2032: USD 12,310 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Leak Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Leak Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Leak Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Leak Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Leak Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Leak Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Leak Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Leak Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,602 million → 2032: USD 12,310 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Leak Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Detectors (pressure, gas, tracer gas detectors)
- 12.3.7.2 Probes
- 12.3.7.3 Sensors
- 12.3.7.4 Valves
- 12.3.7.5 Pumps
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Equipment Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fixed Leak Testing Equipment
- 12.4.7.2 Portable Leak Testing Equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Testing Method/Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pressure Decay Testing
- 12.5.7.2 Vacuum Testing
- 12.5.7.3 Mass Flow Testing
- 12.5.7.4 Helium (Tracer Gas) Testing
- 12.5.7.5 Ultrasonic Testing
- 12.5.7.6 Bubble Emission Testing
- 12.5.7.7 Other Methods (acoustic, optical gas imaging, laser absorption spectroscopy, underwater leak testing)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry/Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Automotive
- 12.6.7.2 Aerospace and Defense
- 12.6.7.3 Medical Devices and Pharmaceuticals
- 12.6.7.4 HVAC/R
- 12.6.7.5 Industrial/Manufacturing
- 12.6.7.6 Packaging
- 12.6.7.7 Electronics
- 12.6.7.8 Oil & Gas
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Leak Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Leak Testing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Leak Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Leak Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ATEQ Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 INFICON
- 18.4 Drägerwerk
- 18.5 Honeywell International
- 18.6 Emerson Electric
- 18.7 TASI Group
- 18.8 MSA Safety
- 18.9 SGS SA
- 18.10 Uson
- 18.11 Pfeiffer Vacuum
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

