
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Licensed Toy Market Size 2024 | USD 29,845.23 million |
| Licensed Toy Market, CAGR | 4.60% |
| Licensed Toy Market Size 2032 | USD 42,778.99 million |
Market Overview
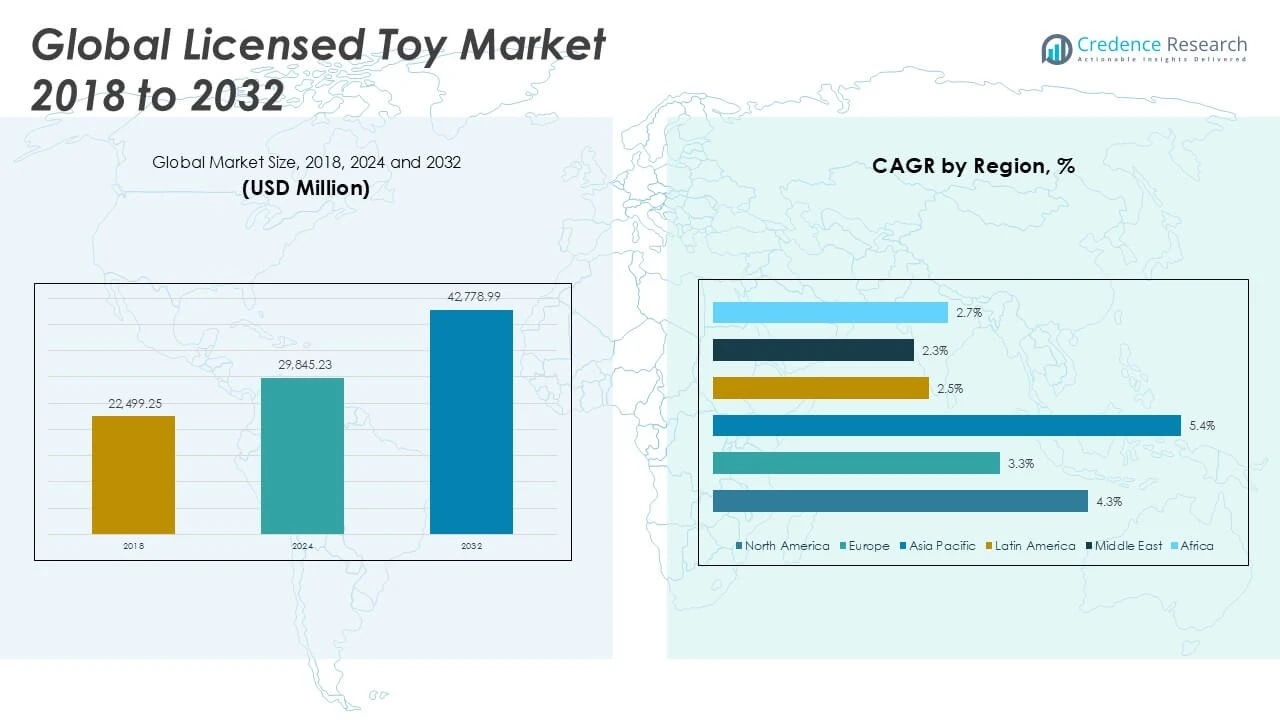
Licensed Toy Market size was valued at USD 22,499.25 million in 2018 to USD 29,845.23 million in 2024 and is anticipated to reach USD 42,778.99 million by 2032, at a CAGR of 4.60% during the forecast period.
The Licensed Toy Market experiences steady growth, driven by the global appeal of popular entertainment franchises and characters that resonate with both children and collectors. Strategic collaborations between toy manufacturers and media companies lead to continuous product innovation and frequent new launches, sustaining consumer interest and brand loyalty. The expansion of digital streaming platforms and social media amplifies the reach of licensed properties, fueling demand across multiple demographics and regions. E-commerce growth and omnichannel retail strategies improve accessibility and convenience for buyers, supporting rising sales volumes. Manufacturers respond to evolving consumer expectations by prioritizing product safety, eco-friendly materials, and unique designs that stand out in a competitive landscape. Trends such as collectible toys, limited editions, and interactive features further boost engagement and repeat purchases. Together, these drivers and trends reinforce the Licensed Toy Market’s position as a dynamic and resilient segment within the global toy industry.
The Licensed Toy Market demonstrates strong global presence, with North America, Europe, and Asia Pacific accounting for the largest revenue contributions due to advanced retail networks, high consumer spending, and deep-rooted connections to major entertainment franchises. Rapid urbanization and rising disposable incomes in Asia Pacific support accelerated growth, especially in countries like China and Japan, where demand for character-based and collectible toys is surging. Europe maintains robust demand for high-quality, safety-certified licensed toys, while Latin America, the Middle East, and Africa exhibit steady growth as international brands expand their reach and local adaptations gain popularity. Leading players in the market include Bandai Namco Holdings Inc., LEGO Group, Hasbro Inc., and Mattel Inc., all of whom leverage strong partnerships with entertainment companies, innovative product design, and diverse portfolios to maintain competitive advantage and capture evolving consumer preferences across regions.
Market Insights
- The Licensed Toy Market was valued at USD 22,499.25 million in 2018, reached USD 29,845.23 million in 2024, and is expected to reach USD 42,778.99 million by 2032, reflecting a CAGR of 4.60% during the forecast period.
- Strong demand for toys based on popular entertainment franchises, movies, and TV series fuels continuous market growth across multiple age groups.
- Key market trends include the rise of collectibles, integration of interactive technology, and a shift toward sustainable and eco-friendly licensed products.
- Major players such as Bandai Namco Holdings Inc., LEGO Group, Hasbro Inc., and Mattel Inc. focus on strategic partnerships, innovative product launches, and expanding their global reach.
- The market faces challenges from counterfeit products, intellectual property concerns, and rapidly shifting consumer preferences that require ongoing adaptation.
- North America, Europe, and Asia Pacific remain the primary regions for market activity, benefiting from advanced retail infrastructure, established licensing agreements, and strong entertainment industries.
- The increasing influence of digital media, gaming, and social media-driven licensing opportunities is expected to shape future product development and support diversified growth in emerging markets.
Market Drivers
Enduring Influence of Entertainment Franchises
The Licensed Toy Market benefits significantly from the enduring influence of globally recognized entertainment franchises. Major film studios, television networks, and digital content creators partner with toy manufacturers to launch products featuring beloved characters and storylines. This synergy drives recurring consumer interest and repeat purchases, as new movie releases, streaming series, and gaming titles generate fresh demand for licensed merchandise. The ability of franchises to cross generations allows the market to appeal to both children and adult collectors. The sustained popularity of brands such as Marvel, Disney, and Star Wars strengthens the market’s foundation. By aligning toy launches with media events, the Licensed Toy Market ensures consistent engagement and visibility across multiple platforms.
- For instance, licensing agreements with major entertainment franchises have led to increased sales of die-cast toys featuring characters from blockbuster films.
Strategic Collaborations and Licensing Agreements
Strategic collaborations and licensing agreements serve as key growth engines for the Licensed Toy Market. Leading manufacturers actively seek partnerships with global entertainment, sports, and gaming brands to diversify their product portfolios. These agreements enable access to well-established fan bases and create opportunities for co-branded products. The market responds quickly to new trends by securing timely licensing rights, enabling rapid development and launch of on-trend toys. Licensing partnerships foster innovation in product design, packaging, and marketing campaigns, which strengthens consumer loyalty. Manufacturers use these alliances to remain agile and competitive in a fast-evolving industry.
- For instance, Indian toy manufacturers now collaborate with international entertainment properties such as Disney, Marvel, Nickelodeon, and DC Comics to produce high-quality toys based on memorable characters.
Advancements in Retail and Distribution Channels
Expanding retail and distribution channels underpin the growth of the Licensed Toy Market. E-commerce platforms, specialty stores, and omnichannel retail strategies improve accessibility and convenience for consumers globally. The rise of digital marketing and influencer collaborations amplifies product reach, while robust logistics networks support efficient distribution. Retailers capitalize on seasonal events, exclusive launches, and bundled promotions to drive sales and maintain shopper interest. The market adapts quickly to shifting consumer behaviors by integrating online and offline experiences. This diversified retail presence ensures that licensed toys remain visible and readily available to a wide audience.
Focus on Innovation, Safety, and Sustainability
A strong focus on innovation, safety, and sustainability differentiates leading players in the Licensed Toy Market. Manufacturers invest in advanced materials, interactive features, and smart technologies to enhance product appeal and functionality. Stringent safety standards guide product development, addressing the concerns of parents and regulators alike. Eco-friendly materials and sustainable production practices gain traction, reflecting growing consumer awareness of environmental impact. The market introduces limited-edition and collectible items to foster exclusivity and encourage repeat purchases. These drivers collectively ensure the Licensed Toy Market remains resilient and responsive to evolving market expectations.
Market Trends
Rise of Collectibles and Limited Editions
The Licensed Toy Market witnesses a pronounced trend toward collectible and limited-edition products. Manufacturers create exclusive releases tied to major entertainment franchises, anniversaries, or media events, generating excitement and urgency among both children and adult collectors. These items often feature unique packaging, numbered certificates, or special accessories, enhancing their perceived value and desirability. The market sees strong secondary sales and trading communities develop around rare licensed toys, driving further engagement. Limited production runs help brands manage inventory risks and command premium prices. This trend amplifies brand loyalty and keeps consumer interest high throughout product life cycles.
- For instance, limited edition niche collectibles for movies, games, and anniversaries are increasingly becoming popular, and the market for such keeps expanding.
Expansion of Licensing Beyond Traditional Media
The Licensed Toy Market expands its scope beyond traditional film and television franchises to include video games, social media influencers, and sports personalities. The proliferation of digital content enables new licensing opportunities, allowing brands to tap into niche fandoms and diverse audiences. Toys inspired by viral internet trends, esports teams, or digital celebrities gain rapid popularity, reflecting shifting entertainment consumption habits. Manufacturers capitalize on these dynamics by adapting product portfolios to align with emerging icons and platforms. This broadens the appeal of licensed toys and supports sustained market growth across multiple demographics.
- For instance, streaming platforms like Netflix and Disney+ are serving as incubators for new intellectual property, which toy companies then translate into licensed toy lines.
Integration of Technology and Interactive Features
Integration of advanced technology stands out as a key trend in the Licensed Toy Market. Brands incorporate smart features such as app connectivity, voice recognition, and augmented reality to create immersive experiences. Interactive toys foster deeper engagement and encourage repeat use by offering customizable content or learning modules linked to licensed properties. The convergence of physical toys with digital platforms supports broader storytelling and cross-media promotion. Parents appreciate the educational value and entertainment options these toys deliver, while children are drawn to their novelty. Manufacturers prioritize partnerships with tech firms to accelerate product development and maintain a competitive edge.
Emphasis on Sustainability and Ethical Sourcing
Sustainability emerges as a central trend in the Licensed Toy Market, with companies adopting eco-friendly materials and transparent sourcing practices. Brands promote recyclable packaging, biodegradable plastics, and responsibly sourced fabrics to address rising consumer concerns about environmental impact. Licensing agreements increasingly include guidelines for ethical production and reduced carbon footprints. The market responds to regulatory pressures and consumer advocacy by publicizing sustainability initiatives and certifications. This commitment supports corporate social responsibility goals while attracting environmentally conscious buyers. Embracing sustainability enhances brand image and aligns licensed toy products with broader global values.
Market Challenges Analysis
Intellectual Property and Counterfeit Risks
The Licensed Toy Market faces persistent challenges related to intellectual property protection and the proliferation of counterfeit products. Unauthorized copying and distribution of popular licensed toys undermine brand reputation and erode the market share of legitimate manufacturers. It imposes significant legal and financial burdens on companies, forcing them to invest heavily in monitoring, enforcement, and anti-counterfeiting measures. The presence of fakes in both physical and online retail channels confuses consumers and raises concerns about product safety and quality. Brands must continually innovate in packaging, authentication, and supply chain management to combat these risks. Ensuring consumer confidence requires vigilant oversight and collaboration with regulatory bodies.
Evolving Consumer Preferences and Regulatory Pressures
Rapid shifts in consumer preferences and tightening regulations present further challenges for the Licensed Toy Market. Changing trends in entertainment and media can quickly alter demand for licensed properties, requiring manufacturers to adapt product lines at a fast pace. The growing emphasis on eco-friendly materials and ethical production places additional pressure on companies to overhaul sourcing and manufacturing practices. Meeting international safety standards demands continuous investment in research, testing, and compliance. Heightened scrutiny from parents, advocacy groups, and regulators increases the complexity of bringing new licensed toys to market. The need to balance innovation, safety, and sustainability often tests the agility and resilience of market participants.
- For instance, the Indian toy industry has witnessed a significant decline in imports due to government-led initiatives promoting domestic manufacturing and quality control.
Market Opportunities
Expansion into Digital and Emerging Media Properties
The Licensed Toy Market holds substantial opportunity in partnering with digital content creators, gaming companies, and social media influencers. The rapid rise of online streaming, mobile gaming, and short-form video platforms generates a continuous stream of new characters and brands that resonate with younger audiences. By securing licensing agreements with these fast-growing media properties, toy manufacturers can launch timely and relevant products that capture emerging consumer trends. It enables brands to reach niche fandoms and capitalize on viral phenomena that traditional media may not cover. Expanding into digital-first franchises supports product diversification and aligns with evolving entertainment consumption habits. This approach fosters innovation and keeps the Licensed Toy Market agile and competitive.
Focus on Sustainability and Ethical Consumerism
The Licensed Toy Market also finds strong opportunity in embracing sustainability and ethical business practices. Consumers are increasingly prioritizing eco-friendly materials, recyclable packaging, and responsible sourcing in their purchasing decisions. Leading companies invest in product innovation to develop toys that meet these expectations without compromising quality or safety. Partnerships with licensors can include sustainability guidelines, driving industry-wide adoption of greener practices. Highlighting ethical initiatives and certifications strengthens brand image and attracts environmentally conscious buyers. This focus positions the Licensed Toy Market for long-term growth, opening new segments and supporting higher brand loyalty in a changing global marketplace.
Market Segmentation Analysis:
By Product Type:
The Licensed Toy Market demonstrates a dynamic and diverse segment structure that supports broad consumer appeal and sustained growth. By product type, action figures and dolls & plush toys account for substantial market share, driven by popular entertainment franchises and the enduring appeal of character-based play. Arts & crafts, games & puzzles, outdoor & sports toys, construction sets, and educational toys each address distinct developmental and recreational needs, while the “others” segment captures niche and seasonal products.
By Price:
Segmenting by price, the market serves a wide spectrum of buyers through low, medium, and high price points. Low-priced toys attract budget-conscious families, while medium-priced options balance affordability with quality and brand recognition. The high-end segment features premium collectibles and limited-edition licensed items, targeting enthusiasts and gift buyers seeking exclusivity.
By Age Group:
Based on age group, the Licensed Toy Market provides tailored offerings from infants below 1 year to children and teenagers up to age 12+, ensuring relevance across every stage of childhood and extending to collectors. This comprehensive segmentation supports targeted marketing, innovation, and product differentiation in a competitive landscape.
Segments:
Based on Product Type:
- Action Figures
- Dolls & Plush Toys
- Arts & Crafts
- Games & Puzzles
- Outdoor & Sports Toys
- Construction Sets
- Educational Toys
- Others
Based on Price:
- Low
- Medium
- High
Based on Age Group:
- Below 1 Yrs.
- Age 1–3
- Age 3–5
- Age 5–12
- Age 12+
Based on End- User:
- Individual
- Commercial
Based on Distribution Channel:
- Online
- Offline
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Licensed Toy Market
North America Licensed Toy Market grew from USD 8,352.40 million in 2018 to USD 10,944.10 million in 2024 and is projected to reach USD 15,738.18 million by 2032, reflecting a CAGR of 4.3%. North America is holding a 37% market share in 2024. The region benefits from a mature retail landscape, strong presence of leading toy manufacturers, and continuous demand for toys linked to blockbuster entertainment franchises. High disposable incomes and a culture of seasonal gifting drive sustained growth. The United States remains the largest market, with frequent launches of licensed toys supported by integrated marketing campaigns. E-commerce and omnichannel strategies enhance accessibility and consumer engagement, reinforcing the region’s dominant position.
Europe Licensed Toy Market
Europe Licensed Toy Market grew from USD 5,202.50 million in 2018 to USD 6,595.87 million in 2024 and is expected to reach USD 8,769.81 million by 2032, with a CAGR of 3.3%. Europe accounts for a 22% market share. The market is shaped by a strong tradition of character-based toys and an emphasis on product safety and sustainability. Key markets such as the United Kingdom, Germany, and France lead adoption, driven by collaborations between toy brands and popular media franchises. Retailers leverage both online and offline channels to reach diverse consumer segments. Licensing agreements with European sports teams and animation studios further boost market growth.
Asia Pacific Licensed Toy Market
Asia Pacific Licensed Toy Market grew from USD 6,642.45 million in 2018 to USD 9,292.76 million in 2024 and is projected to reach USD 14,502.29 million by 2032, posting the fastest CAGR at 5.4%. Asia Pacific holds a 31% market share in 2024. Rapid urbanization, rising incomes, and a growing young population fuel strong demand for licensed toys across China, Japan, and Australia. Local adaptations of global entertainment franchises and the increasing popularity of anime and gaming properties drive product launches. E-commerce growth supports broad product reach, while seasonal promotions and educational campaigns stimulate sales. The region is positioned as a key driver of future global market expansion.
Latin America Licensed Toy Market
Latin America Licensed Toy Market grew from USD 952.62 million in 2018 to USD 1,246.12 million in 2024 and is set to reach USD 1,556.85 million by 2032, registering a CAGR of 2.5%. Latin America captures a 4% market share. Brazil and Mexico lead regional demand, with consumer interest rising for toys featuring international movie and TV characters. Urbanization, improvements in retail infrastructure, and targeted marketing campaigns support incremental growth. E-commerce and specialty stores expand product access, while price-sensitive consumers drive demand for value-oriented licensed products. Regional licensing of local sports and cultural icons also adds diversity to market offerings.
Middle East Licensed Toy Market
Middle East Licensed Toy Market grew from USD 697.48 million in 2018 to USD 853.38 million in 2024 and is projected to reach USD 1,052.09 million by 2032, reflecting a CAGR of 2.3%. The Middle East holds a 3% market share. The market benefits from a young population and increasing adoption of Western entertainment franchises. Key markets include the UAE and Saudi Arabia, where premium licensed toys are in demand. Expanding retail malls and the rise of e-commerce platforms increase accessibility. Licensing of regional characters and educational toys supports market diversification. Economic stability and tourism also help sustain demand.
Africa Licensed Toy Market
Africa Licensed Toy Market grew from USD 651.80 million in 2018 to USD 913.00 million in 2024 and is forecast to reach USD 1,159.78 million by 2032, at a CAGR of 2.7%. Africa holds a 3% market share. Growth is driven by an expanding young population, urbanization, and improving access to international brands. South Africa, Nigeria, and Egypt serve as key growth hubs, supported by investments in retail development and digital infrastructure. Price-sensitive consumers prefer affordable licensed toys, while awareness campaigns build interest in global characters. The market is in a developing stage, presenting long-term opportunities as incomes rise and retail networks mature.
Key Player Analysis
- Bandai Namco Holdings Inc.
- Basic Fun!
- Funko Inc.
- LEGO Group
- Hasbro Inc.
- JAKKS Pacific Inc.
- Mattel Inc.
- Melissa & Doug LLC
- Ravensburger AG
- VTech Holdings Ltd.
- Spin Master Corp.
- Tomy Company Ltd.
Competitive Analysis
The Licensed Toy Market is highly competitive, led by major players such as Bandai Namco Holdings Inc., Basic Fun!, Funko Inc., LEGO Group, Hasbro Inc., JAKKS Pacific Inc., Mattel Inc., Melissa & Doug LLC, Ravensburger AG, VTech Holdings Ltd., Spin Master Corp., and Tomy Company Ltd. These companies command strong brand recognition through established partnerships with global entertainment studios, movie franchises, and gaming companies, enabling them to secure exclusive rights to high-demand licensed properties. They invest heavily in product innovation, launching new collections and limited editions that keep consumer interest high and support premium pricing. Marketing strategies rely on coordinated releases with media events, influencer collaborations, and digital campaigns to reach a broad audience. These players continuously adapt to shifting consumer trends by incorporating technology, sustainability, and customization into their offerings. Robust distribution networks across e-commerce and retail channels ensure widespread product accessibility. To maintain their leadership, these companies emphasize quality, safety, and rapid response to market changes, positioning themselves as trendsetters in the evolving Licensed Toy Market.
Recent Developments
- In May 2025, JAKKS Pacific announced a new toy line for the DC x Sonic the Hedgehog crossover, launching fall 2025. The line features action figures, vehicles, and plush toys combining characters from both franchises, following the launch of a related DC comic series in March 2025.
- In March 2025, Bandai Namco launched a new initiative to strengthen its licensing business, establishing a dedicated licensing division from April 1, 2025. The company listed 27 IPs for potential licensing, including classics like Pac-Man, Ridge Racer, Soul Calibur, and the WonderSwan handheld, aiming to create more opportunities for collaborations and licensed products.
- In February 2025, Basic Fun! announced a worldwide licensing agreement with Hasbro to manufacture and distribute classic and reimagined Stretch Armstrong toys. The new line, featuring "Power Plasma" filling and multi-scale figures, will debut globally in fall 2025, including co-branded Stretch Armstrong-inspired licensed character action figures with other entertainment brands.
- In February 2025, Funko partnered with the NBA to launch personalized Pop! Yourself collectibles, allowing fans to create custom vinyl figures featuring official logos of all 30 NBA teams. This initiative debuted during NBA All-Star 2025, expanding Funko’s library of licensed NBA/NBPA products.
Market Concentration & Characteristics
The Licensed Toy Market displays a moderately high level of market concentration, with a select group of major players holding substantial influence over global sales and product innovation. It is shaped by dynamic collaborations between toy manufacturers and leading entertainment franchises, driving a steady pipeline of new product launches aligned with popular media releases. The market is highly responsive to trends in entertainment, technology, and consumer preferences, supporting continuous evolution in design, materials, and features. Its characteristics include frequent integration of collectible, interactive, and eco-friendly elements to meet the expectations of both children and adult collectors. Distribution is broad, spanning traditional retail, e-commerce, and omnichannel platforms that enable brands to reach diverse global audiences. The Licensed Toy Market benefits from strong brand loyalty, seasonal demand spikes, and the ability to adapt quickly to licensing opportunities and regulatory changes, making it a resilient and competitive segment of the global toy industry.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Price, Age Group, End-User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to continue its steady growth, driven by increasing consumer demand for comfort and wellness products.
- Rising awareness of the therapeutic benefits of heat therapy is expected to boost the adoption of microwaveable stuffed animal toys among both children and adults.
- Manufacturers are likely to focus on incorporating eco-friendly and sustainable materials to meet the growing consumer preference for environmentally conscious products.
- The integration of aromatherapy elements, such as lavender and chamomile scents, is anticipated to enhance the appeal of these toys for stress relief and relaxation.
- Customization options, including personalized designs and scents, are expected to become more prevalent, catering to individual consumer preferences.
- The expansion of e-commerce platforms will continue to facilitate wider distribution and accessibility of microwaveable stuffed animal toys globally.
- Seasonal demand, particularly during colder months and holiday seasons, is projected to contribute significantly to market sales.
- The market may face challenges related to safety regulations and the need for rigorous testing to ensure product safety, especially for children's use.
- Collaborations with healthcare providers and wellness centers could open new avenues for product application and market expansion.
- Continuous innovation in product design and functionality will be crucial for companies to maintain a competitive edge in the evolving market landscape.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enduring Influence of Entertainment Franchises
Globally recognized entertainment franchises such as Marvel, Disney, and Star Wars drive recurring consumer interest and repeat purchases, as new media releases continually generate fresh demand for licensed toys across generations.
Strategic Collaborations and Licensing Agreements
Toy manufacturers actively partner with entertainment, sports, and gaming brands to access established fan bases and launch co-branded products, enabling rapid response to trends and fostering innovation in product design and marketing.
Advancements in Retail and Distribution Channels
The expansion of e-commerce, omnichannel retail, and specialty stores increases accessibility and convenience for consumers, while digital marketing and influencer collaborations amplify product reach and support rising sales volumes.
Focus on Innovation, Safety, and Sustainability
Manufacturers prioritize advanced materials, interactive features, and eco-friendly production to meet evolving consumer expectations, ensuring product appeal, regulatory compliance, and differentiation in a competitive market.
Expansion of Licensing Beyond Traditional Media
Licensing now extends to video games, social media influencers, and digital content creators, allowing toy companies to tap into new fandoms and rapidly adapt to shifting entertainment consumption habits, broadening the market’s demographic reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Licensed Toy Market?
What factors are driving the growth of the Licensed Toy Market?
What are some challenges faced by the Licensed Toy Market?
Who are the major players in the Licensed Toy Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Price
- 1.2.1 Low
- 1.2.2 Medium
- 1.2.3 High
- 1.3 By Age Group
- 1.3.1 Below 1 Year
- 1.3.2 Age 1–3
- 1.3.3 Age 3–5
- 1.3.4 Age 5–12
- 1.3.5 Age 12+
- 1.4 By Product Type
- 1.4.1 Action Figures
- 1.4.2 Dolls & Plush Toys
- 1.4.3 Arts & Crafts
- 1.4.4 Games & Puzzles
- 1.4.5 Construction Sets
- 1.4.6 Educational Toys
- 1.4.7 Outdoor & Sports Toys
- 1.4.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 29,845.23 million → 2032: USD 42,778.99 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Licensed Toy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Licensed Toy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Licensed Toy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Licensed Toy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Licensed Toy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Licensed Toy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Licensed Toy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Licensed Toy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 29,845.23 million → 2032: USD 42,778.99 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Licensed Toy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Price - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Low
- 12.3.7.2 Medium
- 12.3.7.3 High
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Below 1 Year
- 12.4.7.2 Age 1–3
- 12.4.7.3 Age 3–5
- 12.4.7.4 Age 5–12
- 12.4.7.5 Age 12+
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Action Figures
- 12.5.7.2 Dolls & Plush Toys
- 12.5.7.3 Arts & Crafts
- 12.5.7.4 Games & Puzzles
- 12.5.7.5 Construction Sets
- 12.5.7.6 Educational Toys
- 12.5.7.7 Outdoor & Sports Toys
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Licensed Toy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Licensed Toy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Licensed Toy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Bandai Namco Holdings Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 LEGO Group
- 17.4 Hasbro Inc.
- 17.5 Mattel Inc.
- 17.6 Funko Inc.
- 17.7 Spin Master Corp.
- 17.8 JAKKS Pacific Inc.
- 17.9 VTech Holdings Ltd.
- 17.10 Ravensburger AG
- 17.11 Tomy Company Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

