Market Overview
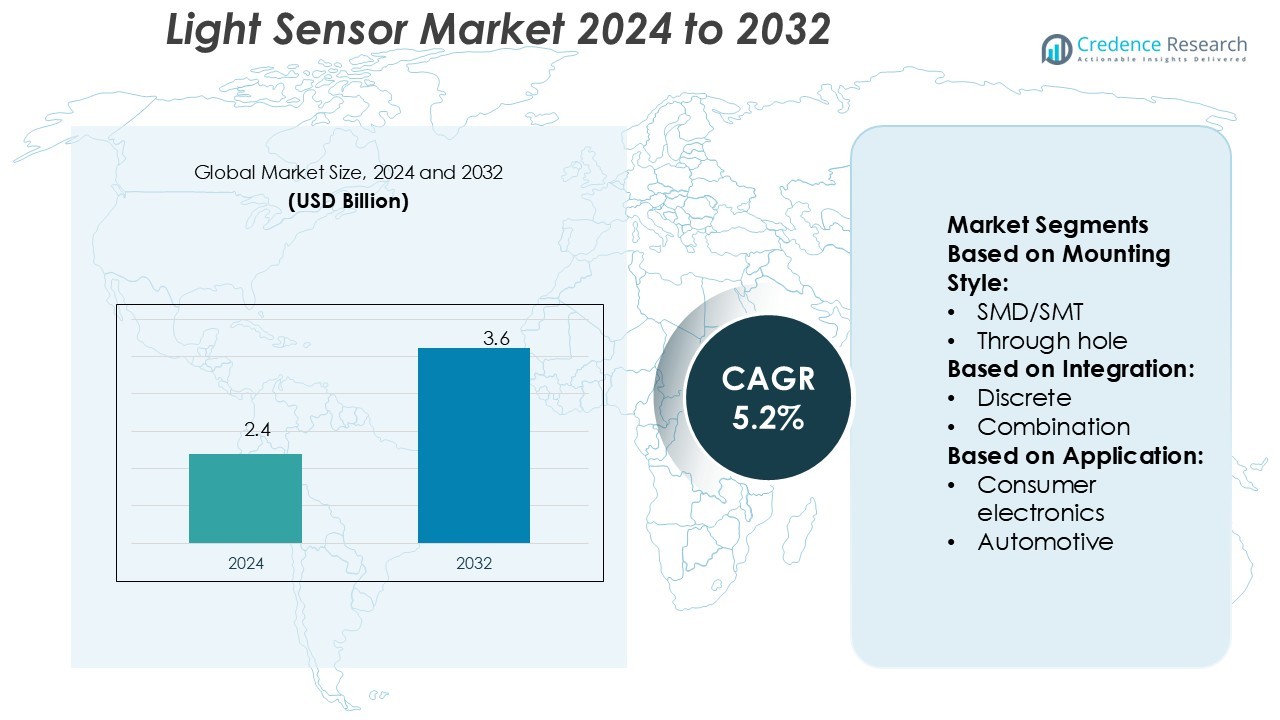
Light Sensor Market size was valued USD 2.4 billion in 2024 and is anticipated to reach USD 3.6 billion by 2032, at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Light Sensor Market Size 2024 | USD 2.4 Billion |
| Light Sensor Market, CAGR | 5.2% |
| Light Sensor Market Size 2032 | USD 3.6 Billion |
The light sensor market is driven by strong competition among leading players including ELAN Microelectronics Corp., Sitronix Technology Corporation, SAMSUNG, ROHM CO., LTD., STMicroelectronics, SHARP CORPORATION, EVERLIGHT ELECTRONICS CO., LTD., Analog Devices, Inc., ams-OSRAM AG, and Broadcom. These companies focus on innovation, large-scale manufacturing, and integration of advanced sensing technologies across consumer electronics, automotive, and industrial applications. Asia-Pacific leads the global market with a 34% share, supported by its strong semiconductor base, large-scale consumer electronics production, and growing adoption of smart devices. This regional dominance positions Asia-Pacific as the central hub for future market expansion.
Market Insights
- The Light Sensor Market size was valued at USD 2.4 billion in 2024 and is anticipated to reach USD 3.6 billion by 2032, growing at a CAGR of 5.2% during the forecast period.
- Market growth is driven by rising demand in consumer electronics, where smartphones, wearables, and laptops account for the largest segment share, supported by applications in automotive safety and industrial automation.
- Key trends include miniaturization of sensors, integration with IoT and AI technologies, and growing adoption in smart homes, which enhance energy efficiency and create new opportunities for multifunctional sensor designs.
- The market remains highly competitive with top players focusing on innovation, cost efficiency, and global expansion, while restraints such as price sensitivity in emerging markets and integration complexity pose challenges.
- Asia-Pacific leads with a 34% share, followed by North America at 32% and Europe at 27%, positioning the region as the hub for future expansion and large-scale sensor production.
Market Segmentation Analysis:
By Mounting Style
In the light sensor market, the SMD/SMT segment dominates with a share exceeding 55%. Its strong adoption stems from compact design, ease of integration, and suitability for high-volume consumer electronics production. Through-hole sensors retain relevance in industrial equipment, offering durability in harsh conditions. However, the miniaturization trend in electronics supports the faster growth of SMD/SMT. Other mounting styles serve niche uses but remain limited. High demand for smartphones, wearables, and IoT devices drives preference for SMD/SMT sensors, ensuring continued dominance in future adoption cycles.
- For instance, Cree Lighting’s OSQ Series area luminaire delivers between 4,000 and 85,000 lumens and reaches up to 171 LPW efficacy in outdoor lighting applications.
By Integration
The discrete segment leads with a market share of nearly 60%, driven by cost efficiency and flexibility across diverse applications. Discrete sensors allow manufacturers to design tailored solutions in automotive, industrial, and healthcare systems. The combination segment is growing quickly, fueled by demand for multi-functional modules in smart devices. Integration with microcontrollers and advanced chipsets increases adoption in connected ecosystems. While discrete sensors dominate due to versatility, the shift toward energy-efficient integrated systems ensures strong opportunities for combination solutions, especially in consumer electronics and automation platforms.
- For instance, OSRAM's OSLON™ UV 3535 UV-C LED, a compact and durable device designed for disinfection and treatment solutions, delivering a significant 115 milliwatt optical output at a peak wavelength of 265 nanometers and a long operating lifetime of over 20,000 hours.
By Application
Consumer electronics hold the largest share at above 40%, supported by rapid integration of light sensors in smartphones, laptops, and wearables. Growth in automotive applications, particularly for advanced driver-assistance systems and adaptive lighting, is accelerating adoption. Industrial uses benefit from sensors in smart manufacturing and energy-efficient systems. Home automation and healthcare applications are expanding as connected devices proliferate. Entertainment and security segments also strengthen demand for precision sensing. Consumer electronics continue to dominate the light sensor market, with innovation in display brightness control and energy savings driving consistent expansion.
Key Growth Drivers
Rising Demand in Consumer Electronics
The growing penetration of smartphones, tablets, laptops, and wearables drives the adoption of light sensors. These devices rely on sensors for automatic brightness adjustment, camera performance, and energy efficiency. Consumer preference for feature-rich electronics accelerates sensor integration across mid-range and premium categories. The demand for IoT-enabled gadgets and AR/VR devices also adds momentum. This segment remains a core driver of market expansion, as manufacturers continue to enhance device performance and deliver improved user experiences with advanced sensor technology.
- For instance, GE’s Cync Direct Connect smart bulbs operate on the 2.4 GHz Wi-Fi band and require no hub. GE’s Daintree WIZ100 wireless module integrates PIR sensing inside a fixture and communicates via low-power wireless to control nodes.
Expansion of Automotive Applications
Automotive innovation creates significant demand for light sensors in adaptive headlights, driver-assistance systems, and in-cabin lighting. Automakers increasingly adopt sensors to meet safety standards and enhance user comfort. The shift toward electric and autonomous vehicles further boosts integration, supporting energy-efficient lighting and advanced driver monitoring features. Governments also enforce regulations that encourage sensor adoption for improved road safety. With rising global vehicle production and adoption of EVs, the automotive sector is emerging as a leading growth driver for the light sensor market.
- For instance, Hubbell’s NX Distributed Intelligence™ platform uses NX Area Controllers to manage up to 1,000 NX devices (including luminaires, sensors, and switches) in wired, wireless, or hybrid mode.
Adoption in Smart Homes and Industrial Automation
The rapid growth of smart homes and industrial automation significantly contributes to light sensor market expansion. Smart lighting systems, energy management platforms, and home security devices rely heavily on sensor integration. Industrial automation uses sensors for energy-efficient lighting control and production monitoring. Growing consumer awareness of sustainability also supports this adoption. In both residential and industrial settings, light sensors enhance operational efficiency and reduce costs, making them an essential component of modern infrastructure and a key driver of future growth.
Key Trends & Opportunities
Integration with IoT and AI Technologies
The integration of light sensors with IoT and AI platforms is reshaping market opportunities. Smart devices and connected ecosystems use sensors for real-time monitoring and automation. AI-driven analytics enhance sensor accuracy and enable predictive adjustments in applications such as healthcare and industrial systems. This trend supports the creation of intelligent environments with energy-efficient lighting and adaptive systems. The convergence of IoT and AI expands the scope of light sensor applications, offering manufacturers opportunities to deliver innovative, value-added solutions.
- For instance, Nichia and Infineon launched a micro-LED matrix (µPLS) with 16,384 individual LEDs controlled via a driver IC, enabling high-definition adaptive lighting in automotive use.
Shift Toward Miniaturization and Multi-Functionality
Growing demand for compact, multifunctional components drives light sensor innovation. Manufacturers are developing miniaturized sensors with enhanced performance to support wearables, portable medical devices, and compact electronics. Multi-functional designs that combine light, proximity, and ambient sensing deliver cost and space efficiency. This trend aligns with consumer expectations for slim, high-performing devices and industrial needs for integrated solutions. The focus on miniaturization not only improves design flexibility but also creates opportunities for broader adoption across emerging applications such as drones and AR/VR systems.
- For instance, Inventronics (the company that now owns the former Osram HubSense product line) offers the QBM IoT Gateway, which supports up to 200 nodes (including LED drivers and sensors) in a single qualified Bluetooth mesh network, enabling robust control in wholesale-scale lighting installations.
Key Challenges
Price Sensitivity in Emerging Markets
High competition and cost constraints in emerging economies pose a challenge for light sensor manufacturers. Consumer electronics and industrial products in these regions often prioritize affordability, limiting adoption of advanced sensors. Price-sensitive buyers restrict demand for high-performance solutions, pressuring manufacturers to balance innovation with cost efficiency. This challenge impacts profit margins and slows the adoption of premium technologies in certain markets. Companies need strategies to optimize production costs and develop scalable models to capture opportunities without compromising profitability.
Complexity in Integration and Calibration
Integrating light sensors into diverse devices and systems presents technical challenges, especially in ensuring calibration accuracy and consistent performance. Variations in lighting conditions across applications demand advanced sensor designs, which increase development complexity. Improper integration can lead to performance issues, reducing efficiency in automotive, healthcare, or industrial applications. The need for precise calibration also raises production costs and lengthens product development cycles. Overcoming these challenges requires investment in R&D and strong collaboration with device manufacturers to ensure seamless integration and reliability.
Regional Analysis
North America
North America holds a market share of 32%, driven by strong adoption in consumer electronics, automotive, and industrial applications. The United States leads the region with advanced R&D, strong semiconductor presence, and high consumer demand for connected devices. Growth in smart homes, EVs, and automation enhances sensor integration. Canada contributes through rising healthcare applications, while Mexico benefits from expanding electronics manufacturing. Stringent energy efficiency regulations also support adoption. With well-established infrastructure and rising investments in smart technologies, North America maintains a leading position in the light sensor market.
Europe
Europe accounts for 27% of the market, supported by high demand in automotive and industrial sectors. Germany leads with strong automotive innovation, integrating light sensors into ADAS, adaptive headlights, and EV platforms. France and the UK contribute through industrial automation and consumer electronics adoption. Sustainability policies and energy efficiency directives further encourage sensor use in smart lighting and building automation. Rising investments in healthcare technology also strengthen regional demand. With robust manufacturing capabilities and regulatory support, Europe remains a key contributor to the growth of the light sensor market.
Asia-Pacific
Asia-Pacific dominates the light sensor market with a 34% share, driven by large-scale consumer electronics manufacturing and rising adoption across sectors. China, Japan, and South Korea lead with strong semiconductor industries and high-volume production of smartphones and wearables. India shows rapid growth in smart homes and automotive applications, supported by expanding industrial automation. Increasing urbanization and rising disposable income accelerate demand for connected devices. The region also benefits from government support for digitalization and energy efficiency initiatives. Asia-Pacific’s leadership is sustained by its production strength and growing consumer base.
Latin America
Latin America represents 3% of the light sensor market, with Brazil and Mexico leading adoption. The region benefits from rising demand for consumer electronics, smart lighting, and security applications. Brazil’s growing automotive sector integrates light sensors in ADAS and in-vehicle systems, while Mexico strengthens adoption through electronics assembly industries. However, economic fluctuations and limited local R&D slow overall growth. Increasing focus on energy efficiency and digital transformation provides opportunities for expansion. With a growing middle-class population and rising connected device usage, Latin America shows steady potential in the light sensor market.
Middle East & Africa
The Middle East & Africa region holds a 4% market share, with growth fueled by smart city projects and increasing adoption of connected devices. Gulf countries, particularly the UAE and Saudi Arabia, invest heavily in automation, smart lighting, and building management systems. Industrial automation in South Africa also drives demand. However, limited local manufacturing and dependence on imports restrain faster adoption. Rising digitalization, coupled with government-backed infrastructure initiatives, positions the region as an emerging market. MEA offers long-term opportunities for light sensor suppliers targeting energy-efficient and sustainable technologies.
Market Segmentations:
By Mounting Style:
- SMD/SMT
- Through hole
By Integration:
- Discrete
- Combination
By Application:
- Consumer electronics
- Automotive
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the light sensor market features prominent players such as ELAN Microelectronics Corp., Sitronix Technology Corporation, SAMSUNG, ROHM CO., LTD., STMicroelectronics, SHARP CORPORATION, EVERLIGHT ELECTRONICS CO., LTD., Analog Devices, Inc., ams-OSRAM AG, and Broadcom. The light sensor market is highly competitive, shaped by continuous innovation, strong manufacturing capabilities, and rising demand across multiple industries. Companies focus on advancing sensor accuracy, reducing power consumption, and developing multifunctional solutions to meet the needs of consumer electronics, automotive systems, and industrial automation. Growing adoption of IoT devices and smart home technologies further intensifies competition, pushing firms to enhance integration and scalability. Market participants also invest in R&D, strategic partnerships, and regional expansions to strengthen their global presence. The competitive environment emphasizes product differentiation, cost efficiency, and alignment with energy efficiency regulations.
Key Player Analysis
- ELAN Microelectronics Corp.
- Sitronix Technology Corporation
- SAMSUNG
- ROHM CO., LTD.
- STMicroelectronics
- SHARP CORPORATION
- EVERLIGHT ELECTRONICS CO., LTD.
- Analog Devices, Inc.
- ams-OSRAM AG
- Broadcom
Recent Developments
- In May 2025, Vishay Intertechnology, Inc. introduced the VEML4031X00, an AEC-Q100 qualified ambient light sensor designed for automotive applications. The sensor integrates an ambient light sensing (ALS) photodiode and an infrared (IR) photodiode within a compact surface-mount package measuring 4.38 mm × 1.45 mm × 0.6 mm.
- In April 2025, Sony Electronics announced the AS-DT1, a compact and lightweight LiDAR depth sensor designed for precise 3D measurement. The AS-DT1 uses Sony’s proprietary Direct Time of Flight (dToF) LiDAR technology. This system measures distance by calculating how long it takes for light to reflect off a surface.
- In March 2025, EarthTronics introduced EarthConnect area light sensors with extended outdoor range for commercial lighting applications. These features provide the ability to control exterior lighting from a smartphone or device with multiple energy-saving functions that help to increase the effectiveness of a security lighting system.
- In May 2024, Lumotive, a pioneer in optical semiconductor technology, and Hokuyo Automatic Co., Ltd., a global leader in sensors and automation, announced the commercial release of the YLM-10LX 3D lidar sensor.
Report Coverage
The research report offers an in-depth analysis based on Mounting Style, Integration, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for light sensors will rise with increasing adoption of smart consumer electronics.
- Automotive applications will expand as EVs and autonomous vehicles integrate advanced lighting systems.
- Industrial automation will drive greater usage of sensors in energy-efficient production environments.
- Smart home adoption will create strong demand for light sensors in connected lighting systems.
- Healthcare applications will grow as sensors support portable medical devices and monitoring tools.
- Miniaturization of sensors will enhance adoption in wearables, AR/VR, and compact electronics.
- Integration with IoT and AI will strengthen predictive and adaptive applications across industries.
- Sustainability initiatives will boost demand for sensors enabling energy-efficient lighting solutions.
- Emerging economies will present new opportunities as digitalization and smart infrastructure expand.
- Continuous innovation and R&D will shape market competitiveness and support broader adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Consumer Electronics
The proliferation of smartphones, wearables, and laptops is driving the integration of light sensors for features like automatic brightness adjustment and camera optimization, making this segment the largest contributor to market growth.
Expansion of Automotive Applications
Automotive manufacturers are increasingly adopting light sensors for adaptive headlights, advanced driver-assistance systems, and in-cabin lighting, especially as electric and autonomous vehicles become more prevalent.
Adoption in Smart Homes and Industrial Automation
The growth of smart home devices and industrial automation platforms relies on light sensors for energy-efficient lighting, security, and operational monitoring, fueling demand across residential and industrial sectors.
Integration with IoT and AI Technologies
Light sensors are being embedded in IoT and AI-driven systems for real-time monitoring, predictive analytics, and adaptive control, expanding their use in intelligent environments and connected ecosystems.
Miniaturization and Multi-Functionality
Ongoing innovation in sensor miniaturization and the development of multifunctional sensors are enabling their use in compact devices such as wearables, AR/VR systems, and portable medical equipment, broadening the market’s application base.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Light Sensor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Light Sensor Market projected to grow between 2025 and 2032?
Which Light Sensor Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Light Sensor Market?
Who are the leading companies in the Light Sensor Market?
Which region commanded the largest share of the Light Sensor Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Consumer electronics
- 1.2.2 Automotive
- 1.2.3 Industrial
- 1.2.4 Home automation
- 1.2.5 Healthcare
- 1.2.6 Entertainment & Security
- 1.3 By Integration
- 1.3.1 Discrete
- 1.3.2 Combination
- 1.4 By Mounting Style
- 1.4.1 SMD/SMT
- 1.4.2 Through hole
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.4 billion → 2032: USD 3.6 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Light Sensor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Light Sensor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Light Sensor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Light Sensor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Light Sensor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Light Sensor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Light Sensor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Light Sensor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.4 billion → 2032: USD 3.6 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Light Sensor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Industrial
- 12.3.7.4 Home automation
- 12.3.7.5 Healthcare
- 12.3.7.6 Entertainment & Security
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Integration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Discrete
- 12.4.7.2 Combination
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mounting Style - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 SMD/SMT
- 12.5.7.2 Through hole
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Light Sensor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Light Sensor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Light Sensor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Light Sensor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ELAN Microelectronics Corp.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sitronix Technology Corporation
- 18.4 SAMSUNG
- 18.5 ROHM CO., LTD.
- 18.6 STMicroelectronics
- 18.7 SHARP CORPORATION
- 18.8 EVERLIGHT ELECTRONICS CO., LTD.
- 18.9 Analog Devices, Inc.
- 18.10 ams-OSRAM AG
- 18.11 Broadcom
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.