
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liquid Detergent Market Size 2024 | USD 38,049.71 million |
| Liquid Detergent Market, CGR | 4.6% |
| Liquid Detergent Market Size 2032 | USD 54,526.15 million |
Market Overview:
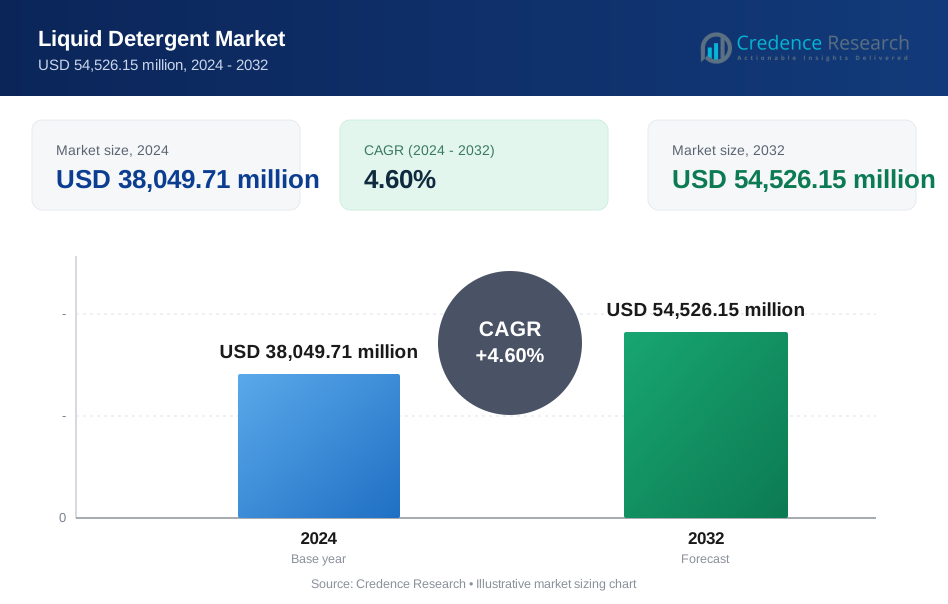
The Liquid Detergent market is projected to grow from USD 38,049.71 million in 2024 to USD 54,526.15 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.6%.
The liquid detergent market is driven by increasing consumer demand for convenience, effectiveness, and eco-friendly solutions. Consumers' preference for liquid detergents over powder formats due to their ease of use, faster dissolving properties, and versatility in various washing machines is fueling market growth. Additionally, the rise in eco-consciousness has led to a surge in demand for sustainable and biodegradable detergent formulations, as manufacturers innovate with plant-based ingredients and recyclable packaging. The growing adoption of smart appliances and the shift toward premium, specialized products such as stain removers and fabric softeners are further contributing to market expansion. Furthermore, the rising disposable income in emerging markets and the ongoing trend of premiumization, with consumers willing to pay more for high-quality, effective detergents, are supporting the growth of the liquid detergent market. These trends, along with increasing awareness of hygiene, are expected to propel the market to new heights over the coming years.
The liquid detergent market exhibits distinct regional dynamics, with North America, Europe, and Asia-Pacific leading in market share. North America, holding 25%, benefits from strong consumer demand for premium and eco-friendly products. Europe, with a 30% share, is driven by sustainability trends and a preference for high-quality formulations. Asia-Pacific leads globally with 35% market share, fueled by rapid urbanization and increasing disposable incomes, especially in countries like China and India. Latin America (5%) and the Middle East and Africa (5%) also show growth potential, though they remain more price-sensitive. Key players like Colgate-Palmolive, Reckitt Benckiser, Henkel, Kao, and Ecover are focusing on regional innovations, targeting both premium and eco-conscious consumer segments across these regions, ensuring strong competition and market expansion.
Market Insights:
- The liquid detergent market is projected to grow from USD 38,049.71 million in 2024 to USD 54,526.15 million by 2032, reflecting a CAGR of 4.6%.
- Consumer demand for convenience, effectiveness, and eco-friendly solutions is driving market growth, with a preference for liquid detergents over powder formats due to their ease of use and quick dissolving properties.
- The rise of eco-conscious consumers is fueling the demand for sustainable and biodegradable liquid detergents, with plant-based ingredients and recyclable packaging becoming key features.
- Technological advancements in detergent formulations are enhancing cleaning power, reducing residue, and introducing specialized products like stain removers and fabric softeners.
- Rising disposable incomes in emerging markets, especially in Asia-Pacific and Latin America, are driving the adoption of premium liquid detergents.
- North America (25%), Europe (30%), and Asia-Pacific (35%) dominate the market, with growing demand for eco-friendly, high-quality products in these regions.
- Latin America and the Middle East & Africa hold a combined 10% market share, with a focus on affordable, effective products due to price sensitivity in these regions.
Market Drivers:
Convenience and Ease of Use:
The growing preference for liquid detergents can be attributed to their convenience and ease of use. Liquid detergents dissolve quickly in water, ensuring that they are effective even in cold washes. This feature enhances their popularity, particularly among consumers seeking faster and more efficient cleaning solutions. For instance, Procter & Gamble's Tide Professional Commercial Laundry Detergent caters to businesses like hospitality and healthcare by offering reliable cleaning in a single wash. Moreover, liquid detergents are often more versatile, being suitable for a wide range of washing machines and laundry types, which boosts their demand. As busy lifestyles drive the need for quick and effective laundry solutions, liquid detergents continue to capture a larger share of the market.
Eco-Friendly Formulations and Sustainability:
As consumers become more environmentally conscious, the demand for eco-friendly and sustainable products is rising. Liquid detergents are increasingly formulated with biodegradable ingredients and come in recyclable packaging. This shift towards environmentally responsible products reflects the broader trend of sustainability across various consumer goods industries. Manufacturers are responding to this demand by developing liquid detergents that are free from harsh chemicals, phosphates, and other pollutants. Such eco-conscious formulations are not only appealing to environmentally aware consumers but also meet regulatory standards aimed at reducing environmental impact.
Technological Advancements in Detergent Formulations:
Advancements in technology and chemical engineering are driving innovation in the liquid detergent sector. Manufacturers are constantly refining detergent formulations to enhance cleaning power, minimize residue, and improve the overall user experience. The introduction of high-efficiency liquid detergents, which require smaller amounts of detergent per load, is contributing to market growth. Additionally, the development of specialized liquid detergents designed for specific purposes, such as stain removal or fabric softening, is expanding the range of products available, meeting diverse consumer needs.
Rising Disposable Incomes in Emerging Markets:
The rising disposable income in emerging markets, particularly in Asia-Pacific and Latin America, is another key driver of the liquid detergent market. As the middle class in these regions grows, consumers are increasingly opting for premium cleaning products, including liquid detergents, as they become more accessible. For instance, Unilever introduced OMO Concentrate, a six-times concentrated laundry detergent designed for dilution at home, first rolled out in Brazil. This shift towards higher-quality, branded liquid detergents is supporting market expansion. Moreover, as urbanization increases and more consumers adopt modern appliances, the demand for efficient and effective laundry products continues to rise, further fueling market growth.
Market Trends:
Shift Towards Eco-Friendly Products:
One of the most prominent trends in the liquid detergent market is the increasing demand for eco-friendly products. Consumers are becoming more aware of the environmental impact of their purchasing decisions, leading to a rise in preference for biodegradable, non-toxic, and sustainable liquid detergents. For instance, ECOS, which unveiled its Ultra-Concentrated Laundry Detergent at the Natural Products Expo West in 2024. The product offers up to 80 washes per recyclable aluminum bottle and incorporates stain-fighting enzymes while minimizing packaging waste. Manufacturers are responding by developing products that utilize plant-based ingredients and environmentally friendly packaging. This trend aligns with broader global efforts to reduce carbon footprints and minimize waste, and it is expected to grow as sustainability continues to be a key factor in consumer decision-making.
Rise of Premium and Specialized Products:
Another notable trend is the growing demand for premium and specialized liquid detergents. Consumers are increasingly willing to pay a premium for products that offer enhanced performance or cater to specific needs, such as fabric softening, stain removal, or hypoallergenic formulas. This trend is driven by a desire for more effective and personalized laundry solutions. As a result, brands are diversifying their product offerings, with many introducing specialized formulations that cater to particular fabrics, washing machines, or environmental conditions, further expanding their market reach.
Adoption of Smart Laundry Solutions:
The integration of smart technology in laundry appliances is influencing the liquid detergent market. With the rise of smart washing machines that optimize wash cycles based on load size and fabric type, there is a growing demand for liquid detergents that are compatible with these advanced systems. This trend is pushing manufacturers to develop products that are specifically formulated for smart appliances, ensuring that consumers receive the best performance and efficiency from their laundry care routine. As smart home technologies continue to gain popularity, the liquid detergent market is poised to benefit from these innovations.
Growth in Emerging Markets:
The liquid detergent market is witnessing significant growth in emerging markets, particularly in regions like Asia-Pacific and Latin America. As disposable incomes rise and urbanization accelerates, more consumers are opting for modern and efficient laundry products, including liquid detergents. For instance, In China, the penetration of washing machines has risen significantly, with 96.7 washing machines per 100 households in 2020 compared to 86.4 in 2015. This shift is supported by increasing awareness of product quality and the availability of diverse product options, making liquid detergents an attractive choice. The growing middle class in these regions is driving both volume and premium product sales, contributing to the overall expansion of the liquid detergent market.
Market Challenges Analysis:
Raw Material Costs and Supply Chain Disruptions:
A significant challenge facing the liquid detergent market is the volatility in raw material costs. Key ingredients such as surfactants, enzymes, and fragrance oils are subject to fluctuating prices, influenced by global supply and demand dynamics, geopolitical events, and economic instability. For example, the price of palm oil, a common ingredient in many liquid detergents, can vary due to environmental concerns, trade restrictions, or weather events that impact crop yields. These fluctuations make it difficult for manufacturers to maintain stable production costs, often resulting in either increased product prices or a reduction in profit margins. Furthermore, ongoing global supply chain disruptions, exacerbated by the COVID-19 pandemic and logistics challenges, have intensified the issue. Delays in sourcing raw materials, transportation bottlenecks, and shortages of essential packaging materials have caused production delays and inflated operational costs. Manufacturers must navigate these hurdles while maintaining competitive pricing, which can prove challenging, particularly in price-sensitive markets.
Regulatory Pressures and Consumer Expectations:
The liquid detergent market also faces challenges related to regulatory pressures and shifting consumer expectations. Governments worldwide are increasingly focused on tightening environmental regulations, requiring manufacturers to comply with stricter guidelines for chemical use, packaging materials, and sustainability practices. Regulations around the use of phosphates and surfactants in detergents are becoming more stringent, with certain chemicals banned or limited due to their environmental impact. These evolving standards require manufacturers to reformulate their products, invest in research and development, and adopt eco-friendly packaging, all of which can increase operational costs. For instance, companies like Seventh Generation have responded by using plant-based surfactants and recyclable packaging to align with consumer preferences for environmentally conscious products. In addition, consumers are increasingly conscious of the ingredients in the products they use, demanding transparency and sustainability from brands. This shift in consumer behavior forces companies to continually adapt to meet the growing demand for eco-friendly, ethical, and high-performance products. Balancing these regulatory requirements while meeting consumer expectations poses a substantial challenge for liquid detergent manufacturers.
Market Opportunities:
The liquid detergent market presents significant opportunities, particularly in emerging economies where rising disposable incomes and urbanization are driving demand for more convenient and efficient laundry solutions. As the middle class expands in regions such as Asia-Pacific and Latin America, consumers are increasingly adopting modern washing machines and are willing to invest in higher-quality, branded liquid detergents. This shift is supported by greater awareness of product performance and a growing preference for liquid formats due to their ease of use and effectiveness. As these regions continue to experience economic growth and urbanization, the demand for liquid detergents is expected to rise, providing manufacturers with a robust growth opportunity. Moreover, the trend towards premiumization in these markets offers potential for introducing specialized liquid detergents that cater to specific needs, such as stain removal or fabric care, further expanding the market base.
Another promising opportunity lies in the growing emphasis on sustainability and eco-consciousness among consumers. With increasing awareness of environmental issues, there is a rising demand for eco-friendly and biodegradable liquid detergents. Manufacturers can capitalize on this trend by developing products that align with sustainable practices, such as plant-based ingredients, recyclable packaging, and cruelty-free formulations. This aligns with both consumer preferences and evolving regulatory requirements related to environmental impact. Additionally, technological innovations in detergent formulations, such as concentrated formulas that reduce packaging waste, offer opportunities to cater to environmentally conscious consumers while providing cost-saving benefits. By investing in research and development to meet these demands, companies can strengthen their market position and differentiate themselves in a competitive landscape, driving growth and brand loyalty.
Market Segmentation Analysis:
By Type
The liquid detergent market is segmented by type into concentrated liquid detergent, regular liquid detergent, and natural or organic liquid detergent. Concentrated liquid detergents are gaining popularity due to their effectiveness and smaller packaging, offering cost savings and convenience. Regular liquid detergents remain widely used, while the increasing demand for natural and organic variants reflects a shift towards environmentally friendly and non-toxic products, appealing to eco-conscious consumers.
By Form
Liquid detergents are available in various forms, including bottles, packs/sachets, and dispensers. Bottles are the most common packaging format, offering convenience and easy storage. Packs and sachets cater to price-sensitive consumers, offering smaller quantities at affordable prices. Dispensers, often seen in commercial and high-usage environments, provide controlled dispensing, reducing waste and enhancing convenience for users with large laundry loads.
By Usage
The liquid detergent market is divided into home laundry and commercial laundry segments. Home laundry accounts for the largest share, driven by increasing household demand for convenient and effective cleaning products. The commercial laundry segment is expanding as businesses, such as hotels, laundromats, and hospitals, require specialized detergents for bulk cleaning needs, offering manufacturers a growing market for tailored solutions.
Segments:
Based on Type
- Concentrated Liquid Detergent
- Regular Liquid Detergent
- Natural or Organic Liquid Detergent
Based on Form
- Bottle
- Pack/Sachet
- Dispenser
Based on Usage
- Home Laundry
- Commercial Laundry
Based on Packaging Size
- Small (less than 1 liter)
- Medium (1-2 liters)
- Large (more than 2 liters)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the liquid detergent market, accounting for 25% in 2024. This region benefits from high consumer awareness and demand for premium and eco-friendly products. The growing preference for liquid detergents over powders, driven by their effectiveness and ease of use, further boosts market growth. The demand for specialized liquid detergents, such as those for sensitive skin or stain removal, has led to the emergence of premium brands. Additionally, the increasing trend toward sustainability and eco-conscious consumer behavior is driving the adoption of environmentally friendly formulations. The presence of major global brands and strong retail distribution channels supports the market in North America, ensuring continued dominance in the liquid detergent sector.
Europe
Europe represents the largest share of the liquid detergent market, with 30% in 2024. The region’s preference for sustainable and high-quality products has fostered growth in eco-friendly liquid detergent variants, especially those using biodegradable ingredients and recyclable packaging. Strict environmental regulations and growing consumer concerns about chemical exposure are pushing manufacturers to innovate with natural or organic liquid detergents. Additionally, the increasing trend of premiumization, where consumers opt for higher-value, specialized detergents, continues to drive the European market. The market is also witnessing growth in commercial laundry as businesses adopt more efficient and sustainable cleaning solutions. Europe’s established retail sector, which offers easy access to liquid detergents, further strengthens its market share.
Asia-Pacific
Asia-Pacific leads the global liquid detergent market with a share of 35% in 2024. The region’s rapid urbanization, growing middle class, and rising disposable income are significant factors contributing to this growth. As more consumers adopt modern washing machines, the demand for liquid detergents, which are preferred for their convenience, continues to increase. Additionally, the expanding demand for premium and specialized liquid detergents in countries like China, India, and Japan offers ample opportunities for market expansion. Increasing awareness of hygiene and rising consumer expectations for high-quality, effective products also contribute to the region's growth. As environmental concerns grow, the demand for sustainable and organic liquid detergents is expected to gain further traction in the coming years.
Latin America
In 2024, Latin America holds a 5% share of the liquid detergent market. Although the region is experiencing steady growth, the market is more price-sensitive compared to North America and Europe. The demand for regular liquid detergents is strong, particularly in countries like Brazil and Mexico, where economic growth is driving consumer purchasing power. However, the adoption of premium and eco-friendly products remains relatively low. As the middle class in these countries continues to grow, there is an increasing shift toward modern laundry solutions, including liquid detergents. Manufacturers are focusing on offering affordable and efficient products that cater to the region's price-sensitive market, which presents growth opportunities, particularly in rural areas and smaller cities.
Middle East and Africa The Middle East and Africa account for 5% of the liquid detergent market share in 2024. This region is characterized by a mix of high-income markets, such as the Gulf Cooperation Council (GCC) countries, and emerging economies. Consumer demand is steadily growing, driven by increasing urbanization, rising living standards, and higher awareness of hygiene. The preference for liquid detergents is growing due to their convenience, and the demand for eco-friendly products is gradually increasing as environmental concerns gain attention. However, economic disparities between regions affect overall market penetration. As disposable incomes rise in certain areas, opportunities for premium liquid detergent products are emerging, especially in urban centers.
Key Player Analysis:
- Reckitt Benckiser
- Bluemoon
- Better Life
- Henkel
- Method Products
- Lion Corporation
- Kao
- Seventh Generation
- Colgate-Palmolive
- Biokleen
- LG Household Health Care
- Ecover
Competitive Analysis:
The liquid detergent market is highly competitive, with several prominent players leading the industry. Colgate-Palmolive, LG Household Health Care, Lion Corporation, Ecover, Biokleen, Kao, Reckitt Benckiser, Bluemoon, Better Life, Henkel, Seventh Generation, and Method Products are among the key companies shaping the market landscape. These companies are focusing on product innovation, sustainability, and premiumization to maintain their market positions. Colgate-Palmolive and Reckitt Benckiser, for instance, have strengthened their portfolios by offering both regular and concentrated formulas, with an emphasis on superior cleaning performance. In response to growing demand for eco-friendly products, companies like Ecover, Seventh Generation, and Biokleen have introduced biodegradable and plant-based detergents, capitalizing on the rising trend for environmentally conscious consumer behavior. Meanwhile, players such as Henkel and Kao continue to dominate with their established presence and extensive distribution networks, while new entrants like Bluemoon and Better Life are pushing for growth in niche segments, especially in price-sensitive markets.
Recent Developments:
- In December 2023, Godrej Consumers launched 'Godrej Fab', a liquid detergent targeted at the mass market in South India, covering Tamil Nadu, Andhra Pradesh, Karnataka, and Kerala. This move is part of the company's efforts to expand its product portfolio to meet the growing demand in the FMCG sector.
- In February 2024, Swash® Laundry Detergent introduced a bold new look with refreshed packaging and a re-engineered Auto-Stop Top, enhancing its ultra-concentrated formula. As part of this update, the brand rolled out a new advertising campaign featuring Hollywood's Ronald Gladden.
- In January 2025, Reckitt Benckiser launched Woolite in India, entering the premium liquid laundry detergent market. The product features a keratin-based formula imported from Europe and is exclusively available on e-commerce platforms.
- In March 2025, Henkel launched new concentrated formulas for its all®, Persil®, and Snuggle® liquid laundry products. These formulas reduce water usage, plastic consumption, and CO2 emissions while integrating 50% recycled plastic into packaging.
Market Concentration & Characteristics:
The liquid detergent market exhibits moderate concentration, with a few large players dominating the industry, alongside several smaller, regional brands. Leading companies such as Colgate-Palmolive, Reckitt Benckiser, Henkel, Kao, and Ecover hold substantial market shares due to their strong brand presence, extensive distribution networks, and product innovation. These global players focus on product differentiation, leveraging advancements in sustainability, premium formulations, and eco-friendly packaging. The market also includes numerous regional and niche players catering to specific consumer needs, particularly in emerging markets where price sensitivity plays a significant role. Competitive characteristics of the liquid detergent market include the growing demand for convenience, effectiveness, and environmentally friendly solutions. Manufacturers are increasingly investing in R&D to develop advanced formulations that meet diverse consumer preferences, such as stain removal and fabric care, while ensuring compliance with tightening environmental regulations. The dynamic nature of this market continues to encourage innovation and competition.
Report Coverage:
The research report offers an in-depth analysis based on Type, Form, Usage, Packaging Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The liquid detergent market will continue to see strong demand driven by growing consumer preference for convenience and efficiency in laundry products.
- Eco-friendly and sustainable formulations will become a central focus, with more brands offering biodegradable ingredients and recyclable packaging.
- Consumers will increasingly opt for specialized products like stain removers, fabric softeners, and detergents designed for specific fabrics or skin sensitivities.
- Emerging markets, particularly in Asia-Pacific and Latin America, will see a rise in the adoption of premium liquid detergents due to increased disposable incomes.
- Manufacturers will prioritize innovation in detergent formulas to improve cleaning power, reduce residue, and enhance user experience.
- The shift towards automation and the growing adoption of smart washing machines will boost the demand for liquid detergents that cater to modern appliances.
- E-commerce channels will continue to grow, making liquid detergents more accessible to a wider range of consumers.
- The trend of "premiumization" will persist, with consumers willing to pay more for high-quality, effective, and eco-conscious products.
- Governments worldwide will implement stricter environmental regulations, pushing manufacturers to reformulate products and adopt more sustainable practices.
- As consumer awareness of hygiene and product transparency increases, brands will focus on providing more information about ingredients and sustainability efforts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Convenience and Ease of Use
Liquid detergents dissolve quickly and work effectively in both cold and hot washes, making them highly convenient for consumers with busy lifestyles. Their versatility across different washing machines and laundry types further boosts their adoption over powder detergents.
Eco-Friendly Formulations and Sustainability
Rising environmental awareness is driving demand for liquid detergents with biodegradable ingredients and recyclable packaging. Manufacturers are innovating with plant-based and non-toxic formulations to appeal to eco-conscious consumers and comply with stricter environmental regulations.
Technological Advancements in Detergent Formulations
Continuous R&D has led to high-efficiency and specialized liquid detergents that offer superior cleaning, reduced residue, and targeted benefits like stain removal or fabric care. These innovations enhance product performance and expand consumer choice.
Rising Disposable Incomes in Emerging Markets
Growing middle-class populations and urbanization in regions like Asia-Pacific and Latin America are increasing the adoption of premium and branded liquid detergents. As consumers gain purchasing power, they are more willing to invest in higher-quality and specialized laundry solutions.
Shift Toward Premium and Specialized Products
Consumers are increasingly seeking premium liquid detergents with added benefits such as hypoallergenic properties, fabric softening, or compatibility with smart appliances. This trend is driving manufacturers to diversify their product portfolios and capture higher-value market segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Liquid Detergent Market?
What factors are driving the growth of the Liquid Detergent Market?
What are the key segments within the Liquid Detergent Market?
Who are the major players in the Liquid Detergent Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Bottle
- 1.2.2 Pack/Sachet
- 1.2.3 Dispenser
- 1.3 By Type
- 1.3.1 Concentrated Liquid Detergent
- 1.3.2 Regular Liquid Detergent
- 1.3.3 Natural or Organic Liquid Detergent
- 1.4 By Usage
- 1.4.1 Home Laundry
- 1.4.2 Commercial Laundry
- 1.5 By Packaging Size
- 1.5.1 Small (less than 1 liter)
- 1.5.2 Medium (1-2 liters)
- 1.5.3 Large (more than 2 liters)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 38,049.71 million → 2032: USD 54,526.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Detergent Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Detergent Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Detergent Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Detergent Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Detergent Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Detergent Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Detergent Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Detergent Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 38,049.71 million → 2032: USD 54,526.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Detergent Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bottle
- 12.3.7.2 Pack/Sachet
- 12.3.7.3 Dispenser
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Concentrated Liquid Detergent
- 12.4.7.2 Regular Liquid Detergent
- 12.4.7.3 Natural or Organic Liquid Detergent
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Usage - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Home Laundry
- 12.5.7.2 Commercial Laundry
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Packaging Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Small (less than 1 liter)
- 12.6.7.2 Medium (1-2 liters)
- 12.6.7.3 Large (more than 2 liters)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Detergent Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Liquid Detergent Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Liquid Detergent Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Colgate-Palmolive
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Reckitt Benckiser
- 17.4 Henkel
- 17.5 Kao
- 17.6 Ecover
- 17.7 Seventh Generation
- 17.8 LG Household Health Care
- 17.9 Lion Corporation
- 17.10 Bluemoon
- 17.11 Method Products
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

