
Market Overview
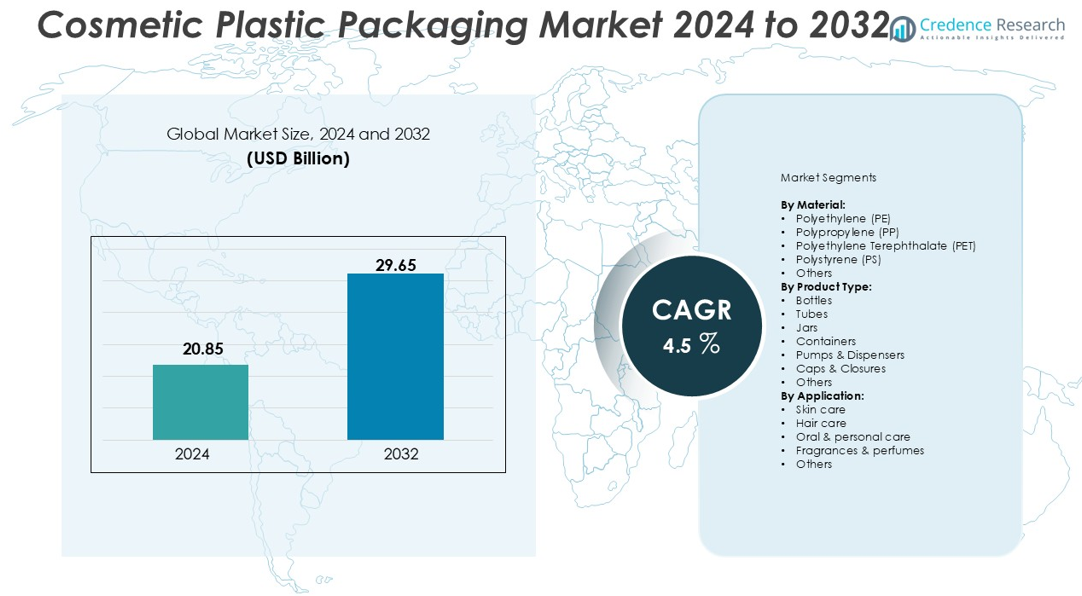
The cosmetic plastic packaging market size was valued at USD 20.85 billion in 2024 and is anticipated to reach USD 29.65 billion by 2032, at a CAGR of 4.5% during the forecast period
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cosmetic Plastic Packaging Market Size 2024 | USD 20.85 billion |
| Cosmetic Plastic Packaging Market, CAGR | 4.5% |
| Cosmetic Plastic Packaging Market Size 2032 | USD 29.65 billion |
The cosmetic plastic packaging market is led by prominent players such as Amcor, Berry Global, Aptar Group, and Albea, which collectively account for a major share of global revenue through their strong product portfolios and global manufacturing networks. These companies focus on sustainable materials, innovative dispensing solutions, and premium packaging designs to meet the evolving needs of cosmetic brands. Other notable participants, including Gerresheimer, AG Poly Packs, Cosmopacks, and Green Earth Packaging, are expanding through customized and eco-friendly solutions. Regionally, Asia-Pacific dominates the market with an estimated 35% share in 2024, driven by high cosmetic consumption, growing e-commerce, and cost-effective production capabilities.
Market Insights
- The global cosmetic plastic packaging market was valued at USD 20.85 billion in 2024 and is projected to reach USD 29.65 billion by 2032, growing at a CAGR of 4.5% during the forecast period.
- Market growth is primarily driven by rising demand for sustainable, lightweight, and aesthetically appealing packaging solutions across skincare, hair care, and personal care segments, with PET material holding the largest share due to its recyclability and durability.
- Key trends include the adoption of refillable and recyclable packaging systems, digital printing for customization, and the growing influence of e-commerce and premium beauty products on packaging innovation.
- The market is moderately competitive, with major players such as Amcor, Berry Global, Aptar Group, and Albea focusing on eco-friendly designs, product innovation, and strategic collaborations to expand global presence.
- Asia-Pacific dominates the market with a 35% share, followed by North America (28%) and Europe (25%), reflecting strong regional cosmetic consumption and manufacturing capacities.
Market Segmentation Analysis:
By Material:
The cosmetic plastic packaging market by material is dominated by Polyethylene Terephthalate (PET), accounting for the largest market share in 2024. PET’s superior transparency, durability, and recyclability make it the preferred choice for premium cosmetic packaging. Its lightweight nature and resistance to impact enhance portability and product safety, driving demand across skincare and personal care products. Polypropylene (PP) and Polyethylene (PE) follow closely, owing to their flexibility and cost-effectiveness. Increasing consumer preference for sustainable and recyclable materials continues to boost the adoption of PET-based packaging solutions.
- For instance, Amcor's new in-line operation in Paris, Texas, is expected to produce approximately 50 million hot-fillable PET bottles each year, enhancing operational efficiencies and sustainability.
By Product Type:
Among product types, bottles hold the dominant share in the cosmetic plastic packaging market, supported by their widespread use in skincare, hair care, and fragrance applications. Bottles offer excellent shelf appeal, ease of use, and design versatility, which attract major cosmetic brands. Growing innovation in lightweight and eco-friendly bottle designs also contributes to their dominance. Meanwhile, tubes and jars are gaining traction for compact and travel-friendly cosmetic products. Rising consumer awareness about product hygiene and controlled dispensing further drives demand for pumps, dispensers, and closures.
- For instance, Aptar's Future Airless PET® is the first high-capacity, e-commerce-capable, and recyclable PET airless packaging solution for beauty brands, offering a sustainable alternative to traditional packaging.
By Application:
The skincare segment leads the cosmetic plastic packaging market by application, capturing the largest market share in 2024. The surge in global skincare consumption, driven by increasing awareness of personal grooming and anti-aging trends, has accelerated demand for aesthetic and functional packaging. Plastic packaging in skincare ensures product protection from contamination and UV exposure, enhancing shelf life. The hair care and personal care segments also show strong growth potential due to rising disposable incomes and urbanization. Customization, portability, and sustainable packaging innovations remain key growth drivers across all applications.
Key Growth Drivers
Rising Demand for Sustainable and Eco-Friendly Packaging
Growing environmental awareness among consumers and regulatory pressures on reducing plastic waste are driving the adoption of sustainable packaging materials in the cosmetic plastic packaging market. Manufacturers are increasingly shifting toward recyclable, biodegradable, and refillable plastic options such as bio-based PET and post-consumer recycled (PCR) plastics. Major cosmetic brands are investing in circular economy initiatives and green packaging innovations to meet sustainability goals and appeal to eco-conscious buyers. This shift not only enhances brand image but also encourages the development of innovative material technologies that reduce environmental impact while maintaining product quality and aesthetics.
- For instance, L’Oréal used 73,707 tonnes of recycled materials in 2021 in its packaging lines, including 43,373 tonnes in primary and secondary packaging, thereby replacing equivalent virgin plastic volumes.
Expanding Cosmetic and Personal Care Industry
The rapid expansion of the global cosmetic and personal care industry is a primary growth driver for the cosmetic plastic packaging market. Rising disposable incomes, urbanization, and evolving beauty standards have significantly boosted the consumption of skincare, hair care, and fragrance products. Plastic packaging remains the material of choice for its lightweight, durability, cost-effectiveness, and design flexibility. The surge in e-commerce beauty product sales also amplifies the demand for protective and visually appealing packaging. Additionally, the proliferation of men’s grooming and organic beauty products continues to broaden market opportunities, reinforcing steady demand across diverse cosmetic categories.
- For instance, Unilever reported that in 2023, 22 percent of its global plastic packaging was made from recycled content, up from 21 percent in 2022 (i.e. if its total plastic portfolio is 1,000,000 tonnes, then 220,000 tonnes used recycled content).
Innovation in Design and Functional Packaging Solutions
Technological advancements and design innovation are reshaping the cosmetic plastic packaging landscape. Brands are investing in smart, functional, and aesthetically appealing packaging that enhances user experience and strengthens brand identity. Features such as airless pumps, precision dispensers, and tamper-evident closures are gaining popularity for improving hygiene and product longevity. Furthermore, digital printing and customization capabilities enable personalized branding and limited-edition packaging, appealing to the premium and luxury cosmetic segments. These innovations not only drive differentiation in a competitive market but also encourage greater consumer engagement and brand loyalty, thereby fostering long-term growth.
Key Trends & Opportunities
Growth of Refillable and Recyclable Packaging Systems
A significant market trend is the growing adoption of refillable and recyclable cosmetic packaging solutions. Leading brands are launching refill pods, modular packaging, and returnable systems to minimize waste and reduce carbon footprints. This trend aligns with sustainability regulations and shifting consumer expectations toward responsible consumption. Companies leveraging advanced recycling technologies, such as chemical recycling, are gaining a competitive edge by producing high-quality recycled resins suitable for cosmetic-grade applications. The opportunity lies in developing cost-effective, scalable, and attractive refillable systems that maintain both functionality and luxury appeal, meeting the dual goals of sustainability and customer satisfaction.
- For instance, L’Oréal Groupe expanded the number of refillable packaging options by a factor of 17 over five years across its brands.
Rising Influence of E-commerce and Digital Branding
The global rise of e-commerce platforms has transformed packaging requirements in the cosmetic industry. Online retail demands durable, lightweight, and visually appealing packaging capable of withstanding transportation while preserving product integrity. Plastic packaging meets these needs effectively and allows brands to experiment with eye-catching digital printing and design innovation for virtual shelf appeal. Furthermore, unboxing experiences and influencer-driven marketing have made packaging a critical brand touchpoint. Companies that integrate smart labeling, QR codes, and augmented reality (AR) elements into their packaging designs can enhance digital engagement and consumer loyalty, creating new opportunities for growth.
Key Challenges
Environmental Concerns and Regulatory Pressures
One of the foremost challenges in the cosmetic plastic packaging market is addressing environmental concerns and meeting stringent regulatory requirements. Governments and international agencies are imposing restrictions on single-use plastics and mandating higher recycling rates. Compliance with these evolving standards increases production costs and operational complexities for manufacturers. In addition, consumer backlash against excessive plastic use has intensified, pressuring companies to adopt sustainable alternatives without compromising aesthetics or affordability. Balancing innovation, cost-efficiency, and environmental responsibility remains a critical challenge that requires ongoing R&D investment
Fluctuating Raw Material Prices and Supply Chain Constraints
The volatility in crude oil prices, which directly affects the cost of plastic resins like PET, PE, and PP, poses a significant challenge to market stability. Unpredictable price fluctuations disrupt manufacturing margins and affect overall profitability. Moreover, global supply chain disruptions-driven by geopolitical tensions, trade restrictions, or logistical bottlenecks-have impacted the timely availability of raw materials and packaging components. These issues compel manufacturers to diversify suppliers, explore alternative materials, and invest in localized production. Building supply chain resilience and cost-effective sourcing strategies is essential to maintaining competitive advantage in a dynamic market environment
Regional Analysis
North America:
North America holds a significant share of the global cosmetic plastic packaging market, accounting for around 28% in 2024. The region’s strong demand stems from the high consumption of premium skincare, hair care, and personal grooming products. The presence of established cosmetic brands and growing adoption of sustainable and recyclable plastic materials drive market growth. Consumers’ preference for convenient, travel-friendly, and aesthetically designed packaging further supports product innovation. Additionally, stringent environmental regulations and increasing investment in eco-friendly packaging technologies are expected to sustain steady growth in the North American market over the forecast period.
Europe:
Europe captures approximately 25% of the global cosmetic plastic packaging market, driven by strong environmental awareness and regulatory mandates promoting sustainability. Countries such as Germany, France, and the U.K. are key contributors, emphasizing recyclable and bio-based plastic packaging solutions. The rising popularity of luxury cosmetics and the shift toward minimalist, refillable packaging designs enhance regional demand. European manufacturers are also leading innovations in circular economy practices, including post-consumer recycled (PCR) materials and closed-loop systems. The market continues to benefit from the region’s mature cosmetic industry and growing preference for eco-conscious, high-quality packaging alternatives.
Asia-Pacific:
Asia-Pacific dominates the cosmetic plastic packaging market with the largest share of around 35% in 2024. Rapid urbanization, rising disposable incomes, and expanding middle-class populations in countries like China, India, Japan, and South Korea are fueling market growth. The booming e-commerce and beauty retail sectors drive high consumption of lightweight and durable packaging. Additionally, increasing awareness of personal grooming and Western beauty trends supports continuous demand. Local manufacturers are investing in cost-effective and innovative packaging designs, while sustainability initiatives are gaining traction, positioning Asia-Pacific as the fastest-growing regional market through 2032.
Latin America:
Latin America accounts for nearly 7% of the global cosmetic plastic packaging market, with Brazil and Mexico emerging as key contributors. The region’s market growth is supported by a thriving beauty and personal care industry, particularly in skincare and hair care categories. Affordable plastic packaging options remain in high demand due to the region’s price-sensitive consumer base. Increasing adoption of modern packaging formats such as pumps, dispensers, and recyclable plastics is enhancing product appeal. While sustainability awareness is still evolving, global cosmetic brands’ regional expansions are expected to drive long-term growth in Latin America.
Middle East & Africa:
The Middle East & Africa region holds about 5% of the global cosmetic plastic packaging market in 2024. Market growth is driven by increasing demand for premium cosmetics, rising disposable incomes, and expanding retail infrastructure. Countries like the UAE, Saudi Arabia, and South Africa are witnessing a surge in personal care consumption influenced by urbanization and lifestyle changes. The adoption of durable and lightweight packaging materials supports growth across skincare and fragrance segments. Although sustainability initiatives are emerging gradually, the region presents strong opportunities for international brands and packaging manufacturers to expand their footprint
Market Segmentations:
By Material:
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene (PS)
- Others
By Product Type:
- Bottles
- Tubes
- Jars
- Containers
- Pumps & Dispensers
- Caps & Closures
- Others
By Application:
- Skin care
- Hair care
- Oral & personal care
- Fragrances & perfumes
- Others
By Geography:
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the cosmetic plastic packaging market is characterized by the presence of several global and regional players focusing on innovation, sustainability, and strategic expansion. Key companies such as Amcor, Berry Global, Aptar Group, and Albea dominate the market through advanced product designs, eco-friendly materials, and smart packaging solutions. These players invest heavily in R&D to develop recyclable, lightweight, and aesthetically appealing packaging that meets evolving consumer preferences and regulatory standards. Emerging participants like AG Poly Packs, Cosmopacks, and Green Earth Packaging are strengthening their positions through customized solutions and cost-effective manufacturing. Strategic partnerships, mergers, and acquisitions are common, enabling companies to enhance their product portfolios and expand geographic reach. The growing focus on circular economy practices and sustainable innovation continues to reshape competition, compelling both established and new entrants to balance functionality, design, and environmental responsibility in their packaging offerings.
Key Player Analysis
- Amcor
- Berry Global
- Aptar Group
- Albea
- Gerresheimer
- AG Poly Packs
- Cosmopacks
- APackaging Group
- Blakelin Plastics
- Green Earth Packaging
- Harman Packaging
- Guangzhou Keyuan Plasticware
- Jarsking
Recent Developments
- In March 2024, GEKA introduced the post-consumer-recycled (PCR) polypropylene (PP) material which is suitable for primary cosmetic packaging. It helps in reducing Co2 emissions by 75% and offers high quality colors to increase the visual appeal of the product.
- In June 2023, Respectueuse, known for its eco-friendly cosmetics, launched a product line which utilizes Sonoco’s rigid paper, EnviroStick Packaging. The company has launched this specifically for its deodorant products across the market.
- In February 2023, WWP Beauty, a company with strong focus on eco-conscious packaging and turnkey solutions for the beauty industry, announced the launch of its sustainable and eco-smart collections and refillable packaging solutions.
Report Coverage
The research report offers an in-depth analysis based on Material, Product Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The cosmetic plastic packaging market is expected to witness steady growth driven by increasing global demand for personal care and beauty products.
- Manufacturers will continue to focus on sustainable and recyclable packaging materials to meet environmental regulations.
- Innovation in refillable and reusable packaging formats will gain strong momentum among premium and mass-market brands.
- Smart packaging technologies, including QR codes and digital labeling, will enhance consumer engagement and brand transparency.
- Lightweight, durable, and travel-friendly packaging designs will remain a top priority for cosmetic brands.
- The rise of e-commerce and direct-to-consumer beauty sales will boost demand for protective and visually appealing packaging.
- Asia-Pacific will continue to lead the market, supported by strong manufacturing bases and expanding beauty industries.
- Collaborations between packaging producers and cosmetic brands will accelerate innovation and design efficiency.
- Bioplastics and post-consumer recycled materials will see increased adoption across product lines.
- Customization and aesthetic differentiation will remain key strategies for maintaining brand competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cosmetic plastic packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cosmetic plastic packaging market projected to grow between 2025 and 2032?
Which Cosmetic plastic packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cosmetic plastic packaging market?
Who are the leading companies in the Cosmetic plastic packaging market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cosmetic Plastic Packaging Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cosmetic Plastic Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 20.85 billion → 2032: USD 29.65 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cosmetic Plastic Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cosmetic Plastic Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cosmetic Plastic Packaging Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cosmetic Plastic Packaging Market Drivers
- 3.3 Cosmetic Plastic Packaging Market Restraints & Challenges
- 3.4 Cosmetic Plastic Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cosmetic Plastic Packaging Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cosmetic Plastic Packaging Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cosmetic Plastic Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cosmetic Plastic Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Cosmetic Plastic Packaging Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Cosmetic Plastic Packaging. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cosmetic Plastic Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cosmetic Plastic Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Cosmetic Plastic Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cosmetic Plastic Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Cosmetic Plastic Packaging
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cosmetic Plastic Packaging Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Cosmetic Plastic Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cosmetic Plastic Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cosmetic Plastic Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cosmetic Plastic Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cosmetic Plastic Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cosmetic Plastic Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cosmetic Plastic Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
