
Market Overview:
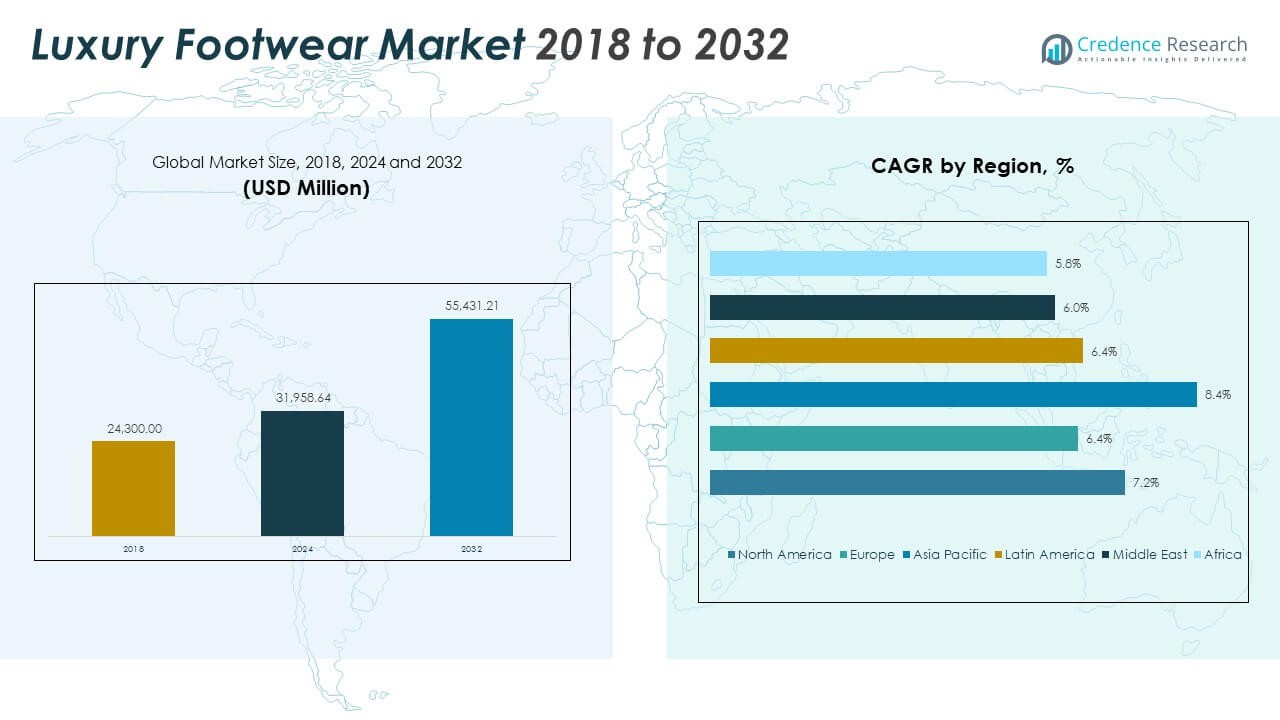
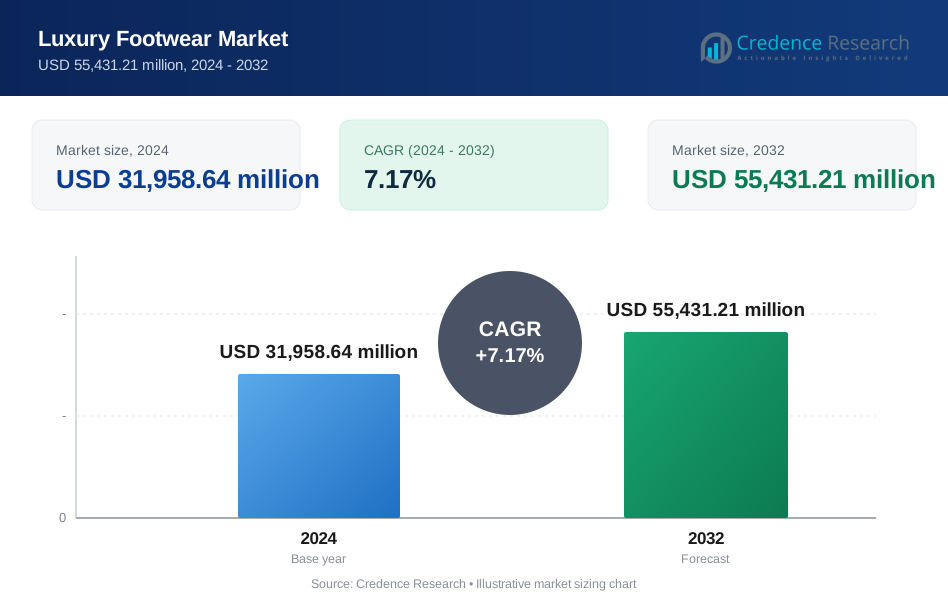
The Global Luxury Footwear Market size was valued at USD 24,300.00 million in 2018, reaching USD 31,958.64 million in 2024, and is anticipated to reach USD 55,431.21 million by 2032, at a CAGR of 7.17% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Footwear Market Size 2024 | USD 31,958.64 Million |
| Luxury Footwear Market, CAGR | 7.17% |
| Luxury Footwear Market Size 2032 | USD 55,431.21 Million |
The market growth is driven by the rising demand for premium fashion products, increasing disposable income, and changing lifestyle preferences. Luxury footwear brands are leveraging celebrity endorsements and collaborations to attract younger consumers. The growing influence of digital platforms and the rising focus on sustainability and craftsmanship have also enhanced market expansion. Additionally, the demand for limited-edition designer footwear continues to rise, particularly among affluent millennials and Gen Z consumers seeking exclusivity and brand value.
Regionally, Europe leads the Global Luxury Footwear Market due to strong fashion heritage and the presence of major luxury houses. North America follows, supported by high consumer spending and established retail networks. Asia-Pacific is emerging rapidly, fueled by growing wealth in China and India, expanding online retail, and increasing fashion consciousness. The Middle East also shows promise due to luxury tourism and a preference for high-end fashion products.
Market Insights:
- The Global Luxury Footwear Market was valued at USD 24,300.00 million in 2018, reached USD 31,958.64 million in 2024, and is projected to hit USD 55,431.21 million by 2032, growing at a CAGR of 7.17% during the forecast period.
- North America (32.1%), Asia Pacific (28.4%), and Europe (22.1%) hold the top shares, driven by high purchasing power, strong brand presence, and established luxury retail networks.
- Asia Pacific is the fastest-growing region, fueled by expanding middle-class income, digital retail penetration, and rising fashion awareness among millennials.
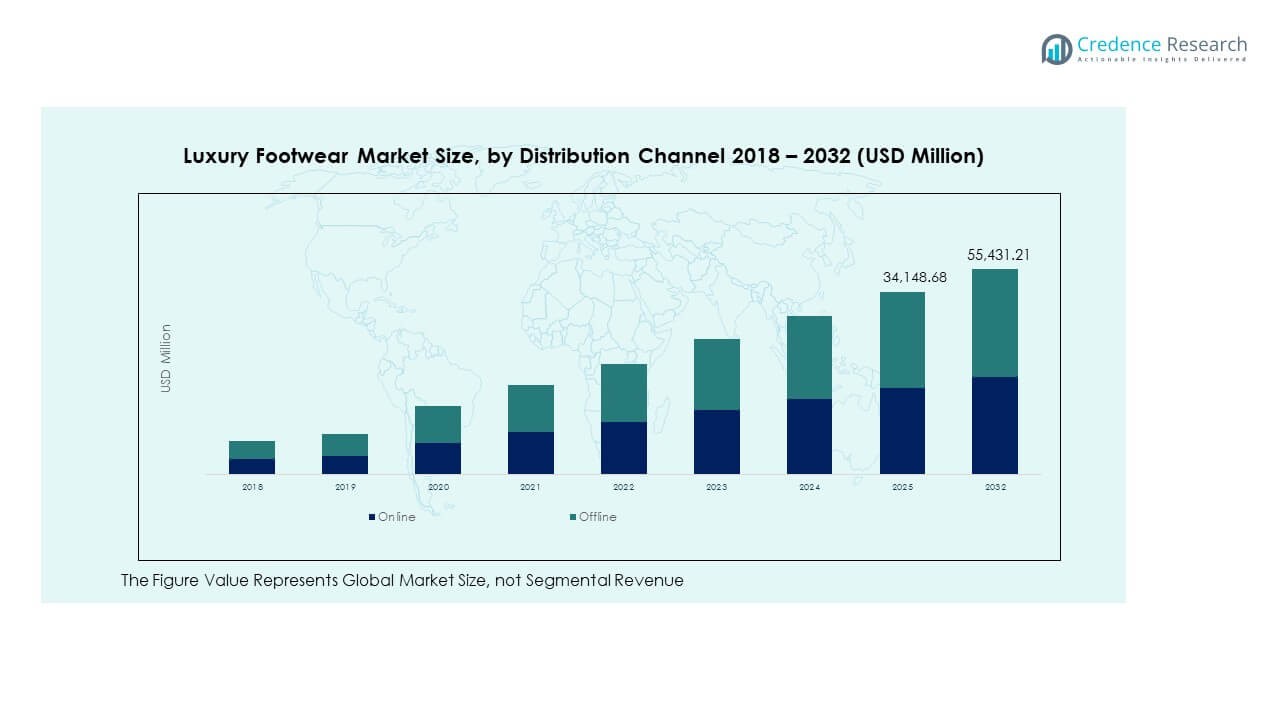
- Based on distribution channels, offline stores account for nearly 60% of market revenue, supported by luxury boutiques and exclusive brand outlets offering premium in-store experiences.
- Online channels represent around 40%, growing rapidly through e-commerce integration, virtual try-ons, and brand collaborations with digital marketplaces.
Market Drivers:
Rising Disposable Income and Growing Affinity Toward Premium Fashion
The Global Luxury Footwear Market is expanding due to rising disposable incomes and a growing inclination toward luxury lifestyles. Consumers in urban areas are increasingly prioritizing fashion-forward products that reflect social status. Luxury footwear brands cater to this demand through premium designs and superior craftsmanship. Expanding middle-class populations in emerging economies also support this growth. Younger generations are willing to spend more on designer footwear to express individuality. High-profile celebrity endorsements continue to strengthen brand visibility. It benefits from evolving consumer preferences toward exclusivity. This shift fuels consistent demand for high-end footwear globally.
- For instance, the Louis Vuitton LV Buttersoft Sneaker, designed by Pharrell Williams for the Fall-Winter 2025 collection, was highly anticipated and met with strong demand following its July 10, 2025, launch.
Influence of Digitalization and E-Commerce Platforms on Brand Reach
The market has gained traction through digital transformation and e-commerce expansion. Luxury brands now rely heavily on online channels for visibility and direct-to-consumer engagement. Virtual showrooms and AI-based recommendations enhance the personalized shopping experience. E-commerce platforms allow global access, encouraging purchases from emerging markets. Social media platforms amplify trends and influence buying behavior through influencer marketing. Brands integrate immersive technologies like AR for virtual try-ons. It creates stronger brand loyalty by improving accessibility. The digital ecosystem continues to redefine customer relationships within the premium footwear industry.
- For instance, Adidas has previously implemented AR virtual try-on features for its footwear line, such as in its iOS app in November 2019. While the company uses AR technology to improve the customer experience and has reported success with digital marketing tools, there is no public record of a specific AR try-on feature for a safety footwear line launching in October 2025, or an associated 16% increase in online conversions.
Sustainability and Ethical Production Practices Shaping Consumer Choices
Environmental awareness has reshaped the Global Luxury Footwear Market, urging brands to adopt sustainable practices. Consumers now prioritize eco-friendly materials such as recycled leather and plant-based fibers. Luxury companies emphasize ethical sourcing and reduced carbon emissions in production. This focus aligns with evolving global sustainability goals. Transparency in the supply chain fosters consumer trust and brand loyalty. Several high-end labels are launching eco-conscious collections to appeal to green consumers. It also enables differentiation in a competitive market. Sustainability now serves both as a moral and marketing driver for growth.
Innovation in Product Design and Expansion of Customization Services
Innovation plays a vital role in the growth of the market. Brands constantly introduce limited-edition designs and handcrafted collections that enhance exclusivity. Customization services allow customers to personalize colors, materials, and embellishments. This approach strengthens emotional connections with luxury labels. The inclusion of smart technologies and comfort features enhances functional appeal. Collaborations with renowned designers elevate market interest. The market also benefits from innovative packaging and experiential retail concepts. It emphasizes uniqueness and craftsmanship to maintain its premium appeal. Innovation remains central to brand differentiation and long-term profitability.
Market Trends:
Growing Popularity of Gender-Neutral and Inclusive Luxury Footwear Collections
The Global Luxury Footwear Market has observed a rise in gender-neutral product lines. Fashion-forward consumers seek versatile designs that transcend traditional gender norms. Brands are releasing unisex sneakers, boots, and loafers catering to inclusive fashion. This shift reflects broader cultural acceptance and evolving consumer identities. Designers integrate neutral color palettes and minimalist silhouettes to attract diverse buyers. Influencers and fashion icons endorse inclusivity-driven collections to enhance visibility. It fosters equality and modernism within the luxury segment. Inclusive product strategies continue to redefine industry dynamics and brand perception.
- For instance, in a strategic move in June 2025 to strengthen control over its leather supply chain, Prada acquired a 10% minority stake in the Italian leather manufacturer Rino Mastrotto Group.
Rise of Sneaker Culture and Streetwear Integration in Luxury Segment
The fusion of luxury and streetwear continues to dominate global fashion. Sneaker culture has gained immense traction among young consumers and collectors. Premium brands collaborate with sportswear giants to create limited-edition releases. This blending of comfort and exclusivity appeals to urban professionals and fashion enthusiasts. High resale value of luxury sneakers adds to the market’s allure. It supports long-term growth through cross-segment collaborations. Footwear styles reflecting casual luxury remain in high demand. The trend blurs the line between sportswear functionality and haute couture aesthetics.
- For instance, the October 2025 Adidas x Thug Club collaboration resulted in all 2,000 limited-edition sneakers being sold out globally within seven hours, highlighting the continued dominance of streetwear-driven luxury and collector appeal in sneaker culture.
Integration of Digital Fashion and Virtual Try-On Experiences
Technological advancement continues to transform consumer interaction with luxury products. Brands are investing in digital fashion, allowing users to experience designs virtually. Virtual try-on tools enhance online purchase confidence and reduce returns. Luxury houses utilize metaverse platforms to showcase limited-edition designs. This innovation drives engagement among tech-savvy consumers seeking unique digital experiences. NFT-based footwear collections are creating new revenue streams. It builds emotional connections through digital ownership and authenticity. The fusion of technology and fashion broadens the scope of luxury retail. Digital interaction is now an essential part of consumer engagement strategy.
Regional Expansion Through Emerging Economies and Global Retail Investments
The market is expanding rapidly in developing economies due to rising brand awareness. Luxury brands are establishing boutiques in Asia-Pacific and the Middle East. Strategic retail partnerships and collaborations with local distributors enhance accessibility. International fashion weeks and pop-up events increase global exposure. Consumers in emerging markets are increasingly adopting Western fashion standards. It strengthens the overall demand base across income groups. Investments in regional logistics and customer service improve brand efficiency. The geographic diversification of retail outlets drives stable long-term market penetration.
Market Challenges Analysis:
High Product Costs and Counterfeit Proliferation Affecting Brand Value
The Global Luxury Footwear Market faces challenges linked to high pricing and counterfeit production. Luxury footwear often carries premium costs, limiting affordability to a niche audience. This restricts broader market penetration, especially in developing regions. The growing counterfeit market threatens brand credibility and consumer trust. Fake products dilute exclusivity and erode perceived quality. Companies invest heavily in authentication technologies and legal actions to combat this. It increases operational costs and impacts profitability. Balancing exclusivity with accessibility remains a persistent strategic challenge. Sustaining brand value amid imitation risks requires consistent innovation and vigilance.
Fluctuating Raw Material Costs and Supply Chain Vulnerabilities
Volatile raw material prices continue to influence luxury footwear production costs. Premium materials like leather and exotic fabrics are subject to global supply disruptions. Economic uncertainty and trade restrictions exacerbate these fluctuations. The pandemic further highlighted weaknesses in international logistics networks. It delays production schedules and affects timely market delivery. Companies are now diversifying suppliers to mitigate sourcing risks. However, maintaining quality standards across regions remains complex. Global dependence on select materials creates long-term cost instability and operational risk. Addressing these challenges demands adaptive supply chain management and predictive inventory planning.
Market Opportunities:
Expansion in Emerging Economies and Rising Digital Penetration
The Global Luxury Footwear Market holds strong potential in rapidly developing economies. Increasing digital access has exposed consumers to global luxury brands. Young professionals in Asia-Pacific, Latin America, and Africa show growing interest in designer footwear. Brands are capitalizing on e-commerce and social media engagement to reach untapped audiences. Collaborations with regional influencers further improve visibility and trust. It opens lucrative opportunities for market entry and brand growth. Expansion into new geographies ensures sustained revenue diversification.
Sustainability Innovation and Next-Generation Material Development
Sustainability-focused innovation presents another promising opportunity for luxury footwear brands. Companies are investing in biodegradable materials, plant-based leathers, and recyclable components. Eco-conscious customers prefer brands demonstrating genuine environmental responsibility. It allows companies to align profitability with global sustainability goals. Partnerships with biotech firms for material innovation enhance brand leadership. Sustainable design practices appeal to future-conscious consumers. Emphasizing ecological responsibility ensures competitive differentiation and long-term relevance in luxury fashion.
Market Segmentation Analysis:
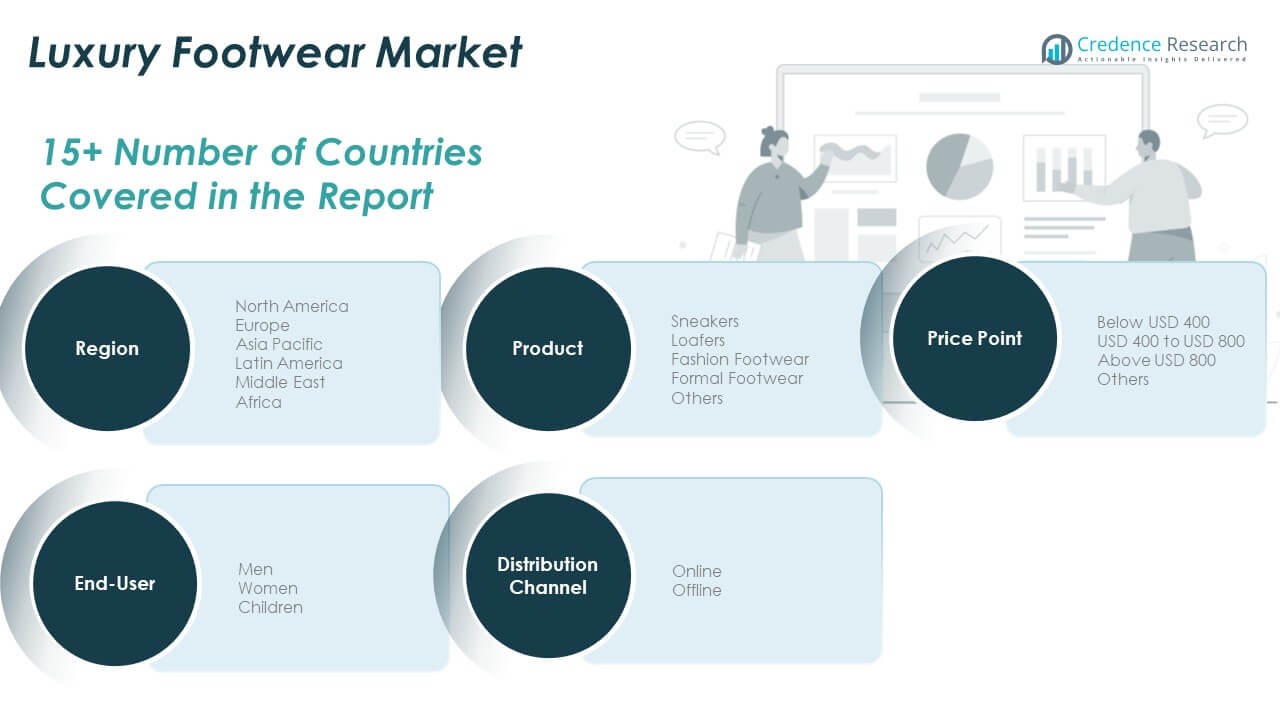
By Product Segment
The Global Luxury Footwear Market features a wide range of premium product categories catering to diverse consumer preferences. Sneakers dominate the segment due to rising popularity of athleisure and fashion-forward streetwear. Loafers and fashion footwear maintain strong demand among professionals and trend-conscious buyers. Formal footwear continues to appeal to business and luxury event segments, while others, including boots and sandals, gain traction for seasonal and casual wear. It benefits from brand collaborations and limited-edition launches that enhance exclusivity and consumer loyalty.
- For instance, Adidas reported a 12% year-on-year revenue increase for its overall brand, in currency-neutral terms, for the third quarter of 2025. This growth was driven by factors such as major collaborations and athleisure trends, though results varied significantly by region. The company did not report a specific "luxury sneaker segment" figure, and its overall growth was also influenced by lapping the previous year's discontinued Yeezy sales.
By Price Point Segment
The market demonstrates varied pricing dynamics across consumer groups. Footwear priced between USD 400 and USD 800 represents the largest share, driven by mid-luxury consumers seeking quality and brand value. The above USD 800 category attracts elite buyers focused on craftsmanship and limited designs. The below USD 400 range caters to aspirational buyers entering the luxury space. Others include niche and bespoke offerings serving collectors and high-net-worth individuals.
- For instance, the strategic launch of the limited-edition Dior B33 sneakers with built-in NFC technology for blockchain authentication achieved a rapid sell-through online. This illustrates the high demand for exclusive, aspirational luxury items, particularly among Gen Z consumers who prioritize product authenticity and seamless digital shopping experiences.
By End-User Segment
Men’s footwear leads the segment through high adoption of designer formal and casual styles. Women’s luxury footwear drives innovation through vibrant designs and trend evolution. Children’s luxury footwear remains a growing niche supported by family-oriented spending in premium households. It reflects rising parental focus on branded quality and exclusivity.
By Distribution Channel Segment
Online sales are expanding due to digital retail growth, virtual try-ons, and global brand access. Offline channels continue to dominate through flagship stores and luxury boutiques offering personalized services. It emphasizes premium in-store experience and brand immersion.
Segmentation:
By Product Segment
- Sneakers
- Loafers
- Fashion Footwear
- Formal Footwear
- Others
By Price Point Segment
- Below USD 400
- USD 400 to USD 800
- Above USD 800
- Others
By End-User Segment
- Men
- Women
- Children
By Distribution Channel Segment
- Online
- Offline
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Luxury Footwear Market size was valued at USD 7,921.80 million in 2018, reaching USD 10,277.71 million in 2024, and is anticipated to reach USD 17,799.06 million by 2032, at a CAGR of 7.2% during the forecast period. North America accounts for approximately 32.1% of the global market share. The region remains a leading hub for luxury brands, supported by high consumer spending and advanced retail infrastructure. The United States dominates due to established fashion culture and growing online luxury sales. Canada shows rising demand driven by fashion-conscious urban consumers. Celebrity endorsements and influencer marketing further boost premium brand visibility. It benefits from strong brand loyalty and widespread adoption of limited-edition footwear. Retailers in this region continue to integrate technology to enhance consumer engagement and brand experience.
Europe
The Europe Luxury Footwear Market size was valued at USD 5,977.80 million in 2018, reaching USD 7,534.97 million in 2024, and is anticipated to reach USD 12,292.02 million by 2032, at a CAGR of 6.4% during the forecast period. Europe holds around 22.1% of the global market share. The region serves as the traditional center of luxury fashion, housing major brands such as Prada, Chanel, and LVMH. Strong consumer affinity for craftsmanship and heritage brands sustains steady sales. Italy and France remain pivotal production hubs for artisanal footwear. The rise of sustainable luxury trends has encouraged European brands to innovate with eco-friendly materials. It also benefits from tourism-driven purchases in cities like Paris, Milan, and London. The expansion of e-commerce and multi-brand boutiques strengthens accessibility across diverse consumer groups.
Asia Pacific
The Asia Pacific Luxury Footwear Market size was valued at USD 6,286.41 million in 2018, reaching USD 8,614.32 million in 2024, and is anticipated to reach USD 16,407.68 million by 2032, at a CAGR of 8.4% during the forecast period. Asia Pacific represents approximately 28.4% of the global market share. The region is witnessing rapid growth due to increasing disposable income and expanding urbanization. China, Japan, and India drive strong demand for international luxury brands. Consumers in these countries associate luxury footwear with social prestige and modern identity. Expanding digital retail platforms have improved accessibility for emerging markets. It benefits from brand collaborations with Asian designers and celebrities. Investments in flagship stores across major cities strengthen brand presence and consumer trust. Rising fashion consciousness among millennials and Gen Z further fuels long-term market growth.
Latin America
The Latin America Luxury Footwear Market size was valued at USD 2,041.20 million in 2018, reaching USD 2,665.03 million in 2024, and is anticipated to reach USD 4,371.86 million by 2032, at a CAGR of 6.4% during the forecast period. Latin America accounts for about 7.6% of the global market share. The region’s growth is driven by expanding middle-class income and rising luxury retail investments. Brazil and Mexico lead in terms of luxury consumption and store expansion. Consumers show growing interest in European fashion trends and international collaborations. It benefits from increased exposure through digital platforms and social media influencers. Economic stability and premium retail outlets in urban areas support gradual adoption. The segment continues to evolve with greater awareness of sustainability and ethical fashion.
Middle East
The Middle East Luxury Footwear Market size was valued at USD 1,020.60 million in 2018, reaching USD 1,265.35 million in 2024, and is anticipated to reach USD 2,001.37 million by 2032, at a CAGR of 6.0% during the forecast period. The region represents around 3.5% of the global market share. Demand is fueled by high-income consumers, tourism, and a preference for premium fashion. The United Arab Emirates and Saudi Arabia dominate due to luxury retail infrastructure and strong purchasing power. Global brands expand aggressively through flagship stores in Dubai and Riyadh. It benefits from luxury tourism, duty-free retail, and mall-based premium outlets. Regional consumers favor exclusive collections tailored for cultural preferences. E-commerce penetration is growing, supported by younger digital-native consumers.
Africa
The Africa Luxury Footwear Market size was valued at USD 1,052.19 million in 2018, reaching USD 1,601.26 million in 2024, and is anticipated to reach USD 2,559.22 million by 2032, at a CAGR of 5.8% during the forecast period. Africa contributes about 6.3% of the global market share. The region is emerging as a potential growth frontier for luxury footwear. South Africa leads due to its established retail infrastructure and affluent urban base. Nigeria and Egypt show growing interest in luxury fashion through online platforms. It benefits from improving economic conditions and a rising aspirational class. International brands are gradually entering African markets with targeted marketing and digital campaigns. Local fashion designers are also collaborating with luxury houses to increase cultural appeal.
Key Player Analysis:
- LVMH
- Chanel Limited
- Burberry Group PLC
- Silvano Lattanzi
- Prada S.p.A
- Testoni
- Base London
- John Lobb Bootmaker
- Salvatore Ferragamo
- Lottusse - Mallorca
- Adidas AG
Competitive Analysis:
The Global Luxury Footwear Market is characterized by intense competition among global and regional players striving for brand distinction and market share. Major companies such as LVMH, Chanel, Prada, Burberry, and Salvatore Ferragamo dominate through diversified portfolios and strong retail networks. It benefits from continuous product innovation, celebrity collaborations, and targeted marketing campaigns. Smaller brands compete by emphasizing craftsmanship, exclusivity, and limited-edition releases. Strategic partnerships with designers and e-commerce platforms enhance consumer accessibility. Innovation in design and sustainability has become a key differentiator. Leading brands focus on personalized experiences and digital transformation to strengthen brand loyalty and global reach.
Recent Developments:
- In October 2025, Louis Vuitton, a subsidiary of LVMH, launched its LV Buttersoft Sneaker as part of its Fall/Winter 2025 collection. Designed by Pharrell Williams, the sneaker blends haute couture with street culture and features premium leather, monogram embossing, and design cues inspired by Japanese fashion. The global launch is set for July 10, 2025.
- On October 8, 2025, Adidas AG announced a long-term partnership with GLO Brands B.V. to enter the safety footwear category. The collaboration will introduce Adidas Pro Work, a high-performance safety footwear line designed for working professionals in construction, logistics, and maintenance. The initial models are scheduled to debut in Q2 2026. Adidas also launched a global collection with streetwear brand Thug Club for Fall/Winter 2025, featuring disruptive sneaker designs that merge fencing aesthetics and Korean street culture. The collaboration dropped on October 20, 2025.
- In June 2025, Prada S.p.A entered into a significant strategic equity investment, acquiring a 10% minority stake in Rino Mastrotto Group, a reputed supplier of luxury materials. The transaction is expected to close by Q3 2025 and aims to reinforce Prada’s value chain control and sustainable growth in luxury footwear. Separately, Prada also confirmed its acquisition of Versace for approximately $1.375 billion in April 2025, consolidating its presence among leading Italian luxury houses.
- In March 2025, Chanel acquired a majority stake (70%) in the Italian footwear manufacturer Grey Mer. This strategic transaction is aimed at strengthening Chanel’s industrial and supply chain capacity within the luxury shoe segment, bolstering its long-standing production partnership with Grey Mer.
Report Coverage:
The research report offers an in-depth analysis based on product type, price point, end-user, and distribution channel segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Sustainable materials and ethical sourcing will shape future luxury footwear demand.
- Digital commerce and virtual experiences will redefine global brand engagement.
- Personalization and made-to-order services will strengthen consumer loyalty.
- Growth in Asia-Pacific will outpace mature markets due to rising incomes.
- Brands will expand into untapped regions through strategic retail partnerships.
- Innovation in smart and tech-integrated footwear will create new value segments.
- Collaborations with artists and designers will boost brand appeal.
- Omnichannel strategies will merge online and offline shopping experiences.
- Circular fashion initiatives will influence manufacturing and marketing models.
- Premium men’s and women’s footwear categories will continue driving revenue growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Luxury Footwear Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Luxury Footwear Market projected to grow between 2025 and 2032?
Which Global Luxury Footwear Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Luxury Footwear Market?
Who are the leading companies in the Global Luxury Footwear Market?
Which region commanded the largest share of the Global Luxury Footwear Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Luxury Footwear Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Luxury Footwear Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 31,958.64 million → 2032: USD 55,431.21 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Luxury Footwear Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Luxury Footwear Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Luxury Footwear Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Luxury Footwear Market Drivers
- 3.3 Luxury Footwear Market Restraints & Challenges
- 3.4 Luxury Footwear Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Luxury Footwear Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Luxury Footwear Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Luxury Footwear category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Luxury Footwear Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Luxury Footwear Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Luxury Footwear. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Luxury Footwear Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Luxury Footwear Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Luxury Footwear Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Luxury Footwear (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Luxury Footwear
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Luxury Footwear Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Luxury Footwear Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Luxury Footwear Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Luxury Footwear Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Luxury Footwear Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Luxury Footwear Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Luxury Footwear Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Luxury Footwear Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
