
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mexico Industrial Catalyst Market Size 2024 | USD 795.79 million |
| Mexico Industrial Catalyst Market, CAGR | 4.8% |
| Mexico Industrial Catalyst Market Size 2032 | USD 1158.32 million |
Market Overview:
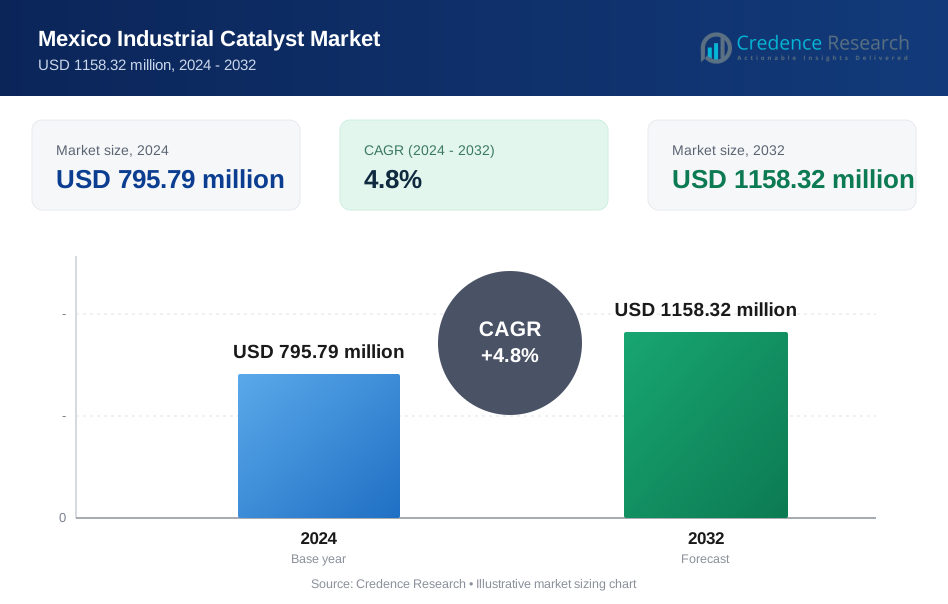
The Mexico Industrial Catalyst Market is projected to grow from USD 795.79 million in 2024 to an estimated USD 1158.32 million by 2032, with a compound annual growth rate (CAGR) of 4.8% from 2024 to 2032.
The growth of the Mexico Industrial Catalyst Market is driven by several key factors, including the trend of nearshoring and foreign direct investment (FDI), which has significantly boosted the country’s manufacturing sector. With increasing geopolitical tensions and rising production costs in other regions, companies are shifting their operations closer to major markets, and Mexico has emerged as a preferred location for these businesses. This shift has led to greater FDI, particularly in the manufacturing and automotive sectors, which require advanced catalytic technologies for emission control and fuel efficiency. Additionally, the growth of Mexico's automotive industry, driven by investments from global players like Tesla and BYD, has fueled the demand for industrial catalysts used in vehicle emission systems. The expansion of the petrochemical industry, supported by both domestic consumption and export growth, also boosts the market for catalysts essential for refining and chemical production. Furthermore, environmental regulations pushing for cleaner production processes and sustainability have encouraged the adoption of advanced catalysts, which are critical for reducing emissions and improving process efficiency.
Regionally, Mexico’s industrial catalyst market benefits from a well-established manufacturing presence in several key areas. The northern states, particularly those near the U.S. border, are industrial hubs, attracting investment from a wide range of industries, including automotive and electronics. Cities like Monterrey are central to this development. The Bajío region, encompassing parts of Guanajuato, Querétaro, and San Luis Potosí, has emerged as a major automotive manufacturing center, further stimulating demand for catalysts. The central and southern regions, such as Puebla and Veracruz, are vital for the country’s petrochemical production, with their proximity to ports and raw material sources supporting the growth of chemical manufacturing. Together, these regions create a dynamic environment for the growth of the industrial catalyst market in Mexico.
Market Insights:
- The Mexico Industrial Catalyst Market is expected to grow from USD 795.79 million in 2024 to USD 1158.32 million by 2032, with a CAGR of 4.8%.
- The global industrial catalyst market is projected to grow from USD 31.56 billion in 2024 to USD 51.15 billion by 2032, with a CAGR of 6.22% from 2024 to 2032.
- Nearshoring and increasing foreign direct investment (FDI) are driving Mexico’s growth, positioning the country as a manufacturing hub for global industries, especially automotive and chemicals.
- Mexico's automotive sector, including major players like Tesla and BYD, continues to fuel the demand for catalysts used in emission control and fuel efficiency technologies.
- The expansion of the petrochemical industry, particularly for refining and chemical production, has further increased the demand for industrial catalysts in Mexico.
- Stricter environmental regulations and a global focus on sustainability are pushing industries in Mexico to adopt advanced catalytic technologies that reduce emissions and improve process efficiency.
- High initial investment costs for advanced catalyst technologies pose a challenge, particularly for small and medium-sized enterprises (SMEs) in Mexico.
- Mexico’s industrial catalyst market benefits from its regional distribution, with northern and central Mexico leading in automotive and petrochemical industries, driving the demand for catalysts.
Report Scope
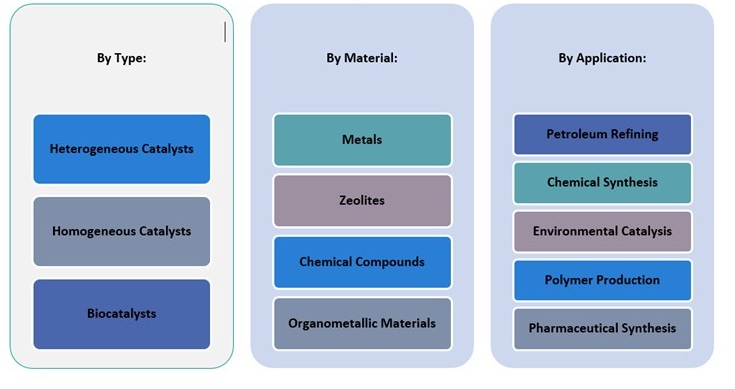
This report segments the Mexico Industrial Catalyst Market as follow
Market Drivers:
Nearshoring and Foreign Direct Investment (FDI)
The shift towards nearshoring has emerged as a key driver for the Mexico Industrial Catalyst Market. As businesses seek to reduce production costs and mitigate risks associated with geopolitical uncertainties, Mexico has become an attractive destination for manufacturing operations. For instance, in 2024, Mexico registered a record $31 billion in Foreign Direct Investment (FDI), with over half of this investment directed towards manufacturing sectors such as automotive, electronics, and chemicals. The country's proximity to the United States, along with its favorable trade agreements such as the USMCA, positions it as an ideal location for industries looking to optimize their supply chains. As a result, Mexico has witnessed a surge in foreign direct investment (FDI), particularly from companies in sectors like automotive, electronics, and chemicals. These industries rely on industrial catalysts to improve manufacturing processes, enhance product quality, and reduce emissions, thus driving the demand for advanced catalytic technologies.
Growth of the Automotive Industry
Mexico's automotive sector plays a significant role in the country’s economic growth and has become one of the leading drivers of the industrial catalyst market. The country has established itself as a major manufacturing hub for global automakers, including companies like Ford, General Motors, and Volkswagen, which have set up large-scale production facilities. Additionally, the rise of electric vehicle (EV) manufacturing, exemplified by companies such as Tesla and BYD, further fuels the demand for catalysts used in emissions control systems and fuel efficiency technologies. The automotive industry’s reliance on industrial catalysts, particularly for vehicle emission reduction, will continue to be a major factor in the growth of the market, especially as stricter environmental regulations are enforced worldwide.
Expansion of the Petrochemical Industry
The petrochemical industry is another vital driver for the industrial catalyst market in Mexico. The country has become a significant player in the global petrochemical supply chain, with increased production of refined petroleum products, plastics, and chemicals. For instance, in March 2025, Pemex's six refineries processed over 1 million barrels per day of crude oil for the first time in eight years, boosting gasoline and diesel output by 32% year-over-year. Industrial catalysts are essential in refining processes, helping to improve the yield and efficiency of production while ensuring compliance with environmental regulations. Mexico’s growing petrochemical industry, bolstered by both domestic demand and export opportunities, has heightened the need for advanced catalysts. As energy consumption and chemical production continue to rise, the demand for catalysts that optimize these processes is expected to grow, making it a critical factor for market expansion.
Environmental Regulations and Sustainability Initiatives
Stricter environmental regulations and the global push for sustainability are powerful drivers of innovation in the Mexico Industrial Catalyst Market. As environmental concerns continue to escalate, industries in Mexico are increasingly turning to advanced catalytic technologies to meet international emission standards and reduce their carbon footprint. Industrial catalysts play a crucial role in facilitating cleaner production processes by reducing pollutants and enhancing the overall efficiency of operations. This growing focus on sustainability aligns with both domestic and global objectives for cleaner, more environmentally responsible manufacturing practices. As the demand for sustainable solutions intensifies, the industrial catalyst market in Mexico is expected to see continued growth in response to these regulatory pressures and sustainability initiatives.
Market Trends:
Technological Advancements in Catalyst Innovation
The Mexico Industrial Catalyst Market is experiencing a notable trend toward the development of advanced catalysts that improve process efficiency and sustainability. Technological advancements are driving the evolution of catalysts, particularly in the areas of selectivity, stability, and activity. With the ongoing demand for greener manufacturing processes, researchers and manufacturers are focused on creating catalysts that reduce harmful emissions, minimize energy consumption, and increase overall process yield. These innovations are not only improving performance but also extending the lifespan of catalysts, reducing the need for frequent replacements, and contributing to more cost-effective production. As industries continue to adopt these new catalyst technologies, the market for industrial catalysts in Mexico is likely to expand further.
Shift Toward Green Catalysts and Sustainability
A growing trend in the Mexico Industrial Catalyst Market is the increasing adoption of green catalysts designed to support environmentally friendly processes. As sustainability becomes a core focus for companies worldwide, Mexico is following suit by integrating greener catalytic solutions into its industrial sectors. Green catalysts, which are designed to minimize environmental impact, are gaining traction due to their ability to reduce harmful emissions and improve the energy efficiency of industrial processes. Ecovyst, for example, collaborates with leading chemical companies to develop catalysts that enhance sustainability by reducing harmful emissions and improving energy efficiency. This shift is particularly evident in the chemical and automotive sectors, where stricter environmental regulations are pushing companies to adopt sustainable practices. The emphasis on green chemistry and sustainable production processes is driving the demand for catalysts that promote eco-friendly outcomes, and this trend is expected to continue in Mexico.
Growth of Bio-Based Catalysts
The adoption of bio-based catalysts, derived from renewable sources such as plants, enzymes, and microorganisms, is gaining traction in Mexico’s industrial catalyst market. These catalysts are increasingly being utilized in industries such as chemicals, pharmaceuticals, and biofuels due to their environmentally friendly and cost-effective nature. For instance, manufacturers are investing heavily in the development of customized biocatalysts to meet specific production needs while maintaining product integrity. In Mexico’s chemical industry, bio-based catalysts are playing a crucial role in improving sustainability and efficiency in production processes. The availability of biomass feedstock and strategic alliances with raw material processors further support the growth of bio-based platform chemicals
Integration of Artificial Intelligence (AI) and Automation
Artificial intelligence (AI) and automation technologies are also influencing trends in the Mexico Industrial Catalyst Market. The integration of AI into catalyst design and production is enabling more precise and efficient development of catalytic materials. AI-driven algorithms are being used to predict the behavior of catalysts under various conditions, optimize their performance, and accelerate the discovery of new catalytic compounds. Additionally, automation in catalyst manufacturing processes is improving production efficiency and consistency, reducing human error, and increasing overall productivity. As AI and automation technologies continue to advance, their role in the Mexico Industrial Catalyst Market is expected to grow, contributing to the ongoing optimization of industrial processes and the development of next-generation catalysts.
Market Challenges Analysis:
High Initial Investment Costs
One of the primary challenges facing the Mexico Industrial Catalyst Market is the high initial investment required for advanced catalyst technologies. The development, manufacturing, and implementation of state-of-the-art catalysts involve significant capital expenditure. This includes costs associated with research and development, specialized manufacturing equipment, and the installation of advanced systems. For many companies, especially small and medium-sized enterprises (SMEs), these high upfront costs can be a significant barrier to adopting newer, more efficient catalytic technologies. Despite the long-term benefits, the initial financial outlay can deter businesses from investing in these solutions, particularly in industries with tight profit margins.
Shortage of Skilled Labor and Technical Expertise
The adoption and optimal use of advanced industrial catalysts require a high level of technical expertise. However, there is a shortage of skilled professionals in Mexico who are proficient in catalyst design, development, and maintenance. This skills gap limits the ability of many companies to fully leverage the potential of catalytic technologies. A lack of technical training programs and a shortage of qualified professionals in the country can slow the adoption of innovative catalytic solutions and hinder overall market growth. Companies are often forced to rely on external expertise, which can increase operational costs and lead to delays in implementing new technologies.
Regulatory and Environmental Compliance Challenges
Stricter environmental regulations in Mexico drive demand for cleaner industrial processes but also pose compliance challenges. For example, companies must adhere to laws such as the General Law of Ecological Balance and Environmental Protection (LGEEPA), which mandates sustainable development practices. Compliance requires continuous investment in catalyst technologies that meet evolving standards for emissions control and waste management. Businesses operating maquiladoras must navigate complex permitting processes issued by SEMARNAT (Secretariat of Environment and Natural Resources). Additionally, regulatory variations across states add complexity for companies operating in multiple locations, increasing costs and operational difficulties
Fluctuating Raw Material Prices
The prices of raw materials used in catalyst production, such as precious metals and chemicals, can fluctuate significantly due to global supply chain disruptions, geopolitical tensions, or changes in demand. These price fluctuations can impact the cost of manufacturing industrial catalysts, leading to increased prices for end-users. In industries where cost control is crucial, these rising material costs can make it difficult for companies to adopt or upgrade catalyst technologies without affecting their profitability.
Market Opportunities:
The Mexico Industrial Catalyst Market presents significant opportunities for growth driven by several factors. One of the key opportunities lies in the country’s rapidly growing manufacturing and automotive industries, which are major consumers of industrial catalysts. As global automakers continue to invest in Mexico, the demand for catalysts used in emissions control and fuel efficiency technologies is expected to rise. Additionally, the expansion of Mexico’s petrochemical and chemical sectors provides a strong market for catalysts that improve production efficiency and reduce environmental impact. With a focus on cleaner production processes, industries are increasingly turning to advanced catalytic solutions that align with sustainability goals and environmental regulations. This trend presents a valuable opportunity for manufacturers of industrial catalysts to introduce innovative, high-performance products tailored to Mexico's industrial needs.
Another emerging opportunity in the Mexico Industrial Catalyst Market lies in the adoption of bio-based catalysts and green technologies. With sustainability becoming a core focus across various industries, the demand for environmentally friendly solutions is growing. Mexico’s chemical and pharmaceutical sectors are particularly well-positioned to adopt bio-based catalysts, which offer renewable alternatives to traditional catalytic processes. Additionally, the integration of artificial intelligence and automation in catalyst design and manufacturing presents a unique opportunity to enhance product development and optimize industrial processes. As Mexico continues to align with global sustainability trends and advanced technological solutions, the market for industrial catalysts is expected to witness substantial growth, offering businesses new avenues for expansion and innovation.
Market Segmentation Analysis:
The Mexico Industrial Catalyst Market is segmented based on type, application, and material, each of which plays a crucial role in the overall market dynamics.
By Type Segment The market is primarily divided into heterogeneous catalysts, homogeneous catalysts, and biocatalysts. Heterogeneous catalysts dominate the market due to their wide use in processes such as petroleum refining and chemical synthesis, where solid catalysts interact with liquid or gas reactants. Homogeneous catalysts are primarily used in chemical reactions in the pharmaceutical and fine chemicals sectors, where high selectivity and efficiency are required. Biocatalysts, derived from biological organisms, are gaining traction in industries such as pharmaceuticals and environmental catalysis, driven by the growing demand for sustainable and eco-friendly solutions.
By Application Segment The Mexico Industrial Catalyst Market sees significant demand across various applications. Petroleum refining remains the largest segment, driven by the country's well-established oil and gas industry. Catalysts are critical in refining processes such as cracking, hydroprocessing, and reforming. Chemical synthesis is another key segment, where catalysts play a crucial role in producing chemicals and materials used across numerous industries. Environmental catalysis, focused on reducing emissions and improving energy efficiency, is seeing increasing demand as global and local regulatory pressures for cleaner production intensify. Polymer production and pharmaceutical synthesis are also critical sectors, with catalysts being essential in creating specialized polymers and active pharmaceutical ingredients.
By Material Segment The materials used in industrial catalysts include metals, zeolites, chemical compounds, and organometallic materials. Metals, particularly precious metals such as platinum and palladium, are widely used in catalysts for automotive and chemical applications. Zeolites are primarily used in petroleum refining and chemical synthesis due to their excellent catalytic properties. Chemical compounds and organometallic materials are increasingly being utilized in specialized applications like pharmaceutical synthesis and polymer production, offering improved reaction selectivity and efficiency.
Segmentation:
By Type Segment
- Heterogeneous Catalysts
- Homogeneous Catalysts
- Biocatalysts
By Application Segment
- Petroleum Refining
- Chemical Synthesis
- Environmental Catalysis
- Polymer Production
- Pharmaceutical Synthesis
By Material Segment
- Metals
- Zeolites
- Chemical Compounds
- Organometallic Materials
Regional Analysis:
The Mexico Industrial Catalyst Market exhibits regional variations driven by the concentration of industrial activity, infrastructure, and demand for catalytic technologies in various sectors. These regions differ in the level of market penetration and growth potential, with the major contributors being the northern, central, and southern regions of Mexico.
Northern Mexico
Northern Mexico, particularly regions like Nuevo León and Baja California, holds the largest market share in the industrial catalyst market. This area benefits from its proximity to the U.S. border, making it a critical hub for manufacturing and assembly plants, especially in the automotive and electronics sectors. Monterrey, the capital of Nuevo León, is one of the most prominent industrial centers in Mexico, attracting significant foreign direct investment (FDI). Automotive manufacturers such as General Motors, Ford, and Tesla have established plants here, driving demand for catalysts used in emission control systems and fuel efficiency technologies. Northern Mexico accounts for an estimated 40-45% of the total market share, owing to the concentration of key industries that rely heavily on industrial catalysts for their operations.
Central Mexico
Central Mexico, including regions such as Guanajuato, Querétaro, and San Luis Potosí, is another key market for industrial catalysts, especially driven by the growth of the automotive and chemical industries. The Bajío region, in particular, has become a major automotive manufacturing zone, supporting Mexico's position as a leader in vehicle production. Additionally, central Mexico hosts petrochemical plants and chemical processing industries, which rely on catalysts for refining and chemical synthesis processes. The region is expected to hold a market share of approximately 30-35%, fueled by both automotive manufacturing and petrochemical production.
Southern Mexico
Southern Mexico, including states like Veracruz and Puebla, also contributes to the industrial catalyst market, albeit to a lesser extent than northern and central regions. Veracruz is a critical area for petrochemical production due to its strategic location near the Gulf of Mexico, which provides access to raw materials and export markets. Puebla, known for its automotive manufacturing, also plays a role in the demand for industrial catalysts. However, the market share in this region is estimated to be around 20-25%, with the majority of catalyst demand stemming from the petrochemical industry and automotive sectors.
Yucatán Peninsula and Other Regions
The Yucatán Peninsula, with its growing chemical production facilities, represents a smaller but emerging market segment. The region is likely to see increased demand for industrial catalysts as infrastructure and manufacturing capabilities expand. Other regions in Mexico, though not as industrially developed, are beginning to see gradual adoption of catalytic technologies as industries such as agriculture, food processing, and pharmaceuticals expand.
Key Player Analysis:
- BASF SE
- Johnson Matthey
- Albemarle Corporation
- ExxonMobil Chemical Company
- W. R. Grace & Co.
- Dow Inc.
- Honeywell UOP
- Chevron Phillips Chemical Company
- PQ Corporation
- Arkema Inc.
Competitive Analysis:
The Mexico Industrial Catalyst Market is characterized by a competitive landscape with both domestic and international players driving innovation and market growth. Key global catalyst manufacturers, such as BASF, Clariant, and Johnson Matthey, have established a strong presence in the country, providing a wide range of catalyst solutions across various industries, including petroleum refining, chemical synthesis, and automotive. These companies benefit from their advanced research and development capabilities, extensive distribution networks, and strong customer relationships. Local manufacturers and suppliers, including Grupo Idesa and Química del Rey, also play a significant role in the market, particularly in the petrochemical sector. These companies are increasingly focusing on sustainability and cost-effective solutions to remain competitive. Additionally, the market is witnessing increased collaboration between industry players and research institutions to develop new catalytic technologies that meet environmental regulations and optimize industrial processes. The growing demand for green catalysts and sustainable solutions is creating new opportunities for both global and local market participants.
Recent Developments:
- In December 2024, BASF inaugurated its new Catalyst Development and Solids Processing Center in Ludwigshafen, Germany. This state-of-the-art facility aims to accelerate the development of innovative catalyst and process technologies, serving as a hub for pilot-scale synthesis of chemical catalysts. The center is equipped with cutting-edge process equipment, enabling faster and more focused R&D activities essential for the green transformation.
- In Feb, 2025, Johnson Matthey PLC announced a partnership with Bosch to develop catalyst-coated membranes (CCMs) for fuel cell stacks. These CCMs will be integrated into Bosch's fuel cell power modules for commercial vehicles, promoting zero-emission hydrogen technology. The collaboration focuses on advancing cleaner mobility solutions and energy generation.
- In March 2025, ExxonMobil Chemical Companyshowcased its Signature Polymers brand at PLASTIMAGEN MEXICO 2025 in Mexico City. The company highlighted advanced solutions for mechanical and chemical recycling, including its Vistamaxx™ performance polymers and Exxtend™ technology, which support the circular economy by enabling the incorporation of recycled content into high-performance plastics
Market Concentration & Characteristics:
The Mexico Industrial Catalyst Market is moderately concentrated, with a few large multinational players dominating the industry alongside regional and local suppliers. Global companies such as BASF, Clariant, and Johnson Matthey lead the market, leveraging their extensive R&D capabilities, established product portfolios, and global supply chains. These companies hold a significant share of the market, particularly in high-demand sectors like petroleum refining and automotive manufacturing. However, local players such as Grupo Idesa and Química del Rey also contribute notably to the market, especially in the petrochemical and chemical synthesis segments. These companies tend to focus on cost-effective, region-specific catalyst solutions that cater to the unique needs of Mexican industries. The market is characterized by high competition, driven by technological advancements, cost pressures, and increasing demand for sustainable and eco-friendly catalytic solutions. As environmental regulations tighten, the market is shifting toward innovative and greener catalysts, creating opportunities for both established and emerging players.
Report Coverage:
The research report offers an in-depth analysis based on Type Segment, Application Segment and Material Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Mexico Industrial Catalyst Market is expected to see steady growth driven by increased foreign investment in manufacturing and automotive sectors.
- Stricter environmental regulations will push industries toward greener and more sustainable catalytic solutions.
- The automotive industry's expansion, particularly electric vehicle production, will boost demand for advanced emission control catalysts.
- The petrochemical industry will continue to be a major driver, with catalysts playing a vital role in refining and chemical production.
- The growing adoption of bio-based catalysts will support Mexico’s shift toward more sustainable industrial practices.
- Technological advancements in catalyst design and material composition will enhance efficiency and reduce production costs.
- Collaboration between global manufacturers and local suppliers will strengthen the market’s competitive landscape.
- Regional market disparities will persist, with northern and central Mexico leading growth due to automotive and petrochemical hubs.
- Investment in AI and automation technologies will optimize catalyst manufacturing and accelerate the development of new solutions.
- Mexico’s position as a nearshoring destination will further increase the demand for industrial catalysts, particularly in the automotive and electronics sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mexico Industrial Catalyst Market?
What factors are driving the growth of the Mexico Industrial Catalyst Market?
What are some challenges faced by the Mexico Industrial Catalyst Market?
Who are the major players in the Mexico Industrial Catalyst Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mexico Industrial Catalyst Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mexico Industrial Catalyst Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 795.79 million → 2032: USD 1158.32 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mexico Industrial Catalyst Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mexico Industrial Catalyst Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mexico Industrial Catalyst Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mexico Industrial Catalyst Market Drivers
- 3.3 Mexico Industrial Catalyst Market Restraints & Challenges
- 3.4 Mexico Industrial Catalyst Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mexico Industrial Catalyst Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mexico Industrial Catalyst Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mexico Industrial Catalyst category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mexico Industrial Catalyst Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mexico Industrial Catalyst Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mexico Industrial Catalyst market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mexico Industrial Catalyst Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mexico Industrial Catalyst Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mexico Industrial Catalyst Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mexico Industrial Catalyst (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mexico Industrial Catalyst Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mexico Industrial Catalyst Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mexico Industrial Catalyst Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mexico Industrial Catalyst Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mexico Industrial Catalyst Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mexico Industrial Catalyst Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mexico Industrial Catalyst Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mexico Industrial Catalyst Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mexico Industrial Catalyst Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer