
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Managed Database Services Market Size 2024 | USD 347912 Million |
| Managed Database Services Market, CAGR | 13.1% |
| Managed Database Services Market Size 2032 | USD 931473 Million |
Market Overview:
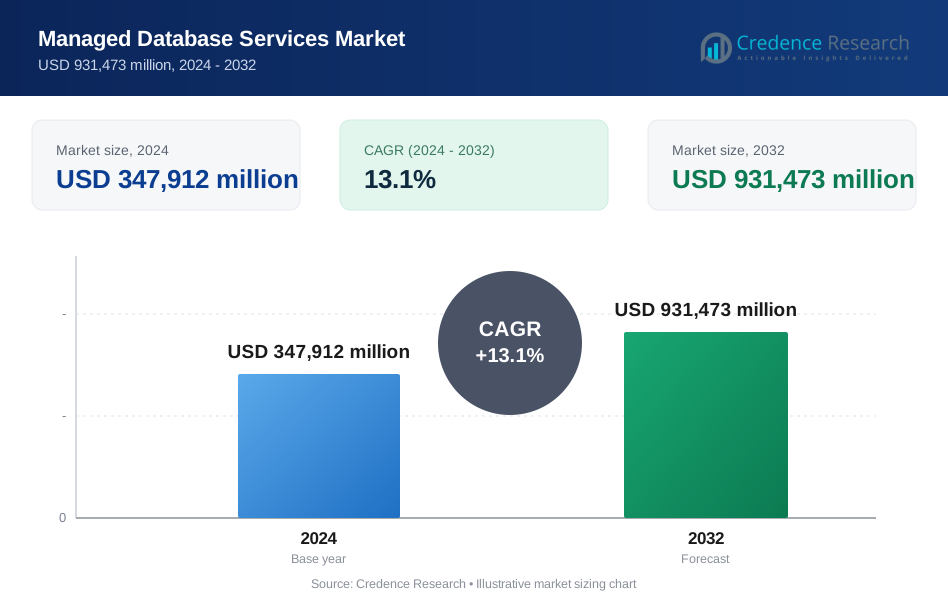
Managed Database Services Market size was valued at USD 347912 million in 2024 and is anticipated to reach USD 931473 million by 2032, at a CAGR of 13.1% during the forecast period (2024-2032).
Key drivers fueling market expansion include the growing reliance on big data analytics and the surge in digital transformation initiatives across various industries. Enterprises are generating vast amounts of data, necessitating advanced management solutions that offer high efficiency and minimal downtime. The growing adoption of Database-as-a-Service (DBaaS) is streamlining IT operations and reducing infrastructure complexity. The increasing adoption of hybrid and multi-cloud strategies has also heightened demand for managed database services, allowing organizations to optimize performance while ensuring data redundancy and security. Cybersecurity threats and the need for continuous database monitoring are further pushing businesses toward managed database solutions. Additionally, regulatory compliance requirements across sectors such as finance, healthcare, and retail are compelling businesses to invest in managed database solutions that provide automated updates and security patches, ensuring adherence to evolving industry standards.
Regionally, North America leads the market, driven by early adoption of cloud computing, significant investments in database automation, and the presence of key market players. The region benefits from well-established IT infrastructure and a strong emphasis on cybersecurity compliance. Europe is witnessing steady growth due to stringent data protection regulations and the increasing adoption of cloud infrastructure by enterprises. The General Data Protection Regulation (GDPR) plays a crucial role in driving the demand for managed database security and compliance services. The Asia-Pacific region is expected to register the highest growth rate, fueled by rapid digitalization, expanding IT infrastructure, and the increasing number of startups leveraging managed database services. The region's growing e-commerce sector and the need for scalable cloud solutions are key factors propelling demand. Emerging economies in Latin America and the Middle East & Africa are also adopting these solutions, particularly in industries such as finance, telecommunications, and e-commerce, contributing to overall market expansion.
Market Insights:
- The market was valued at USD 347,912 million in 2024 and is projected to reach USD 931,473 million by 2032, growing at a CAGR of 13.1% due to increasing adoption across industries.
- The rise of big data analytics and the growth of digital transformation initiatives are driving demand for advanced managed database services that offer high efficiency and minimal downtime.
- Database-as-a-Service (DBaaS) is gaining traction as businesses seek cost-effective, scalable, and automated solutions for database management.
- Hybrid and multi-cloud database strategies are becoming the preferred choice for enterprises to optimize performance, enhance security, and ensure data redundancy.
- Cybersecurity threats and data compliance regulations are compelling organizations to invest in real-time threat detection, encryption, and automated compliance monitoring.
- North America leads the market with a 38% share, driven by strong cloud adoption, cybersecurity compliance, and the presence of major technology players.
- Asia-Pacific is the fastest-growing region, fueled by rapid digitalization, cloud investments, and a booming e-commerce sector, increasing the need for scalable database solutions.
Market Drivers:
Increasing Adoption of Cloud-Based Database Solutions:
The growing reliance on cloud computing is a primary driver for the managed database services market. Organizations are shifting from traditional on-premises databases to cloud-based solutions to enhance scalability, improve accessibility, and reduce infrastructure costs. For instance, the United States Census Bureau has adopted cloud-based database solutions to manage and analyze vast amounts of demographic data, enabling more efficient data collection and dissemination processes. Cloud-based database services offer automated backup, disaster recovery, and real-time synchronization, ensuring business continuity and operational efficiency. As enterprises continue digital transformation initiatives, the need for robust and managed database services is increasing across industries such as finance, healthcare, and retail.
Growing Demand for Big Data Analytics and AI Integration:
The exponential growth of data generation has heightened the demand for advanced database management solutions. Businesses are leveraging big data analytics and artificial intelligence to extract actionable insights, optimize processes, and improve decision-making. For instance, Walmart has successfully implemented big data analytics and AI integration in its managed database services to enhance inventory management and personalize customer experiences across its global retail operations. Managed database services provide seamless integration with AI-driven analytics tools, enabling real-time data processing and predictive modeling. The increasing adoption of AI-powered automation in database management is also reducing the need for manual intervention, minimizing errors, and improving efficiency in data handling.
Rising Concerns Over Data Security and Compliance:
Stringent data protection regulations and the rising frequency of cyber threats are driving businesses to adopt managed database services. Industries dealing with sensitive information, such as banking, healthcare, and government sectors, require databases that comply with regulatory frameworks like GDPR, HIPAA, and CCPA. For instance, the National Health Service (NHS) in the United Kingdom has implemented managed database services with advanced security features to protect patient data and ensure compliance with healthcare regulations. Managed database providers offer advanced security features, including encryption, access control, and real-time threat monitoring, ensuring data confidentiality and integrity. As businesses prioritize compliance and risk mitigation, the demand for managed database solutions with robust security features is growing.
Expansion of Multi-Cloud and Hybrid Cloud Strategies:
Enterprises are increasingly adopting multi-cloud and hybrid cloud strategies to optimize performance and enhance flexibility in database management. Managed database services enable businesses to integrate multiple cloud environments, ensuring seamless data migration, interoperability, and load balancing. For instance, General Electric (GE) has successfully implemented a multi-cloud strategy for its managed database services, leveraging different cloud providers to optimize performance and reduce costs across its diverse business units. These services help organizations avoid vendor lock-in, improve redundancy, and ensure uninterrupted operations. The rise of edge computing and the need for real-time data accessibility further contribute to the expansion of managed database solutions across diverse industries.
Market Trends:
Increasing Adoption of AI-Driven Automation:
Organizations are increasingly integrating artificial intelligence and machine learning into database management to enhance efficiency and reduce operational complexities. AI-driven automation optimizes database performance, automates routine maintenance, and predicts potential failures, minimizing downtime. For instance, the US General Services Administration (GSA) leverages AI technologies to streamline its procurement process, automating routine tasks such as contract reviews and compliance checks, allowing GSA staff to focus on more strategic tasks. Businesses are leveraging these capabilities to improve data processing speed, ensure proactive issue resolution, and enhance overall system reliability, making AI-powered managed database services a key market trend.
Rising Popularity of Database-as-a-Service (DBaaS):
The growing demand for cloud-based solutions has fueled the adoption of Database-as-a-Service (DBaaS), allowing businesses to outsource database management while focusing on core operations. DBaaS providers offer scalable, cost-effective solutions with automatic updates, security patches, and backup management. For instance, Loadsure utilizes Google Cloud's Document AI and Gemini AI to automate insurance claims processing, extracting data from various documents and classifying them with high accuracy. Enterprises are increasingly choosing DBaaS to eliminate infrastructure complexities, reduce IT overhead costs, and enhance data accessibility, particularly in industries such as e-commerce, finance, and healthcare.
Growing Emphasis on Security and Compliance:
With the rise in data breaches and stringent regulatory requirements, businesses are prioritizing security and compliance in database management. Managed database service providers are implementing advanced encryption techniques, real-time threat detection, and automated compliance monitoring to help enterprises meet legal and industry standards. For instance, Mayo Clinic is utilizing a hybrid cloud strategy to keep patient data secure. They are storing patient's sensitive data on-premises for high-end security and adhering to HIPAA compliance, while externally using Google Cloud Platform for many operational tasks like medical research, AI development and collaborative innovation platforms. Companies operating in sectors with strict data regulations, such as finance and healthcare, are particularly driving the demand for security-focused managed database solutions.
Expansion of Hybrid and Multi-Cloud Strategies:
Businesses are adopting hybrid and multi-cloud strategies to optimize performance, enhance flexibility, and ensure data redundancy. Managed database services support seamless data integration across multiple cloud environments, reducing dependency on a single vendor and improving disaster recovery capabilities. For instance, Coca-Cola has adopted a hybrid cloud infrastructure to manage its global supply chain. In real-time, they rely on this hybrid cloud setup to stay informed on inventory levels, production schedules, and shipping statuses. By doing so, Coca-Cola ensures its supply chains run efficiently even during times of high demand. The rising demand for real-time data synchronization and scalability is driving enterprises to implement multi-cloud database solutions, ensuring greater operational resilience and efficiency.
Market Challenges Analysis:
Data Security and Compliance Risks:
One of the primary challenges in the managed database services market is ensuring robust data security and compliance with evolving regulatory frameworks. Organizations dealing with sensitive data, particularly in industries such as finance, healthcare, and government, must adhere to strict regulations like GDPR, HIPAA, and CCPA. Managed database providers must continuously update their security protocols to protect against cyber threats, data breaches, and unauthorized access. However, the complexity of managing compliance across multiple jurisdictions presents a significant challenge. Additionally, businesses migrating to cloud-based databases often face concerns over data sovereignty, as storing data on third-party servers can increase risks related to privacy and regulatory non-compliance. The growing sophistication of cyberattacks, including ransomware and phishing schemes, further complicates database security, requiring constant monitoring and advanced threat detection. Failure to meet compliance standards can result in financial penalties and reputational damage, making regulatory adherence a top priority for database service providers.
Integration Complexities and Vendor Lock-In:
Enterprises adopting managed database services often encounter integration challenges, particularly when migrating from legacy systems to cloud-based infrastructures. The process requires significant time, expertise, and resources to ensure seamless data transition without disrupting business operations. Furthermore, organizations that opt for a single managed service provider may face vendor lock-in, limiting their flexibility to switch providers or adopt multi-cloud strategies. This dependency can lead to increased long-term costs and reduced control over database configurations. Companies must carefully assess compatibility with existing IT ecosystems and implement strategies to maintain interoperability across multiple cloud platforms. A lack of standardized database migration protocols can further hinder smooth transitions, leading to unexpected downtime and performance issues. To mitigate these risks, enterprises must adopt vendor-agnostic database management solutions that offer scalability, flexibility, and customization tailored to their specific operational needs.
Market Opportunities:
The managed database services market presents significant growth opportunities driven by the increasing demand for scalable, efficient, and secure database solutions. As businesses generate vast amounts of structured and unstructured data, the need for advanced database management solutions is rising. The rapid adoption of cloud computing across industries is further expanding the market, as enterprises seek cost-effective and flexible database management services. Small and medium-sized enterprises (SMEs), which previously lacked the resources for sophisticated database management, are increasingly leveraging managed database services to streamline operations, enhance efficiency, and reduce IT overhead costs. Additionally, the growing focus on real-time data processing and analytics is creating opportunities for service providers to offer AI-powered database management solutions, improving decision-making and business intelligence capabilities.
The expansion of multi-cloud and hybrid cloud strategies is another key opportunity in the market. Organizations are increasingly deploying databases across multiple cloud environments to enhance redundancy, ensure data availability, and reduce the risk of vendor lock-in. Managed database service providers that offer seamless integration across cloud platforms, along with robust security and compliance solutions, are well-positioned for growth. Furthermore, industries such as healthcare, finance, and e-commerce, which handle large volumes of sensitive data, are driving demand for managed database services with advanced encryption, automated compliance monitoring, and real-time threat detection. As digital transformation accelerates across global markets, managed database service providers have an opportunity to expand their offerings with tailored solutions catering to industry-specific requirements and regulatory standards.
Market Segmentation Analysis:
By Service
The managed database services market is segmented into database administration, database security, backup and recovery, performance monitoring, and analytics services. Businesses are increasingly outsourcing database administration to service providers to reduce IT infrastructure costs and enhance operational efficiency. Security services, including encryption and access management, are witnessing high demand due to rising cyber threats and stringent compliance requirements. Backup and recovery services are also gaining traction as enterprises prioritize disaster recovery and business continuity strategies.
By Application
Managed database services cater to applications such as transactional databases, big data analytics, cloud-based databases, and artificial intelligence-driven data management. The growing adoption of cloud computing is driving the demand for scalable and flexible cloud-based databases. Businesses are also leveraging managed services for big data analytics, enabling real-time data processing and business intelligence insights. AI-driven database management is becoming a key application area, improving automation and predictive analytics capabilities.
By Industry Vertical
Key industry verticals utilizing managed database services include BFSI, healthcare, retail, IT and telecommunications, government, and manufacturing. The BFSI sector relies on managed services for secure financial transactions and compliance adherence. Healthcare organizations utilize database management solutions for patient records and regulatory compliance. The retail industry benefits from real-time inventory tracking and customer analytics. The increasing adoption of digital solutions across all sectors continues to fuel the growth of managed database services.
Segmentations:
By Service:
- Database Security
- Database Optimization
- Database Administration
- Database Backup and Recovery
- Database Disaster Recovery
- Database Monitoring
By Applications:
- Web applications
- Big data analytics
- Customer relationship management (CRM)
- Supply chain management (SCM)
- Enterprise resource planning (ERP)
- Others
By Industry Vertical:
- Healthcare
- BFSI
- Manufacturing
- IT and Telecom
- Retail
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America (Market Share: 38%)
North America holds the largest share in the managed database services market, accounting for 38% of the total market. The region's dominance is driven by the early adoption of cloud computing, the presence of major technology firms, and a strong focus on cybersecurity and regulatory compliance. Enterprises across industries, including BFSI, healthcare, and retail, are increasingly investing in managed database solutions to enhance operational efficiency and data security. Stringent data protection regulations, such as GDPR compliance for companies operating globally and CCPA in the United States, are further driving demand for database security and managed compliance solutions. Additionally, the growing use of artificial intelligence and machine learning in database management is accelerating market expansion, with enterprises leveraging AI-driven automation for enhanced data processing and analytics.
Europe (Market Share: 29%)
Europe accounts for 29% of the managed database services market, supported by strict data privacy laws and a rapidly expanding cloud infrastructure. The General Data Protection Regulation (GDPR) has been a key driver in the adoption of managed database security and compliance solutions across financial services, healthcare, and e-commerce sectors. Companies in the region are prioritizing secure and scalable database management to ensure regulatory adherence while optimizing performance. The increasing focus on digital transformation and cloud migration strategies is further propelling market growth, with enterprises adopting hybrid and multi-cloud database management solutions. Additionally, government initiatives aimed at strengthening cybersecurity infrastructure are encouraging organizations to invest in advanced database protection and monitoring services.
Asia-Pacific (Market Share: 24%)
Asia-Pacific holds a 24% share in the managed database services market, driven by rapid digitalization, expanding IT infrastructure, and a growing number of small and medium-sized enterprises (SMEs) embracing cloud-based solutions. The increasing adoption of e-commerce, fintech services, and artificial intelligence-driven applications is fueling the demand for scalable and secure database management services. Countries such as China, India, and Japan are experiencing strong growth in cloud computing investments, prompting businesses to integrate managed database solutions for improved data accessibility and performance. Additionally, rising concerns over cybersecurity threats and government regulations related to data protection are accelerating the adoption of managed security services in the region. The expansion of multi-cloud strategies and demand for real-time data analytics further contribute to market growth in Asia-Pacific.
Key Player Analysis:
- Amazon Web Services (AWS)
- IBM
- SAP
- Oracle
- Microsoft Azure
- Google Cloud Platform (GCP)
- Alibaba Cloud
- Redis Labs
- DataStax
- Rackspace
- Teradata
Competitive Analysis:
The managed database services market is highly competitive, with key players focusing on innovation, security enhancements, and cloud-based service expansion. Leading companies are investing in artificial intelligence and automation to improve database performance, reduce downtime, and enhance security features. For instance, IBM Cloud® Database-as-a-Service (DBaaS) delivers ready-to-use, highly available database instances, allowing developers and IT staff to focus on value-added tasks while benefiting from advanced security measures and global hybrid cloud scale design. Established cloud service providers dominate the market by offering integrated database management solutions with advanced analytics and compliance tools. Major players in the industry compete on scalability, cost-effectiveness, and security compliance, catering to enterprises across diverse sectors. Companies are also expanding their service portfolios through strategic partnerships and acquisitions to strengthen their market position. The rising demand for multi-cloud and hybrid cloud database management solutions is driving competitive differentiation. As businesses increasingly shift towards cloud-based infrastructure, managed database service providers continue to innovate, ensuring high availability, seamless integration, and data protection to meet evolving enterprise needs.
Recent Developments:
- In February 2025, Oracle introduced long-term retention backup (LTR) for Autonomous Recovery Service, allowing storage of full backups for up to ten years.
- In September 2024, Oracle launched Select AI with Google Gemini support for Autonomous Database, enabling natural language to SQL query generation.
- In August 2023, AWS renamed Amazon Kinesis Data Analytics to Amazon Managed Service for Apache Flink, enhancing real-time data processing capabilities.
- In November 2023, SAP extended the mainstream support for SAP Data Services and SAP Information Steward 4.3 until the end of December 2026.
Market Concentration & Characteristics:
The managed database services market is moderately concentrated, with a mix of global cloud service providers, specialized database management firms, and emerging technology startups. Leading players, including major cloud providers, dominate the market by offering integrated database solutions with advanced automation, security, and analytics capabilities. The market is characterized by high scalability, continuous innovation, and strong demand for hybrid and multi-cloud database management solutions. Enterprises across industries are prioritizing database security, real-time analytics, and compliance-driven solutions, leading to increased adoption of AI-driven automation and predictive maintenance. The competitive landscape is further shaped by strategic partnerships, acquisitions, and service expansions, as companies aim to enhance operational efficiency and minimize data management complexities. As digital transformation accelerates, market players continue to focus on delivering high-performance, cost-effective, and secure managed database services tailored to evolving enterprise needs.
Report Coverage:
The research report offers an in-depth analysis based on Service, Applications, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of artificial intelligence and machine learning in database management will continue to rise, enabling automated performance optimization, predictive maintenance, and real-time data analytics.
- Businesses will increasingly shift towards hybrid and multi-cloud database strategies to enhance flexibility, ensure data redundancy, and avoid vendor lock-in.
- Security and compliance will remain key priorities, with growing demand for managed services offering advanced encryption, real-time threat detection, and automated compliance updates.
- The integration of edge computing with managed database services will expand, allowing faster data processing and improved efficiency in decentralized environments.
- Database-as-a-Service (DBaaS) will gain traction, providing enterprises with cost-effective, scalable, and fully managed cloud database solutions.
- Industry-specific managed database solutions will see increased demand, particularly in finance, healthcare, and e-commerce, where data security and regulatory compliance are critical.
- Real-time data streaming and analytics capabilities will drive innovation, enabling businesses to make faster and more accurate data-driven decisions.
- Open-source database solutions managed by third-party providers will gain popularity, providing enterprises with greater flexibility and cost savings.
- The market will witness increased mergers and acquisitions as companies aim to expand service offerings and strengthen competitive positioning.
- As digital transformation accelerates, enterprises will continue to invest in managed database services to enhance efficiency, scalability, and operational resilience.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Adoption of Cloud-Based Database Solutions
Organizations are migrating from traditional on-premises databases to cloud-based managed services to enhance scalability, accessibility, and reduce infrastructure costs. This shift is driven by the need for automated backup, disaster recovery, and real-time synchronization, supporting business continuity and operational efficiency.
Growing Demand for Big Data Analytics and AI Integration
The exponential growth in data generation is pushing businesses to leverage advanced analytics and AI-driven tools, which require robust managed database services for real-time processing and predictive modeling. Managed services enable seamless integration with analytics platforms, improving decision-making and operational efficiency.
Rising Concerns Over Data Security and Compliance
With increasing cyber threats and stringent regulations like GDPR and HIPAA, organizations are turning to managed database services for advanced security features such as encryption, access control, and real-time threat monitoring. These services help ensure data confidentiality, integrity, and regulatory compliance.
Expansion of Multi-Cloud and Hybrid Cloud Strategies
Enterprises are adopting multi-cloud and hybrid cloud approaches to optimize performance, enhance flexibility, and avoid vendor lock-in. Managed database services facilitate seamless data migration, interoperability, and load balancing across multiple cloud environments, supporting business agility and resilience.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the managed database services market in 2024 and its forecast for 2032?
What are the key drivers of the managed database services market?
Why are businesses increasingly adopting managed database services?
Which region leads the managed database services market?
Which region is expected to grow the fastest?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Database Security
- 1.2.2 Database Optimization
- 1.2.3 Database Administration
- 1.2.4 Database Backup and Recovery
- 1.2.5 Database Disaster Recovery
- 1.2.6 Database Monitoring
- 1.3 By Application
- 1.3.1 Web applications
- 1.3.2 Big data analytics
- 1.3.3 Customer relationship management (CRM)
- 1.3.4 Supply chain management (SCM)
- 1.3.5 Enterprise resource planning (ERP)
- 1.3.6 Others
- 1.4 By Industry Vertical
- 1.4.1 Healthcare
- 1.4.2 BFSI
- 1.4.3 Manufacturing
- 1.4.4 IT and Telecom
- 1.4.5 Retail
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 347,912 million → 2032: USD 931,473 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Managed Database Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Managed Database Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Managed Database Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Managed Database Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Managed Database Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Managed Database Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Managed Database Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Managed Database Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 347,912 million → 2032: USD 931,473 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Managed Database Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Database Security
- 12.3.6.2 Database Optimization
- 12.3.6.3 Database Administration
- 12.3.6.4 Database Backup and Recovery
- 12.3.6.5 Database Disaster Recovery
- 12.3.6.6 Database Monitoring
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Web applications
- 12.4.6.2 Big data analytics
- 12.4.6.3 Customer relationship management (CRM)
- 12.4.6.4 Supply chain management (SCM)
- 12.4.6.5 Enterprise resource planning (ERP)
- 12.4.6.6 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Healthcare
- 12.5.6.2 BFSI
- 12.5.6.3 Manufacturing
- 12.5.6.4 IT and Telecom
- 12.5.6.5 Retail
- 12.5.6.6 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Managed Database Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Managed Database Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Managed Database Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Managed Database Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amazon Web Services (AWS)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 IBM
- 18.4 SAP
- 18.5 Oracle
- 18.6 Microsoft Azure
- 18.7 Google Cloud Platform (GCP)
- 18.8 Alibaba Cloud
- 18.9 Redis Labs
- 18.10 DataStax
- 18.11 Rackspace
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

