
Market Overview:
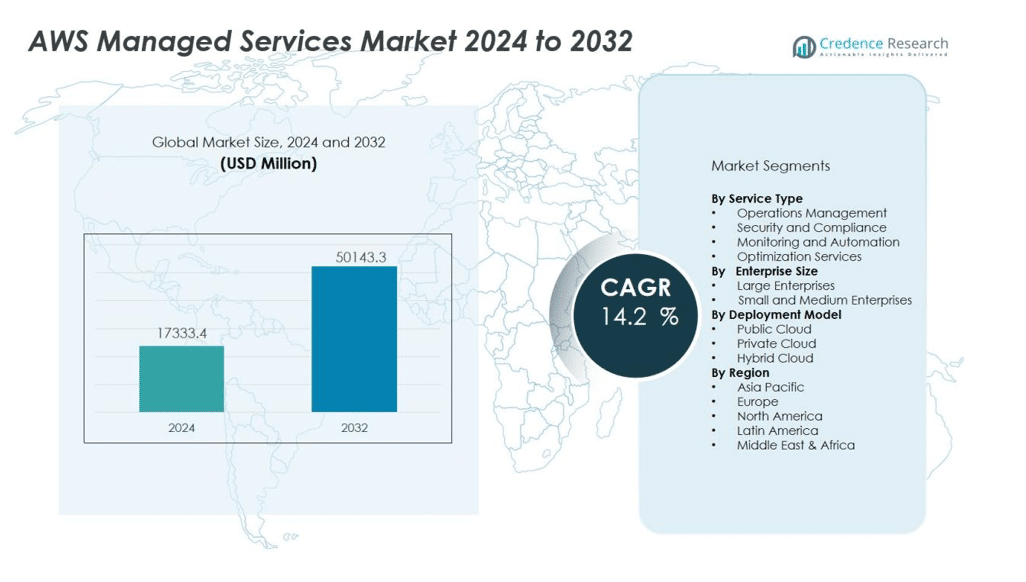
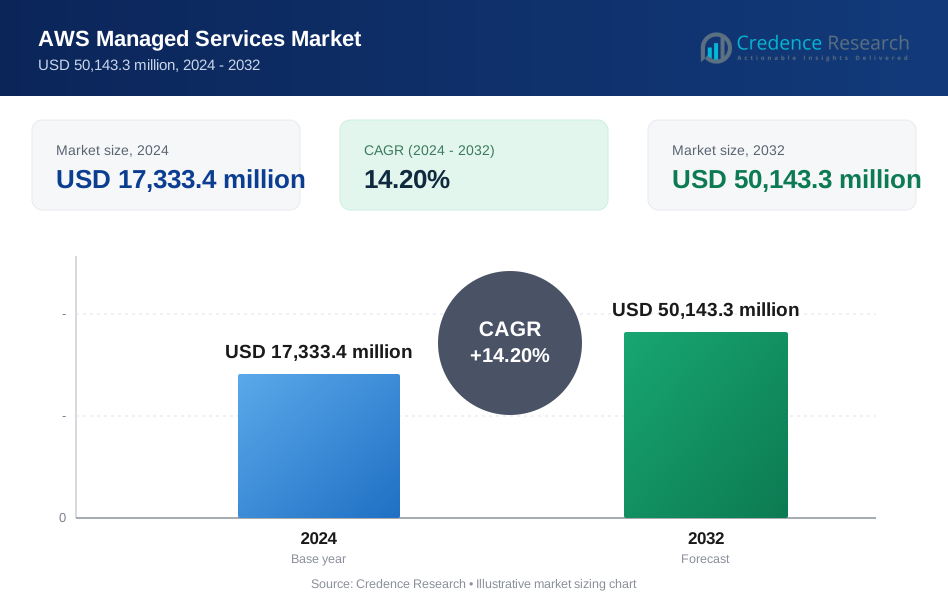
The AWS Managed Services Market size was valued at USD 17333.4 million in 2024 and is anticipated to reach USD 50143.3 million by 2032, at a CAGR of 14.2 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AWS Managed Services Market Size 2024 | USD 17333.4 million |
| AWS Managed Services Market, CAGR | 14.2% |
| AWS Managed Services Market Size 2032 | USD 50143.3 million |
Growth is primarily driven by the increasing reliance on cloud infrastructure for business continuity, the rising need for compliance with regulatory frameworks, and the growing complexity of multi-cloud and hybrid IT environments. Enterprises are seeking AWS managed services to streamline operations, enhance data security, and achieve cost optimization. The market also benefits from rising demand for DevOps, automation, and managed security services, as organizations face growing pressure to modernize IT infrastructure and improve operational resilience.
Regionally, North America dominates the AWS managed services market due to the high concentration of cloud service providers, advanced IT infrastructure, and rapid adoption across industries such as BFSI, healthcare, and retail. Europe follows with strong demand driven by GDPR compliance and digital transformation initiatives. Asia-Pacific is the fastest-growing region, fueled by rapid enterprise cloud adoption, government-backed digitization programs, and the expanding presence of SMEs embracing AWS cloud solutions. Emerging regions such as Latin America and the Middle East & Africa are also showing steady growth, supported by increasing cloud investments and modernization of legacy systems.
Market Insights:
- The AWS managed services market was valued at USD 17,333.4 million in 2024 and is projected to reach USD 50,143.3 million by 2032, growing at a CAGR of 14.2% during 2024–2032.
- Rising enterprise adoption of AWS platforms drives demand for managed services that enhance scalability, agility, and operational efficiency.
- Compliance and governance requirements fuel adoption as organizations prioritize data security, regulatory adherence, and business continuity.
- Multi-cloud and hybrid strategies create opportunities for managed services to streamline integration, resource utilization, and workload management.
- High costs, integration challenges, and vendor dependency remain key barriers, particularly for small and mid-sized enterprises with limited budgets.
- North America holds 41% market share, supported by strong enterprise cloud migration, advanced IT infrastructure, and industry-wide digital transformation.
- Asia-Pacific, with 21% market share, emerges as the fastest-growing region, fueled by government-led digitization programs, SME adoption, and expansion of e-commerce and manufacturing sectors.
Market Drivers:
Rising Enterprise Cloud Adoption Driving Managed Service Demand:
The AWS managed services market grows with the rapid enterprise shift toward cloud-based infrastructure. Businesses adopt AWS platforms to gain scalability, agility, and cost-efficiency, creating strong demand for managed services that simplify operations. It enables organizations to offload routine IT tasks such as monitoring, patching, and automation to service providers. This adoption reduces operational complexity and allows companies to focus on innovation and customer engagement.
- For instance, Capital One completed its migration from eight on-premises data centers to AWS in 2020, achieving 70% better disaster recovery performance in tests.
Increasing Focus on Compliance, Security, and Governance:
Data privacy and regulatory compliance are critical factors fueling adoption of managed services. Enterprises across industries face stringent regulatory standards that require robust governance, monitoring, and data security. The AWS managed services market addresses these needs by offering built-in compliance frameworks, identity management, and automated security protocols. It supports organizations in reducing risks while maintaining business continuity.
- For instance, Wells Fargo partnered with Microsoft Azure to build a multi-cloud compliance strategy, using Azure Policy and Security Center to process and monitor over 20 billion security signals daily while meeting stringent U.S. financial regulations.
Growing Complexity of Multi-Cloud and Hybrid Environments:
Businesses increasingly adopt multi-cloud and hybrid strategies to optimize workloads and reduce dependency on a single provider. This trend drives demand for AWS managed services to streamline integration, monitoring, and workload management. The AWS managed services market supports organizations with automation and standardized processes that improve resource utilization across diverse environments. It creates efficiency by managing complex infrastructures with minimal disruption.
Rising Demand for Cost Optimization and Operational Efficiency:
Enterprises prioritize cost control and efficiency to maximize returns on cloud investments. The AWS managed services market supports this objective by delivering proactive monitoring, automation, and resource optimization. It helps companies eliminate unnecessary expenditures, reduce downtime, and improve scalability through better workload alignment. This driver positions managed services as an essential tool for achieving sustainable growth in competitive industries.
Market Trends:
Expansion of AI, Automation, and DevOps Integration into Managed Services:
The AWS managed services market is witnessing strong adoption of AI-driven tools, automation, and DevOps practices that enhance cloud operations. Service providers integrate machine learning algorithms to enable predictive monitoring, anomaly detection, and intelligent workload distribution. Automation supports faster deployment, reduces manual intervention, and improves overall system reliability. DevOps integration accelerates software development cycles and strengthens collaboration between development and operations teams. It helps enterprises achieve agility and maintain competitiveness in fast-changing markets. The trend highlights a shift toward proactive management where efficiency, speed, and resilience define service value.
- For instance, Google Cloud deployed its Active Assist operations tool, which helped clients eliminate more than 5 million idle VM hours in one year, optimizing managed service usage.
Growing Adoption of Industry-Specific Cloud Solutions and Hybrid Cloud Strategies:
The AWS managed services market is evolving toward industry-tailored solutions that address sector-specific needs such as compliance, data protection, and scalability. Healthcare, BFSI, and retail enterprises increasingly seek managed services that align with strict regulations and unique workload demands. Hybrid and multi-cloud strategies also gain momentum, with organizations using AWS alongside private clouds or other public platforms to ensure flexibility and resilience. It enables businesses to avoid vendor lock-in while optimizing workloads across diverse environments. This trend reflects a growing need for customized services that balance innovation with operational stability. The shift toward specialized offerings strengthens market differentiation and long-term adoption.
- For instance, Deutsche Bahn’s retail subsidiary DB Systel migrated workloads to AWS in a hybrid model, improving digital ticketing operations that now handle more than 7 million customer transactions per day without disruptions
Market Challenges Analysis:
High Costs, Integration Barriers, and Vendor Dependency Issues:
The AWS managed services market faces challenges related to high costs and complex integration processes. Many small and mid-sized enterprises struggle to justify the expense of managed services, especially when budgets are tight. Integration with existing legacy systems often creates delays, technical hurdles, and higher implementation costs. It raises concerns about vendor dependency, as businesses may feel locked into specific service providers and pricing models. Limited transparency in service-level agreements adds further hesitation, making enterprises cautious about long-term commitments. These factors slow adoption among cost-sensitive organizations.
Security Concerns, Compliance Risks, and Talent Shortages:
Security and compliance remain critical barriers in the AWS managed services market, with organizations expressing concerns over third-party access to sensitive data. Breaches or compliance lapses can undermine trust and result in regulatory penalties. It highlights the difficulty of balancing convenience with robust governance and monitoring. Shortages of skilled professionals also create pressure, as enterprises depend heavily on providers to bridge capability gaps. Limited internal expertise can reduce flexibility and make businesses overly reliant on external partners. These risks reinforce the need for stronger frameworks and consistent trust-building efforts within the market.
Market Opportunities:
Expansion Through Industry-Specific Solutions and Cloud Modernization Initiatives:
The AWS managed services market presents strong opportunities through industry-focused solutions that address sector-specific challenges. Healthcare, BFSI, and government sectors demand services aligned with compliance, security, and scalability standards. Service providers can differentiate by developing tailored offerings that support critical workloads and regulatory frameworks. It creates scope for long-term partnerships as enterprises modernize infrastructure to meet digital transformation goals. The growing shift from on-premises systems to cloud-first strategies further expands demand for managed services. These opportunities enable providers to capture niche segments and build deeper market penetration.
Rising Demand for Advanced Analytics, AI, and Hybrid Cloud Management:
The AWS managed services market benefits from increasing adoption of advanced analytics, artificial intelligence, and hybrid cloud strategies. Enterprises seek real-time insights, predictive monitoring, and AI-driven automation to optimize workloads and enhance efficiency. Managed services that deliver these capabilities provide strong value in competitive industries. It opens opportunities for providers to offer hybrid and multi-cloud management solutions that balance flexibility and cost optimization. The rising need for unified governance across diverse IT environments creates further scope for innovation. Providers that integrate analytics, automation, and hybrid cloud support can secure a leading position in the evolving landscape.
Market Segmentation Analysis:
By Service Type:
The AWS managed services market is segmented by service type into operations management, security and compliance, monitoring and automation, and optimization services. Operations management dominates due to strong demand for day-to-day support and streamlined infrastructure performance. Security and compliance hold significant share with enterprises prioritizing data protection and adherence to regulatory standards. Monitoring and automation services grow steadily as organizations seek efficiency and proactive issue resolution. Optimization services further expand adoption by enabling cost control and resource alignment with business goals.
- For instance, Capgemini automated patch management across 120,000 EC2 instances using AWS Systems Manager, completing full compliance scans in under three hours.
By Enterprise Size:
The AWS managed services market shows strong adoption across large enterprises and SMEs. Large enterprises lead demand due to complex IT environments, high investment capacity, and greater emphasis on scalability and compliance. SMEs contribute significantly with growing preference for cost-effective managed solutions that reduce operational burdens. It supports smaller businesses in addressing skill shortages, improving resilience, and focusing on innovation. Both segments rely on managed services to maximize the value of AWS investments.
By Deployment Model:
The AWS managed services market is segmented by deployment model into public cloud, private cloud, and hybrid cloud. Public cloud deployment holds a leading share, driven by scalability and cost-efficiency. Private cloud adoption remains steady where security and customization are priorities. Hybrid cloud deployment is gaining momentum, offering flexibility and workload balancing across environments. It reflects the growing need for resilience, compliance, and operational agility in diverse industries.
- For instance, Netflix leverages AWS public cloud infrastructure to stream content to over 270 million global subscribers, demonstrating the scalability and reliability of AWS-managed public cloud services.
Segmentations:
By Service Type:
- Operations Management
- Security and Compliance
- Monitoring and Automation
- Optimization Services
By Enterprise Size:
- Large Enterprises
- Small and Medium Enterprises (SMEs)
By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds 41% market share in the AWS managed services market, supported by widespread adoption of advanced cloud infrastructure. The United States leads growth with high investment in digital transformation, automation, and cybersecurity solutions. It benefits from strong participation of leading managed service providers and extensive enterprise cloud migration initiatives. Sectors such as BFSI, healthcare, and retail accelerate demand by adopting AWS for scalability and compliance. Canada also contributes significantly with government-backed digital initiatives and growing adoption in mid-sized enterprises. The region’s focus on innovation and technology integration reinforces its leadership position in the market.
Europe:
Europe accounts for 27% market share in the AWS managed services market, driven by strict data privacy regulations and GDPR compliance requirements. Countries such as Germany, the United Kingdom, and France lead adoption due to strong enterprise IT modernization initiatives. It reflects a rising need for managed services that ensure secure operations and data governance. Growth is further supported by expanding investments in smart manufacturing, financial services, and e-commerce platforms. European enterprises prioritize hybrid and multi-cloud strategies to achieve flexibility and operational resilience. The region continues to build momentum with demand for tailored solutions that align with regulatory frameworks.
Asia-Pacific:
Asia-Pacific holds 21% market share in the AWS managed services market, fueled by rapid enterprise cloud adoption and government-backed digitalization programs. China, India, and Japan dominate regional growth through investments in IT modernization, e-commerce, and manufacturing. It benefits from rising demand among SMEs that seek cost-effective managed solutions to support scalability. Expansion of digital payment systems and online services further strengthens adoption across diverse industries. The region’s focus on infrastructure modernization and innovation accelerates reliance on AWS managed services. Asia-Pacific demonstrates strong potential to close the gap with mature markets through aggressive adoption strategies.
Key Player Analysis:
- Accenture plc
- 8K Miles Software Services Ltd.
- DXC Technology Company
- Smartronix Inc.
- Microsoft Azure
- Reliam LLC
- Onica
- Claranet Group
- Stratalux
- GS Lab
- Cloudnexa
- Capgemini
- e-Zest
Competitive Analysis:
The AWS managed services market is highly competitive, with global and regional players delivering a mix of infrastructure management, automation, and compliance solutions. Leading companies such as Accenture plc, 8K Miles Software Services Ltd., DXC Technology Company, Smartronix Inc., Microsoft Azure, Reliam LLC, and Onica strengthen their presence through strategic partnerships, industry-specific offerings, and advanced cloud capabilities. It demonstrates strong rivalry where established providers focus on scalability and innovation, while niche players emphasize agility and tailored solutions. Competitive strategies center on integrating AI-driven automation, hybrid cloud support, and managed security services to address evolving enterprise demands. The market also reflects rising collaboration between AWS and managed service providers to expand delivery capacity and reach new customer segments. Vendors differentiate themselves by prioritizing cost optimization, governance, and resilience, making service quality and customization decisive factors in maintaining long-term client relationships.
Recent Developments:
- In August 2025, Accenture plc announced the acquisition of Superdigital, enhancing its social and influencer marketing capabilities.
- In July 2025, Capgemini announced the acquisition of WNS, a move set to create a global leader in Agentic AI-powered intelligent operations.
Market Concentration & Characteristics:
The AWS managed services market demonstrates moderate to high concentration, with leading global providers holding a significant portion of revenue share through strong partnerships, advanced offerings, and extensive client bases. It is characterized by continuous innovation, integration of automation, AI, and DevOps practices, and growing emphasis on security and compliance. Competition intensifies as both established players and niche providers expand their portfolios to address industry-specific needs and hybrid cloud strategies. The market shows strong customer dependence on providers for cost optimization, operational efficiency, and governance, creating long-term contractual relationships. It evolves rapidly, with differentiation built on service quality, scalability, and ability to deliver tailored solutions across diverse sectors.
Report Coverage:
Deployment Model and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The AWS managed services market will expand with rising enterprise adoption of cloud-first strategies and digital transformation initiatives.
- Service providers will integrate AI, machine learning, and predictive analytics to enhance automation and efficiency.
- Growing demand for managed security services will drive innovation in governance, compliance, and identity management.
- Hybrid and multi-cloud adoption will strengthen, creating opportunities for providers offering unified management platforms.
- Industry-specific solutions will gain traction, particularly in healthcare, BFSI, retail, and government sectors.
- The market will witness greater emphasis on cost optimization, resource utilization, and workload alignment.
- Partnerships between AWS and regional service providers will expand, enhancing local expertise and delivery capacity.
- SMEs will increasingly adopt managed services to overcome skill shortages and reduce operational complexities.
- The focus on sustainability and green IT will encourage providers to integrate energy-efficient cloud management practices.
- Long-term growth will be supported by continuous innovation, deeper enterprise reliance on AWS environments, and evolving customer expectations for tailored, scalable services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the AWS managed services market, and what is its projected size in 2032?
Which AWS managed services market segment held the largest share in 2024?
What are the primary factors fueling the growth of the AWS managed services market?
Who are the leading companies in the AWS managed services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 AWS Managed Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global AWS Managed Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17,333.4 million → 2032: USD 50,143.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 AWS Managed Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. AWS Managed Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 AWS Managed Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 AWS Managed Services Market Drivers
- 3.3 AWS Managed Services Market Restraints & Challenges
- 3.4 AWS Managed Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 AWS Managed Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 AWS Managed Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, AWS Managed Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 AWS Managed Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. AWS Managed Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the AWS Managed Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 AWS Managed Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 AWS Managed Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 AWS Managed Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in AWS Managed Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New AWS Managed Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global AWS Managed Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America AWS Managed Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe AWS Managed Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific AWS Managed Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America AWS Managed Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East AWS Managed Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa AWS Managed Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. AWS Managed Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
