
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Managed Services Market Size 2024 | USD 335320 Million |
| Managed Services Market, CAGR | 14.5% |
| Managed Services Market Size 2032 | USD 990611.47 Million |
Market Overview:
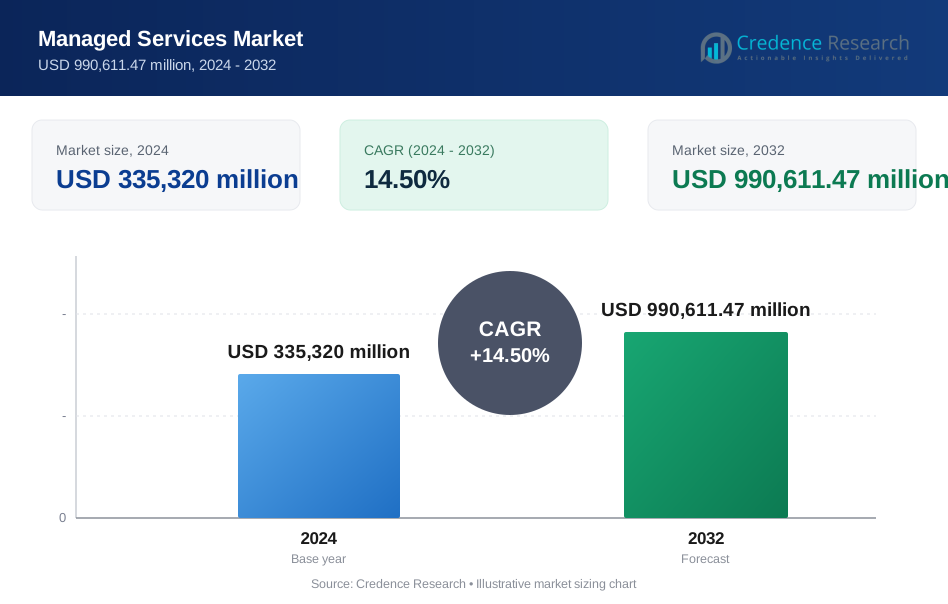
The Managed Services Market is projected to grow from USD 335320 million in 2024 to an estimated USD 990611.47 million by 2032, with a compound annual growth rate (CAGR) of 14.5% from 2024 to 2032.
Several key factors are propelling the growth of the managed services market. Organizations are increasingly seeking to enhance operational efficiency, reduce IT maintenance costs, and focus on core business functions. The adoption of advanced technologies such as cloud computing, artificial intelligence (AI), and the Internet of Things (IoT) necessitates specialized expertise, prompting businesses to partner with managed service providers (MSPs) for effective integration and management. Additionally, the escalating threat of cyberattacks and stringent regulatory compliance requirements are compelling companies to outsource cybersecurity and data management services to trusted MSPs. Rising demand for unified communication, collaboration tools, and remote monitoring is further strengthening the value proposition of managed services. The growing trend of hybrid work models and decentralized IT infrastructure has made continuous support and monitoring essential, thereby expanding the addressable market for service providers.
Regionally, North America currently dominates the managed services market, accounting for a significant revenue share. This dominance is attributed to the region's rapid adoption of cloud technologies, a high concentration of enterprises, and a strong emphasis on cybersecurity measures. The United States, in particular, is a major contributor, with a substantial number of businesses leveraging managed services for IT operations. In contrast, the Asia-Pacific region is anticipated to witness the fastest growth, driven by increasing digital transformation initiatives, the proliferation of SMEs, and government-led programs promoting technological advancement. Countries like India and China are at the forefront, with India experiencing a surge in demand for managed services due to its expanding IT sector and emphasis on digital infrastructure development
Market Insights:
- The Managed Services Market is projected to grow from USD 335,320 million in 2024 to USD 990,611.47 million by 2032, registering a CAGR of 14.5%.
- Businesses are increasingly outsourcing non-core IT operations to managed service providers to improve operational efficiency and focus on innovation and growth.
- Cost optimization remains a key growth driver, with MSPs helping organizations reduce capital expenditure and achieve predictable, performance-driven service models.
- The rising complexity of technologies like AI, cloud computing, and IoT is creating demand for specialized managed services that ensure seamless integration and performance.
- Escalating cybersecurity threats and strict compliance mandates are pushing companies to adopt managed security services to manage risk and regulatory demands.
- Challenges such as legacy system integration, resistance to change, and shortage of skilled professionals continue to hinder adoption in some sectors.
- North America leads the market with 38.5% share due to early tech adoption, while Asia-Pacific is the fastest-growing region, driven by digitalization and SME demand.
Market Drivers:
Increased Focus on Core Business Functions Is Fueling Outsourcing of IT Operations
Enterprises are increasingly turning to managed service providers to offload non-core IT operations and concentrate on strategic business activities. The rising need to streamline internal resources and reduce operational complexities has elevated the appeal of managed services. Businesses view MSPs as long-term partners who can manage infrastructure, applications, and end-user systems efficiently. This shift allows internal teams to focus on innovation, customer engagement, and competitive differentiation. The Managed services market is benefiting from this trend, particularly in industries such as BFSI, manufacturing, and retail. It is also supported by the growing need for continuous uptime and service availability across global operations.
- For instance, IBM partners with MSPs to manage non-core IT operations, allowing internal teams to focus on innovation and strategic initiatives.
Surging Demand for Cost Optimization and Operational Efficiency
Cost containment remains a primary driver behind the adoption of managed services. Companies are under pressure to reduce IT expenditures while maintaining service quality, scalability, and security. Outsourcing to MSPs helps achieve predictable spending models, eliminates capital investments, and converts fixed costs into variable costs. Managed service models also reduce downtime and optimize resource allocation through automation and proactive support. It enables faster resolution of IT issues and enhances productivity across departments. Organizations are increasingly relying on MSPs to meet performance metrics under defined service level agreements, driving steady growth in the market.
Adoption of Emerging Technologies Necessitates Specialized Expertise
The rapid adoption of cloud computing, AI, machine learning, and IoT has created complex IT environments that require advanced capabilities. Businesses lack the in-house expertise to manage evolving technology stacks, integration, and compliance demands. This knowledge gap drives demand for MSPs who can deploy, maintain, and secure these technologies while ensuring performance. The Managed services market is expanding as providers offer value-added services like cloud orchestration, cybersecurity, and data analytics support. It allows organizations to remain agile, reduce implementation risks, and gain faster returns on digital investments. MSPs play a crucial role in enabling technology-led business transformation.
Heightened Security Threats and Regulatory Pressures Drive Managed Services Adoption
The global increase in cyber threats, data breaches, and ransomware attacks has made cybersecurity a top priority. Regulatory frameworks such as GDPR, HIPAA, and CCPA impose strict compliance obligations on enterprises. Many organizations find it difficult to maintain in-house capabilities that align with these standards and prefer to delegate these responsibilities to specialized providers. Managed security services help detect, prevent, and respond to incidents while maintaining compliance. It also ensures continuous risk assessment, vulnerability monitoring, and policy enforcement. These factors are compelling businesses to adopt managed services as a reliable solution for risk mitigation and regulatory adherence.
- For instance, IBM's managed security services include continuous risk assessment and compliance with GDPR and HIPAA, helping clients detect and respond to ransomware and data breaches effectively.
Market Trends:
Rising Integration of Artificial Intelligence and Automation in Service Delivery
The integration of artificial intelligence (AI) and automation tools into managed service offerings is transforming service delivery. MSPs are leveraging AI-driven platforms to enhance issue detection, automate repetitive tasks, and predict IT failures before they occur. Automation tools are streamlining patch management, system monitoring, and ticket resolution, which boosts efficiency and lowers service costs. AI-powered analytics are also helping providers deliver real-time insights into system performance and user behavior. The Managed services market is evolving with these intelligent solutions, creating value through faster response times and reduced downtime. It empowers clients to achieve operational excellence while reducing dependence on manual intervention.
- For example, NexusTek, a U.S.-based MSP, developed the Nexus Tech Secure AI platform, allowing customers to test and deploy multiple AI models tailored to their security, operations, or customer service needs. This flexibility has been described as a "game-changer" by NexusTek’s CEO, Hamilton Yu, noting that “everyone in the company is using it to become more efficient, from customer support to operations.
Shift Toward Hybrid and Multi-Cloud Management Services
Organizations are increasingly adopting hybrid and multi-cloud strategies to enhance agility, reduce vendor lock-in, and optimize workload distribution. This shift creates complex environments that require centralized management and seamless interoperability between platforms. MSPs are stepping in to provide unified cloud management, governance frameworks, and cross-platform optimization. The Managed services market is seeing a strong demand for providers who can support diverse infrastructures across public, private, and edge computing environments. It reflects the growing need for flexibility and scalability in digital infrastructure management. Service providers are also focusing on offering cloud cost optimization and compliance solutions to support business goals.
Expansion of Managed Security Services in Response to Evolving Threats
The sophistication of cyber threats has led to a sharp increase in demand for managed security services. Organizations seek end-to-end protection that includes threat intelligence, incident response, firewall management, and endpoint detection. Managed service providers are expanding their security portfolios with advanced solutions such as Security Operations Centers (SOCs), Zero Trust frameworks, and identity access management. The Managed services market is witnessing strong momentum in this segment, particularly among enterprises with sensitive data and regulatory obligations. It is reshaping the competitive landscape, with vendors focusing on cybersecurity as a core differentiator. These developments are reinforcing trust in MSPs as strategic security partners.
- For instance, Fulcrum IT Partners has implemented AI-powered platforms to automate threat detection and provide on-demand insights, empowering clients to interact directly with their security data.
Growing Demand for Industry-Specific and Customized Managed Services
Businesses are looking for tailored managed services that align with industry-specific compliance, workflows, and technologies. Sectors like healthcare, finance, education, and manufacturing require niche capabilities that go beyond generic IT support. MSPs are responding by developing customized service models that address regulatory requirements, mission-critical applications, and specialized hardware environments. The Managed services market is growing due to this trend, with providers differentiating themselves through vertical-specific expertise. It allows clients to receive targeted support that enhances operational continuity and regulatory alignment. Industry-focused solutions also improve client retention by addressing nuanced pain points within each sector.
Market Challenges Analysis:
Complexity of Legacy Systems and Resistance to Change Slow Adoption
Many organizations continue to rely on legacy IT infrastructure that lacks compatibility with modern managed services solutions. The process of transitioning from outdated systems to cloud-based or automated environments presents significant technical and financial hurdles. Resistance to change within organizations, especially among traditional sectors, further complicates adoption. Businesses often hesitate to relinquish control over core IT functions, fearing loss of visibility or disruption in operations. The Managed services market faces challenges in convincing stakeholders of the long-term value and ROI associated with outsourcing. It must address these concerns through education, transparent SLAs, and phased integration strategies to build trust.
- For example, when the U.S. Department of Veterans Affairs attempted to modernize its electronic health records system, the transition was delayed by over a year due to legacy software dependencies and integration challenges, as reported in a 2023 GAO review.
Shortage of Skilled Professionals and Rising Competition Impact Service Delivery
The growing demand for managed services has outpaced the availability of skilled professionals with expertise in cybersecurity, cloud management, and automation. This talent shortage limits the scalability of managed service providers and affects service quality and innovation. Smaller MSPs face difficulty in competing with established players who can offer broader portfolios and higher levels of customization. The Managed services market is experiencing intensified competition, which pressures providers to reduce pricing while maintaining service excellence. It creates challenges in sustaining profitability and investing in R&D. To remain competitive, MSPs must prioritize workforce development, upskilling, and strategic differentiation.
Market Opportunities:
Small and medium-sized enterprises (SMEs) are increasingly embracing managed services to access enterprise-level IT capabilities without incurring high costs. Many SMEs lack internal IT departments and rely on external partners to manage infrastructure, cybersecurity, and cloud operations. The Managed services market is well-positioned to tap into this segment by offering flexible, scalable, and subscription-based models. It allows SMEs to improve operational efficiency, enhance security posture, and support digital transformation initiatives. Providers can seize this opportunity by tailoring offerings that align with SME budgets and industry-specific needs. The growing adoption of remote work and e-commerce further amplifies this demand.
Emerging economies are undergoing rapid digitalization, supported by government initiatives, infrastructure development, and increased internet penetration. Businesses across sectors are investing in IT modernization, cloud migration, and automation to stay competitive. The Managed services market can capitalize on this shift by delivering localized solutions that address regulatory and operational requirements. It has significant potential in regions such as Southeast Asia, Latin America, and Africa, where enterprises seek reliable partners for scalable and secure technology deployments. Providers who establish strong regional partnerships and build culturally aligned service models can unlock long-term growth opportunities in these underpenetrated markets.
Market Segmentation Analysis:
By service types, the Managed services market spans a wide range of services with managed network services and managed security services leading in demand due to rising cybersecurity threats and the complexity of enterprise networks. Managed cloud services and managed IT support services are also gaining momentum, driven by cloud migration and the need for scalable remote support. Managed data center services and backup and disaster recovery solutions support business continuity, while managed mobility and application services address digital workplace requirements.
By deployment model, cloud-based managed services dominate, fueled by cost efficiency, flexibility, and ease of integration. On-premise models remain relevant in highly regulated industries where data control is critical.
By Organization size, the market serves both large enterprises and SMEs, though SMEs are rapidly increasing adoption due to limited internal IT capabilities and rising digital demands.
By end-user industries, BFSI and IT & telecom hold major shares due to their reliance on secure, high-performance systems. Healthcare, manufacturing, and retail sectors show growing uptake, while government, education, and logistics sectors are accelerating investments in managed services for operational resilience and efficiency.
Segmentation:
By Service Type
- Managed Network Services
- Managed Security Services
- Managed Data Center Services
- Managed Infrastructure Services
- Managed Mobility Services
- Managed Communication and Collaboration Services
- Managed IT Support Services
- Managed Cloud Services
- Managed Application Services
- Managed Backup and Disaster Recovery Services
By Deployment Model
- On-Premise
- Cloud-Based
By Organization Size
- Small and Medium-Sized Enterprises (SMEs)
- Large Enterprises
By End-User Industry
- BFSI (Banking, Financial Services, and Insurance)
- IT and Telecom
- Healthcare
- Manufacturing
- Retail and E-commerce
- Government and Public Sector
- Energy and Utilities
- Education
- Media and Entertainment
- Transportation and Logistics
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads the Global Managed Services Market with Strong Digital Infrastructure
North America holds the largest share of the global managed services market, accounting for 38.5% of the total revenue in 2024. The region's dominance stems from early technology adoption, mature digital infrastructure, and a high concentration of enterprises across key sectors such as banking, healthcare, and manufacturing. The United States drives much of this growth, with businesses outsourcing IT operations to improve efficiency and meet compliance requirements. Strong demand for managed security services and cloud management solutions continues to strengthen the market. It benefits from the region’s focus on innovation, backed by investments in AI, automation, and analytics. Canada also contributes significantly, with increased adoption of managed services among small and mid-sized businesses.
Asia-Pacific Emerges as the Fastest-Growing Region with Expanding SME Base
Asia-Pacific accounts for 27.3% of the global managed services market share and is expected to witness the fastest growth during the forecast period. The region is experiencing a surge in digital transformation across emerging economies such as India, China, Indonesia, and Vietnam. High mobile penetration, increased cloud adoption, and favorable government initiatives are driving demand for managed IT and cloud-based services. The Managed services market is expanding rapidly in this region due to the rising number of SMEs seeking cost-effective IT support. It also benefits from the growing focus on cybersecurity and infrastructure modernization. Regional MSPs are strengthening their capabilities to serve both domestic and international clients.
Europe Holds a Stable Position Driven by Regulatory Compliance and Industry Maturity
Europe holds 22.1% of the global managed services market share, supported by a strong presence of global enterprises and regulated industries. Countries such as Germany, the UK, and France are leading in outsourcing IT services to comply with complex data protection and cybersecurity regulations. The market benefits from the region's structured approach to digitalization, especially in finance, healthcare, and public services. It is witnessing increased adoption of managed cloud, network, and security services. Demand is also rising for industry-specific solutions that align with local compliance frameworks like GDPR. Service providers with deep domain expertise are well-positioned to capture value across Europe's diverse business landscape.
Key Player Analysis:
- Accenture
- ARYAKA NETWORKS, INC.
- AT&T Inc.
- Atera Networks Ltd.
- BMC Software, Inc.
- Broadcom
- Cisco Systems, Inc.
- DXC Technology Company
- Fujitsu
- HCL Technologies Limited
- HP Development Company, L.P.
- International Business Machines Corporation
- Lenovo
Competitive Analysis:
The managed services market is highly competitive, with global and regional players vying for market share through service innovation, strategic partnerships, and acquisitions. Key companies such as IBM Corporation, Accenture, Cisco Systems, Fujitsu, and Tata Consultancy Services dominate the landscape by offering comprehensive portfolios that span cloud management, cybersecurity, infrastructure services, and application support. The market is witnessing intensified competition as providers focus on enhancing automation, analytics, and AI-driven capabilities. It also sees niche firms gaining traction by delivering industry-specific and cost-effective solutions tailored to SMEs. Large enterprises prefer providers with global reach and robust compliance frameworks, while smaller clients value flexibility and localized support. The managed services market rewards players who can balance scale, customization, and continuous innovation to meet evolving client needs across diverse industries and geographies. Strategic investments in workforce skills, customer experience, and service integration are becoming critical for long-term differentiation and sustained growth.
Recent Developments:
- In May 2025, Accenture deepened its partnership with SAP to launch ADVANCE, a suite of packaged service offerings designed to help high-growth companies enable connected intelligence and accelerate business transformation using AI-driven insights. This initiative targets organizations with up to $5 billion in annual revenue, providing streamlined finance, procurement, supply chain, and workforce management solutions delivered through preconfigured services.
- In May 2025, Atera launched its Autopilot platform, an AI-driven tool that autonomously identifies and resolves Tier 1 IT issues in real time, freeing IT teams from repetitive tasks and enhancing efficiency for managed service providers (MSPs).
- In March 2025, Aryaka announced a significant expansion in the Asia Pacific region, establishing new partnerships with NI+C in Japan and ASV Platforms in Australia. These partnerships are part of Aryaka’s strategy to extend the reach of its Unified SASE as a Service offering, accompanied by key leadership appointments to drive global go-to-market efforts.
- In March 2025, DXC launched new products in partnership with ServiceNow, introducing DXC Assure BPM, an AI-powered business process management solution aimed at modernizing the insurance industry and reducing operational costs.
Market Concentration & Characteristics:
The managed services market exhibits moderate to high market concentration, with a few dominant players holding significant global shares while regional firms maintain strong local presence. It is characterized by a blend of large-scale, full-service providers and specialized vendors offering niche solutions. The market favors companies with diversified portfolios, global delivery capabilities, and strong technical expertise. It is driven by long-term contracts, recurring revenue models, and high client retention rates, particularly in industries with complex regulatory or operational requirements. Customization, service-level agreements, and integration with emerging technologies such as AI and cloud computing define competitive differentiation. The managed services market continues to evolve rapidly, influenced by digital transformation, enterprise outsourcing trends, and growing demand for scalable, secure, and agile IT support.
Report Coverage:
The research report offers an in-depth analysis based on Service Type, Deployment Model, Organization Size and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The managed services market will continue to expand due to rising demand for scalable IT infrastructure across all industries.
- Cloud-native managed services are expected to gain momentum with increasing hybrid and multi-cloud adoption.
- AI and automation will play a key role in transforming service delivery, enhancing efficiency and reducing human intervention.
- Managed security services will see heightened demand driven by complex cyber threats and stricter compliance mandates.
- SMEs will emerge as a major growth segment, attracted by flexible pricing and tailored support models.
- Providers will focus on industry-specific solutions to address unique operational and regulatory needs.
- Edge computing and IoT proliferation will open new opportunities for localized managed services.
- Partnerships between MSPs and hyperscalers like AWS, Microsoft Azure, and Google Cloud will shape competitive dynamics.
- Talent acquisition and upskilling will become critical to meet the demand for advanced technical capabilities.
- Emerging markets in Asia, Latin America, and Africa will drive the next wave of growth through digital adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Managed services market?
What factors are driving the growth of the Managed services market?
What are the key segments within the Managed services market?
What are some challenges faced by the Managed services market?
Who are the major players in the Managed services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Managed Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Managed Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 335,320 million → 2032: USD 990,611.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Managed Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Managed Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Managed Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Managed Services Market Drivers
- 3.3 Managed Services Market Restraints & Challenges
- 3.4 Managed Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Managed Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Managed Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Managed Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Managed Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Managed Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Managed Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Managed Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Managed Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Managed Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Managed Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Managed Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Managed Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Managed Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Managed Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Managed Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Managed Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Managed Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Managed Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Managed Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
