
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
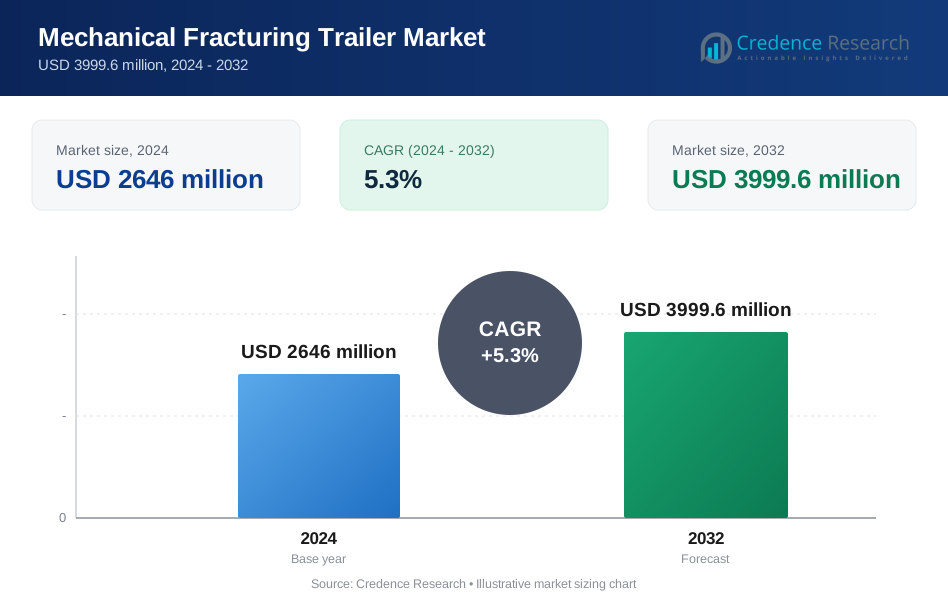
| Mechanical Fracturing Trailer Market Size 2024 | USD 2646 million |
| Mechanical Fracturing Trailer Market, CAGR | 5.3% |
| Mechanical Fracturing Trailer Market Size 2032 | USD 3999.6 million |
Market Overview:
The Mechanical Fracturing Trailer Market is projected to grow from USD 2646 million in 2024 to an estimated USD 3999.6 million by 2032, with a compound annual growth rate (CAGR) of 5.3% from 2024 to 2032.
Several factors contribute to the robust growth of the mechanical fracturing trailer market. The primary driver is the increasing exploration and production activities in shale and tight gas formations, particularly in North America. These unconventional resources require specialized equipment to enhance extraction efficiency and reduce operational costs. Technological advancements in hydraulic fracturing, such as improvements in pump designs and automation, have further bolstered the demand for mechanical fracturing trailers. Additionally, the industry's focus on reducing environmental impact has led to the development of trailers powered by cleaner energy sources, aligning with global sustainability goals. The growing need for enhanced productivity and cost-effectiveness in hydraulic fracturing operations continues to push the demand for these advanced trailers across the globe. Furthermore, the rising oil and gas production across various regions is expected to further accelerate the market growth in the coming years.
Regionally, North America dominates the mechanical fracturing trailer market, accounting for a significant share due to extensive shale gas exploration activities in the United States and Canada. The region's well-established oil and gas industry, coupled with the presence of major market players, further drives the market's growth. Additionally, the high level of technological innovation in the region's hydraulic fracturing processes ensures sustained demand for advanced trailers. In contrast, the Asia-Pacific region is anticipated to witness rapid growth during the forecast period. Countries like China and India are increasing investments in oil and gas exploration and production operations, fueling the demand for fracturing trailers. Favorable government policies and efforts to enhance local production capabilities are also contributing to the market's expansion in this region. Emerging markets in Latin America and the Middle East are also expected to present new growth opportunities for manufacturers of mechanical fracturing trailers, as they ramp up energy production and exploration activities.
Market Insights:
- The mechanical fracturing trailer market is projected to grow from USD 2646 million in 2024 to USD 3999.6 million by 2032, driven by increasing demand for hydraulic fracturing operations.
- The primary market driver is the rising exploration of unconventional oil and gas resources, particularly in shale and tight gas formations, requiring specialized fracturing equipment.
- Technological advancements, including automation, improved pump designs, and real-time monitoring, are enhancing the performance and efficiency of mechanical fracturing trailers.
- Environmental sustainability is a major focus, pushing the development of energy-efficient trailers powered by cleaner energy sources to reduce operational emissions and noise.
- The market sees expanding opportunities in emerging regions like Asia-Pacific, Latin America, and the Middle East as countries increase their investment in shale gas exploration.
- High operational and maintenance costs pose challenges, with the need for frequent servicing and specialized technicians increasing the financial burden for operators.
- Evolving regulatory and environmental standards require manufacturers and operators to comply with stringent emissions, noise reduction, and energy efficiency regulations, adding complexity and costs.
Market Drivers:
Increasing Demand for Unconventional Oil and Gas Extraction
The demand for mechanical fracturing trailers is primarily driven by the rising exploration and production of unconventional oil and gas resources, particularly in shale and tight gas formations. These resources require specialized equipment to optimize extraction processes and enhance operational efficiency. The need for hydraulic fracturing, or fracking, to unlock such resources has led to greater demand for robust mechanical fracturing trailers. These trailers are essential for transporting fracturing pumps, mixing equipment, and other hydraulic components to remote well sites, ensuring smooth and efficient operations. As exploration in unconventional reserves continues to rise globally, the demand for these trailers is expected to increase substantially.
Technological Advancements in Hydraulic Fracturing
Technological innovations in hydraulic fracturing are another key driver of the mechanical fracturing trailer market. The ongoing advancements in pump designs, automation, and energy efficiency have enhanced the overall performance of mechanical fracturing trailers. These improvements allow for better pressure control, faster setup times, and more reliable operations, which are essential in maximizing the efficiency of fracturing processes. Enhanced control systems and real-time monitoring features have been integrated into new trailer models, contributing to the increased adoption of such equipment in the field. With these technological enhancements, operators can achieve higher levels of productivity while reducing the overall operational costs of hydraulic fracturing.
Focus on Environmental Sustainability and Energy Efficiency
The growing emphasis on environmental sustainability within the oil and gas industry is significantly influencing the mechanical fracturing trailer market. Companies are increasingly focused on reducing the carbon footprint of their operations and minimizing environmental impact. This has driven the development of more energy-efficient mechanical fracturing trailers, often powered by cleaner sources such as electricity or natural gas instead of diesel. Innovations that reduce noise, emissions, and energy consumption are becoming standard features in new trailer models. The shift toward sustainability is crucial for ensuring long-term industry viability, and it is pushing manufacturers to integrate green technologies into their product offerings.
- Baker Hughes, for example, has focused on developing sustainable and eco-friendly fracturing trailers to address environmental concerns related to hydraulic fracturing.
Expansion of Hydraulic Fracturing Operations in Emerging Markets
The expansion of hydraulic fracturing activities in emerging markets, especially in Asia-Pacific, Africa, and Latin America, is a key factor propelling the growth of the mechanical fracturing trailer market. As countries such as China, India, and Brazil increase their investments in oil and gas extraction, the need for advanced hydraulic fracturing equipment, including mechanical fracturing trailers, has surged. These regions are actively exploring and developing their shale gas reserves, which requires specialized equipment to manage the complexities of fracking operations. The continued expansion of these markets presents a significant growth opportunity for manufacturers of mechanical fracturing trailers to tap into new customer bases and increase market share globally.
- For example, CNPC has developed advanced hydraulic fracturing technology and equipment, such as the Apollo 1 turbine fracturing pumper, which has been successfully deployed in shale gas operations in Sichuan Province, China, demonstrating high power and efficiency in challenging field conditions.
Market Trends:
Growth of Automation and Digitalization in Mechanical Fracturing Trailers
A prominent trend in the mechanical fracturing trailer market is the increasing integration of automation and digitalization in fracturing operations. Technological innovations in trailer designs now incorporate automated systems that allow for enhanced precision, real-time monitoring, and data collection. These advancements help streamline the overall process, reduce human error, and improve operational efficiency. The ability to monitor fracturing processes remotely and adjust parameters in real-time ensures better control over the entire operation, boosting productivity. With the rise of the Internet of Things (IoT) and smart technologies, mechanical fracturing trailers are becoming more sophisticated, providing operators with better insights and control over their equipment and performance.
Shift Towards Energy-Efficient and Environmentally Friendly Trailers
Sustainability continues to shape trends in the mechanical fracturing trailer market, with a strong push towards energy-efficient and environmentally friendly solutions. The oil and gas industry is under increasing pressure to minimize its environmental footprint, and mechanical fracturing trailers are no exception. Manufacturers are focusing on creating trailers that are more fuel-efficient, use alternative energy sources, and reduce noise and emissions. This trend reflects the broader movement within the industry to adopt greener practices and comply with increasingly stringent environmental regulations. The development of electric and hybrid-powered trailers, designed to reduce reliance on fossil fuels, is gaining traction and further contributing to the market's growth.
- For instance, Halliburton’s ZEUS® platform, for example, eliminates diesel use entirely on electric frac sites, reducing emissions by up to 45% when powered by the grid and by up to 30% when using reciprocating engines, compared to Tier 2 diesel engines.
Increase in Customization and Modular Solutions
Customization is becoming a significant trend in the mechanical fracturing trailer market. Operators seek equipment that can be tailored to their specific needs and site conditions. This trend has led to the rise of modular fracturing trailer solutions that offer flexible configurations. These modular systems allow for easy upgrades, repairs, and adjustments depending on the project requirements. By offering a higher level of customization, manufacturers are catering to the diverse needs of operators across various sectors of the oil and gas industry. This trend towards modular solutions not only increases the versatility of mechanical fracturing trailers but also contributes to long-term cost savings for operators.
- SANY’s YLC2500 mechanical fracturing unit, for example, is equipped with advanced wireless construction transmission technology and a mobile app for intelligent management, allowing operators to tailor equipment configurations and monitor equipment status in real time.
Focus on Safety and Compliance with Regulatory Standards
Safety remains a priority in the mechanical fracturing trailer market, with increasing emphasis on compliance with stringent regulatory standards. The growing complexity of hydraulic fracturing operations has made safety features and regulatory adherence essential. Manufacturers are incorporating advanced safety technologies such as automatic shut-off systems, pressure control mechanisms, and enhanced structural integrity to meet evolving safety standards. This trend reflects the industry's heightened focus on preventing accidents, protecting workers, and mitigating environmental risks. The continuous improvement of safety protocols within the mechanical fracturing trailer market ensures that operators comply with the latest industry regulations while maintaining safe and efficient operations.
Market Challenges Analysis:
High Operational and Maintenance Costs
One of the key challenges faced by the mechanical fracturing trailer market is the high operational and maintenance costs associated with these systems. Mechanical fracturing trailers are integral to hydraulic fracturing operations, and their maintenance can be expensive due to the complex machinery and high wear and tear under harsh field conditions. Frequent repairs and servicing are required to ensure the efficient operation of the trailers, which can significantly impact the overall cost structure for oil and gas companies. Moreover, these trailers often require specialized technicians for maintenance, further driving up costs. The financial burden of purchasing and maintaining advanced mechanical fracturing trailers can be a significant barrier, particularly for smaller operators or those in emerging markets with limited budgets.
Regulatory and Environmental Compliance Challenges
The mechanical fracturing trailer market faces increasing pressure from evolving regulatory and environmental standards. As governments worldwide impose stricter environmental regulations on the oil and gas industry, operators must ensure their equipment complies with these new rules. Mechanical fracturing trailers must meet stringent emissions, noise reduction, and waste disposal requirements, which can involve costly upgrades or modifications. In addition, as the focus on environmental sustainability intensifies, companies must invest in more energy-efficient solutions, which can lead to higher upfront costs. Adapting to these changing regulations while maintaining operational efficiency remains a significant challenge for market participants. The need for constant compliance with both local and international environmental standards adds an additional layer of complexity to the industry.
Market Opportunities:
Expansion of Hydraulic Fracturing in Emerging Markets
The mechanical fracturing trailer market presents significant opportunities in emerging markets, where the oil and gas industry is rapidly growing. Countries in Asia-Pacific, Africa, and Latin America are increasing investments in unconventional resources, driving the demand for hydraulic fracturing technologies. These regions' growing shale gas reserves offer new prospects for mechanical fracturing trailers, as local operators seek efficient and reliable equipment for their operations. As exploration activities intensify in these regions, there will be a surge in demand for advanced, cost-effective fracturing solutions. This creates a valuable growth opportunity for manufacturers to expand their market presence and cater to these developing markets.
Technological Advancements and Customization Trends
Another opportunity in the mechanical fracturing trailer market lies in the ongoing technological advancements and customization trends. As operators demand more efficient and flexible solutions, manufacturers can capitalize on these needs by offering tailored and modular systems. The trend toward smart trailers, equipped with real-time monitoring and automation capabilities, is creating opportunities for manufacturers to innovate and differentiate their products. These advancements not only improve operational efficiency but also provide a competitive edge to operators who seek better control over their operations. By focusing on integrating new technologies and offering customizable solutions, manufacturers can meet the evolving needs of the market.
Market Segmentation Analysis:
The mechanical fracturing trailer market is segmented based on product type, application, power source, end-user, and technical type, each playing a significant role in shaping its growth.
By Product Type, the market includes single pump, dual pump, and multi-pump trailers. Multi-pump trailers are expected to lead due to their higher efficiency in handling larger-scale fracturing operations.
- For instance, multi-pump trailers are preferred by companies like ProPetro and CNPC for their advanced fracturing fleets, as these units are specifically designed to support high-volume, simultaneous pumping operations at complex well sites.
By Application, the market is primarily driven by the oil and gas sector, which remains the dominant user of mechanical fracturing trailers. Mining and construction also represent growing segments, with trailers required for various industrial and infrastructural projects.
By Power Source, the diesel-powered trailers continue to hold a significant share, though electric and hybrid-powered trailers are gaining popularity due to rising environmental concerns and regulatory pressure for cleaner solutions.
- Baker Hughes, for example, has introduced electric and hybrid fracturing solutions to reduce emissions and improve energy efficiency, while FIDMASH has developed equipment options that can be powered by electricity or natural gas, directly addressing environmental and regulatory demands1
By End-User, the market is divided into onshore and offshore segments. Onshore applications dominate, driven by large-scale fracking operations in regions like North America. Offshore applications are increasing, driven by the growing exploration activities in offshore oil and gas fields.
By Type (Technical), hydraulic fracturing trailers lead the market due to their widespread use in various fracturing processes. Nitrogen and acid fracturing trailers cater to specialized needs, further diversifying the market offerings.
Segmentation:
By Product Type
- Single Pump Trailer
- Dual Pump Trailer
- Multi-Pump Trailer
By Application
- Oil and Gas
- Mining
- Construction
- Others
By Power Source
- Diesel
- Electric
- Hybrid
By End-User
- Onshore
- Offshore
By Type (Technical)
- Hydraulic Fracturing Trailers
- Nitrogen Fracturing Trailers
- Acid Fracturing Trailers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America: Market Leader
North America holds the largest market share in the mechanical fracturing trailer market, primarily due to the robust demand from the United States and Canada. The region's established oil and gas industry, particularly in shale gas extraction, has led to extensive use of hydraulic fracturing equipment, including mechanical fracturing trailers. North America accounts for approximately 45% of the global market share, driven by the continuous exploration and production of unconventional oil and gas reserves. The presence of key industry players and advanced technologies has further supported market growth in this region. Increased adoption of energy-efficient and environmentally compliant trailers, alongside a rise in automation, continues to drive demand. The continued expansion of fracking operations in shale-rich regions like the Permian Basin further solidifies North America's market dominance.
Asia-Pacific: Rapid Growth Potential
The Asia-Pacific region is expected to experience the highest growth rate in the mechanical fracturing trailer market over the forecast period. This region's market share currently stands at around 20%, but it is anticipated to increase significantly as countries like China, India, and Indonesia ramp up investments in oil and gas exploration. With a rising demand for energy and increased focus on domestic resource development, these countries are turning to hydraulic fracturing technologies to tap into their shale gas reserves. The growing trend of industrialization, alongside government efforts to boost local oil and gas production, creates a promising outlook for mechanical fracturing trailers. As regional operators expand their operations, there is a growing need for advanced equipment that can enhance productivity and reduce operational costs.
Middle East and Africa: Expanding Oil and Gas Exploration
The Middle East and Africa hold a significant share in the mechanical fracturing trailer market, with the region contributing around 18% to the global market. The Middle East, with its rich reserves of conventional oil and gas, has been slow to adopt hydraulic fracturing techniques compared to other regions. However, as exploration expands into unconventional reserves, such as those in Saudi Arabia, the UAE, and Algeria, the demand for fracturing equipment is increasing. The African market is also poised for growth as countries like South Africa and Nigeria continue to explore untapped shale gas resources. The combination of strong governmental support for energy sector development and rising investments in hydraulic fracturing technologies will drive market growth in this region. The increasing shift towards advanced equipment and more efficient operational practices will further fuel demand for mechanical fracturing trailers in the coming years.
Key Player Analysis:
- Baker Hughes
- Basic Energy Services
- C&J Energy Services
- Calfrac Well Services
- FTS International
- Halliburton
- Keane Group
- Key Energy Services
- Liberty Oilfield Services
- Nabors Industries
- National Oilwell Varco
- Nextier Oilfield Solutions
- Nine Energy Service
- Pioneer Energy Services
- ProPetro Holding Corp
- RPC Inc.
- Schlumberger
- Superior Energy Services
- Trican Well Service
- Weatherford International
Competitive Analysis:
The mechanical fracturing trailer market is highly competitive, with several key players driving innovation and growth. Major companies such as Halliburton, Schlumberger, and Caterpillar dominate the market by offering advanced equipment with enhanced efficiency, durability, and automation features. These companies focus on developing energy-efficient trailers that comply with stringent environmental standards, meeting the increasing demand for sustainability. Smaller players also contribute by offering customized and modular trailer solutions, catering to specific regional needs. Market competition is intensifying as companies strive to enhance their product offerings with cutting-edge technologies, such as real-time monitoring and remote control capabilities. With the rise in global shale gas exploration, the demand for advanced mechanical fracturing trailers continues to grow, further fueling the competitive landscape. Manufacturers are differentiating themselves through product innovation, customer service, and after-sales support, aiming to maintain a strong foothold in this rapidly expanding market.
Recent Developments:
- In March 2025, Caterpillar Oil & Gas introduced the Caterpillar® Gas Mechanical System (GMS), a new power solution specifically designed to maximize efficiency and performance in mechanical fracturing trailer operations. This launch demonstrates Caterpillar’s ongoing commitment to innovation in the oil and gas sector, offering advanced technology to enhance hydraulic fracturing processes.
- In July 2024, Schlumberger announced the planned acquisition of ChampionX in an all-stock transaction, expected to close in the fourth quarter of 2024 or the first quarter of 2025, pending regulatory approvals.This acquisition aims to enhance Schlumberger's capabilities in the mechanical fracturing trailer market.
Market Concentration & Characteristics:
The mechanical fracturing trailer market is characterized by a moderate level of concentration, with a few large players dominating the landscape, including industry leaders like Halliburton, Schlumberger, and Caterpillar. These companies control a significant portion of the market, leveraging their established reputations and comprehensive product portfolios to maintain their position. The market also includes smaller, regional manufacturers offering specialized and customizable solutions tailored to specific customer needs. This fragmentation allows for innovation, as smaller players introduce modular designs and energy-efficient systems to address growing sustainability demands. Companies compete based on technological advancements, product performance, and service offerings, while focusing on maintaining compliance with strict environmental and safety regulations. With the ongoing demand for enhanced operational efficiency and cost reduction, the market is witnessing continuous product evolution driven by both large and niche players.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, Power Source, End-User and Type (Technical). It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The mechanical fracturing trailer market will continue to grow as demand for unconventional oil and gas extraction increases globally.
- Technological advancements will drive the development of smarter trailers with automated systems and real-time monitoring capabilities.
- Environmental regulations will lead to greater adoption of energy-efficient and eco-friendly trailers.
- The market will see a rise in modular and customizable trailer solutions to meet diverse operational needs.
- As shale gas exploration expands, particularly in emerging markets, regional demand for mechanical fracturing trailers will increase.
- Increased investment in hydraulic fracturing technologies will boost demand for advanced mechanical fracturing trailers.
- Companies will prioritize reducing operational costs, driving further innovation in energy-efficient trailer designs.
- Market competition will intensify, with both major players and smaller manufacturers innovating to offer better products and services.
- The rise of digitalization in oil and gas operations will enhance trailer performance and operational efficiency.
- Growth in the Asia-Pacific and Middle East regions will provide new opportunities for manufacturers to expand market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mechanical Fracturing Trailer Market
What factors are driving the growth of the Mechanical Fracturing Trailer Market?
What are some challenges faced by the Mechanical Fracturing Trailer Market?
Who are the major players in the Mechanical Fracturing Trailer Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mechanical Fracturing Trailer Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mechanical Fracturing Trailer Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2646 million → 2032: USD 3999.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mechanical Fracturing Trailer Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mechanical Fracturing Trailer Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mechanical Fracturing Trailer Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mechanical Fracturing Trailer Market Drivers
- 3.3 Mechanical Fracturing Trailer Market Restraints & Challenges
- 3.4 Mechanical Fracturing Trailer Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mechanical Fracturing Trailer Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mechanical Fracturing Trailer Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mechanical Fracturing Trailer category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mechanical Fracturing Trailer Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mechanical Fracturing Trailer Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mechanical Fracturing Trailer market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mechanical Fracturing Trailer Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mechanical Fracturing Trailer Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mechanical Fracturing Trailer Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mechanical Fracturing Trailer (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mechanical Fracturing Trailer Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mechanical Fracturing Trailer Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mechanical Fracturing Trailer Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mechanical Fracturing Trailer Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mechanical Fracturing Trailer Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mechanical Fracturing Trailer Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mechanical Fracturing Trailer Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mechanical Fracturing Trailer Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mechanical Fracturing Trailer Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
