
Market Overview
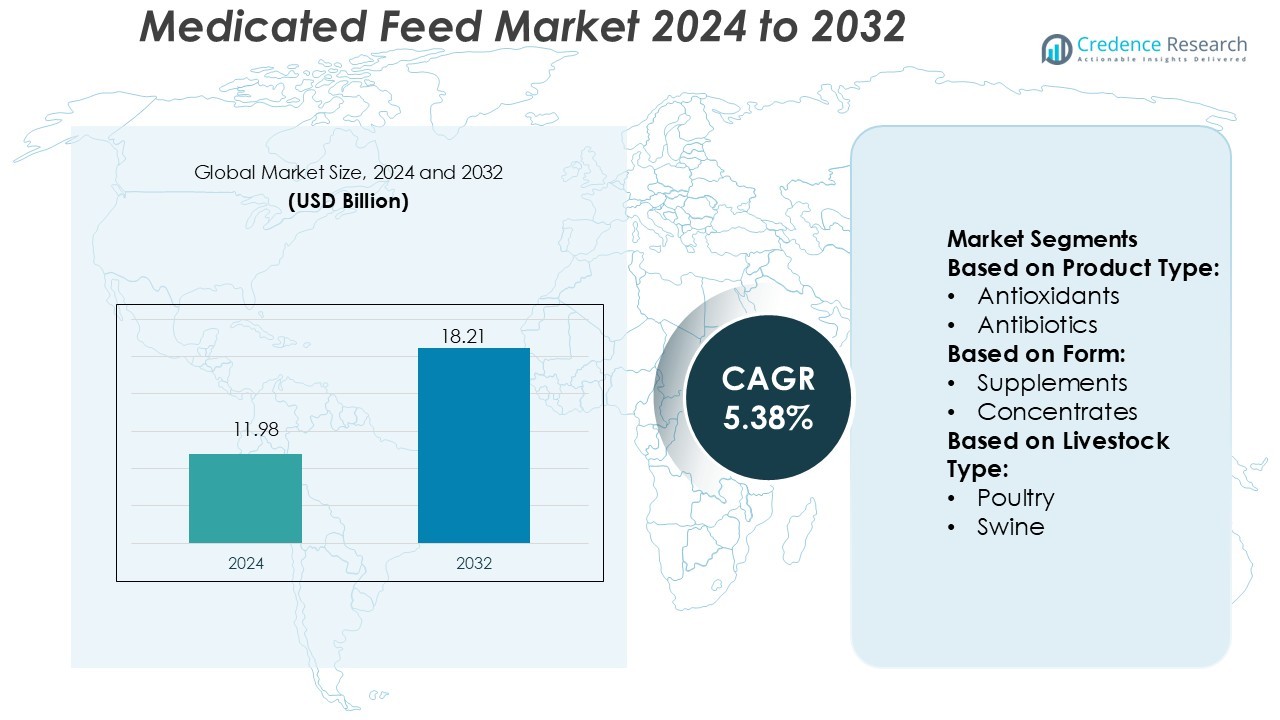
Medicated Feed Market size was valued USD 11.98 billion in 2024 and is anticipated to reach USD 18.21 billion by 2032, at a CAGR of 5.38% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medicated Feed Market Size 2024 | USD 11.98 Billion |
| Medicated Feed Market, CAGR | 5.38% |
| Medicated Feed Market Size 2032 | USD 18.21 Billion |
The Medicated Feed Market is highly competitive, with major players such as Cargill, Archer Daniels Midland Company (ADM), BASF SE, Alltech, Biomin Holdings, Ajinomoto Eurolysine, Bentoli, Bioseutica, Champrix, and Adilisa Holding Group leading global operations. These companies focus on research-driven product development, sustainable feed formulations, and expansion across emerging livestock markets. North America dominates the market with a 34% share, supported by advanced animal health infrastructure, high awareness of feed safety, and strong presence of multinational feed producers. Strategic investments in antibiotic alternatives, precision nutrition, and region-specific formulations further strengthen North America’s leadership in global medicated feed production and distribution.
Market Insights
- The Medicated Feed Market was valued at USD 11.98 billion in 2024 and is projected to reach USD 18.21 billion by 2032, expanding at a CAGR of 5.38%.
- Rising livestock disease cases and growing demand for antibiotic-free animal nutrition remain the key growth drivers.
- The market is witnessing trends such as adoption of probiotic-based formulations, digital monitoring tools, and precision feed technologies.
- High production costs and regulatory restrictions on antibiotic use act as key restraints for smaller feed producers.
- North America holds 34% of the global share, while Asia-Pacific records the fastest growth, supported by livestock expansion and aquaculture demand; among segments, multi-layer and enzyme-based formulations account for the largest share due to efficiency and performance benefits.
Market Segmentation Analysis:
By Product Type
Antibiotics dominate the Medicated Feed Market with a 36% share, driven by their widespread use in disease prevention and performance enhancement across poultry and swine sectors. They help reduce mortality rates and improve feed efficiency in intensive livestock systems. However, rising regulatory scrutiny over antimicrobial resistance is pushing demand for probiotics and prebiotics, which account for a growing share. These alternatives promote gut health and immunity naturally. Amino acids and enzymes support nutritional balance, while antioxidants extend feed shelf life and stability, enhancing overall animal productivity and feed quality.
- For instance, Biomin Holdings launched its Digestarom DC range, demonstrating a 6.5% improvement in feed conversion ratio and a 12% reduction in pathogenic bacteria in broiler trials across Europe.
By Form
Premix feeds lead the market with a 42% share, favored for their precise nutrient composition and ease of blending with bulk feed. They ensure uniform dosage delivery and support large-scale livestock production systems. Supplements and concentrates follow, offering flexibility for small and medium farmers aiming to enhance feed performance without full formulation changes. Base mixes gain adoption among integrated producers due to simplified logistics and consistency in feed conversion. The shift toward standardized premix solutions reflects producers’ focus on productivity optimization and reduced feed variability.
- For instance, Cargill opened a 220,000 square-foot premix and nutrition facility in Lewisburg, Ohio, which features gram-level precision dosing hoppers and four segregated production lines that can each complete a mix in about one hour.
By Livestock Type
Poultry holds the largest market share at 45%, supported by the rapid growth of broiler and layer production across emerging economies. High feed conversion rates and disease prevention needs drive antibiotic and enzyme inclusion in poultry diets. Swine represent the second-largest segment, where medicated feeds aid in gut health and weight gain efficiency. Aquaculture shows strong growth, supported by rising fish farming and probiotic-based feed demand. Other livestock types, including cattle and sheep, contribute steadily through nutritional supplementation and preventive healthcare programs.
Key Growth Drivers
Rising Livestock Disease Incidence
Increasing prevalence of bacterial, parasitic, and viral infections among livestock is driving medicated feed adoption. Farmers use antibiotic- and enzyme-based feeds to improve immunity and recovery rates. Demand is strong in poultry and swine sectors where respiratory and digestive diseases are common. For instance, the European Food Safety Authority reported over 40% of poultry health issues linked to bacterial infections, reinforcing the need for medicated feed. This trend supports higher productivity and reduces mortality, enhancing profitability for commercial farms.
- For instance, Ajinomoto Eurolysine (now part of Ajinomoto Animal Nutrition Europe S.A.S.) developed its AjiPro™-L lysine formulation featuring 80% rumen bypass and 64% intestinal bioavailability, ensuring more essential amino acid reaches the intestine for absorption.
Growing Demand for High-Quality Animal Protein
Expanding global meat and dairy consumption is boosting the need for animal health management through medicated nutrition. Consumers are more aware of food safety, driving stricter farm-level health standards. Medicated feed ensures faster growth and safer end products by controlling disease outbreaks. For instance, the U.S. Department of Agriculture observed a 25% increase in medicated feed use in poultry farms between 2020–2024 to maintain protein quality standards. This shift supports sustainable animal productivity and long-term food supply stability.
- For instance, Champrix introduced its Champ-Green antibiotic-free essential oil blend, which independent trials report reduced E. coli counts by 25 CFU/g in broiler gut samples under controlled conditions.
Expansion of the Livestock Sector in Emerging Economies
Developing nations like India, Brazil, and Vietnam are witnessing rapid livestock expansion, supported by government subsidies and private sector investments. Rising incomes and urbanization fuel higher meat and dairy demand, encouraging farms to adopt preventive feed solutions. For instance, India’s livestock output grew 7% annually between 2019–2023, with increasing reliance on medicated concentrates to improve animal performance. These regions offer significant growth opportunities for feed manufacturers due to favorable regulations and expanding distribution networks.
Key Trends & Opportunities
Shift Toward Natural and Antibiotic-Free Formulations
Growing regulatory restrictions on antibiotic use have accelerated the shift toward probiotics, prebiotics, and enzyme-based medicated feeds. Producers are investing in natural additives to sustain gut health and immunity. For instance, DSM Animal Nutrition launched a probiotic feed additive line in 2023 to replace conventional antibiotics. This trend supports cleaner production and aligns with consumer demand for residue-free animal products.
- For instance, Adilisa Holding Group operates a fully automated additives production line with a capacity of 3,000 metric tons per month and a pre-initiator feed line at 700 metric tons per month.
Integration of Precision Livestock Nutrition
Digital monitoring and smart feeding technologies are enabling customized medicated feed formulations. Precision nutrition improves dosage accuracy, minimizes wastage, and ensures timely disease prevention. For instance, Cargill introduced digital feed monitoring platforms that analyze animal health data and adjust medication levels automatically. Such innovations enhance efficiency and profitability for large-scale livestock operations.
- For instance, Alltech’s InTouch toolkit, comprising a control unit, mobile app, and online dashboard, enabled a finishing beef enterprise to reduce feed mixing errors by 96%, while maintaining consistent ration loading and mixing times across multiple operators.
Expansion of Aquaculture Medicated Feed
Rising aquaculture production in Asia and South America presents a strong opportunity for medicated feed makers. Controlled medication through feed improves water quality and reduces disease spread. For instance, Skretting developed medicated fish feed variants targeting bacterial infections in salmon and tilapia. The expansion of sustainable aquaculture is likely to support future market growth.
Key Challenges
Regulatory Restrictions on Antibiotic Use
Stringent global regulations limit the inclusion of antibiotic-based compounds in animal feed. The European Union and U.S. FDA impose restrictions on non-therapeutic antibiotic applications to prevent antimicrobial resistance. For instance, the EU banned preventive antibiotic feed use since 2022, forcing producers to reformulate products. Compliance increases R&D costs and limits product flexibility, challenging smaller manufacturers.
High Cost of Medicated Feed Formulation
Medicated feed production requires precision dosing, quality control, and pharmaceutical-grade ingredients, increasing manufacturing expenses. Fluctuating raw material prices and storage constraints further strain profit margins. For instance, amino acid and enzyme prices rose by over 15% globally in 2023, raising production costs for medicated feed producers. These financial pressures hinder adoption among small-scale farmers in developing markets.
Regional Analysis
North America
North America holds the leading position with a 34% market share in the global medicated feed market. The United States and Canada dominate due to advanced livestock management practices and strong demand for high-quality meat and dairy. The presence of major feed producers, including Cargill and ADM, supports innovation in antibiotic alternatives and precision nutrition. Rising concerns about zoonotic diseases and stricter food safety regulations drive continuous product development. The region’s well-established distribution channels and high adoption of customized formulations sustain its competitive edge and long-term growth potential.
Europe
Europe accounts for 27% of the global medicated feed market, driven by strict regulations and growing emphasis on antibiotic-free feed. Countries such as Germany, France, and the Netherlands lead production due to advanced research and high animal welfare standards. Manufacturers increasingly invest in probiotics, enzymes, and phytogenic additives to comply with EU feed directives. For instance, regional players like De Heus and Nutreco focus on residue-free formulations to meet consumer expectations. The mature livestock industry, combined with strong government monitoring, sustains Europe’s steady market share and innovation-driven development.
Asia-Pacific
Asia-Pacific captures 29% of the global medicated feed market, making it the fastest-growing region. Rapid livestock expansion in China, India, and Vietnam drives significant feed demand. Government-backed disease prevention programs and rising meat consumption accelerate adoption. Multinational companies are expanding production facilities to cater to local needs. For instance, Alltech and Charoen Pokphand Group increased medicated feed output to meet regional livestock growth. Increasing aquaculture activity and urban dietary changes also support expansion. The combination of economic development and evolving animal health infrastructure enhances the region’s global influence.
Latin America
Latin America holds 6% of the global medicated feed market, supported by a robust livestock export industry. Brazil and Mexico lead regional demand, driven by poultry and beef production growth. Rising awareness about disease control and feed efficiency boosts the use of medicated concentrates and supplements. For instance, Brazilian feed producers are adopting probiotics to enhance export compliance with EU regulations. Despite infrastructure challenges, increasing foreign investments in feed mills and R&D facilities strengthen the region’s production capacity and competitiveness in global animal health nutrition.
Middle East & Africa
The Middle East & Africa region represents 4% of the global medicated feed market, showing gradual expansion. Growing poultry and dairy farming activities in Saudi Arabia, Egypt, and South Africa stimulate feed demand. Governments are investing in livestock vaccination and feed safety programs to reduce disease outbreaks. International feed manufacturers are entering partnerships with local cooperatives to improve access to medicated formulations. Despite limited manufacturing capacity, the region benefits from increasing awareness of animal health management, supported by imports of veterinary-grade feed additives and supplements.
Market Segmentations:
By Product Type:
- Antioxidants
- Antibiotics
By Form:
- Supplements
- Concentrates
By Livestock Type:
- Poultry
- Swine
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Medicated Feed Market features key players such as Biomin Holdings, Cargill, Ajinomoto Eurolysine, Champrix, Adilisa Holding Group, Alltech, BASF SE, Bentoli, Bioseutica, and Archer Daniels Midland Company (ADM). The Medicated Feed Market is characterized by continuous innovation, strategic alliances, and a strong focus on sustainable livestock nutrition. Companies invest heavily in research and development to create antibiotic-free formulations and enhance animal immunity through probiotics, enzymes, and amino acids. Mergers, acquisitions, and regional expansions strengthen global market penetration, while digital technologies support precision feeding and disease management. Manufacturers increasingly collaborate with veterinary institutions and farmers to develop customized medicated feed solutions that improve growth efficiency and food safety. This competitive environment fosters rapid product diversification and drives consistent market advancement worldwide.
Key Player Analysis
- Biomin Holdings
- Cargill
- Ajinomoto Eurolysine
- Champrix
- Adilisa Holding Group
- Alltech
- BASF SE
- Bentoli
- Bioseutica
- Archer Daniels Midland Company (ADM)
Recent Developments
- In March 2025, Kemin Industries launched PROSIDIUM™, a new feed pathogen control system based on peroxy acids, at the VIV Asia 2025 trade show. The system uses a novel application method to eliminate pathogens like Salmonella and viruses from animal feed, aiming to improve overall biosecurity and food safety.
- In September 2024, Growel Group launched its new pet food brand, Carniwel, to expand into the pet food market with affordable, premium nutrition for both dogs and cats. Carniwel offers a range of products, including vegetarian options, enriched with superfoods and fresh proteins like chicken and lamb.
- In August 2024, Boehringer Ingelheim India and Vvaan Lifesciences Private Limited formed a strategic distribution partnership for Boehringer Ingelheim's pet parasiticide portfolio.
- In July 2024, Merck Animal Health completed the acquisition of Elanco's aquaculture business for which significantly strengthens its position in the industry by expanding its portfolio of fish health, welfare, and sustainability solutions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Form, Livestock Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for antibiotic-free and probiotic-based medicated feed will continue to rise.
- Precision livestock farming will boost adoption of customized medicated formulations.
- Aquaculture medicated feed will expand due to growing fish farming activities.
- Integration of digital monitoring tools will enhance feed dosing accuracy.
- Emerging economies will drive large-scale investments in livestock nutrition.
- Regulatory reforms will encourage innovation in natural and enzyme-based products.
- Collaborations between feed manufacturers and veterinary firms will strengthen product development.
- Sustainable sourcing of raw materials will become a major competitive factor.
- Increasing awareness of animal health will influence purchasing behavior among farmers.
- Technological advancements in feed processing will improve product efficiency and shelf life.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Medicated Feed Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medicated Feed Market projected to grow between 2025 and 2032?
Which Medicated Feed Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Medicated Feed Market?
Who are the leading companies in the Medicated Feed Market?
Which region commanded the largest share of the Medicated Feed Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11.98 billion → 2032: USD 18.21 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medicated Feed Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medicated Feed Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medicated Feed Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medicated Feed Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medicated Feed Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medicated Feed Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medicated Feed Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medicated Feed Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11.98 billion → 2032: USD 18.21 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medicated Feed Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medicated Feed Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Medicated Feed Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Medicated Feed Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

