
Market Overview
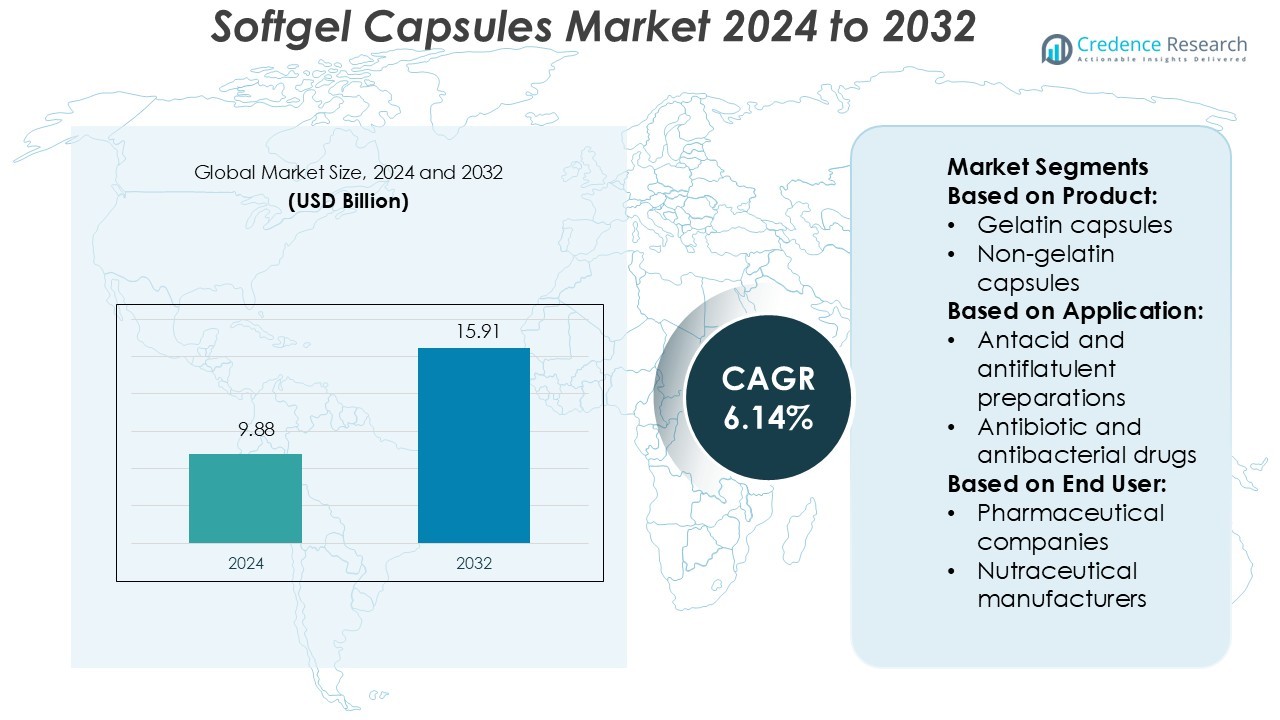
Softgel Capsules Market size was valued USD 9.88 billion in 2024 and is anticipated to reach USD 15.91 billion by 2032, at a CAGR of 6.14% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Softgel Capsules Market Size 2024 | USD 9.88 Billion |
| Softgel Capsules Market, CAGR | 6.14% |
| Softgel Capsules Market Size 2032 | USD 15.91 Billion |
The Softgel Capsules Market is highly competitive, with major players including ACG Worldwide, Bright Pharma Caps, CapsCanada, Capsuline, Chemcaps, Fortcaps Healthcare, Lonza, Natural Capsules, Qingdao Yiqing, and Roquette Frères. These companies focus on enhancing encapsulation technologies, expanding plant-based capsule production, and meeting global nutraceutical and pharmaceutical demand. Lonza leads with advanced HPMC and gelatin capsule innovations, while ACG Worldwide and Roquette Frères emphasize sustainable and clean-label solutions. North America dominates the global market with a 36% share, driven by robust pharmaceutical manufacturing, rising nutraceutical consumption, and strong regulatory frameworks that support advanced dosage form development and innovation.
Market Insights
- The Softgel Capsules Market was valued at USD 9.88 billion in 2024 and is projected to reach USD 15.91 billion by 2032, growing at a CAGR of 6.14%.
- Rising demand for nutraceutical and dietary supplements is driving market expansion, supported by consumer preference for easy-to-swallow and high-bioavailability dosage forms.
- The market is witnessing a strong shift toward plant-based and non-gelatin capsules, reflecting global trends in vegan and allergen-free formulations.
- Key players such as Lonza, ACG Worldwide, and Roquette Frères lead innovation in encapsulation technologies and sustainability-focused manufacturing practices.
- North America dominates with a 36% share, followed by Europe at 28%, while the gelatin capsule segment remains the largest contributor, supported by its superior stability and compatibility across pharmaceutical and nutraceutical applications.
Market Segmentation Analysis:
By Product
Gelatin capsules dominate the Softgel Capsules Market with the largest share, driven by their superior bioavailability and ease of digestion. These capsules are widely used for enclosing oils and fat-soluble drugs, enhancing absorption rates. Pharmaceutical companies favor gelatin-based formats due to their smooth texture, extended shelf life, and compatibility with various formulations. For instance, key manufacturers invest in bovine and porcine gelatin sources to maintain high-quality standards and regulatory compliance. Non-gelatin variants such as HPMC and starch-based capsules are gaining traction among vegan consumers and for moisture-sensitive formulations, further diversifying the market landscape.
- For instance, Qingdao Yiqing Biotechnology Co., Ltd. produces a variety of capsules, including gelatin capsules, that meet various standards, including those from the USP and EP. As of recently, the company reports an annual capsule capacity of up to 60 billion capsules.
By Application
The antibiotic and antibacterial drugs segment holds the dominant share in the Softgel Capsules Market, driven by the need for precise dosage and improved patient compliance. Softgel formulations enhance the bioavailability of active pharmaceutical ingredients, ensuring faster therapeutic effects. For instance, leading pharmaceutical companies develop softgel-based antibiotic solutions for better stability and controlled release in gastrointestinal absorption. Antacid and antiflatulent preparations also witness notable demand due to their rapid action and convenience, while other therapeutic areas such as vitamins and dietary supplements expand usage across preventive healthcare applications.
- For instance, Bright-Poly brand of USDA Organic certified capsules has an annual production capacity of approximately 1.5 billion capsules. These capsules provide a superior oxygen barrier, making them ideal for encapsulating oxygen-sensitive materials like enzymes and live bacteria.
By End User
Pharmaceutical companies represent the leading end-user segment, accounting for the highest market share owing to large-scale adoption of softgel formulations for prescription and over-the-counter drugs. Their focus on patient-friendly delivery systems and enhanced product aesthetics boosts adoption rates. For instance, pharmaceutical manufacturers leverage automated encapsulation technologies to achieve uniform dosing and large-volume production efficiency. Nutraceutical manufacturers follow closely, driven by rising consumer interest in supplements for immunity, cardiovascular health, and nutrition. The “other end use” category includes contract manufacturing organizations supporting small-scale firms with specialized softgel production services.
Key Growth Drivers
Rising Demand for Nutraceutical and Dietary Supplements
Increasing health awareness and preventive healthcare practices are driving demand for nutraceutical softgel capsules. Consumers prefer easy-to-swallow formats for vitamins, omega-3 fatty acids, and herbal extracts. Manufacturers are expanding production capacities to meet this surge. For instance, companies such as Catalent, Inc. have increased softgel manufacturing capabilities to serve the growing supplement market. The focus on lifestyle-related disease prevention and immune health continues to strengthen the demand for nutraceutical-based softgel formulations globally.
- For instance, Roquette introduced MICROCEL® 103 SD and MICROCEL® 113 SD microcrystalline cellulose grades. These grades offer an average water activity (Aw) of no more than 0.2% and 0.1%, respectively, ensuring improved stability for moisture-sensitive formulations.
Technological Advancements in Encapsulation Techniques
Advances in encapsulation technologies are improving the efficiency, stability, and shelf life of softgel capsules. Modern rotary die encapsulation machines allow precise control over fill weight and material thickness. For instance, Lonza Group introduced enhanced encapsulation systems that enable uniform distribution of active ingredients and reduced oxidation rates. These innovations enhance bioavailability and accelerate product development, supporting pharmaceutical and nutraceutical manufacturers in launching diverse formulations quickly and cost-effectively.
- For instance, Fortcaps Healthcare Ltd. uses an automated dipping process to produce over 6.5 billion capsules annually. Their state-of-the-art facilities utilize 16 fully automatic capsule manufacturing machines, ensuring efficient and precise production of Empty Hard Gelatin (EHG) and Pullulan (Satvik certified veg) capsules.
Growing Adoption of Plant-Based and Non-Gelatin Capsules
The shift toward plant-based, vegetarian, and vegan-friendly capsules is accelerating market growth. Consumers increasingly seek products free from animal-derived ingredients, pushing companies to develop HPMC and starch-based alternatives. For instance, Aenova Group launched plant-derived softgel variants suitable for temperature-sensitive and moisture-sensitive formulations. These eco-friendly and allergen-free options appeal to ethical consumers and support regulatory compliance in regions with restrictions on animal-based ingredients.
Key Trends & Opportunities
Expansion in Personalized and Functional Formulations
The rise of personalized nutrition and functional medicine presents new opportunities for targeted softgel formulations. Manufacturers are integrating customized nutrient blends for specific health needs such as immunity, cognition, and energy enhancement. For instance, firms are using advanced R&D tools to tailor formulations with optimized release profiles and taste-masking features. This trend supports differentiation in a competitive market and aligns with the growing consumer preference for individualized health solutions.
- For instance, ACG's ZRO series encapsulation machines, such as the ZRO 90T and ZRO 200T models, offer maximum speeds of 90,000 and 200,000 capsules per hour, respectively.
Strategic Collaborations and Contract Manufacturing Growth
Partnerships between pharmaceutical firms and contract manufacturing organizations (CMOs) are expanding softgel production capabilities. These collaborations help companies scale production, ensure quality, and accelerate product launches. For instance, Thermo Fisher Scientific’s contract manufacturing services have enabled clients to streamline softgel formulation development. The outsourcing trend benefits small and mid-sized enterprises by reducing operational costs and focusing on core competencies such as innovation and marketing.
- For instance, Natural Capsules has significantly expanded its hard-shell capsule manufacturing capabilities. The company now operates facilities with an annual production capacity of 19.50 billion empty hard gelatin (EHG) and HPMC capsules, a figure reported as of the end of FY25.
Key Challenges
High Production Costs and Capital Investment
Softgel capsule manufacturing requires significant investment in specialized equipment and skilled labor. The need for strict temperature and humidity control adds to production costs. For instance, smaller nutraceutical brands often struggle to meet regulatory and quality standards due to limited budgets. These financial constraints hinder scalability and delay product commercialization, particularly in emerging markets with limited access to advanced encapsulation technology.
Regulatory Compliance and Ingredient Limitations
Stringent regulatory standards for excipients, gelatin sourcing, and stability testing pose major challenges. Manufacturers must comply with region-specific guidelines, increasing time-to-market and operational complexity. For instance, variations in FDA, EMA, and CFDA requirements create hurdles for global distribution. Ingredient restrictions, particularly for animal-based gelatin, further limit product flexibility. These challenges demand continuous monitoring and reformulation efforts to ensure consistent market presence across multiple regions.
Regional Analysis
North America
North America holds the dominant share of 36% in the Softgel Capsules Market, supported by a well-established pharmaceutical and nutraceutical manufacturing base. The United States leads due to strong consumer awareness of dietary supplements and advanced drug delivery technologies. For instance, firms like Catalent and Thermo Fisher Scientific operate large-scale facilities offering softgel encapsulation services. Rising health consciousness and FDA-approved production standards drive innovation and demand across both prescription and OTC products. Canada and Mexico also contribute through expanding nutraceutical exports and rising preventive healthcare investments.
Europe
Europe accounts for 28% of the Softgel Capsules Market, driven by growing demand for vegan and plant-based formulations. The region’s strict regulatory framework encourages manufacturers to adopt high-quality, non-gelatin alternatives. For instance, Lonza Group’s Capsugel division in Switzerland focuses on developing HPMC and starch-based capsules for pharmaceutical and nutraceutical clients. Germany, the UK, and France remain major production hubs, supported by advanced R&D facilities and consumer preference for premium supplements. The region’s focus on sustainability and clean-label products continues to boost market penetration across diverse healthcare segments.
Asia Pacific
Asia Pacific holds a 23% share and is the fastest-growing region in the Softgel Capsules Market, fueled by expanding pharmaceutical manufacturing and dietary supplement adoption. Countries like China, India, and Japan lead due to increasing healthcare expenditure and consumer focus on wellness. For instance, India’s nutraceutical producers are investing in softgel production lines to meet export demands. The region benefits from a large population base, supportive government policies, and rising disposable incomes. Growing awareness of herbal and traditional formulations further promotes regional growth.
Latin America
Latin America represents 8% of the market, supported by the rising popularity of nutraceuticals and vitamins among urban consumers. Brazil and Mexico dominate regional sales, benefiting from growing pharmaceutical manufacturing capabilities and import partnerships. For instance, regional companies are adopting advanced encapsulation techniques to produce cost-effective softgel formulations for local and export markets. Favorable trade agreements and expanding retail healthcare networks drive demand. However, limited awareness and economic disparities pose moderate challenges to consistent market growth.
Middle East & Africa
The Middle East & Africa collectively account for 5% of the global Softgel Capsules Market, showing steady expansion through increasing healthcare infrastructure and consumer awareness. The UAE, Saudi Arabia, and South Africa are key growth contributors due to rising pharmaceutical imports and nutraceutical consumption. For instance, several international capsule manufacturers have established regional distribution partnerships to serve local markets efficiently. Government-led healthcare initiatives and a growing middle-class population support steady adoption. However, price sensitivity and limited production capacities restrain faster regional development.
Market Segmentations:
By Product:
- Gelatin capsules
- Non-gelatin capsules
By Application:
- Antacid and antiflatulent preparations
- Antibiotic and antibacterial drugs
By End User:
- Pharmaceutical companies
- Nutraceutical manufacturers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Softgel Capsules Market is characterized by the strong presence of key players such as Qingdao Yiqing, Bright Pharma Caps, Roquette Frères, Fortcaps Healthcare, ACG Worldwide, Natural Capsules, Chemcaps, Lonza, Capsuline, and CapsCanada. The Softgel Capsules Market is defined by continuous innovation, strategic partnerships, and expanding production capacities. Manufacturers are focusing on advanced encapsulation technologies to improve drug bioavailability, stability, and shelf life. The industry is witnessing a growing shift toward plant-based and non-gelatin capsules to meet consumer demand for vegan and allergen-free options. Contract manufacturing and outsourcing are becoming major trends, enabling cost efficiency and faster product launches. Companies are also investing in automation, quality control, and sustainable raw material sourcing to strengthen global competitiveness and align with evolving regulatory and environmental standards.
Key Player Analysis
- Qingdao Yiqing
- Bright Pharma Caps
- Roquette Frères
- Fortcaps Healthcare
- ACG Worldwide
- Natural Capsules
- Chemcaps
- Lonza
- Capsuline
- CapsCanada
Recent Developments
- In May 2025, ACG introduced the personalized capsule machine (PCM), a patented technology for on-demand capsule formulation. In partnership with Art of You, ACG expanded portfolio in personalized nutrition solutions.
- In March 2024, Lonza announced an agreement with Roche to acquire Genentech's biologics manufacturing site in California. This is expected to significantly enhance Lonza's biologics manufacturing capability and make it one of the largest sites globally.
- In December 2023, Amneal Pharmaceuticals, Inc. and Strides Pharma Science Limited together launched ofIcosapent ethyl acid soft gel capsules, a product referencing VASCEPA. The product has been in-licensed from Strides, and commercialized by Amneal in the fourth quarter of 2023.
- In March 2023, VANTAGE NUTRITION, an ACG company, acquired ComboCap, Inc. in the U.S. and BioCap in South Africa, intending to expand their technology and footprint in North America and across the globe.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for plant-based and non-gelatin capsules will continue to increase globally.
- Technological innovations will enhance encapsulation precision and improve bioavailability.
- Manufacturers will invest more in automation to boost large-scale production efficiency.
- Expansion in personalized nutrition will drive customized softgel formulations.
- Regulatory harmonization will simplify cross-border manufacturing and product approvals.
- Growth in nutraceutical consumption will strengthen market presence in developing economies.
- Sustainability-focused manufacturing practices will gain importance across leading firms.
- Strategic mergers and acquisitions will enhance global supply chain capabilities.
- The pharmaceutical sector will increasingly adopt softgels for controlled-release drugs.
- Rising e-commerce and digital health trends will support higher supplement accessibility.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Softgel Capsules Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Softgel Capsules Market projected to grow between 2025 and 2032?
Which Softgel Capsules Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Softgel Capsules Market?
Who are the leading companies in the Softgel Capsules Market?
Which region commanded the largest share of the Softgel Capsules Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Softgel Capsules Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Softgel Capsules Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9.88 billion → 2032: USD 15.91 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Softgel Capsules Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Softgel Capsules Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Softgel Capsules Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Softgel Capsules Market Drivers
- 3.3 Softgel Capsules Market Restraints & Challenges
- 3.4 Softgel Capsules Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Softgel Capsules Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Softgel Capsules Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Softgel Capsules category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Softgel Capsules Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Softgel Capsules Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Softgel Capsules. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Softgel Capsules Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Softgel Capsules Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Softgel Capsules Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Softgel Capsules (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Softgel Capsules
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Softgel Capsules Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Softgel Capsules Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Softgel Capsules Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Softgel Capsules Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Softgel Capsules Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Softgel Capsules Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Softgel Capsules Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Softgel Capsules Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
