
Market Overview
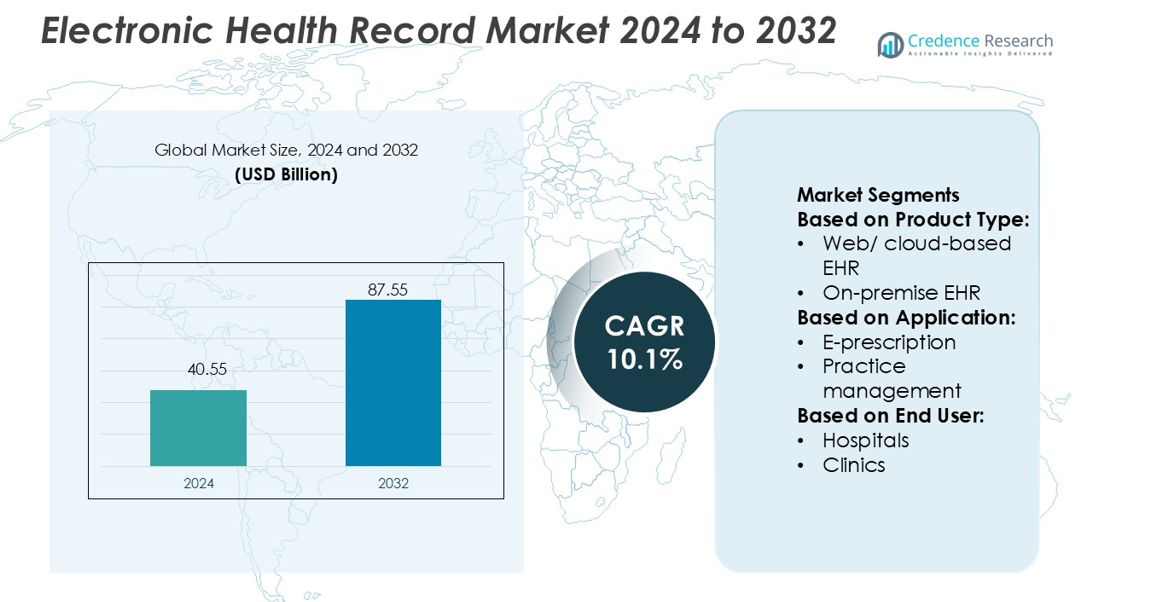
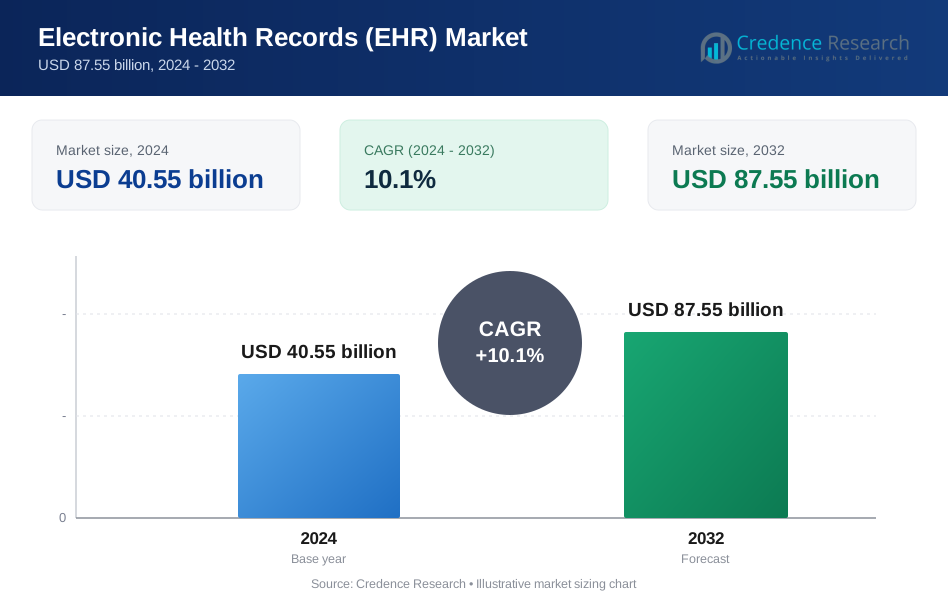
Electronic Health Record Market size was valued USD 40.55 billion in 2024 and is anticipated to reach USD 87.55 billion by 2032, at a CAGR of 10.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Health Record Market Size 2024 | USD 40.55 billion |
| Electronic Health Record Market, CAGR | 10.1% |
| Electronic Health Record Market Size 2032 | USD 87.55 billion |
The Electronic Health Record market includes major vendors offering cloud-based platforms, analytics, and interoperability tools for hospitals and clinics. Key companies expand product portfolios to support e-prescriptions, telehealth, revenue cycle management, and secure patient data access. North America remains the leading region with 38% share, driven by strong digital infrastructure, federal health IT programs, and high adoption among large healthcare networks. Vendors invest in AI-enabled decision support, mobile access, and cybersecurity to meet regulatory standards and reduce clinical workload. Growing integration with imaging systems, labs, pharmacies, and insurance platforms continues to push modernization across the global healthcare ecosystem.
Market Insights
- The Electronic Health Record Market reached USD 40.55 billion in 2024 and will grow to USD 87.55 billion by 2032 at a CAGR of 10.1%.
- Demand rises due to cloud-based EHR platforms, faster digital workflows, e-prescriptions, and automated billing services across large and small healthcare facilities.
- Vendors expand AI-backed analytics, telehealth integration, patient portals, and cybersecurity tools to reduce errors, strengthen compliance, and improve clinical outcomes.
- Data security concerns, high installation cost in small clinics, and slow interoperability in developing countries remain key restraints for wider adoption.
- North America leads with 38% share due to strict IT regulations and hospital digitization, while cloud-based deployment holds a dominant segment share driven by lower upfront expenses and faster upgrades.
Market Segmentation Analysis:
By Product Type
Web/cloud-based EHR holds the dominant share due to easy deployment, lower upfront costs, and remote accessibility. Healthcare providers prefer subscription-based models with real-time updates, automated backups, and reduced IT maintenance. Cloud platforms allow quick scalability for large hospitals and small clinics, improving data exchange between departments. Interoperability with telehealth, imaging systems, and laboratory platforms drives adoption in developed markets. On-premise EHR remains relevant among institutions handling sensitive patient data with strict internal data control policies, but higher setup and hardware requirements slow growth compared to cloud systems.
- For instance, CureMD Healthcare’s cloud EHR supports over 15,000 providers and integrates more than 450 certified labs through a single interface, enabling secure multi-location access with sub-3 second chart loading time for clinicians.
By Application
E-prescription is the leading application due to regulatory encouragement and medication safety benefits. Digital prescriptions reduce handwriting errors, drug-to-drug interactions, and pharmacy dispensing mistakes. Many countries promote e-prescription compliance to track controlled substances and minimize fraud. Practice management and patient management also expand as hospitals integrate scheduling, billing, and clinical workflows in a unified interface. Population health management gains traction for chronic disease tracking and preventive care analytics. Verification, accuracy, and real-time data exchange are key drivers for high adoption across healthcare systems.
- For instance, ModMed platform has powered 1.7 billion clinical diagnoses processed across its specialty-specific EHR systems. ModMed also reports handling 718 million patient check-in encounters recorded in its system to date.
By End-user
Hospitals account for the largest market share because they manage high patient volumes and complex medical records. Multi-department coordination requires centralized access to patient histories, diagnostics, and treatment plans, making EHR essential for workflow continuity. Large hospital networks invest in integrated modules for clinical decision support, imaging data, telehealth, and revenue cycle management. Clinics and ambulatory surgical centers adopt EHR systems to improve appointment tracking and claims processing. Smaller end-users benefit from cloud-based solutions with low upfront investment and simple interfaces tailored for routine care.
Key Growth Drivers
Growing Need for Digital Healthcare Integration
Healthcare providers adopt EHR systems to replace paper-based records and improve data accuracy. Digital records allow coordinated care, faster diagnostics, and real-time patient updates across multiple departments. Governments encourage electronic documentation to reduce clinical errors and maintain unified health databases. Telemedicine growth and remote monitoring also depend on EHR connectivity, pushing hospitals and clinics to upgrade legacy systems. Better interoperability supports data sharing between labs, pharmacies, and imaging centers, improving treatment outcomes and administrative efficiency.
- For instance, McKesson Corporation operates an expansive clinical data exchange network (part of its Prescription Technology Solutions and related businesses) that connects more than 4,800 hospitals and 50,000 physician practices, with automated routing for over 1.5 billion annual lab and prescription transactions.
Government Programs and Compliance Requirements
Many countries enforce digital health regulations to promote transparency, safety, and data reporting. Incentive programs, national e-health initiatives, and mandatory reporting standards drive EHR adoption across public and private sectors. Healthcare facilities that meet compliance rules receive financial support and performance-based incentives, while non-compliant facilities face penalties. Mandated e-prescription, digital billing, and population health reporting increase system usage. These policy frameworks encourage hospitals and small practices to invest in certified EHR platforms and improve long-term documentation quality.
- For instance, eClinicalWorks provides a certified EHR platform that supports more than 180,000 physicians and 850,000 medical professionals across the globe. The platform includes robust e-prescribing capabilities and connects to a vast network of pharmacies.
Rising Demand for Advanced Analytics and Decision Support
Healthcare professionals rely on EHR software to track clinical data and support better decisions. Integrated analytics help identify disease patterns, improve diagnosis accuracy, and monitor chronic patients. AI-based alerts prevent medication errors and highlight high-risk cases. Hospitals use data insights for resource planning, patient flow management, and operational cost control. As preventive care programs expand, data-driven models become essential for population health initiatives. The need for fast access to medical history and structured patient information strengthens EHR adoption worldwide.
Key Trends & Opportunities
Cloud-Based and Mobile EHR Expansion
Cloud platforms gain traction because healthcare providers want flexible, scalable, and low-maintenance systems. Mobile access allows doctors to review patient charts, lab results, and prescriptions from any connected device. Small clinics and ambulatory centers adopt subscription-based solutions to avoid hardware costs. Vendors offer automated updates, cybersecurity tools, and telehealth integration, making cloud systems attractive for modern digital care models. As remote consultation increases, mobile-friendly EHR unlocks new growth opportunities in both emerging and developed markets.
- For instance, CareCloud’s cloud EHR supports more than 40,000 active healthcare providers and handles over 58 million patient records on its network. The CareCloud Companion mobile app enables physicians to access charts, notes, and diagnostic reports with a documented average login-to-record load time of under 3 seconds.
AI, Interoperability, and Automation Growth
EHR systems now include AI for predictive analytics, automated coding, and clinical decision alerts. Interoperability modules allow data exchange between hospitals, pharmacies, imaging centers, and insurance companies. Automated workflows reduce documentation time, helping doctors spend more time on patient care. Health information exchange (HIE) networks expand digital sharing across regions and care settings. These upgrades support personalized medicine, early disease detection, and streamlined billing, improving revenue cycle performance and medical accuracy.
- For instance, Epic’s Care Everywhere network supports clinical data exchange across more than 12,000 healthcare organizations and transfers over 22 million patient records each day.
Opportunity from Value-Based and Preventive Care Models
Global health systems shift from fee-based treatment to value-based outcomes, prioritizing early diagnosis and long-term patient management. EHR platforms support outcome tracking, chronic disease planning, and remote monitoring. Insurers and governments favor data-driven assessments for reimbursement, pushing hospitals to adopt stronger documentation tools. Preventive screening, vaccination monitoring, and wellness programs depend on real-time health records. This transition opens new opportunities for analytics-focused EHR vendors and population health platforms.
Key Challenges
High Implementation Cost and Workflow Disruption
EHR adoption requires software licensing, data migration, staff training, and hardware upgrades. Small clinics often avoid large investments or delay migration from paper systems. Initial deployment disrupts daily workflows, causing slower patient processing and higher administrative pressure. Some facilities struggle with change management as staff adapt to digital entry and new protocols. Although cloud systems reduce costs, full-scale integration remains expensive for large hospitals with legacy infrastructure.
Data Security Risks and Interoperability Issues
EHR systems face cybersecurity threats, including ransomware and unauthorized data access. Hospitals must follow strict data protection standards to prevent breaches and loss of sensitive health records. Many platforms still lack seamless interoperability, causing delays in data sharing across vendors or care settings. Incomplete integration leads to duplicate tests, administrative errors, and limited clinical visibility. These issues reduce user trust and force healthcare providers to invest heavily in security and compliance upgrades.
Regional Analysis
North America
North America leads the Electronic Health Record (EHR) market with 38% share, supported by strong healthcare IT adoption, strict regulatory reporting, and high spending per patient. Hospitals use EHR systems for interoperability, billing accuracy, and clinical decision support. The U.S. benefits from federal incentives, Meaningful Use standards, and cloud-based upgrades in large health networks. Canada focuses on unified patient records and telehealth integration across provinces. Vendors expand analytics, e-prescription, and mobile access to meet physician demand. Rising chronic diseases and digital appointments continue to strengthen regional growth and modernization of legacy systems.
Europe
Europe holds 27% share due to nationwide e-health policies, cross-border data standards, and strong public healthcare funding. The EU promotes secure patient data exchange, e-prescription services, and digital health passports that boost EHR integration across hospitals and clinics. Germany, France, and the U.K. accelerate cloud migration and mobile access for physicians. Governments support cybersecurity, AI diagnostics, and interoperability frameworks to link primary care and specialty centers. Demand increases in Eastern Europe, driven by digital reforms, new hospital infrastructure, and training programs for medical staff.
Asia-Pacific
Asia-Pacific captures 23% share and represents the fastest-growing region. Governments invest in digital health records to improve care access, insurance claims, and population health tracking. China, Japan, India, Australia, and South Korea enhance hospital digitization and adopt cloud-based platforms due to lower cost and scalable deployment. Mobile health, telemedicine, and AI tools integrate with EHRs for remote prescriptions and diagnostics. Private hospitals expand digital workflows to compete on patient experience and efficiency. Large patient populations and rising chronic diseases push demand for secure data management and analytics-backed treatments.
Latin America
Latin America accounts for 7% share with steady progress in Brazil, Mexico, Chile, and Colombia. Public hospitals digitize medical records to reduce paper-based errors, improve billing, and coordinate care. Private clinics adopt cloud-based EHRs for cost savings and faster deployment. Governments work on interoperability and data protection rules to support national digital health frameworks. Telehealth expansion after the pandemic increases demand for secure record access across remote regions. Vendors offer multilingual platforms and mobile portals for patients, boosting engagement and driving modernization in urban healthcare networks.
Middle East & Africa
The Middle East & Africa hold 5% share, driven by modernization of hospital infrastructure and new health insurance systems. Gulf countries invest in smart hospitals, AI-enabled diagnostics, and integrated digital platforms for patient data. Public health programs in Saudi Arabia and UAE expand national EHR networks to improve service quality and reduce medical errors. In Africa, adoption rises in private hospitals and urban clinics using cloud-based EHRs for affordability and scalability. International partnerships, training programs, and donor-funded projects strengthen digital transformation despite infrastructure and connectivity challenges.
Market Segmentations:
By Product Type:
- Web/ cloud-based EHR
- On-premise EHR
By Application:
- E-prescription
- Practice management
By End User:
- Hospitals
- Clinics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Electronic Health Record market remains highly competitive, with key players such as CureMD Healthcare, Greenway Health, LLC, Modernizing Medicine, McKesson Medical-Surgical Inc., eClinicalWorks, CareCloud, Inc., Epic Systems Corporation, Medical Information Technology, Inc., Athenahealth, Inc., and AdvancedMD, Inc. The Electronic Health Record market is driven by advanced digital capabilities, cloud migration, and strong demand for interoperable platforms. Vendors upgrade systems with AI-backed clinical decision support, e-prescription tools, data security layers, and integration with diagnostic labs and pharmacies. Cloud-based EHR solutions grow rapidly due to lower upfront costs and easier deployment for hospitals and clinics of all sizes. Companies focus on patient engagement features such as mobile portals, telehealth connectivity, appointment reminders, and secure access to medical history. Data analytics, population health tools, and regulatory compliance remain major investment areas. Continuous product innovation, strategic partnerships, and regional expansion define competition, while the shift toward unified healthcare information platforms strengthens long-term market growth.
Key Player Analysis
- CureMD Healthcare
- Greenway Health, LLC
- Modernizing Medicine
- McKesson Medical-Surgical Inc.
- eClinicalWorks
- CareCloud, Inc.
- Epic Systems Corporation
- Medical Information Technology, Inc.
- Athenahealth, Inc.
- AdvancedMD, Inc.
Recent Developments
- In January 2025, Maruti Suzuki unveiled the production-spec version of its first electric SUV, the e Vitara, at the Bharat Mobility Global Auto Expo. The vehicle was showcased as a preview for the market.
- In June 2024, Munich Re Life US and Clareto today announced a new digital solution, Automated EHR Summarizer, which provides an intelligent and intuitive synopsis of EHR data. This solution provides the data in two formats that include user-friendly human-readable HTML report and structured digital data for integration into rules, models, and analytics.
- In May 2024, Lohia Auto released the 'Humsafar IAQ,' an electric three-wheeler designed for short-distance travel and last-mile connectivity. It features a range of 185 km per charge, a top speed of 48 kmph, and a seating capacity for one driver and four passengers.
- In January 2024, Eli Lilly introduced LillyDirect, a digital platform designed to streamline purchasing specific medications for patients with prescriptions addressing conditions like diabetes, obesity, and migraine. This platform offers direct access to medications by linking patients with independent teleHealth
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Cloud-based EHR platforms will gain wider adoption due to easier scaling and lower IT costs.
- AI and predictive analytics will support faster diagnosis, automated reporting, and clinical decision support.
- Interoperability standards will improve seamless data exchange between hospitals, clinics, labs, and pharmacies.
- Patient portals and mobile apps will expand self-service access to reports, prescriptions, and appointment management.
- Telehealth integration will become a default feature in EHR systems for remote care and virtual consultations.
- Cybersecurity investments will rise to protect sensitive health records and ensure regulatory compliance.
- Voice recognition and NLP tools will help reduce documentation workload for physicians and support real-time charting.
- Governments will push national digital health programs, boosting adoption in public hospitals and rural networks.
- Data-driven population health tools will help manage chronic diseases and large-scale screening programs.
- Vendors will expand globally with localized languages, regional compliance, and scalable cloud deployment models.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electronic Health Records (EHR) Market?
At what Compound Annual Growth Rate is the Electronic Health Record Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Electronic Health Records (EHR) Market?
What are the key segments within the Electronic Health Records (EHR) Market?
What are some challenges faced by the Electronic Health Records (EHR) Market?
Who are the major players in the Electronic Health Records (EHR) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electronic Health Records (EHR) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electronic Health Records (EHR) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 40.55 billion → 2032: USD 87.55 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electronic Health Records (EHR) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electronic Health Records (EHR) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electronic Health Records (EHR) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electronic Health Records (EHR) Market Drivers
- 3.3 Electronic Health Records (EHR) Market Restraints & Challenges
- 3.4 Electronic Health Records (EHR) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electronic Health Records (EHR) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electronic Health Records (EHR) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electronic Health Records (EHR) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electronic Health Records (EHR) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Electronic Health Records (EHR) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Electronic Health Records (EHR) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electronic Health Records (EHR) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electronic Health Records (EHR) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Electronic Health Records (EHR) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electronic Health Records (EHR) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Electronic Health Records (EHR) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electronic Health Records (EHR) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Electronic Health Records (EHR) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electronic Health Records (EHR) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electronic Health Records (EHR) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electronic Health Records (EHR) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electronic Health Records (EHR) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electronic Health Records (EHR) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electronic Health Records (EHR) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
