
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Metal Abrasives Market Size 2024 | USD 7,200 million |
| Metal Abrasives Market, CAGR | 4.2% |
| Metal Abrasives Market Size 2032 | USD 10006 million |
Market Overview:
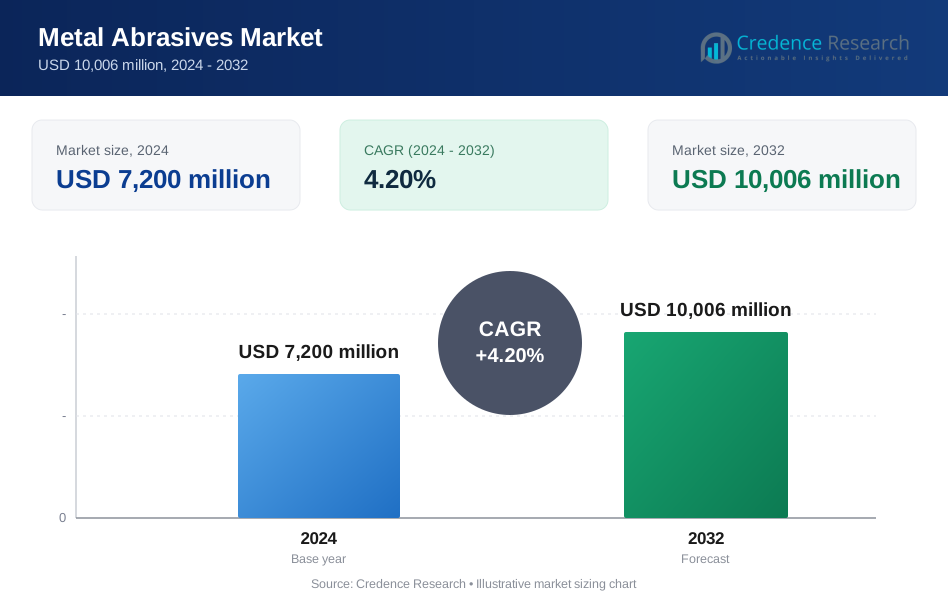
Metal Abrasives Market size was valued at USD 7,200 million in 2024 and is anticipated to reach USD 10006 million by 2032, at a CAGR of 4.2% during the forecast period (2024-2032).
The market is driven by increasing applications in automotive, construction, shipbuilding, and heavy machinery industries where surface preparation and treatment are critical. Rising demand for precision finishing and corrosion-resistant surfaces is pushing manufacturers to adopt advanced abrasive technologies. The preference for metal abrasives over non-metallic counterparts is growing due to their recyclability and higher durability. Stringent regulations on dust emission and workplace safety are also promoting the use of cleaner and more efficient abrasive materials. Manufacturers are investing in R&D to develop eco-friendly products that align with sustainability goals.
Asia Pacific dominates the global market, with strong growth fueled by rapid urbanization, expanding infrastructure, and rising industrial output. Countries across this region are investing in large-scale infrastructure projects, boosting demand for surface treatment solutions. Europe maintains a solid market presence, driven by innovation in surface finishing and the presence of leading automotive OEMs. North America continues to adopt advanced metal treatment technologies across various sectors, maintaining stable demand. Emerging regions such as Latin America and the Middle East are witnessing a gradual rise in demand due to increasing industrialization and modernization of manufacturing facilities. Regional players are strengthening distribution networks and forming strategic alliances to enhance their market reach.
Market Insights:
- The Metal Abrasives Market was valued at USD 7,200 million in 2024 and is projected to reach USD 10,006 million by 2032, growing at a CAGR of 4.2% during the forecast period (2024–2032).
- The market is driven by expanding applications in automotive, construction, shipbuilding, and heavy machinery industries, where precision surface preparation and corrosion resistance are critical.
- Recyclability, high durability, and compliance with environmental regulations are increasing the preference for metal abrasives over non-metallic alternatives across industrial sectors.
- Automation and smart technologies are transforming abrasive equipment, enabling consistent performance, reduced downtime, and improved operational efficiency.
- Rising raw material costs and global supply chain disruptions are pressuring profit margins and limiting scalability, particularly for smaller manufacturers.
- Asia Pacific dominates the global market with 47% share, driven by rapid infrastructure growth and strong demand in China, India, Japan, and South Korea.
- Europe and North America collectively account for 44% of the market, supported by advanced manufacturing, regulatory compliance, and sustained demand from automotive and aerospace industries.
Market Drivers:
Rising Demand from Automotive and Heavy Machinery Industries:
The Metal Abrasives Market is gaining traction due to increased usage in automotive and heavy equipment manufacturing. Surface cleaning, deburring, and shot peening are essential processes that enhance the longevity and performance of critical components. The push toward high-efficiency manufacturing and lightweight vehicles has led to greater reliance on abrasive technologies. Automakers are incorporating advanced surface preparation techniques to improve coating adherence and corrosion resistance. The rise in electric vehicle production is creating new opportunities for abrasive applications. It is becoming essential in achieving high-quality surface finishes and ensuring part durability.
Infrastructure Development and Industrial Expansion Boosting Consumption:
The global expansion of infrastructure projects is significantly contributing to the Metal Abrasives Market. Construction and fabrication activities require abrasive materials for structural steel preparation, rust removal, and concrete surface treatment. Developing nations are investing in transportation, energy, and urban infrastructure, fueling the demand for abrasives. The rise in shipbuilding, railways, and bridges also supports the market's growth trajectory. It supports faster project completion by offering efficient surface treatment solutions. Industries prefer metal abrasives for their recyclability, cost-effectiveness, and performance consistency in demanding environments.
- For instance, India’s Bharatmala Pariyojana for road development and the Smart Cities Mission have led to increased use of high-quality abrasives for cutting and drilling concrete and granite, while the U.S. Census Bureau reported a surge in construction expenditure, driving demand for metal abrasives in cleaning and surface preparation for infrastructure projects.
Increased Focus on Sustainable and Recyclable Abrasive Solutions:
Sustainability concerns are driving the adoption of metal abrasives over non-metallic alternatives. Metal abrasives can be reused multiple times, reducing overall material waste and cost. The market is seeing a shift towards products that comply with environmental and workplace safety regulations. Regulatory agencies are imposing stricter dust emission standards, prompting industries to invest in cleaner technologies. It is aligning with broader global efforts to minimize environmental impact and promote circular economy practices. Manufacturers are redesigning abrasive solutions to meet efficiency and sustainability targets.
- For instance, Imerys has joined the Sustainable European Abrasive Manufacturers (SEAM) program to improve the sustainability of its abrasive products, and the Indian government has mandated minimum recycled content in new non-ferrous metal products, promoting recycling and circular economy practices in the abrasives sector.
Technological Advancements in Abrasive Equipment and Automation:
The integration of automation and smart technologies is reshaping the Metal Abrasives Market. Modern blasting systems are equipped with sensors, automated controls, and energy-efficient components to improve process precision. These technologies ensure uniform surface finishes while reducing operational downtime. Equipment advancements are enabling real-time monitoring and predictive maintenance, enhancing overall productivity. It is helping manufacturers lower operational costs and improve product consistency. This trend is encouraging adoption across industries with high throughput requirements.
Market Trends:
Rising Preference for High-Performance and Customizable Abrasive Materials:
The Metal Abrasives Market is witnessing a shift toward high-performance and application-specific abrasive materials. Industries are seeking abrasives that offer higher durability, lower breakdown rates, and better recyclability to improve operational efficiency. Manufacturers are focusing on product customization to meet the distinct requirements of automotive, aerospace, and construction sectors. Demand for premium-grade steel grit and shot that can withstand intensive blasting cycles is growing steadily. It is also prompting suppliers to enhance quality control and consistency in particle size, shape, and hardness. This trend is supporting increased adoption in precision-based and large-scale manufacturing environments.
- For instance, the U.S. Bureau of Labor Statistics notes that steel abrasives are widely used in automotive and aerospace manufacturing processes to achieve consistent surface finishes and improve component durability, reflecting the industry's preference for high-quality, customizable abrasive solutions.
Integration of Automation and Digital Monitoring in Surface Treatment Processes:
Technological innovation is emerging as a key trend influencing the Metal Abrasives Market. Automated blasting systems equipped with digital controls and real-time process monitoring are gaining traction across industries. These systems enable consistent surface preparation, reduced abrasive consumption, and improved safety compliance. It is enabling companies to streamline workflows, reduce labor dependency, and achieve repeatable results. The integration of data analytics and sensor-based monitoring is also enhancing maintenance planning and productivity. Manufacturers are leveraging these advancements to remain competitive in high-volume and quality-sensitive production environments.
- For instance, Wheelabrator provides automated wheelblast and airblast systems for sectors such as aerospace, automotive, and construction, offering complete solutions with digital controls and real-time process monitoring for optimal efficiency and reliability.
Market Challenges Analysis:
Rising Raw Material Costs and Supply Chain Disruptions Impacting Profit Margins:
The Metal Abrasives Market faces challenges due to fluctuating prices of raw materials such as steel and iron. Global supply chain disruptions, including geopolitical tensions and transportation delays, have added volatility to sourcing and logistics. Manufacturers are encountering difficulty in maintaining stable production costs while meeting customer demand. It is pressuring companies to either absorb additional expenses or pass costs onto end-users, affecting competitiveness. Prolonged supply issues may limit availability and delay project timelines for consumers in construction and manufacturing. The lack of stable raw material supply also restricts smaller players from scaling operations.
- For instance, Shilpan Steelcast has implemented strategic supplier partnerships and advanced inventory management, including real-time tracking and just-in-time (JIT) inventory approaches, to ensure a steady supply of high-quality metals and reduce the risk of production delays, helping maintain cost-effectiveness and timely deliveries despite broader market volatility.
Stringent Environmental and Workplace Safety Regulations Limiting Flexibility:
Regulatory frameworks on air quality, dust emissions, and waste disposal are becoming more stringent across key markets. Compliance with environmental standards requires investment in advanced equipment and safer processing methods. It is increasing capital expenditure for manufacturers and creating barriers for new entrants. Companies must upgrade facilities and adopt cleaner technologies to align with sustainability goals. The need for employee safety and reduced exposure to harmful particles further restricts usage of certain abrasive types. These regulatory demands may limit operational flexibility and add complexity to product design and delivery.
Market Opportunities:
Expansion of Infrastructure and Industrial Projects in Emerging Economies:
The Metal Abrasives Market holds significant opportunities in rapidly industrializing regions where infrastructure and heavy manufacturing projects are gaining momentum. Countries in Asia, Latin America, and the Middle East are investing in transportation, energy, and urban development. These large-scale projects demand extensive surface preparation and metal treatment, driving the need for reliable abrasive solutions. It is well-positioned to support these activities with durable, high-efficiency products. Government initiatives supporting industrial growth are creating favorable conditions for abrasive manufacturers to expand their operations. Local production facilities and strategic partnerships can help companies tap into these high-growth markets.
Growth in Demand for Eco-Friendly and Recyclable Abrasive Solutions:
Sustainability is emerging as a key area of opportunity within the Metal Abrasives Market. Industries are seeking recyclable and low-dust abrasive materials to comply with environmental standards and reduce operational waste. This shift is encouraging innovation in product design and material composition. It is enabling manufacturers to differentiate their offerings through environmentally responsible solutions. The demand for cleaner, safer work environments is also promoting the use of advanced blasting systems paired with sustainable abrasives. Companies that invest in green technologies and circular economy practices are likely to gain a competitive edge in this evolving market landscape.
Market Segmentation Analysis:
By Material
The Metal Abrasives Market is segmented into steel shot, steel grit, cut wire, and others. Steel shot leads the segment due to its extensive use in shot blasting, surface cleaning, and peening operations. Its spherical shape and high recyclability make it ideal for repeated use in industrial applications. Steel grit is preferred for aggressive cleaning tasks where rough surfaces and scale removal are required, particularly in construction and heavy machinery. Cut wire abrasives are gaining popularity in precision applications such as aerospace and automotive components due to their consistent size and hardness. It is expanding with demand for customized abrasives that deliver high performance across diverse surface conditions.
By Application
The Metal Abrasives Market is categorized by application into automotive, construction, shipbuilding, aerospace, and heavy machinery. Automotive and construction sectors dominate due to continuous manufacturing, infrastructure development, and refurbishment activities. Shipbuilding relies heavily on abrasives for surface treatment of hulls and structural steel. Aerospace applications demand high-precision abrasives to meet stringent quality and safety standards. Heavy machinery uses abrasives for cleaning and surface conditioning of large metal components. It addresses a wide range of applications by delivering efficiency, material compatibility, and surface consistency across industries.
Segmentations:
By Material
- Steel Shot
- Steel Grit
- Cut Wire
- Others
By Application
- Automotive
- Construction
- Shipbuilding
- Aerospace
- Heavy Machinery
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Strong Demand in Asia Pacific Driven by Manufacturing and Infrastructure Growth
Asia Pacific holds 47% of the global Metal Abrasives Market, making it the leading regional segment. The region's dominance is supported by robust manufacturing output and high-volume infrastructure development across China, India, Japan, and South Korea. Countries in this region continue to expand automotive, shipbuilding, construction, and heavy machinery industries, all of which rely heavily on surface treatment applications. The market benefits from competitive production costs, abundant raw material availability, and rising domestic consumption. It gains further traction from government investments in industrial corridors and energy infrastructure that require durable abrasive solutions. The presence of numerous regional manufacturers enhances supply reliability and intensifies competition.
Europe Maintains Steady Growth with Focus on Innovation and Quality
Europe accounts for 26% of the global Metal Abrasives Market, driven by demand from automotive, aerospace, and foundry sectors. The region’s growth is fueled by advanced manufacturing practices and strict adherence to quality standards, particularly in Germany, France, and Italy. Environmental regulations have accelerated the shift toward recyclable and low-dust abrasives, prompting innovation in product design. It supports sustainable practices through investments in energy-efficient production and precision surface treatment technologies. European manufacturers emphasize automation and high-performance materials to maintain competitiveness. Continued investment in R&D ensures a steady pipeline of advanced abrasive solutions tailored to specific industrial needs.
North America Benefits from Technological Integration and Industrial Resilience
North America holds 18% of the global Metal Abrasives Market, supported by its developed industrial ecosystem and adoption of advanced technologies. The United States and Canada are major contributors, with strong consumption in aerospace, defense, and construction sectors. It is increasingly adopting automated blasting systems and smart abrasive technologies to improve operational efficiency and compliance with workplace safety standards. Regional players invest in sustainable production and localized manufacturing to reduce lead times and enhance supply security. Infrastructure renewal and industrial modernization continue to support steady demand. Strategic collaborations and innovation-driven production are reinforcing North America’s market position.
Key Player Analysis:
- Abrasives Inc.
- Vulkan INOX GmbH
- Silcal Metallurgic Ltd.
- Ervin Industries
- W Abrasives
- Grind well, Norton Ltd
- Abrasive Shot
- 3M India Ltd.
- Macro Group International
- Siambrator Co., Ltd.
- Air blast-Abrasives B.V.
- Metaltec Steel Abrasive
Competitive Analysis:
The Metal Abrasives Market is highly competitive, with leading players focusing on product innovation, capacity expansion, and regional penetration to maintain market share. Key companies such as Winoa Group, Ervin Industries, Abrasives Inc., and Sinto Group are actively investing in advanced manufacturing technologies to improve abrasive performance and durability. It is witnessing consolidation through strategic mergers and acquisitions aimed at expanding global footprints and enhancing product portfolios. Players are also emphasizing the development of recyclable and eco-friendly abrasives to comply with stringent environmental regulations. Local and regional manufacturers contribute to price competitiveness and supply flexibility, especially in emerging markets. Companies are strengthening distribution networks and customer support services to improve market responsiveness. The adoption of automation in surface treatment equipment is also prompting collaboration between abrasive producers and equipment manufacturers to deliver integrated solutions. Continuous R&D investment remains a critical factor in maintaining a competitive edge across industrial applications.
Recent Developments:
- In August 2024, the National Company Law Tribunal (NCLT) in Bengaluru approved the amalgamation of 3M Electro & Communication India Private Limited with 3M India Limited.
- In March 2025, Macro Global announced a strategic partnership with Volume, a leader in open banking payment solutions.
Market Concentration & Characteristics:
The Metal Abrasives Market exhibits moderate market concentration, with a mix of global leaders and numerous regional players operating across key geographies. It is characterized by strong competition based on product quality, price, and performance efficiency. Leading companies maintain a competitive edge through advanced manufacturing technologies, broad product portfolios, and global distribution networks. The market favors firms capable of offering recyclable, high-durability abrasives that align with evolving environmental standards. Entry barriers remain relatively high due to capital-intensive production processes and strict compliance requirements. It continues to evolve through innovation in materials and integration with automated surface treatment systems. Regional players compete by offering customized solutions and maintaining cost-effective supply chains.
Report Coverage:
The research report offers an in-depth analysis based on Material, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Metal Abrasives Market will witness increased demand from automotive and construction sectors due to rising infrastructure development and vehicle production.
- Manufacturers will prioritize eco-friendly and recyclable abrasives to comply with evolving environmental regulations.
- Automation and smart abrasive systems will gain traction, enhancing process control and operational efficiency.
- Advancements in abrasive material technology will lead to products with longer life cycles and higher performance.
- Emerging economies will offer growth opportunities driven by rapid industrialization and capital investment in manufacturing.
- Strategic collaborations between abrasive producers and equipment manufacturers will support integrated surface treatment solutions.
- Customization in abrasive size, hardness, and material type will become a key differentiator for suppliers targeting niche applications.
- Increasing demand for high-precision surface finishing in aerospace and defense will drive innovation in premium-grade abrasives.
- Regional players will expand capacity and distribution to meet growing domestic and export demand in Asia and the Middle East.
- Investment in R&D and digital monitoring tools will play a critical role in product development and quality assurance across industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and future projection of the Metal Abrasives Market?
What industries are driving demand for metal abrasives?
Which region leads the Metal Abrasives Market?
How are companies responding to environmental regulations?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Metal Abrasives Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Metal Abrasives Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,200 million → 2032: USD 10,006 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Metal Abrasives Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Metal Abrasives Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Metal Abrasives Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Metal Abrasives Market Drivers
- 3.3 Metal Abrasives Market Restraints & Challenges
- 3.4 Metal Abrasives Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Metal Abrasives Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Metal Abrasives Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Metal Abrasives category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Metal Abrasives Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Metal Abrasives Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Metal Abrasives market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Metal Abrasives Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Metal Abrasives Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Metal Abrasives Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Metal Abrasives (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Metal Abrasives Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Metal Abrasives Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Metal Abrasives Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Metal Abrasives Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Metal Abrasives Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Metal Abrasives Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Metal Abrasives Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Metal Abrasives Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Metal Abrasives Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
