
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Metal Powders For Additive Manufacturing Market Size 2024 | USD 517.32 Million |
| Metal Powders For Additive Manufacturing Market, CAGR | 20.4% |
| Metal Powders For Additive Manufacturing Market Size 2032 | USD 2,284 Million |
Market Overview:
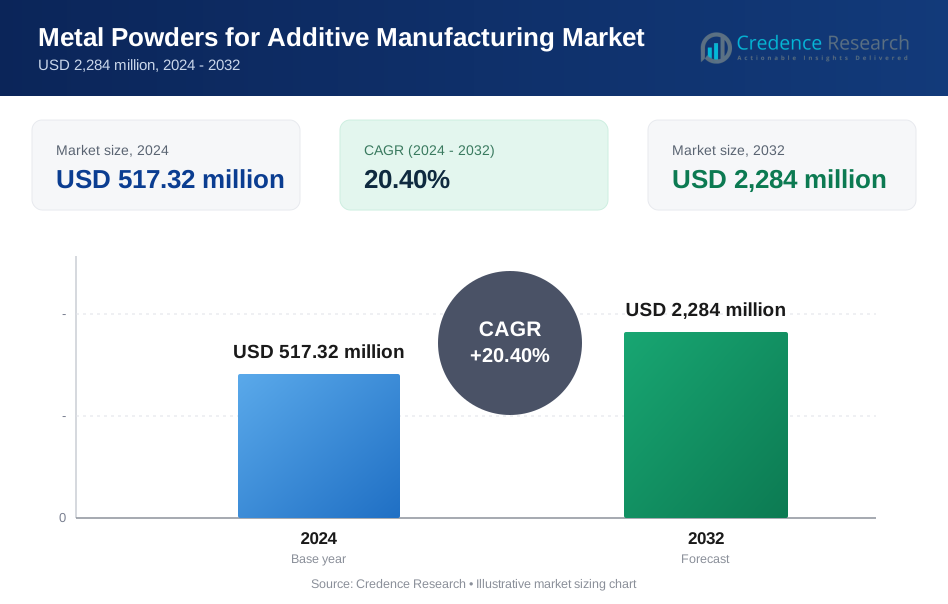
Metal Powders For Additive Manufacturing Market size was valued at USD 517.32 million in 2024 and is anticipated to reach USD 2,284 million by 2032, at a CAGR of 20.4% during the forecast period (2024-2032).
Key drivers propelling the market include the widespread integration of additive manufacturing in industrial production, increasing R&D investments, and advancements in metal powder production techniques. The shift toward mass customization and the demand for cost-effective, on-demand manufacturing solutions are encouraging companies to adopt metal powder-based 3D printing. Titanium, stainless steel, and aluminum powders are witnessing high demand due to their mechanical strength, corrosion resistance, and compatibility with complex geometries. Moreover, technological advancements in binder jetting and powder bed fusion processes are enhancing printing precision and efficiency, further supporting market adoption. The growth of Industry 4.0 and digital manufacturing ecosystems is also fueling the demand for advanced additive manufacturing materials. Additionally, strategic collaborations between powder manufacturers and 3D printer OEMs are fostering innovation and expanding application scopes.
Regionally, North America holds a dominant position in the global Metal Powders for Additive Manufacturing market, supported by the presence of major aerospace and defence manufacturers and a robust technological infrastructure. Europe follows closely, with countries like Germany, the UK, and France investing heavily in additive manufacturing technologies. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, driven by rapid industrialization, government support for advanced manufacturing, and growing adoption of 3D printing in automotive and electronics sectors, particularly in China, Japan, and South Korea. Expanding manufacturing capabilities and the rise of local powder production in Asia are further bolstering regional market growth. Meanwhile, increasing government-backed initiatives in North America and Europe to promote sustainable manufacturing are creating favorable regulatory environments.
Market Insights:
- The market was valued at USD 517.32 million in 2024 and is projected to reach USD 2,284 million by 2032, driven by strong industrial adoption.
- Industries such as aerospace, automotive, and healthcare are increasingly using metal powders to produce lightweight and complex components.
- High demand for titanium, stainless steel, and aluminum powders is driven by their strength, durability, and printability.
- Technological advancements in binder jetting and powder bed fusion are enhancing production efficiency and precision.
- Strategic collaborations between powder manufacturers and 3D printer OEMs are fostering innovation and expanding application scopes.
- North America leads the global market, while Asia-Pacific is set to witness the fastest growth due to rapid industrialization and local manufacturing support.
- Despite strong growth, challenges such as high production costs and lack of standardization remain key barriers to broader adoption.
Market Drivers:
Rising Adoption of Additive Manufacturing Across Industries:
The increasing integration of additive manufacturing in various end-use industries is a primary driver of the metal powders market. Sectors such as aerospace, automotive, healthcare, and energy are rapidly adopting 3D printing to produce lightweight, durable, and geometrically complex components. This shift is reducing dependency on traditional manufacturing methods while improving material efficiency and reducing production time. As industries continue to focus on performance optimization and material savings, the demand for high-quality metal powders tailored for specific applications is expected to grow steadily.
Advancements in Powder Metallurgy and Production Techniques:
Technological innovations in metal powder production methods are enhancing product quality, consistency, and scalability. Techniques such as gas atomization, plasma atomization, and water atomization are enabling the production of spherical, fine-grain powders with superior flowability and uniformity. For instance, Retech Systems LLC has developed Plasma Gas Atomization (PGA) technology, which eliminates previous limitations on scalability and quality, enabling the production of high-quality powders suitable for aerospace and medical applications. These advancements directly contribute to better layer adhesion and structural integrity in printed components. Moreover, the increased availability of customized powder blends and alloy compositions is expanding their application across specialized industrial needs, further driving market expansion.
Increased Focus on Mass Customization and On-Demand Manufacturing:
The growing need for mass customization and on-demand production is fueling the adoption of metal powders in additive manufacturing. For instance, Minnesota-based DI Labs is leveraging Multi Jet Fusion (MJF) technology to deliver customized components efficiently through its Threedom platform, catering to industries such as aeroponics agriculture. Companies are leveraging 3D printing to produce complex parts with minimal lead times, reducing inventory costs and accelerating time-to-market. Metal powders enable manufacturers to create intricate geometries and lightweight components, particularly useful in aerospace and medical implants. This shift towards flexible, digital production methods is expected to strengthen demand for reliable and high-performance metal powders.
Supportive Investments and Strategic Collaborations:
The market is witnessing increased R&D investments and strategic partnerships among powder manufacturers, OEMs, and research institutions. These collaborations are aimed at developing next-generation materials with enhanced mechanical and thermal properties. Government initiatives promoting digital manufacturing, coupled with growing venture capital in additive technologies, are also contributing to market momentum. Such investments are fostering innovation, expanding material portfolios, and enabling wider industrial adoption of metal powder-based 3D printing solutions.
Market Trends:
Growing Preference for High-Performance Alloys:
One of the prominent trends shaping the metal powders for additive manufacturing market is the increasing demand for high-performance alloys such as titanium, nickel, and cobalt-based materials. These alloys offer excellent strength-to-weight ratios, corrosion resistance, and thermal stability, making them ideal for aerospace, defence, and medical applications. Manufacturers are developing advanced alloy compositions to meet specific industry requirements, driving greater specialization within the metal powder supply chain.
Expansion of Binder Jetting and Powder Bed Fusion Technologies:
Binder jetting and powder bed fusion technologies are gaining significant traction in the additive manufacturing sector. These methods offer improved print resolution, faster build rates, and compatibility with a wide range of metal powders. For instance, General Electric (GE) has been advancing its H2 Binder Jet machine to enable mass production across industries like automotive, providing scalable solutions for manufacturers. The growing preference for these techniques is influencing powder producers to refine particle size distribution, morphology, and flow characteristics to optimize performance. As equipment manufacturers continue to enhance printer capabilities, demand for powders tailored to these technologies is rising.
Shift Toward Sustainable and Recyclable Materials:
Sustainability is becoming a central focus in additive manufacturing. The ability to recycle unused metal powders and reduce material waste aligns with global efforts toward sustainable production. For instance, Henkel has partnered with TerraCycle to provide recycling solutions for UV-curable 3D printing resins and adhesives, promoting circularity in additive manufacturing operations. Market players are investing in closed-loop powder handling systems and exploring environmentally friendly powder production methods. This trend is especially prevalent in regions with strict environmental regulations, pushing the industry toward greener solutions without compromising performance.
Rise of Customized and Industry-Specific Powder Solutions:
Another key trend is the development of application-specific metal powders for sectors such as healthcare, automotive, and energy. Companies are collaborating with end-users to create materials with precise mechanical, thermal, and chemical properties. This customization enhances performance and reliability in critical applications, reinforcing the strategic role of material innovation in additive manufacturing. The trend also supports the move toward digital inventory and decentralized production.
Market Challenges Analysis:
High Production Costs and Limited Material Availability:
One of the most significant challenges in the metal powders for additive manufacturing market is the high cost associated with powder production. Advanced techniques such as gas atomization and plasma atomization require substantial capital investment and operational expenses, making the end products expensive. For instance, the SMS Group has developed a Continuous Powder Production Plant that significantly reduces production costs by transforming conventional batch processes into a continuous process, enabling large-scale production of up to 4,000 tons per year. These high costs limit the accessibility of metal powders, especially for small- and medium-scale enterprises. Additionally, the availability of certain critical metals-such as titanium, tantalum, and rare earth elements-remains constrained due to limited global reserves and geopolitical dependencies, affecting consistent supply and pricing stability. This scarcity increases procurement risks for manufacturers and limits long-term production scalability. Moreover, price volatility in raw materials can directly impact profit margins and disrupt supply chains.
Technical Barriers and Standardization Issues:
The lack of standardized quality metrics and performance specifications across different metal powders presents another major challenge. Variability in powder characteristics such as particle size distribution, morphology, and chemical purity can lead to inconsistent printing outcomes and structural defects in finished parts. This inconsistency hampers scalability and reduces confidence among end-users in regulated industries such as aerospace and healthcare. Furthermore, the need for specialized storage, handling, and recycling infrastructure adds operational complexity. The absence of universally accepted certification and quality assurance protocols also slows the adoption of metal powders in mission-critical applications, hindering the market’s full potential. The ongoing shortage of skilled professionals in additive manufacturing further complicates quality control and process optimization. In addition, the long validation cycles required for new materials delay time-to-market for innovative powder solutions.
Market Opportunities:
The Metal Powders for Additive Manufacturing market presents substantial growth opportunities driven by the expanding adoption of 3D printing in emerging industries and the increasing demand for advanced manufacturing capabilities. As industries shift toward lightweight, high-performance, and complex components, the need for specialized metal powders is expected to rise significantly. Emerging applications in energy, marine, and defense sectors are opening new avenues for market expansion, particularly in the production of custom parts with enhanced strength and durability. Furthermore, the ongoing development of new alloy compositions tailored for additive manufacturing is enabling manufacturers to meet diverse performance requirements, creating opportunities for product differentiation and material innovation.
In addition, advancements in additive manufacturing technologies and growing investments in digital manufacturing infrastructure are accelerating the integration of metal powders across various production environments. The rise of Industry 4.0 and smart factories offers a favorable ecosystem for real-time customization, digital inventory, and decentralized production-further boosting the demand for high-quality metal powders. Governments across regions are supporting additive manufacturing through funding, tax incentives, and innovation grants, especially in Asia-Pacific and Europe. This regulatory and financial support is fostering R&D initiatives and encouraging collaborations between powder manufacturers, research institutions, and end-use industries. As the market matures, opportunities will also emerge in the development of sustainable and recyclable metal powders that align with global environmental goals, enabling companies to gain a competitive edge through eco-friendly solutions.
Market Segmentation Analysis:
By Metal Type
The market is categorized into titanium, aluminum, stainless steel, nickel, cobalt, copper, and others. Titanium dominates the segment due to its high strength-to-weight ratio and biocompatibility, making it ideal for aerospace and medical applications. Stainless steel and aluminum are widely used for their cost-effectiveness and mechanical versatility across industrial and automotive sectors. Nickel and cobalt-based alloys are preferred for high-temperature and corrosion-resistant applications, particularly in energy and defense.
By Application
The key application segments include prototyping, tooling, and functional part manufacturing. Functional part manufacturing holds the largest share, driven by the increasing demand for end-use components with complex geometries and performance-critical properties. Prototyping remains essential in design validation and product development, while tooling applications benefit from the customization and precision offered by additive manufacturing technologies.
By End-User
End-users include aerospace and defense, automotive, healthcare, industrial manufacturing, and others. Aerospace and defense lead the market due to the early adoption of metal 3D printing for lightweight, durable components. The healthcare sector is rapidly expanding, with growing use of metal powders for orthopedic implants and surgical instruments. Automotive and industrial users continue to adopt metal powders for efficient, on-demand production and enhanced part performance.
Segmentations:
By Metal Type
- Titanium
- Aluminum
- Stainless Steel
- Nickel
- Cobalt
- Copper
- Others
By Application
- Prototyping
- Tooling
- Functional Part Manufacturing
- Research and Development
- Design and Modeling
By End-User
- Aerospace and Defense
- Automotive
- Healthcare
- Industrial Manufacturing
- Consumer Electronics
- Energy and Power
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
North America accounted for 38% of the global Metal Powders for Additive Manufacturing market in 2023, making it the leading region in terms of market share. The region’s dominance is largely attributed to the strong presence of aerospace, defense, and medical device manufacturers that extensively utilize metal additive manufacturing technologies. The United States leads the market in North America, supported by substantial R&D investments, government-funded initiatives, and a mature industrial base. Key players are actively collaborating with research institutions to develop high-performance alloys and enhance powder quality. Moreover, the rapid adoption of Industry 4.0 practices and the presence of leading 3D printer manufacturers are contributing to the sustained growth of metal powder demand across advanced manufacturing sectors. North America's commitment to technological innovation positions it as a primary driver of global additive manufacturing advancements.
Europe
Europe captured 31% of the global market in 2023, positioning it as the second-largest regional market. Germany, the United Kingdom, and France are the major contributors, driven by strong investments in advanced manufacturing technologies and a well-established automotive and aerospace industry. The European Union’s focus on sustainability and digital transformation is encouraging the integration of additive manufacturing in energy-efficient and environmentally friendly applications. Furthermore, public-private partnerships and innovation-driven funding frameworks are enabling the development of customized metal powders for high-precision and mission-critical components. European manufacturers are also leveraging additive manufacturing to improve supply chain resilience and reduce material waste, further enhancing regional market competitiveness. The region's strategic emphasis on circular economy models supports long-term growth in eco-friendly powder production.
Asia-Pacific
Asia-Pacific held 24% of the global market share in 2023 and is expected to register the fastest growth rate over the forecast period. China, Japan, and South Korea are at the forefront of this regional expansion, driven by rapid industrialization and strong governmental support for smart manufacturing initiatives. Increasing adoption of 3D printing in automotive, consumer electronics, and healthcare sectors is fueling demand for metal powders in the region. Additionally, the development of local powder manufacturing facilities and growing collaborations with global additive manufacturing companies are enhancing supply chain efficiency. The region is also investing in workforce training and infrastructure to support the long-term integration of metal additive manufacturing technologies. Asia-Pacific’s rise as a cost-effective manufacturing hub offers significant opportunities for global market participants.
Key Player Analysis:
- Arcam AB (GE Additive)
- EOS GmbH
- SLM Solutions Group AG
- Renishaw PLC
- Carpenter Technology Corporation
- Sandvik AB
- LPW Technology Ltd.
- ATI Powder Metals
- Hoganas AB
- Praxair Surface Technologies (Linde plc)
Competitive Analysis:
The Metal Powders for Additive Manufacturing market is characterized by the presence of well-established global players and emerging regional manufacturers competing on product innovation, quality, and scalability. Key companies such as Sandvik AB, Höganäs AB, Carpenter Technology Corporation, EOS GmbH, and GKN Additive lead the market through continuous investment in research and development, strategic partnerships, and expansion of production capabilities. These players focus on developing advanced metal powders tailored for specific additive manufacturing processes and end-use applications. Competitive differentiation is driven by product purity, particle morphology, and compatibility with diverse 3D printing technologies. Additionally, collaborations between powder producers and 3D printer manufacturers are enhancing material-process integration and improving overall printing outcomes. Emerging players in Asia-Pacific are intensifying competition by offering cost-effective solutions and expanding local supply chains. The market remains dynamic, with innovation and strategic alliances serving as critical factors for maintaining a competitive edge.
Recent Developments:
- In March 2025, EOS expanded its metal powder range by introducing NickelAlloy IN718 API for the Oil & Gas sector and Nickel NiCP for semiconductor applications. These powders are optimized for use in EOS's Laser Beam Powder Bed Fusion (PBF-LB) systems.
- In November 2024, Continuum Powders qualified reclaimed metal powders for use with Renishaw’s RenAM 500 series machines, promoting sustainability by integrating recycled materials into additive manufacturing processes.
- In April 2024, GE Additive rebranded as Colibrium Additive, retiring the Concept Laser and Arcam EBM legacy brands. This move aims to align with GE Aerospace’s brand identity while maintaining a focus on innovation and customer collaboration.
Market Concentration & Characteristics:
The Metal Powders for Additive Manufacturing market exhibits a moderately consolidated structure, with a few major players holding significant market shares and a growing number of specialized manufacturers entering the space. Established companies such as Sandvik AB, Höganäs AB, and Carpenter Technology Corporation dominate through advanced R&D capabilities, global distribution networks, and strong industry partnerships. The market is characterized by high entry barriers due to the capital-intensive nature of powder production and the need for stringent quality control standards. Product differentiation is primarily based on powder morphology, particle size distribution, purity, and compatibility with various additive manufacturing technologies. The industry also demonstrates a strong focus on innovation, driven by evolving end-user requirements and the rapid advancement of 3D printing systems. Additionally, the market benefits from long-term contracts, particularly in aerospace and medical sectors, where material reliability and certification play a critical role in supplier selection and customer retention.
Report Coverage:
The research report offers an in-depth analysis based on Metal Type, Application, End-user and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for metal powders in additive manufacturing will continue to grow as industries prioritize lightweight, high-strength, and complex components.
- Ongoing advancements in powder production technologies will improve quality, consistency, and cost-efficiency.
- Adoption of metal additive manufacturing will expand across emerging sectors such as energy, marine, and consumer electronics.
- Increased focus on sustainable and recyclable materials will drive the development of eco-friendly metal powder solutions.
- Strategic partnerships between powder manufacturers and 3D printer OEMs will enhance material-process compatibility and performance.
- Customization of metal powders for specific applications will become a key differentiator in meeting end-user requirements.
- Government initiatives promoting digital manufacturing and local production will support market expansion, especially in Asia-Pacific and Europe.
- Growth in decentralized and on-demand manufacturing will boost the need for readily available, high-quality powders.
- Investment in workforce training and infrastructure will strengthen the global supply chain and support technology adoption.
- Innovation in high-performance alloys will unlock new applications and drive long-term market opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Widespread Integration of Additive Manufacturing in Industrial Production
Industries such as aerospace, automotive, and healthcare are increasingly adopting additive manufacturing to produce lightweight, complex, and high-performance components, driving demand for specialized metal powders.
Advancements in Metal Powder Production Techniques
Innovations in powder metallurgy, such as gas and plasma atomization, are improving powder quality, consistency, and scalability, making metal powders more suitable for demanding additive manufacturing applications.
Rising Demand for Mass Customization and On-Demand Manufacturing
The shift toward digital manufacturing and the need for rapid, cost-effective production of customized parts are encouraging companies to use metal powders for 3D printing, enabling flexible and efficient supply chains.
Strategic Collaborations and R&D Investments
Increased partnerships between powder manufacturers, 3D printer OEMs, and research institutions are fostering the development of next-generation metal powders with enhanced properties, expanding application scopes and accelerating market growth.
Growth of Industry 4.0 and Digital Manufacturing Ecosystems
The adoption of smart factories and digital inventory systems is fueling the need for advanced additive manufacturing materials, with metal powders playing a central role in enabling real-time customization and decentralized production.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Metal Powders for Additive Manufacturing market?
What factors are driving the growth of this market?
Which metal powders are in high demand?
Which regions are leading the market?
How is technology improving the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Aerospace and Defense
- 1.2.2 Automotive
- 1.2.3 Healthcare
- 1.2.4 Industrial Manufacturing
- 1.2.5 Consumer Electronics
- 1.2.6 Energy and Power
- 1.2.7 Others
- 1.3 By Metal Type
- 1.3.1 Titanium
- 1.3.2 Aluminum
- 1.3.3 Stainless Steel
- 1.3.4 Nickel
- 1.3.5 Cobalt
- 1.3.6 Copper
- 1.3.7 Others
- 1.4 By Application
- 1.4.1 Prototyping
- 1.4.2 Tooling
- 1.4.3 Functional Part Manufacturing
- 1.4.4 Research and Development
- 1.4.5 Design and Modeling
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 517.32 million → 2032: USD 2,284 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Metal Powders for Additive Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Metal Powders for Additive Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Metal Powders for Additive Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Metal Powders for Additive Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Metal Powders for Additive Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Metal Powders for Additive Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Metal Powders for Additive Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Metal Powders for Additive Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 517.32 million → 2032: USD 2,284 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Metal Powders for Additive Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aerospace and Defense
- 12.3.7.2 Automotive
- 12.3.7.3 Healthcare
- 12.3.7.4 Industrial Manufacturing
- 12.3.7.5 Consumer Electronics
- 12.3.7.6 Energy and Power
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Metal Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Titanium
- 12.4.7.2 Aluminum
- 12.4.7.3 Stainless Steel
- 12.4.7.4 Nickel
- 12.4.7.5 Cobalt
- 12.4.7.6 Copper
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Prototyping
- 12.5.7.2 Tooling
- 12.5.7.3 Functional Part Manufacturing
- 12.5.7.4 Research and Development
- 12.5.7.5 Design and Modeling
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Metal Powders for Additive Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Metal Powders for Additive Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Metal Powders for Additive Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Metal Powders for Additive Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arcam AB (GE Additive)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 EOS GmbH
- 18.4 SLM Solutions Group AG
- 18.5 Renishaw PLC
- 18.6 Carpenter Technology Corporation
- 18.7 Sandvik AB
- 18.8 LPW Technology Ltd.
- 18.9 ATI Powder Metals
- 18.10 Hoganas AB
- 18.11 Praxair Surface Technologies (Linde plc)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

