
Market Overview:
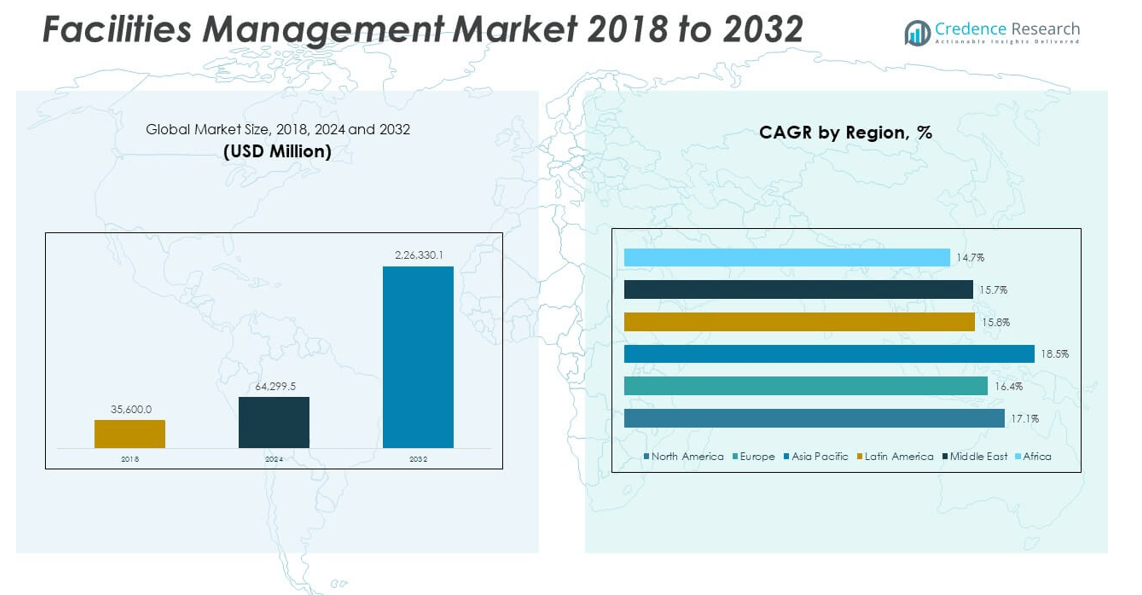
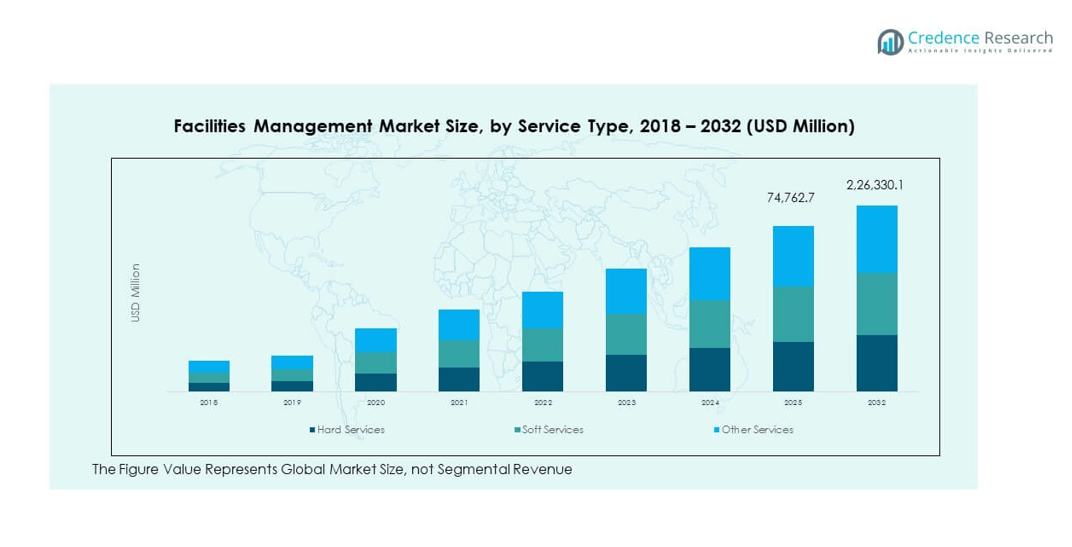
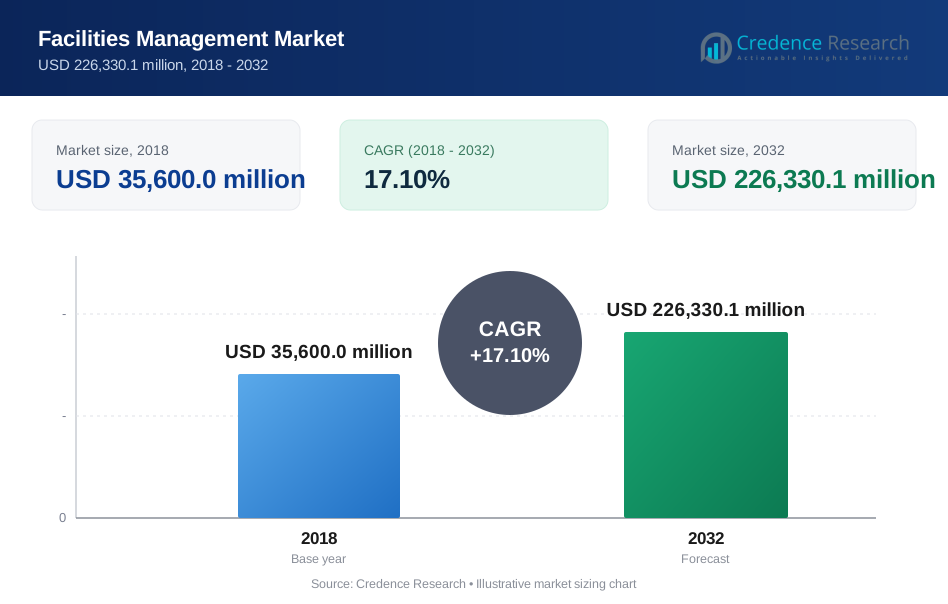
The Global Facilities Management Market size was valued at USD 35,600.0 million in 2018 to USD 64,299.5 million in 2024 and is anticipated to reach USD 226,330.1 million by 2032, at a CAGR of 17.10% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Facilities Management Market Size 2024 | USD 64,299.5 million |
| Facilities Management Market, CAGR | 17.10% |
| Facilities Management Market Size 2032 | USD 226,330.1 million |
Market Insights:
- The Global Facilities Management Market size was valued at USD 35,600.0 million in 2018, reached USD 64,299.5 million in 2024, and is projected to hit USD 226,330.1 million by 2032, registering a CAGR of 17.10% during the forecast period.
- Rising demand for integrated facility services across corporate, healthcare, education, and industrial sectors is a primary driver enhancing operational efficiency and cost-effectiveness.
- Sustainability initiatives and energy management programs are accelerating adoption, with organizations prioritizing eco-friendly practices and compliance with global environmental standards.
- High operational costs and workforce management complexities restrain growth, with service providers under pressure to balance profitability with quality.
- North America leads the market with advanced adoption of digital facility solutions and outsourcing penetration, supported by strong corporate real estate demand.
- Asia Pacific emerges as the fastest-growing region due to rapid urbanization, infrastructure expansion, and growing multinational presence in India and China.
- Europe continues to expand steadily, driven by sustainability mandates and strong emphasis on green building practices, while the Middle East shows potential from mega infrastructure projects.
Market Drivers:
Rising demand for integrated facility services across corporate, industrial, and institutional sectors:
The Global Facilities Management Market is driven by increasing adoption of integrated service delivery models that combine maintenance, cleaning, catering, security, and other operational needs into a single framework. Businesses prefer these bundled solutions to streamline vendor management and reduce administrative burden. It enhances service quality while creating cost efficiencies across large-scale facilities. Demand is strong in commercial real estate, manufacturing plants, healthcare institutions, and educational campuses. Service providers are investing in scalable platforms to meet diverse client requirements. Strong focus on workforce productivity also fuels adoption of integrated offerings. It helps organizations allocate resources more effectively. Outsourcing partners strengthen competitiveness by improving operational agility.- For instance, ISS A/S secured a 7-year integrated facility management contract in August 2024 with the UK Department of Work and Pensions (DWP), covering more than 800 sites. The contract is valued at DKK1.2billion (GBP135million) per year and includes bundled services such as cleaning, technical support, catering, and workplace solutions-all delivered through a unified platform and a single point of contact.
Growing emphasis on sustainability, energy management, and environmentally responsible operations:
Sustainability has become a central driver shaping demand for modern facilities management solutions. Organizations seek service providers capable of implementing energy-efficient practices and green building standards. The Global Facilities Management Market benefits from rising awareness of carbon reduction targets and corporate environmental responsibility. Energy monitoring, waste reduction, and adoption of smart lighting and HVAC systems are key priorities for clients. It allows businesses to cut utility costs while aligning with government regulations. Sustainable facility solutions also enhance brand reputation in competitive markets. Corporate policies increasingly mandate eco-friendly practices across facility operations. Facilities management partners offering advanced sustainability consulting gain strong market traction.- For instance, Sodexo also achieved energy management certification at over 700 managed sites, reflecting its investment in certified sustainability platforms that help clients meet stringent government and corporate carbon reduction targets, per its latest sustainability performance disclosures.
Rapid urbanization and infrastructure development driving facility outsourcing in emerging economies:
Urbanization trends create strong demand for professional facilities management across new office complexes, airports, shopping malls, and industrial parks. The Global Facilities Management Market is witnessing heightened activity in emerging regions where large-scale infrastructure projects are underway. Governments are prioritizing modern urban spaces with advanced safety and maintenance requirements. It pushes enterprises to outsource facility services for effective upkeep of high-value assets. Expansion of IT hubs in India and China fuels demand for end-to-end facility solutions. Rising middle-class populations contribute to growth of organized retail and commercial buildings requiring structured facility support. Service providers leverage this demand to strengthen long-term contracts. Infrastructure expansion ensures sustained growth momentum.Increasing reliance on technology-enabled facilities management platforms and automation:
Technology adoption stands as a major driver influencing market expansion. The Global Facilities Management Market is experiencing a transformation with integration of IoT sensors, predictive maintenance tools, and building automation systems. It helps reduce downtime and ensures seamless facility operations. Digital platforms provide real-time data on energy use, occupancy levels, and equipment health. Cloud-based solutions improve collaboration between providers and clients. Data-driven decision-making enhances accuracy of service delivery. Artificial intelligence and robotics are increasingly deployed for routine tasks such as cleaning and surveillance. Organizations recognize efficiency gains from automation-enabled facility operations. Technology creates competitive differentiation for service providers.Market Trends:
Growing adoption of workplace experience solutions to improve employee engagement and retention:
Modern facility management is no longer limited to maintenance but extends to improving employee well-being and workplace experience. The Global Facilities Management Market reflects this trend through customized workplace solutions designed to increase engagement. Companies are adopting digital desk booking systems, wellness spaces, and ergonomic workplace design. It supports higher employee satisfaction and productivity in hybrid work environments. Demand for smart workspaces has intensified with flexible office models. Providers are offering wellness-focused amenities to attract top talent. Human-centric facility management has become a strong differentiator for employers. Integration of workplace apps with facility services continues to gain traction.- For instance, CBRE launched Host, a workplace experience platform. Host integrates digital desk booking, wellness amenities, and real-time facility feedback features, driving an average user engagement rate of 75%, as measured in global deployments for Fortune 500 clients.
Expansion of specialized services catering to healthcare, education, and critical infrastructure:
Industry-specific facility services are gaining importance, particularly in sensitive sectors such as hospitals, schools, and data centers. The Global Facilities Management Market shows increasing demand for providers with sector expertise. Healthcare facilities require specialized cleaning, biohazard management, and compliance-driven services. Education institutions need security, hygiene, and campus energy optimization. It strengthens the role of specialized providers with certified expertise. Facilities supporting data-driven operations demand uninterrupted uptime, enhancing importance of predictive maintenance. Tailored services reduce risks for mission-critical operations. Providers are expanding capabilities through industry-focused service portfolios. Specialized expertise enhances trust and ensures long-term client contracts.- For instance, Aramark Healthcare+ serviced over 400 acute care hospitals in 2024, providing a validated model for infection control, with the company performing of terminal cleaning in U.S. hospitals during the year. Its sector-focused teams supported compliance with Joint Commission and CDC regulations, while custom workflows ensured zero instances of non-conformance during annual regulatory audits at flagship partner sites.
Increasing outsourcing penetration driven by corporate preference for core business focus:
Organizations across multiple industries continue to outsource non-core facility operations to focus on strategic functions. The Global Facilities Management Market demonstrates rising outsourcing penetration as enterprises emphasize lean structures. It allows companies to reallocate budgets toward innovation and growth initiatives. Outsourced service providers ensure compliance with evolving workplace standards. Long-term contracts and strategic partnerships support predictable service delivery. Small and medium enterprises also adopt outsourced models to access professional expertise without high fixed costs. Outsourcing aligns with corporate strategies for efficiency and cost management. The trend supports consolidation of global service providers.Rising influence of predictive analytics and AI-powered decision-making in facility operations:
Analytics-driven solutions are gaining momentum as organizations seek data-based insights for facility optimization. The Global Facilities Management Market is integrating artificial intelligence into predictive maintenance, space utilization, and energy forecasting. It enhances operational efficiency by identifying issues before they escalate. Machine learning algorithms improve resource allocation and service scheduling. AI-powered chatbots are deployed for service requests and tenant management. It reduces human dependency while ensuring responsiveness. Predictive analytics also enhances risk management and safety protocols. Adoption of advanced analytics creates measurable business value for facility owners and tenants. Technology-led transformation continues to shape industry competitiveness.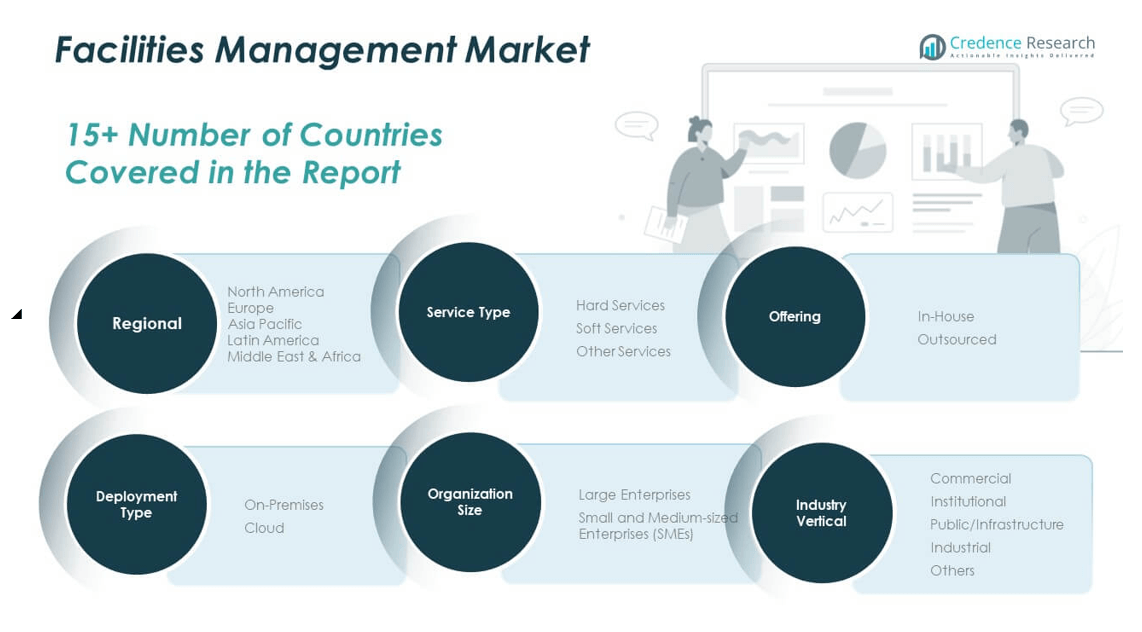
Market Challenges Analysis:
High operational cost pressures and workforce management complexities limiting service scalability:
The Global Facilities Management Market faces significant challenges in managing cost structures and workforce complexities. Service delivery requires large labor forces across multiple sites, leading to high wage expenses. It places pressure on providers to maintain profitability while meeting service-level agreements. Rising costs of energy and raw materials also contribute to financial constraints. Providers must invest in training and compliance programs for workforce management. Talent shortages in specialized facility services create operational gaps. The fragmented vendor landscape makes standardization difficult. Sustaining high-quality delivery across diverse regions remains a core challenge. Market consolidation attempts often face regulatory scrutiny.Compliance with evolving health, safety, and environmental regulations creating operational risks:
Regulatory compliance poses another challenge for facility service providers globally. The Global Facilities Management Market must adhere to diverse national and regional regulations. It requires continuous monitoring of health, safety, and environmental standards. Failure to comply leads to financial penalties and reputational damage. Providers must invest in regular audits, certifications, and staff training. Regulations on carbon footprint and energy efficiency demand costly technology integration. Cultural and legislative differences across regions complicate uniform service models. Service providers also face liability concerns in high-risk sectors like healthcare. Compliance pressures increase operational risks for both local and multinational vendors.Market Opportunities:
Rising demand for smart city infrastructure creating new avenues for facility services growth:
The Global Facilities Management Market is positioned to benefit from large-scale smart city investments worldwide. Urban development projects require sophisticated facility management for transportation hubs, residential complexes, and commercial districts. It creates opportunities for providers offering technology-enabled solutions. Smart infrastructure needs energy optimization, automated security, and predictive maintenance services. Governments and private investors are increasing spending on urban resilience and sustainability. Service providers can secure long-term contracts aligned with infrastructure lifecycles. Smart city initiatives promote adoption of integrated digital facility platforms. The growing scope of smart cities ensures consistent growth momentum for the sector.Increasing expansion of multinational corporations in emerging economies fueling structured facility outsourcing:
Multinational corporations expanding into Asia Pacific, Latin America, and the Middle East present strong opportunities for organized facility services. The Global Facilities Management Market gains traction as these firms demand uniform quality and standardized processes across offices. It provides outsourcing opportunities for global service providers with regional presence. Expansion of IT parks, logistics centers, and retail outlets further boosts outsourcing demand. Providers capable of delivering consistency across geographies are well-positioned. Corporate focus on sustainability enhances demand for green facility management in emerging regions. Growing foreign direct investments expand service scope for structured outsourcing. Service providers benefit from multinational scaling needs.Market Segmentation Analysis:
By Service Type The Global Facilities Management Market shows strong demand for hard services, led by technical maintenance, utilities management, and building infrastructure support. Soft services such as cleaning, catering, and security remain vital for commercial and institutional facilities, while other services, including waste disposal and landscaping, expand with rising preference for bundled solutions. It reflects client interest in comprehensive and integrated offerings. By Offering Outsourced facilities management holds a larger market share due to the growing shift of enterprises toward external expertise for non-core activities. It allows businesses to improve efficiency and reduce operational overhead. In-house models remain relevant in industries with strict operational control, though hybrid approaches that combine internal and external management are becoming more common.- For instance, CBRE’s 2024 Annual Report documented that its managed portfolio was handled through outsourced or hybrid facility management contracts, including clients leveraging CBRE’s integrated supply chain and external contractor network for non-core building operations.
Segmentation:
By Service Type- Hard Services
- Soft Services
- Other Services
- In-House
- Outsourced
- On-Premises
- Cloud
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
- Commercial
- Institutional
- Public/Infrastructure
- Industrial
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America The North America Global Facilities Management Market size was valued at USD 12,744.8 million in 2018 to USD 22,735.9 million in 2024 and is anticipated to reach USD 79,900.8 million by 2032, at a CAGR of 17.1% during the forecast period. It accounts for approximately 35.3% of the global market share in 2024. North America leads the market with strong adoption of digital facility platforms, high outsourcing penetration, and established corporate real estate demand. Enterprises rely heavily on outsourced providers to focus on strategic business functions. The region benefits from advanced infrastructure and strong emphasis on workplace sustainability. The U.S. drives growth with large-scale commercial complexes, IT hubs, and healthcare facilities requiring integrated services. Canada and Mexico contribute steadily through expanding urban infrastructure and manufacturing activity. Increasing demand for smart buildings and IoT-enabled facility management supports technological innovation. It continues to set benchmarks for global service providers. Europe The Europe Global Facilities Management Market size was valued at USD 10,128.2 million in 2018 to USD 17,635.6 million in 2024 and is anticipated to reach USD 58,903.0 million by 2032, at a CAGR of 16.4% during the forecast period. It represents nearly 27.4% of the market share in 2024. Europe demonstrates strong growth with emphasis on sustainability and green building standards. Countries such as Germany, the UK, and France drive adoption of energy-efficient facility solutions. Institutional and public infrastructure sectors remain key revenue contributors. Service providers benefit from EU regulations that encourage compliance-driven facility services. The commercial real estate sector fuels outsourcing demand, particularly in financial and technology hubs. Southern European countries, including Italy and Spain, show increasing investments in facility modernization. Eastern Europe emerges as a developing hub with growing demand from industrial parks and logistics facilities. It remains a highly regulated and competitive market. Asia Pacific The Asia Pacific Global Facilities Management Market size was valued at USD 8,935.6 million in 2018 to USD 16,836.5 million in 2024 and is anticipated to reach USD 65,054.2 million by 2032, at a CAGR of 18.5% during the forecast period. It secures about 26.2% of the global market share in 2024. Asia Pacific records the fastest growth, driven by rapid urbanization, infrastructure expansion, and strong multinational presence. China and India dominate with growing commercial real estate, IT parks, and industrial complexes requiring professional facility services. Japan and South Korea contribute with advanced technological integration in smart building management. Australia and Southeast Asia present rising opportunities through infrastructure modernization and retail expansion. The region benefits from government-backed smart city initiatives and foreign direct investment. SMEs increasingly adopt outsourced facility solutions to enhance competitiveness. It continues to attract global providers expanding regional networks. Latin America The Latin America Global Facilities Management Market size was valued at USD 1,815.6 million in 2018 to USD 3,240.0 million in 2024 and is anticipated to reach USD 10,384.0 million by 2032, at a CAGR of 15.8% during the forecast period. It accounts for roughly 5.0% of the global market share in 2024. Latin America shows steady adoption with growing demand from commercial, healthcare, and public infrastructure projects. Brazil leads the region with strong investments in corporate real estate and manufacturing. Mexico supports growth with expanding urban facilities and logistics infrastructure. Argentina demonstrates gradual recovery through industrial development. Service providers face challenges from economic volatility and fragmented regulations. Outsourcing adoption increases as enterprises seek cost-efficient solutions. Regional expansion of global providers strengthens competitive positioning. It remains an emerging market with long-term growth opportunities. Middle East The Middle East Global Facilities Management Market size was valued at USD 1,384.8 million in 2018 to USD 2,346.5 million in 2024 and is anticipated to reach USD 7,470.1 million by 2032, at a CAGR of 15.7% during the forecast period. It represents around 3.6% of the global market share in 2024. The region demonstrates strong demand driven by mega infrastructure projects, particularly in the Gulf Cooperation Council (GCC) countries. Saudi Arabia and the UAE lead adoption with large-scale smart city and commercial development initiatives. Qatar and Kuwait contribute with rising investments in healthcare and hospitality infrastructure. Israel showcases growth in technology-enabled facility solutions. Turkey strengthens demand through industrial expansion. Service providers benefit from high-value contracts for mega projects, though operational costs remain a challenge. The market is expanding through government-backed diversification programs. It offers high-potential opportunities for international players. Africa The Africa Global Facilities Management Market size was valued at USD 591.0 million in 2018 to USD 1,504.9 million in 2024 and is anticipated to reach USD 4,617.8 million by 2032, at a CAGR of 14.7% during the forecast period. It holds about 2.3% of the global market share in 2024. Africa is at a developing stage with rising adoption in South Africa, Egypt, and Nigeria. Growth is fueled by urbanization, construction of commercial complexes, and public infrastructure projects. South Africa leads with strong corporate outsourcing practices. Egypt and Kenya present growing opportunities through smart city initiatives. The region faces challenges from limited technology penetration and fragmented regulatory frameworks. Service demand is gradually expanding in industrial and institutional sectors. Global players are entering through partnerships with local providers. It represents an emerging market with untapped potential and long-term opportunities.Key Player Analysis:
- CBRE Group, Inc.
- Compass Group
- Sodexo
- Aramark
- ISS A/S
- Jones Lang LaSalle Incorporated (JLL)
- Cushman & Wakefield
- Brookfield Global Integrated Solutions
- Serco Group plc
Competitive Analysis:
The Global Facilities Management Market is highly competitive, with a mix of global leaders and regional players shaping its landscape. Companies such as CBRE Group, ISS A/S, Sodexo, Compass Group, Aramark, and Jones Lang LaSalle dominate through large-scale contracts, diverse service portfolios, and advanced digital platforms. It is characterized by intense rivalry where firms compete on service quality, technological innovation, and sustainability performance. Regional providers leverage local knowledge to secure contracts in niche markets. Multinational corporations increasingly seek global consistency, favoring international players with integrated solutions. Strategic acquisitions, partnerships, and investments in smart technologies define competitive differentiation.Recent Developments:
- In July 2025, Compass Group Equity Partners partnered with The Illuminate Group to launch a new cold chain platform. This partnership aims to triple Illuminate’s R&D capacity and accelerate the development of solutions for pharmaceutical cold chain management. The initiative also represents the fourth platform from Compass Group’s Fund III and underpins Compass’s commitment to growth in temperature-controlled logistics.
- On July 22, 2025, Compass Group PLC agreed to acquire Vermaat Group, a premium food services provider in Europe. This strategic acquisition is aimed at expanding Compass Group’s premium service segment and accelerating its European growth, subject to regulatory approval. The acquisition also brings Vermaat’s strong operational leadership into Compass Group’s business.
- In May 2025, Sodexo announced a strategic partnership with food-tech workplace platform HUNGRY to enhance its corporate dining offerings, leveraging HUNGRY’s network of 1,500 food partners across 19 major cities. The partnership brings a flexible, digitally enabled food service model to Sodexo’s clients, with immediate implementation on select accounts.
- In Feb 2025, ISS secured an integrated facilities services contract with Aroundtown across 47 German locations, covering services such as cleaning, building technology, security, landscaping, and winter services.
- In May 2025, Mitie secured a £12 million three-year integrated facilities management contract with the UK Intellectual Property Office (with an option to extend), covering engineering, cleaning, and waste management across two sites.
- In Feb 2025 (FM/biomed ops), Sodexo India announced an advanced Healthcare Technology Management facility in Kolkata and highlighted CMMS-driven decision support for equipment uptime and maintenance planning.
- In January 2025, CBRE Group, Inc. announced a definitive agreement to acquire Industrious National Management Company, a leading provider of flexible workplace solutions. This acquisition led to the launch of a new business segment, Building Operations & Experience (BOE), which unifies building operations, workplace experience, and property management for comprehensive client solutions across offices, data centers, and warehouses. The transaction marks a significant expansion in CBRE’s global workplace service offerings and is expected to close by the end of January 2025.
Market Concentration & Characteristics:
The Global Facilities Management Market demonstrates moderate to high concentration, with top international players holding a significant portion of global revenues. It features a competitive environment where global leaders drive standardization, while regional and local firms focus on cost efficiency and sector-specific services. It relies heavily on long-term contracts, outsourcing models, and technology adoption to create differentiation. Price sensitivity, regulatory compliance, and sustainability remain defining characteristics. It is marked by continuous consolidation, with acquisitions and partnerships enabling firms to expand service portfolios and geographic reach.Report Coverage:
The research report offers an in-depth analysis based on service type, offering, deployment type, organization size, and industry vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook:
- Growing demand for integrated service models will expand market scope.
- Digital transformation and AI-driven platforms will strengthen efficiency.
- Sustainability and green building compliance will remain top priorities.
- Outsourcing penetration will rise across emerging economies.
- Cloud-based deployment will gain dominance over on-premises systems.
- Large enterprises will continue to lead demand for comprehensive solutions.
- SMEs will increasingly adopt facility services for cost optimization.
- Commercial and institutional facilities will drive the largest revenue share.
- Regional players will expand through niche and sector-focused services.
- Strategic alliances and acquisitions will shape competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integrated Service Delivery Models
Organizations are increasingly adopting integrated facilities management solutions that bundle maintenance, cleaning, security, and other services into a single contract. This streamlines vendor management, reduces administrative overhead, and enhances operational efficiency, driving market growth.
Sustainability and Energy Management Initiatives
Rising corporate and regulatory focus on sustainability is accelerating the adoption of facilities management services that prioritize energy efficiency, waste reduction, and compliance with green building standards. Providers offering advanced sustainability consulting and certified platforms are gaining market traction.
Rapid Urbanization and Infrastructure Expansion
Emerging economies are experiencing significant urban growth and infrastructure development, leading to increased demand for professional facilities management in new office complexes, industrial parks, and public infrastructure. Outsourcing facility services is becoming essential for effective asset upkeep in these regions.
Technology-Enabled Facility Management
The integration of IoT, predictive analytics, and automation in facility management platforms is transforming service delivery. Real-time monitoring, data-driven decision-making, and AI-powered maintenance are improving efficiency and reducing costs, making technology adoption a key growth driver.
Outsourcing for Strategic Focus
Corporations are increasingly outsourcing non-core facility operations to specialized providers, allowing them to focus on core business activities. This trend is particularly strong among large enterprises and multinationals seeking standardized, high-quality facility services across multiple locations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Facilities Management Market, and what is its projected size in 2032?
Which Global Facilities Management Market segment held the largest share in 2024?
What are the primary factors fueling the growthn of the Global Facilities Management Market?
Who are the leading companies in the Global Facilities Management Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 In-House
- 1.2.2 Outsourced
- 1.3 By Service Type
- 1.3.1 Hard Services
- 1.3.2 Soft Services
- 1.3.3 Other Services
- 1.4 By Deployment Type
- 1.4.1 On-Premises
- 1.4.2 Cloud
- 1.5 By Industry Vertical
- 1.5.1 Commercial
- 1.5.2 Institutional
- 1.5.3 Public/Infrastructure
- 1.5.4 Industrial
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 35,600.0 million → 2032: USD 226,330.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Facilities Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Facilities Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Facilities Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Facilities Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Facilities Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Facilities Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Facilities Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Facilities Management Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 35,600.0 million → 2032: USD 226,330.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Facilities Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 In-House
- 12.3.7.2 Outsourced
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hard Services
- 12.4.7.2 Soft Services
- 12.4.7.3 Other Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premises
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Commercial
- 12.6.7.2 Institutional
- 12.6.7.3 Public/Infrastructure
- 12.6.7.4 Industrial
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Facilities Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Facilities Management Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Facilities Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Facilities Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CBRE Group, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Compass Group
- 18.4 Sodexo
- 18.5 Aramark
- 18.6 ISS A/S
- 18.7 Jones Lang LaSalle Incorporated (JLL)
- 18.8 Cushman & Wakefield
- 18.9 Brookfield Global Integrated Solutions
- 18.10 Serco Group plc
- 18.11 Mitie Group plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

