
Market Overview:
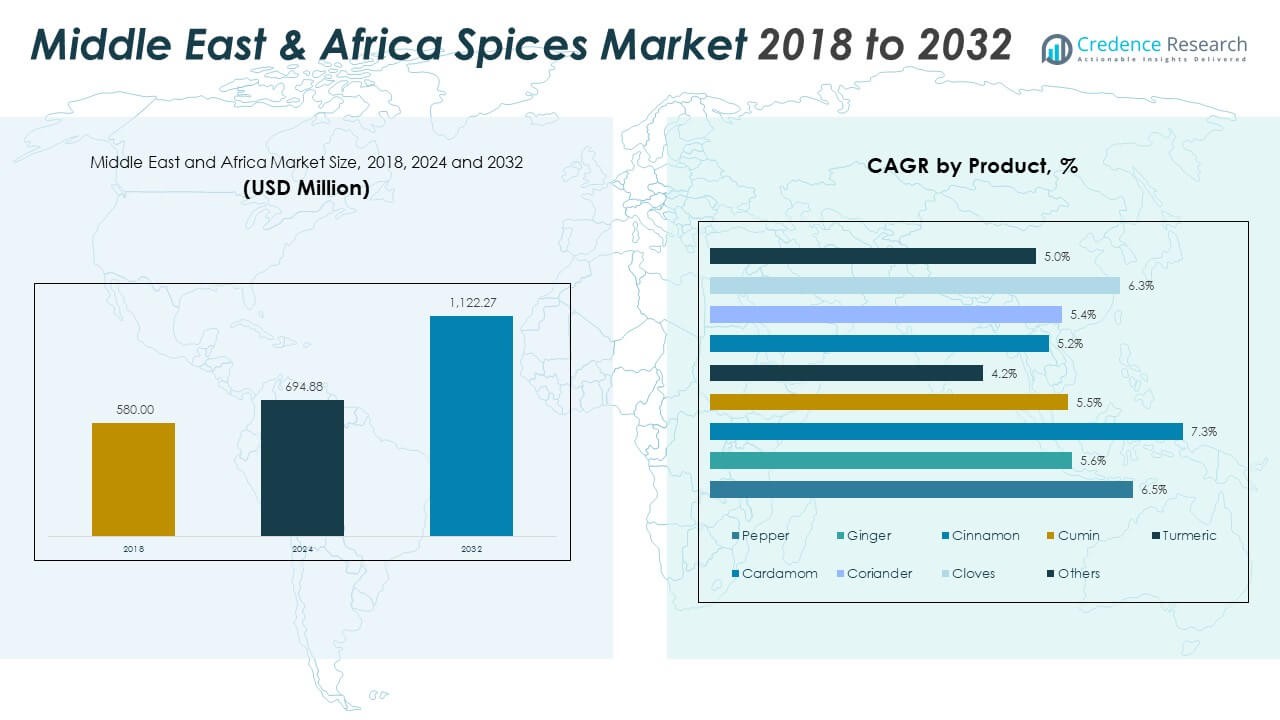
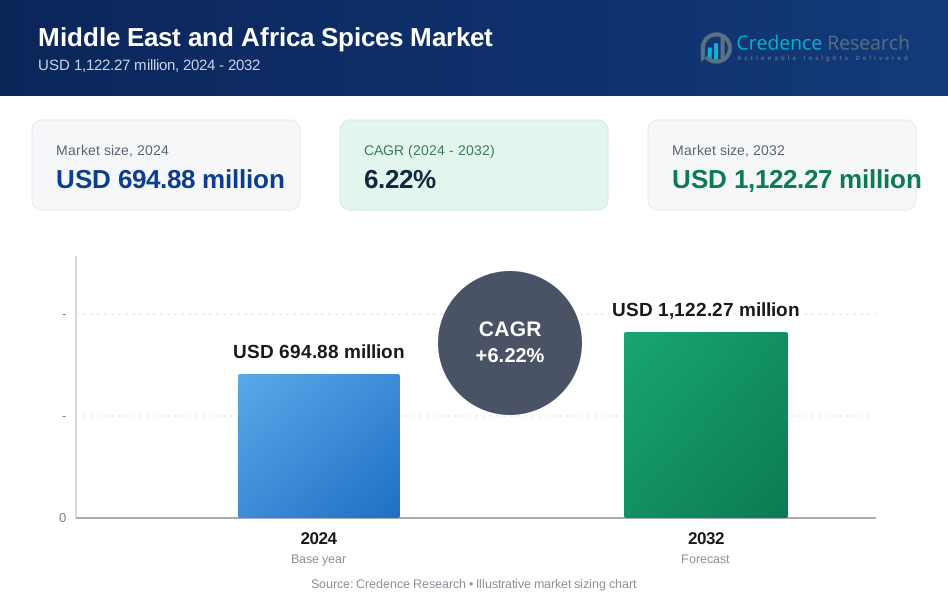
The Middle East & Africa Spices Market size was valued at USD 580.00 million in 2018 to USD 694.88 million in 2024 and is anticipated to reach USD 1,122.27 million by 2032, at a CAGR of 6.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Middle East & Africa Spices Market Size 2024 | USD 694.88 Million |
| Middle East & Africa Spices Market, CAGR | 6.22% |
| Middle East & Africa Spices Market Size 2032 | USD 1,122.27 Million |
The growth of the Middle East & Africa Spices Market is driven by several factors, including the increasing demand for healthy and natural food options. Spices such as turmeric, ginger, and cumin are sought after for their health benefits. Additionally, the rise of regional cuisines and the growing interest in ethnic flavors are pushing consumers to explore diverse spice offerings. The availability of spices through both traditional retail and e-commerce channels is further supporting market growth.
Regionally, the Middle East & Africa Spices Market is dominated by the GCC countries, including Saudi Arabia and the UAE, due to their strong foodservice sectors and affluent populations. Sub-Saharan Africa is emerging as a growth market, driven by urbanization, increasing disposable incomes, and changing dietary habits. North Africa, particularly Morocco and Egypt, also holds significant market share, thanks to their historical spice trade and consumption patterns.
Market Insights
- The Middle East & Africa Spices Market size was valued at USD 580.00 million in 2018, growing to USD 694.88 million in 2024, and is projected to reach USD 1,122.27 million by 2032, with a CAGR of 6.22% during the forecast period.
- The GCC countries hold the largest market share at 38%, driven by strong demand in foodservice and retail, followed by North Africa at 27%, supported by a history of spice trade and consumption, and Sub-Saharan Africa at 35%, where urbanization is pushing market growth.
- Sub-Saharan Africa is the fastest-growing region, contributing to 35% of the market share, driven by urbanization, increasing disposable income, and the rising demand for convenience and packaged spice products.
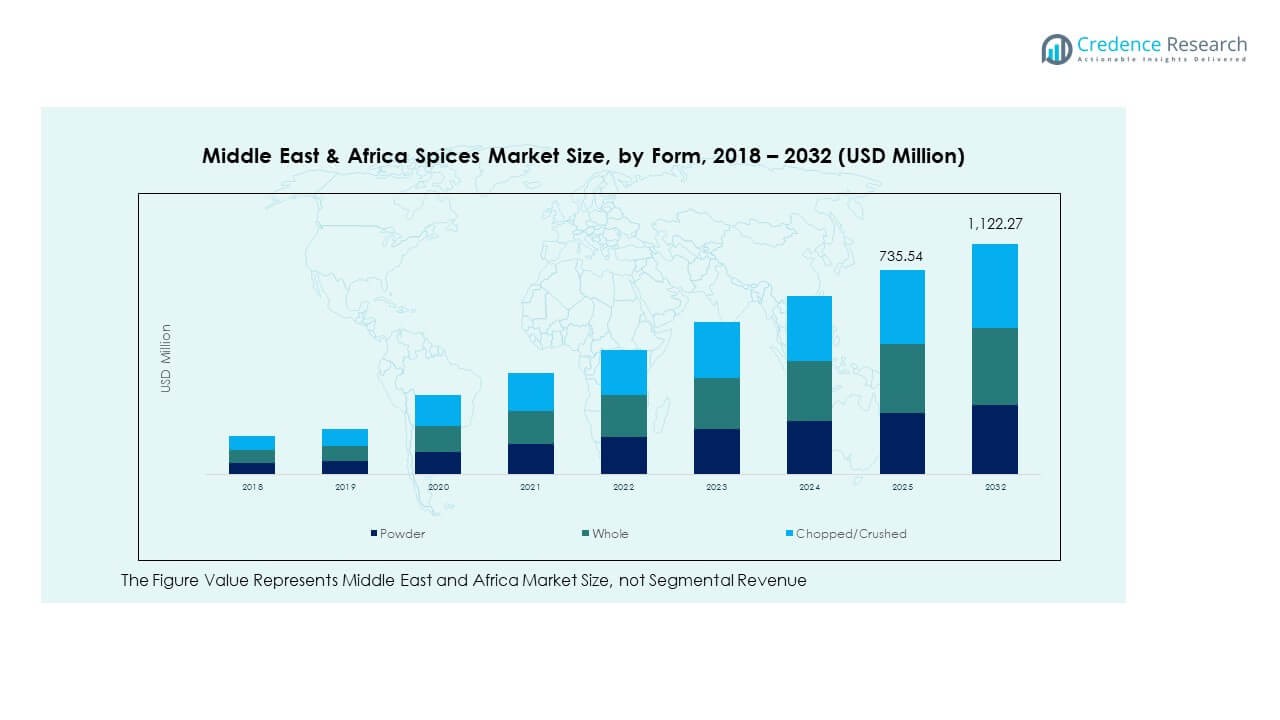
- The powder form of spices leads the market with the largest share, followed by whole spices, while chopped/crushed spices are growing at a steady pace, contributing to market diversification.
- The powder form of spices holds the dominant share, with a significant portion of the market coming from whole spices. Chopped/crushed spices are expected to grow rapidly due to increasing convenience-oriented demand.
Market Drivers:
Increasing Consumer Awareness of Health Benefits
The growing awareness of the health benefits of spices is a key driver of the Middle East & Africa Spices Market. Consumers are increasingly turning to natural remedies and foods that support overall well-being. Spices such as turmeric, ginger, and cinnamon are widely recognized for their anti-inflammatory and antioxidant properties. These health-conscious choices are prompting more individuals to include spices in their daily diet. As more information becomes available about the medicinal benefits of these spices, their demand is expected to rise significantly. It is clear that consumers are looking for healthier alternatives, which will continue to influence the spice market. This trend aligns with the broader global movement toward organic and plant-based foods.
- For instance, Olam Food Ingredients (ofi) offers its AtSource sustainable sourcing solution, which provides full traceability and transparency on origin and sustainability for spices sourced into the Middle East & Africa. The AtSource Plus platform tracks over 350 metrics on health, environmental, and social impact, with verifiable primary data, ensuring that health-focused consumers and manufacturers access spices verified for their natural and beneficial properties.
Growing Popularity of Ethnic and Regional Cuisines
Ethnic and regional cuisines are gaining more attention, driving demand for specific spices in the Middle East & Africa Spices Market. Consumers are increasingly exploring the authentic flavors of traditional dishes from various cultures. With the rise of social media and food blogs, people have become more experimental with their cooking. Spices that are integral to regional dishes such as Moroccan, Indian, and Middle Eastern are now being incorporated into everyday meals. These growing culinary trends push the demand for a diverse range of spices, including cumin, coriander, and saffron. It reflects an increasing desire for flavor complexity and food authenticity.
- For instance, North African and Ethiopian spice blends like ras el hanout and berbere have seen increased adoption across African restaurants and food producers, with Berbere becoming a culinary cornerstone for regional dishes such as doro wat and injera-based meals in Ethiopia and Eritrea, reflecting the mainstreaming of traditional flavors in both foodservice and home kitchens.
Expansion of Retail and Online Sales Channels
The expansion of retail and online sales channels has been a driving force behind the Middle East & Africa Spices Market growth. Consumers now have easy access to a broader selection of spices through e-commerce platforms and retail outlets. This increased accessibility, combined with convenience, supports market expansion. Traditional brick-and-mortar stores continue to dominate, but online platforms are quickly gaining ground as they provide consumers with access to a variety of spices from around the world. It is this growing infrastructure that allows the spice market to thrive across regions in the Middle East and Africa.
Rising Disposable Income and Urbanization
Rising disposable income and increasing urbanization in the Middle East & Africa are positively impacting the spices market. As more people move into urban areas, their purchasing power increases, allowing them to spend more on food and lifestyle products. Urban centers are home to a diverse population with different tastes and preferences, which further boosts the demand for diverse spice varieties. In parallel, consumers are seeking premium, high-quality products as their economic circumstances improve. It is expected that as the middle class continues to expand, the demand for spices will increase accordingly.
Market Trends:
Increasing Demand for Organic and Natural Spices
Organic and natural spices are gaining popularity in the Middle East & Africa Spices Market. Consumers are becoming more conscious about the potential harmful effects of pesticides and chemicals in food products. This shift in consumer preferences is resulting in greater demand for organic spices, as they are perceived to be healthier and more sustainable. Organic certification offers reassurance to consumers looking for transparency in sourcing and production methods. It is also driving the growth of a niche market focused on certified organic products, particularly in high-income urban areas.
- For instance, AKO The Spice Company has held EU ECO-Regulation organic certification for its spice imports and processing since June 2014, undergoing annual independent audits as well as compliance reviews by FSSC 22000-accredited boards, ensuring each batch meets strict pesticide and chemical-free standards.
Spices in Functional Foods and Beverages
There is a rising trend of using spices in functional foods and beverages across the Middle East & Africa. Consumers are increasingly looking for products that provide additional health benefits beyond basic nutrition. This includes beverages enriched with spices like ginger, turmeric, and mint, known for their soothing properties. Similarly, functional snacks and foods are incorporating spices to boost flavor and health benefits. Spices are now being seen not only as flavor enhancers but also as ingredients that provide wellness benefits, which is appealing to health-conscious consumers. It represents an evolving trend where food manufacturers are blending spices into innovative new products.
Advances in Spice Processing and Packaging Technologies
Technological advancements in spice processing and packaging are shaping the Middle East & Africa Spices Market. Companies are increasingly investing in modern equipment and techniques that improve the efficiency and quality of spice production. These innovations lead to spices that are fresher, more flavorful, and longer-lasting. Packaging has also evolved, with more attention given to preserving the aroma and potency of spices. Innovative packaging solutions, such as vacuum-sealed bags and glass containers, have helped maintain the spices' integrity and appeal to consumers. It reflects a growing commitment to quality and sustainability in the industry.
- For instance, Indian manufacturers such as Hathi Masala have industrially deployed cryogenic grinding technology, reaching temperatures as low as −196∘C and achieving extended shelf life for spices, specific tests show microbiological growth reduction and volatile oil retention resulting in longer domestic and export shelf lives.
Customization of Spice Products for Local Preferences
The trend of customizing spice products to cater to local preferences is gaining traction in the Middle East & Africa. Manufacturers are developing spice blends that cater to the unique tastes and culinary traditions of specific regions and countries. These tailored products appeal to consumers looking for a more authentic culinary experience. The demand for regional variations of popular spices like curry powder, za'atar, and ras el hanout is growing, as consumers seek flavors that resonate with their cultural palate. It signifies a more localized approach to spice production, emphasizing the need for more region-specific offerings.
Market Challenges Analysis:
Supply Chain Disruptions and Price Volatility
One of the significant challenges facing the Middle East & Africa Spices Market is the disruption in the supply chain and the volatility in spice prices. Natural disasters, political instability, and fluctuations in fuel prices can severely affect spice production and transportation. This leads to unpredictability in spice availability and pricing, making it difficult for manufacturers and suppliers to maintain consistent pricing strategies. The market also faces challenges related to the perishable nature of spices, which require careful handling and storage. As a result, any disruption in the supply chain can cause delays and lead to increased costs for both suppliers and consumers.
Competition from Substitutes and Counterfeit Products
The Middle East & Africa Spices Market also faces challenges from the increasing competition posed by substitutes and counterfeit products. Spices are sometimes substituted with cheaper alternatives that mimic their taste and appearance, often compromising quality. Additionally, counterfeit spices are a growing concern, as unregulated products are entering the market under false claims of quality. This issue undermines consumer trust and can create a significant market imbalance. Manufacturers need to focus on quality assurance and certifications to maintain their brand integrity and meet regulatory requirements.
Market Opportunities:
Growth in Health-Conscious Consumer Segments
The growing focus on health and wellness presents significant opportunities for the Middle East & Africa Spices Market. Health-conscious consumers are increasingly choosing spices for their medicinal benefits, such as reducing inflammation and boosting immunity. There is a rising demand for functional foods that incorporate spices like ginger, garlic, and turmeric, further supporting market growth. As consumers move towards healthier diets, the spice market is well-positioned to capitalize on these trends by offering products that align with these preferences. This shift provides a valuable opportunity for growth in the market.
Expansion of Spice Blends and Ready-to-Use Products
There is an emerging opportunity for manufacturers in the Middle East & Africa Spices Market to expand into spice blends and ready-to-use products. Busy urban lifestyles are driving the demand for convenient cooking solutions, and spice blends cater perfectly to this need. Pre-packaged spice mixes for specific dishes like curry, shawarma, and tagine are growing in popularity. It provides an opportunity for spice producers to innovate and cater to this demand by offering convenient yet high-quality products that suit modern lifestyles.
Market Segmentation Analysis
By Product:
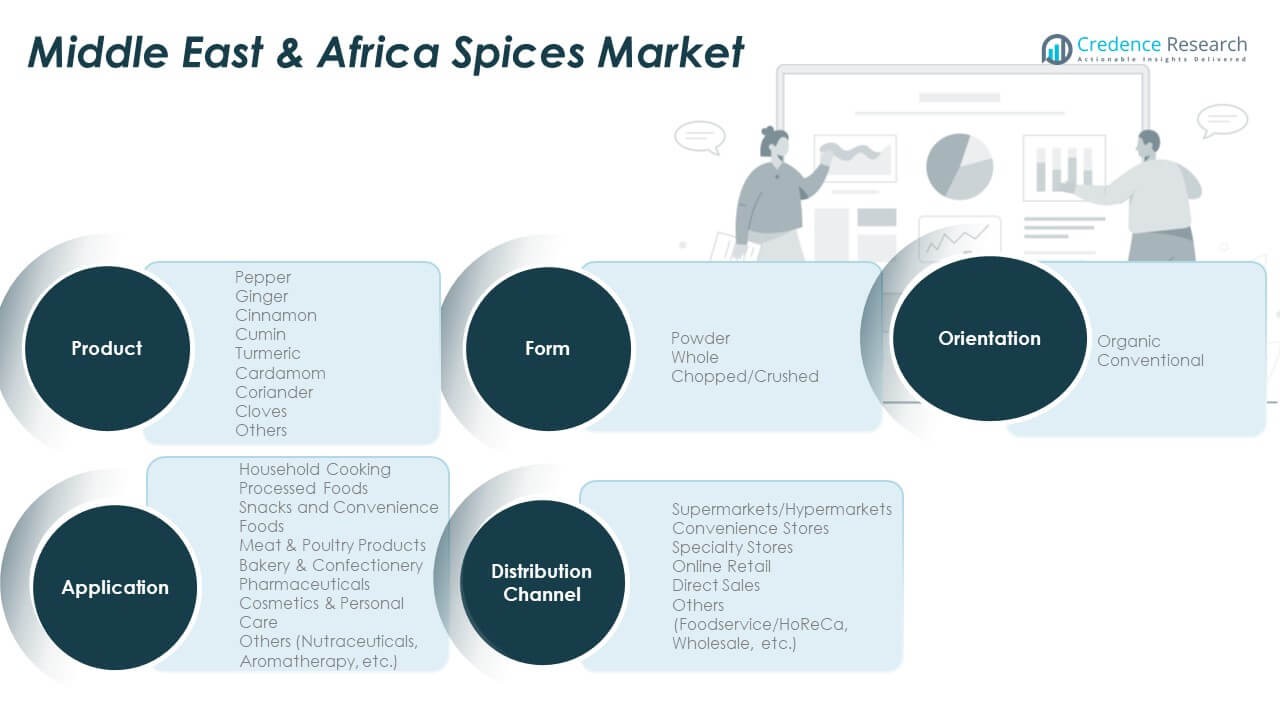
The Middle East & Africa Spices Market is driven by a diverse range of spices, with pepper, ginger, and cumin leading in demand. Pepper remains the most widely used spice, owing to its versatility in various cuisines. Ginger is gaining popularity due to its medicinal benefits, contributing to the growing trend of health-conscious consumption. Turmeric and cardamom follow closely, valued for their strong flavor and health benefits. Cinnamon, coriander, and cloves are also significant, often used in regional cuisines. The "Others" category includes niche spices, which contribute to the market’s overall growth.
By Form:
The form of spices significantly impacts consumer preferences in the Middle East & Africa Spices Market. Powdered spices dominate the market due to their ease of use and versatility in cooking. Whole spices are popular for consumers who prefer freshly ground flavors and longer shelf life. Chopped or crushed spices are increasingly being used in convenience products, offering ready-to-use solutions for consumers. The choice of spice form varies based on regional cuisine, with consumers seeking fresh or pre-ground options to suit their cooking habits and convenience.
- For example, Frontier Co-op, the parent of Simply Organic, launched the first nationally distributed Regenerative Organic Certified® bottled spices line in 2024, backed by third-party certification. These products implement advanced zero-synthetic farming and documented social/environmental standards.
By Orientation:
Organic spices are gaining traction in the Middle East & Africa Spices Market as health-conscious consumers prioritize natural and chemical-free options. Organic spices, though more expensive, are seen as a healthier choice due to their perceived purity and sustainability. Conventional spices, however, still account for a significant market share, being more widely available and cost-effective. The growing demand for organic products is expected to further boost the market for organic spices, particularly in high-income urban regions.
By Application:
The Middle East & Africa Spices Market sees diverse applications, with household cooking leading in consumption. Processed foods and snacks are also major contributors to the market, as they increasingly incorporate spices for enhanced flavor. Spices are crucial in meat & poultry products, bakery & confectionery, and pharmaceuticals, where their functional and preservative properties are valued. Cosmetics and personal care products are incorporating spices for their antioxidant properties. The "Others" category covers niches like nutraceuticals and aromatherapy, expanding the application scope of spices in the region.
- For example, SPAR Group South Africa’s digital platform “SPAR2U” recorded a 174% increase in on-demand delivery volumes for food and grocery items including spices in the first half of 2025, as published in multiple retail industry news sources and the company's interim financial results.
By Distribution Channel:
Supermarkets and hypermarkets are the primary distribution channels for spices in the Middle East & Africa Spices Market, offering wide accessibility to consumers. Convenience stores play an important role, especially in urban areas, where consumers seek quick and easy access to spices. Specialty stores provide premium and organic spice options, catering to health-conscious buyers. Online stores are growing in popularity due to the increasing digital penetration in the region. Direct sales and other channels, including foodservice and wholesale, also contribute to the market’s dynamic distribution landscape.
Segmentation
By Product:
- Pepper
- Ginger
- Cinnamon
- Cumin
- Turmeric
- Cardamom
- Coriander
- Cloves
- Others
By Form:
- Powder
- Whole
- Chopped/Crushed
By Orientation:
- Organic
- Conventional
By Application:
- Household Cooking
- Processed Foods
- Snacks and Convenience Foods
- Meat & Poultry Products
- Bakery & Confectionery
- Pharmaceuticals
- Cosmetics & Personal Care
- Others (Nutraceuticals, Aromatherapy, etc.)
By Distribution Channel:
- Supermarkets/Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Stores
- Direct Sales
- Others (Foodservice/HoReCa, Wholesale, etc.)
Regional Analysis
In the Gulf Cooperation Council (GCC) sub‑region, including Saudi Arabia and the UAE, the Middle East & Africa Spices Market holds an estimated 38% market share. The GCC benefits from high disposable income, modern retail infrastructure and strong import networks, which drive robust spice consumption. Urbanization and a growing expatriate population in cities like Dubai and Riyadh further support demand. Retailers in this sub‑region focus on premium and organic spice offerings, boosting value‑segment growth. The market here remains relatively mature but still offers incremental growth through product premiumization. Manufacturers prioritise GCC expansion to capture this lead share and establish brand presence early.
In North Africa, which includes Egypt, Morocco and Algeria, the market share stands at approximately 27%. Local cuisines feature spice‑rich recipes, which sustains consistent consumption. The region’s role in spice production and trade adds supply advantages for local manufacturers and importers. Retail penetration still trails the GCC, giving scope for branded spice adoption growth. Economic shifts and growing tourism in Morocco and Egypt contribute to rising demand for packaged and convenience spice products. Challenges such as variable logistics and regulatory complexity present barriers, yet the region’s share remains strong and stable.
Sub‑Saharan Africa, including Nigeria, Kenya and South Africa, accounts for around 35% of the region’s spices market. It is an emerging growth zone with rising urban populations and increasing demand for convenient food solutions incorporating spices. Many consumers shift from traditional loose spices to branded options, creating opportunities for new players. Infrastructure development and improving supply chains support this transition. However, price sensitivity and fragmented distribution networks constrain rapid uptake of premium segments. Despite these constraints, this sub‑region offers the highest potential growth among the three.
Key Player Analysis
- Ajinomoto Co., Inc.
- Associated British Foods plc
- Baria Pepper
- Kerry Group
- The Bart Ingredients Co. Ltd.
- DS Group
- McCormick & Company, Inc.
Competitive Analysis
The competitive landscape in the Middle East & Africa Spices Market features several multinational and regional players. McCormick & Company, Inc. operates across multiple markets in the region, leveraging strong brand equity and global supply chains to scale presence. Associated British Foods plc also participates in spice and seasoning categories, leveraging its regional manufacturing and distribution networks. Kerry Group Plc supports blended spice solutions and functional ingredients, enhancing its position in both retail and industrial segments. Ajinomoto Co., Inc. extends its spice portfolio into flavour enhancement for ingredients and food‑service applications. Baria Pepper operates with strong regional sourcing capabilities for raw spices, enabling cost advantages for downstream brands. These companies compete on product innovation, supply‑chain efficiency, local sourcing strategies and premiumisation of offerings. Local companies often focus on cost‑competitive blends and private‑label contracts. Overall rivalry remains high, and firms invest in branded outreach, organic certifications and expanded distribution to strengthen market positioning.
Recent Developments
- In January 2025, DS Group officially unveiled new television commercials (TVCs) for Catch Spices, their prominent brand, which signals active promotional efforts in the spice segment relevant to both India and, by virtue of brand expansion, the wider region including the Middle East and Africa.
- In January 2025, Kerry Group launched its 2025 Taste Charts, specifically highlighting major flavor trends and expanded efforts in Africa, including hot and spicy ingredient solutions. Kerry’s increasing engagement in the Middle East and Africa is supported by recent partnerships, local R&D expansion, and tailored flavor innovation strategies as confirmed by company statements and industry media.
Report Coverage
The research report offers an in-depth analysis based on Product, Form, Orientation, Application and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for organic and natural spices is expected to continue growing as consumers become more health-conscious.
- E-commerce platforms will play an increasingly vital role in spice distribution, reaching a larger customer base.
- Regional spice blends tailored to local preferences will gain popularity in both retail and foodservice segments.
- There will be a rise in demand for value-added and premium spice products, especially in GCC countries.
- Urbanization across Sub-Saharan Africa will drive the demand for convenience products such as pre-blended spices and ready-to-use mixes.
- The Middle East & Africa Spices Market will see further product innovations, including functional foods and beverages enriched with spices.
- Competition will intensify as global and regional brands expand their footprint, especially in emerging markets.
- Regulatory frameworks and compliance standards will evolve, ensuring quality control and sustainability practices.
- Increasing disposable income in key regions will fuel higher consumption of premium and organic spice varieties.
- Advancements in spice processing and packaging technologies will enhance product shelf life, contributing to overall market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumer Awareness of Health Benefits
Consumers in the Middle East & Africa are increasingly seeking spices such as turmeric, ginger, and cinnamon for their recognized anti-inflammatory and antioxidant properties, driving demand for both traditional and new spice products.
Growing Popularity of Ethnic and Regional Cuisines
The rise of interest in authentic regional dishes and ethnic flavors, fueled by social media and culinary tourism, is expanding the use of diverse spices in both home and foodservice settings across the region.
Expansion of Retail and Online Sales Channels
The proliferation of modern retail formats and e-commerce platforms has made a wider variety of spices more accessible to consumers, supporting market growth by reaching new customer segments and enabling convenient purchasing.
Rising Disposable Income and Urbanization
Urbanization and increasing disposable incomes, especially in the GCC and Sub-Saharan Africa, are enabling consumers to spend more on premium, organic, and convenience-oriented spice products, further boosting market value.
Demand for Organic and Natural Spices
Health-conscious consumers are driving the growth of organic and natural spice segments, particularly in high-income urban areas, as they seek products perceived as healthier and more sustainable.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Middle East & Africa Spices Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Middle East & Africa Spices Market projected to grow between 2024 and 2032?
Which Middle East & Africa Spices Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Middle East & Africa Spices Market?
Who are the leading companies in the Middle East & Africa Spices Market?
Which region commanded the largest share of the Middle East & Africa Spices Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Powder
- 1.2.2 Whole
- 1.2.3 Chopped/Crushed
- 1.3 By Product
- 1.3.1 Pepper
- 1.3.2 Ginger
- 1.3.3 Cinnamon
- 1.3.4 Cumin
- 1.3.5 Turmeric
- 1.3.6 Cardamom
- 1.3.7 Coriander
- 1.3.8 Cloves
- 1.3.9 Others
- 1.4 By Orientation
- 1.4.1 Organic
- 1.4.2 Conventional
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 694.88 million → 2032: USD 1,122.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East and Africa Spices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East and Africa Spices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East and Africa Spices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East and Africa Spices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East and Africa Spices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East and Africa Spices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East and Africa Spices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East and Africa Spices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 694.88 million → 2032: USD 1,122.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East and Africa Spices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powder
- 12.3.7.2 Whole
- 12.3.7.3 Chopped/Crushed
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pepper
- 12.4.7.2 Ginger
- 12.4.7.3 Cinnamon
- 12.4.7.4 Cumin
- 12.4.7.5 Turmeric
- 12.4.7.6 Cardamom
- 12.4.7.7 Coriander
- 12.4.7.8 Cloves
- 12.4.7.9 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Orientation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Organic
- 12.5.7.2 Conventional
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East and Africa Spices Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Middle East and Africa Spices Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Middle East and Africa Spices Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 McCormick & Company, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Ajinomoto Co., Inc.
- 17.4 Associated British Foods plc
- 17.5 Kerry Group
- 17.6 The Bart Ingredients Co. Ltd.
- 17.7 DS Group
- 17.8 Baria Pepper
- 17.9 AKO The Spice Company
- 17.10 Frontier Co-op
- 17.11 Olam Food Ingredients (ofi)
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

