
Market Overview:
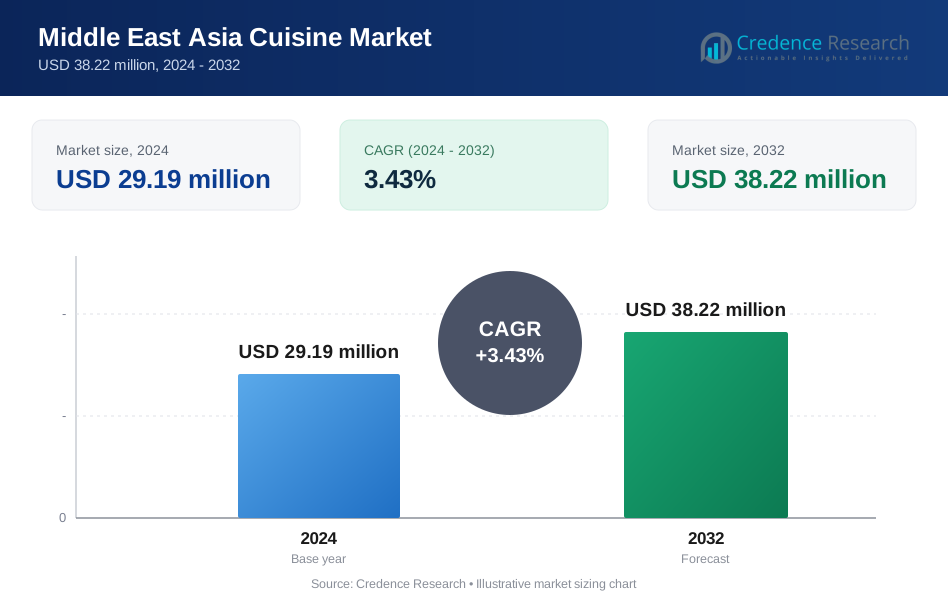
The Middle East Asia Cuisine Market size was valued at USD 28.16 million in 2018 to USD 29.19 million in 2024 and is anticipated to reach USD 38.22 million by 2032, at a CAGR of 3.43% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Middle East Asia Cuisine Market Size 2024 | USD 29.19 Million |
| Middle East Asia Cuisine Market, CAGR | 3.43% |
| Middle East Asia Cuisine Market Size 2032 | USD 38.22 Million |
Rising consumer interest in authentic Asian culinary experiences drives market growth. Urban populations increasingly seek diverse dining options, prompting restaurants to expand menus and offer premium Asian dishes. Higher disposable incomes support frequent dining out and experimentation with flavors. Ready-to-eat and frozen Asian food products gain traction for convenience. Food festivals and social media influence enhance awareness and demand. Quick-service and casual dining chains adopt Asian offerings to capture a broader audience. Tourism further boosts market expansion by attracting international and local consumers.
Geographically, the GCC region dominates, led by the UAE and Saudi Arabia, due to high expatriate populations, disposable incomes, and strong tourism. Emerging markets such as Qatar, Oman, and Kuwait show increasing adoption, fueled by growing middle-class consumers. North Africa maintains gradual growth, while Levant countries witness niche adoption of Asian cuisines. Urban centers with multicultural dining cultures serve as primary demand hubs. Market penetration strengthens in regions emphasizing international culinary experiences and modern foodservice infrastructure.
Market Insights
- The Middle East Asia Cuisine Market size was valued at USD 29.19 million in 2024 and is projected to reach USD 38.22 million by 2032, growing at a CAGR of 3.43%.
- Rising consumer preference for authentic Asian flavors and diverse dining experiences drives market growth.
- Urbanization and higher disposable incomes encourage frequent dining at restaurants offering Japanese, Chinese, and Korean cuisines.
- Ready-to-eat and frozen Asian food products support convenience-focused consumer demand.
- Market expansion faces challenges from cultural barriers and limited availability of authentic ingredients in some regions.
- The GCC region, particularly UAE and Saudi Arabia, leads the market due to high expatriate populations and tourism.
- Emerging markets like Qatar, Oman, and Kuwait show growth potential, supported by increasing middle-class consumers and modern foodservice infrastructure.
Market Drivers
Rising Demand For Authentic Asian Culinary Experiences Across Urban Centers
The Middle East Asia Cuisine Market benefits from growing consumer interest in authentic Asian flavors. Urban populations increasingly prefer diverse dining experiences, boosting restaurant visits and foodservice spending. It encourages chefs to innovate menus while retaining traditional tastes. Higher disposable incomes allow consumers to explore premium Asian dishes. Food festivals and pop-up events increase exposure to regional cuisines. The availability of imported ingredients supports menu authenticity. Retail channels introduce ready-to-eat Asian products, expanding market access. Social media influence strengthens consumer awareness of trending dishes. Tourists also contribute to higher adoption of authentic Asian food.
Expansion Of Quick-Service And Casual Dining Chains Offering Asian Cuisine
Quick-service and casual dining chains drive market growth by expanding Asian menu options. The Middle East Asia Cuisine Market gains traction through strategic openings in urban and suburban areas. It attracts younger demographics seeking convenient dining experiences. Chain restaurants standardize quality while introducing regional specialties. Partnerships with delivery platforms increase accessibility. It encourages competition, prompting innovation in flavors and presentation. Promotions and loyalty programs enhance consumer retention. Market penetration improves through franchise models across multiple cities. Growing awareness of health-conscious Asian dishes further supports expansion.
- For example, Panda Express has been expanding in the Middle East, with new outlets opening in key cities such as Dubai and Riyadh, supported by the company’s global growth strategy through both company-owned and franchise models.
Increasing Popularity Of Ready-To-Eat And Frozen Asian Food Products Among Consumers
The demand for ready-to-eat and frozen Asian products fuels market growth. The Middle East Asia Cuisine Market benefits from modern retail chains stocking diverse Asian options. It allows consumers to replicate restaurant-quality meals at home. Convenience and longer shelf life appeal to working professionals and expatriates. Packaging innovations preserve freshness and flavor integrity. Distribution networks improve product availability across regions. It drives collaborations between Asian food producers and local retailers. Consumers explore a wide variety of dishes without visiting restaurants. Cooking tutorials and social media exposure increase adoption of packaged products.
- For example, Saudi Arabia represents one of the largest frozen food markets in the Middle East, with leading players such as Al Kabeer Group and Americana Foods driving strong demand for ready-to-eat and Asian-style frozen meals.
Influence Of Social Media And Digital Food Delivery Platforms On Market Growth
Digital platforms accelerate the market by connecting consumers with Asian food providers. The Middle East Asia Cuisine Market experiences higher awareness through online promotions and reviews. It motivates restaurants to maintain consistent quality and innovative offerings. Food delivery apps increase reach beyond urban centers. Online campaigns highlight trending dishes and limited-time specials. It allows smaller vendors to gain visibility alongside established brands. Consumer feedback guides menu adjustments and service improvements. Mobile platforms simplify ordering, boosting sales volume. Interactive content, including live cooking sessions, engages potential customers consistently.
Market Trends
Integration Of Fusion Cuisine And Regional Asian Flavors In Modern Menus
Middle East Asia Cuisine Market shows a growing trend of combining Asian flavors with local culinary practices. It encourages chefs to experiment while maintaining authenticity. Fusion dishes attract adventurous diners seeking new taste experiences. Menu diversification increases restaurant competitiveness. It promotes cross-cultural culinary education for consumers. Signature dishes are modified to suit regional preferences. Media coverage highlights innovative offerings, boosting popularity. It expands potential consumer base beyond traditional Asian cuisine enthusiasts. Emerging restaurants leverage fusion trends to differentiate from competitors.
- For examples, Orfali Bros Bistro in Dubai secured the No. 1 spot in Middle East & North Africa's 50 Best Restaurants for 2025. It is recognized for its inventive Aleppian fusion dishes and features menu items such as shish barak à la gyoza and corn bomb.
Adoption Of Sustainable And Health-Conscious Ingredients Across Asian Menus
Sustainability and health consciousness drive menu development in the Middle East Asia Cuisine Market. It encourages the use of organic vegetables, lean proteins, and locally sourced produce. Consumers prefer dishes with lower sodium, sugar, and artificial additives. Restaurants highlight transparent ingredient sourcing in marketing. It aligns with global health trends and wellness initiatives. Eco-friendly packaging enhances the dining experience while reducing environmental impact. Chefs create balanced meals catering to dietary restrictions. It stimulates innovation in recipe formulation. Health-focused menu offerings strengthen brand reputation and customer loyalty.
Expansion Of Digital Ordering Systems And Cloud Kitchens For Asian Cuisine
The Middle East Asia Cuisine Market leverages technology through cloud kitchens and online ordering systems. It reduces overhead costs while increasing market reach. Consumers gain convenient access to diverse Asian dishes. It encourages rapid scaling of new concepts without traditional infrastructure. Data analytics inform menu design and targeted promotions. It supports operational efficiency through inventory and delivery management. Collaboration with food delivery platforms increases order frequency. It enhances customer experience via real-time tracking and feedback. Urban areas see accelerated adoption, strengthening market penetration.
- For example, Kitopi, headquartered in Dubai, has grown into the largest multi-brand cloud kitchen platform in the Middle East, operating across several countries and supporting hundreds of restaurant brands through its technology-driven kitchens.
Growing Investment In Culinary Tourism And Experiential Dining Experiences
Experiential dining becomes a prominent trend in the Middle East Asia Cuisine Market. It offers consumers immersive Asian culinary experiences beyond traditional meals. Cooking classes, themed restaurants, and cultural events attract food enthusiasts. It enhances brand visibility and drives foot traffic. Partnerships with travel and hospitality sectors increase exposure. Social media amplification of unique experiences stimulates broader interest. It encourages repeat visits and long-term loyalty. Regional flavors are showcased to educate diners. Market players capitalize on combining taste with interactive entertainment.
Market Challenges Analysis
High Import Costs And Supply Chain Complexities For Asian Ingredients
The Middle East Asia Cuisine Market faces challenges due to high import costs of authentic ingredients. It relies on overseas suppliers for key spices, sauces, and specialty products. Currency fluctuations affect pricing stability for restaurants. It creates operational uncertainty and impacts profit margins. Limited local availability hinders menu variety and consistency. It increases dependency on distributors and logistics networks. Regulatory approvals and import tariffs delay deliveries. It forces restaurants to adjust pricing or substitute ingredients. Maintaining authenticity remains a persistent operational challenge.
Cultural Preferences And Competition From Established Local And International Cuisines
Consumer acceptance varies due to cultural and taste preferences, challenging market penetration. The Middle East Asia Cuisine Market competes with established Middle Eastern and Western cuisine options. It requires continuous marketing and educational initiatives to promote adoption. Limited awareness of regional Asian dishes restricts customer reach. It demands training staff for authentic preparation and service standards. Brand loyalty to familiar cuisines slows trial rates. It increases pressure on innovation while controlling costs. Consumer skepticism toward new flavors limits expansion potential. Maintaining differentiation while appealing to mainstream tastes requires strategic focus.
Market Opportunities
Rising Interest In Health-Oriented And Specialized Asian Cuisine Offering New Growth Prospects
The Middle East Asia Cuisine Market has opportunities in health-oriented menus, vegan options, and allergen-free dishes. It attracts health-conscious consumers seeking nutritious and balanced meals. Partnerships with nutritionists enhance menu credibility. It encourages the introduction of functional foods and low-calorie dishes. Emerging consumer segments show willingness to explore authentic flavors with dietary benefits. It opens avenues for ready-to-eat healthy Asian products. Digital marketing highlights these offerings effectively. It strengthens brand positioning while expanding consumer reach. Growth prospects align with wellness trends across urban populations.
Expansion Through E-Commerce And Innovative Delivery Models To Enhance Market Penetration
Online platforms and delivery-focused operations create new avenues for the Middle East Asia Cuisine Market. It allows small and medium players to reach wider audiences without traditional restaurant infrastructure. Cloud kitchens reduce operational costs while increasing geographic coverage. It fosters partnerships with major delivery platforms and apps. Consumer convenience drives repeat orders and brand loyalty. It enables market entry into emerging cities with growing demand. Data-driven insights optimize menu offerings and pricing strategies. It strengthens overall market competitiveness and scalability. Digital engagement supports targeted promotions and customer retention.
Market Segmentation Analysis
By Type
The Japanese cuisine segment leads the Middle East Asia Cuisine Market due to high consumer preference for sushi, ramen, and other traditional dishes. It benefits from urban consumers seeking authentic flavors and premium dining experiences. The Chinese cuisine segment follows, driven by widespread popularity of dim sum, noodles, and regional specialties. Korean cuisine gains traction through increasing interest in barbecue, kimchi, and fusion dishes. Indonesian cuisine maintains a niche presence, appealing to adventurous diners and expatriate communities. The “Others” category captures diverse Asian cuisines, supporting experimentation and menu variety across restaurants. It strengthens market diversity and encourages innovation in flavor offerings.
- For example, Kura Sushi, a leading Japanese conveyor belt sushi chain, is recognized for its large-scale, technology-driven dining formats, using extensive conveyor systems and automation to deliver meals efficiently across hundreds of seats in its restaurants.
By Distribution Channel
Offline channels dominate the Middle East Asia Cuisine Market, including dine-in restaurants, casual dining, and quick-service outlets. It ensures consistent consumer experiences, menu authenticity, and brand visibility. Online channels, including food delivery platforms and cloud kitchens, are rapidly growing due to convenience and urban lifestyle adoption. It enables smaller players to reach wider audiences without large physical infrastructure. Integration of digital ordering apps enhances customer engagement and repeat purchases. Both channels complement each other, expanding market reach while maintaining quality standards. Strategic expansion across these channels supports long-term market growth.
- For example, Talabat has piloted autonomous delivery robots, known as “Talabots,” in Dubai Silicon Oasis, supporting last-mile delivery trials in partnership with local authorities as part of Dubai’s smart mobility initiatives.
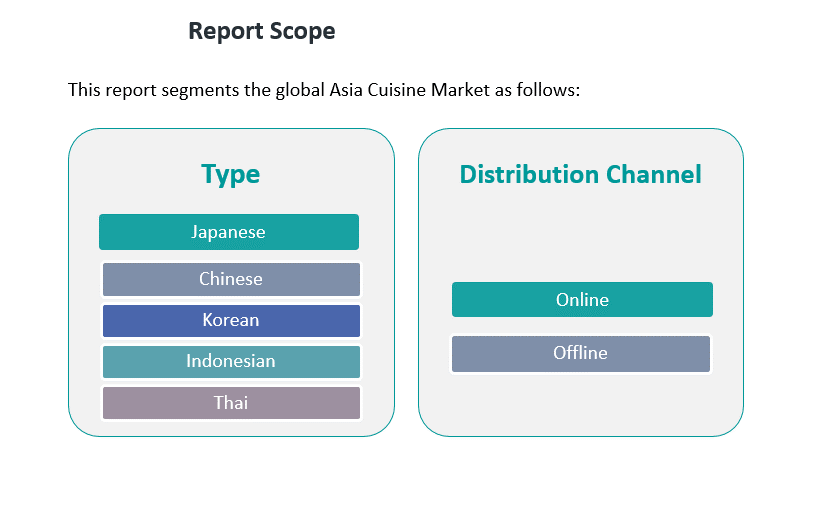
Segmentation
By Type
- Japanese
- Chinese
- Korean
- Indonesian
- Others
By Distribution Channel
- Online
- Offline
Regional Analysis
Gulf Cooperation Council (GCC) Region
The GCC region leads the Middle East Asia Cuisine Market, accounting for approximately 60% of the market share. Countries like Saudi Arabia and the UAE are major contributors, driven by high disposable incomes, a growing expatriate population, and a strong tourism sector. The proliferation of quick-service restaurants (QSRs) and casual dining establishments offering Asian cuisines has further fueled market growth. The UAE, in particular, is experiencing rapid expansion due to its diverse population and status as a global tourism hub. Saudi Arabia's Vision 2030 initiative also supports the diversification of the foodservice sector, including Asian culinary offerings.
Levant and North Africa
The Levant and North Africa together hold about 25% of the market share. Countries such as Lebanon, Jordan, and Egypt are witnessing a steady rise in the popularity of Asian cuisines, particularly Chinese and Japanese. This trend is attributed to increasing urbanization, exposure to international cultures, and a growing middle class with a taste for diverse culinary experiences. While the market is expanding, it remains more niche compared to the GCC region, with Asian cuisine often integrated into local dining preferences.
Iran and Turkey
Iran and Turkey collectively contribute around 15% to the market. In Iran, Asian cuisine is gaining traction, especially in urban centers like Tehran, due to a younger population and exposure to global food trends. However, economic sanctions and import restrictions pose challenges to the availability of authentic ingredients, affecting the authenticity and growth of Asian culinary establishments. Turkey, with its rich culinary heritage, exhibits a moderate interest in Asian cuisines, primarily in cosmopolitan cities like Istanbul, where fusion and international cuisines are more prevalent.
Key Player Analysis
- Panda Express
- Noodles & Company
- Pei Wei Asian Diner
- The Cheesecake Factory
- Nestlé
- Conagra Brands
- Taco Bell
- McCormick & Company Inc.
- Lulu Hypermarket
- Spinneys
- Carrefour
Competitive Analysis
The Middle East Asia Cuisine Market is characterized by a diverse competitive landscape, featuring a mix of international chains, regional players, and local establishments. International brands like Panda Express and Noodles & Company have established a presence, capitalizing on the growing demand for Asian cuisines. Regional giants such as Americana Group and Savola Group dominate the market, leveraging extensive networks and local market knowledge to offer a wide range of Asian food options. Local players, including independent restaurants and food trucks, contribute to the market's vibrancy by providing authentic and innovative Asian dishes tailored to local tastes. The competition is intensifying as consumer preferences shift towards healthier, sustainable, and convenient dining options, prompting both established and emerging players to innovate and adapt to these trends.
Recent Developments
- In June 2025, Noodles & Company strengthened its global culinary appeal by partnering with the Food Network to curate four new “Food Network Favorites” entrees. This menu refresh brought more than two-thirds new or improved dishes, aiming to position the brand at the forefront of globally inspired noodle innovations, including flavors reminiscent of East and Southeast Asian cuisine.
- In June 2025, Conagra Brands introduced over 50 new frozen food products, including globally inspired, plant-based, and single-serve meals. This launch emphasized convenience, flavor, and multicultural culinary influences (notably Asian and Middle Eastern cuisines) and strengthened the brand’s leadership as a pace-setter in frozen foods for the region.
- In August 2025, Spinneys announced a landmark joint venture with the Alshaya Group to enter the Kuwait market the chain’s fourth Gulf territory. The first of 10 planned premium supermarkets is set to open in 2026, aiming to bring Spinneys’ fresh-focused and globally inspired cuisine, including Asian flavors, to Kuwaiti consumers.
Report Coverage
The research report offers an in-depth analysis based on Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Expansion of quick-service and casual dining chains will drive market penetration across urban centers.
- Rising consumer preference for authentic Asian flavors will encourage menu innovation and premium offerings.
- Growth of digital ordering platforms and cloud kitchens will enhance accessibility and convenience.
- Health-conscious and diet-specific Asian cuisine options will attract a larger consumer base.
- Fusion and regional flavor adaptations will create opportunities for differentiation among competitors.
- Increasing expatriate populations and tourism will continue to boost demand for Asian culinary experiences.
- Retail channels will expand the availability of ready-to-eat and frozen Asian cuisine products.
- Investments in marketing and social media engagement will strengthen brand visibility and consumer awareness.
- Sustainable sourcing and eco-friendly packaging will appeal to environmentally conscious consumers.
- Strategic partnerships, mergers, and regional expansions will reinforce competitive positioning and market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Middle East Asia Cuisine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Middle East Asia Cuisine Market projected to grow between 2024 and 2032?
Which Middle East Asia Cuisine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Middle East Asia Cuisine Market?
Who are the leading companies in the Middle East Asia Cuisine Market?
Which region commanded the largest share of the Middle East Asia Cuisine Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East Asia Cuisine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East Asia Cuisine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 29.19 million → 2032: USD 38.22 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East Asia Cuisine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East Asia Cuisine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East Asia Cuisine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East Asia Cuisine Market Drivers
- 3.3 Middle East Asia Cuisine Market Restraints & Challenges
- 3.4 Middle East Asia Cuisine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East Asia Cuisine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East Asia Cuisine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East Asia Cuisine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East Asia Cuisine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East Asia Cuisine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East Asia Cuisine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East Asia Cuisine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East Asia Cuisine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East Asia Cuisine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East Asia Cuisine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East Asia Cuisine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East Asia Cuisine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East Asia Cuisine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East Asia Cuisine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East Asia Cuisine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East Asia Cuisine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East Asia Cuisine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East Asia Cuisine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East Asia Cuisine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
