
Market Overview:
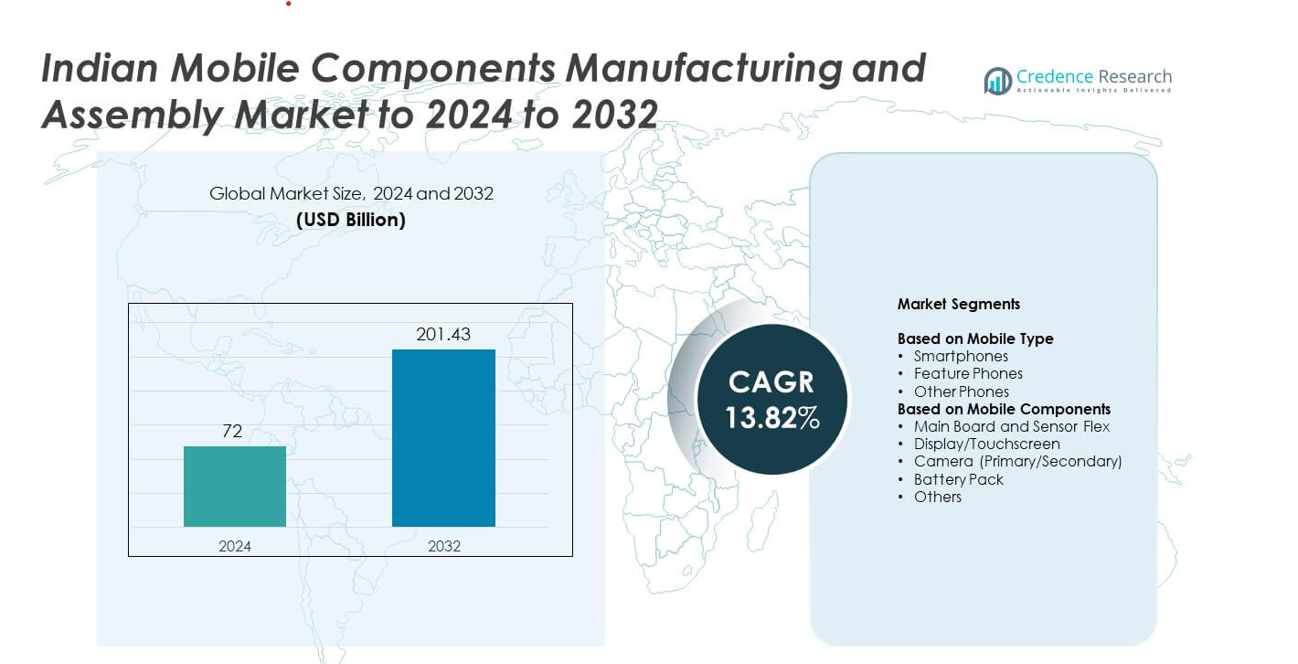
Indian Mobile Components Manufacturing and Assembly Market size was valued at USD 72 Billion in 2024 and is anticipated to reach USD 201.43 Billion by 2032, at a CAGR of 13.82% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Indian Mobile Components Manufacturing and Assembly Market Size 2024 | USD 72 Billion |
| Indian Mobile Components Manufacturing and Assembly Market , CAGR | 13.82% |
| Indian Mobile Components Manufacturing and Assembly Market Size 2032 | USD 201.43 Billion |
The Indian mobile components manufacturing and assembly market is led by key players such as Samsung Electronics Co. Ltd., Xiaomi Corporation, Vivo Mobile Communications Co. Ltd., Oppo Guangdong Mobile Communications Co. Ltd., and Lenovo Group Ltd., along with prominent domestic firms including Lava International Limited, Micromax Informatics Limited, Intex Technologies, and Karbonn Mobiles. These companies dominate production and assembly through strong local manufacturing bases and strategic partnerships. Uttar Pradesh leads the regional landscape with a 34.6% share, followed by Andhra Pradesh with 22.3% and Telangana with 18.7%. Tamil Nadu and Karnataka collectively contribute around 24.4%, supported by robust infrastructure, skilled labor, and proactive state policies driving large-scale component and device assembly operations across India.
Market Insights
- The Indian Mobile Components Manufacturing and Assembly Market was valued at USD 72 billion in 2024 and is projected to reach USD 201.43 billion by 2032, growing at a CAGR of 13.82%.
- Growth is driven by government incentives under the Production Linked Incentive (PLI) scheme, rapid smartphone adoption, and increasing localization of component manufacturing across key states.
- Emerging trends include automation, adoption of smart manufacturing technologies, and rising demand for 5G-enabled device components such as advanced sensors and chipsets.
- The market is competitive, with global and domestic players expanding local assembly lines and focusing on value-added components like displays, batteries, and camera modules.
- Uttar Pradesh leads with a 34.6% regional share, followed by Andhra Pradesh at 22.3% and Telangana at 18.7%, while smartphones dominate the mobile type segment with an 82.6% share, supported by strong production infrastructure and policy-driven expansion.
Market Segmentation Analysis:
By Mobile Type
Smartphones dominate the Indian mobile components manufacturing and assembly market with an estimated 82.6% share in 2024. The dominance is fueled by rapid 5G rollout, rising digital adoption, and increasing demand for advanced camera and display technologies. Growing local manufacturing under the Production Linked Incentive (PLI) scheme has boosted domestic smartphone assembly, reducing dependence on imports. Feature phones continue to serve rural and low-income segments due to affordability and long battery life, while other phone categories remain niche, catering to industrial and specialized communication applications.
- For instance, Foxconn plans to assemble up to 30 million iPhones in India in 2025, which is more than double its 2024 output in India of approximately 12 million units.
By Mobile Components
Display and touchscreen components lead the market with around 34.2% share in 2024. The growth is driven by increasing adoption of AMOLED, OLED, and foldable display technologies in mid and premium smartphone segments. Expanding domestic panel assembly capabilities and strategic partnerships with global display manufacturers further enhance local value addition. Camera modules and battery packs follow as key growth areas supported by innovation in multi-sensor systems, high-resolution imaging, and longer-lasting lithium-polymer technologies to meet evolving consumer expectations.
- For instance, Salcomp makes about 100 million phone chargers per year in India, anchoring power components.
Key Growth Drivers
Government Incentives and Localization Push
Government initiatives such as the Production Linked Incentive (PLI) scheme and phased manufacturing programs are accelerating domestic production of mobile components. These policies encourage global and local firms to establish assembly units, reducing import reliance and promoting value addition within India. Rising investments in manufacturing clusters across states like Uttar Pradesh and Tamil Nadu have also expanded supply chain capabilities, enabling large-scale component integration and export competitiveness.
- For instance, the HCL–Foxconn JV won approval for a Noida fab to make 36 million display-driver chips monthly from 2027.
Rising Smartphone Penetration and Technological Advancements
The growing adoption of smartphones, supported by affordable data plans and expanding digital infrastructure, is driving component demand. Increasing consumer preference for 5G-enabled devices, advanced camera systems, and high-refresh-rate displays is pushing manufacturers to upgrade production technologies. This trend has stimulated domestic assembly for critical parts like chipsets, displays, and sensors, strengthening India’s position in the global electronics manufacturing ecosystem.
- For instance, Tata Electronics currently employs around 20,000 people at its Hosur factory (as of September 2024), and plans to hire an additional 20,000 workers to double the workforce to 40,000 within the next year.
Foreign Investments and Strategic Partnerships
Rising foreign direct investment from major technology companies has fueled growth in India’s mobile component ecosystem. Partnerships between global brands and Indian manufacturers are enhancing local capabilities in printed circuit boards, camera modules, and battery systems. Collaborative ventures are fostering skill development and advanced technology transfer, positioning India as a strategic hub for component manufacturing in Asia.
Key Trends and Opportunities
Expansion of 5G and IoT-Driven Component Demand
The rollout of 5G networks and increasing integration of IoT applications have created strong opportunities for advanced component manufacturing. Demand for high-performance processors, efficient antennas, and precision sensors is growing rapidly. Local suppliers are investing in automation and smart assembly lines to meet the evolving performance and connectivity standards required by next-generation mobile devices.
- For instance, Apple shifted approximately 20% of global iPhone production to India as of early 2025, with plans to increase this share further to around 25-32% by 2027.
Emergence of Smart Manufacturing and Automation
Automation and robotics are transforming mobile component assembly by improving precision and efficiency. The adoption of Industry 4.0 practices, including AI-based quality control and real-time process monitoring, is enhancing production output and reducing defects. This shift toward smart manufacturing enables scalability, cost optimization, and improved competitiveness for Indian manufacturers in global supply chains.
- For instance, the Pegatron facility acquired by Tata Electronics had around 10,000 employees at the time of the deal closure in late 2024/early 2025.
Growing Domestic Supply Chain Integration
India is witnessing greater collaboration among component makers, assemblers, and logistics providers to strengthen local value chains. This integration supports faster production cycles and reduced dependency on imported parts. Enhanced backward linkages in materials such as semiconductors, connectors, and display glass are paving the way for sustainable, end-to-end mobile manufacturing within the country.
Key Challenges
Dependence on Imports for Core Components
Despite strong domestic assembly growth, India remains reliant on imports for high-value components such as semiconductors, display panels, and camera sensors. This dependence limits local value addition and exposes the sector to global supply disruptions. Establishing indigenous capabilities in advanced manufacturing technologies is critical to reduce import dependency and enhance resilience.
Skill Gaps and Infrastructure Constraints
The shortage of skilled labor and limited availability of advanced manufacturing infrastructure pose major challenges. Many production units lack adequate automation systems, cleanroom environments, and testing facilities required for precision component fabrication. Strengthening vocational training programs and investing in infrastructure modernization are essential to sustain long-term industry competitiveness.
Regional Analysis
Uttar Pradesh
Uttar Pradesh leads the Indian mobile components manufacturing and assembly market with a 34.6% share in 2024. The state’s dominance is driven by large-scale manufacturing clusters in Noida and Greater Noida, hosting major assembly units of global brands. Supportive state policies, skilled workforce availability, and proximity to the National Capital Region enhance industrial growth. Continuous investments in component production, including displays, batteries, and camera modules, strengthen its supply chain. The region’s focus on infrastructure and logistics modernization further boosts its competitiveness in large-volume mobile manufacturing.
Andhra Pradesh
Andhra Pradesh holds about 22.3% share of the Indian mobile components manufacturing and assembly market in 2024. The state benefits from a strong industrial base, special economic zones, and favorable investment policies. Manufacturing hubs in Tirupati and Sri City attract both domestic and international electronics players. The presence of advanced logistics infrastructure and port connectivity supports export-oriented component production. Growing participation of small and medium enterprises in PCB assembly and power management modules continues to enhance the region’s contribution to the national electronics ecosystem.
Telangana
Telangana accounts for 18.7% share of the Indian mobile components manufacturing and assembly market in 2024. Hyderabad’s Electronics Manufacturing Cluster and dedicated industrial corridors have positioned the state as a leading destination for component manufacturing. Government incentives and partnerships with global technology firms are driving investments in semiconductor packaging, sensor modules, and battery systems. A strong digital infrastructure, skilled talent pool, and efficient supply networks support sustained growth. Telangana’s focus on high-value electronics and smart manufacturing ensures its strategic importance in India’s mobile production landscape.
Tamil Nadu
Tamil Nadu represents around 14.2% share of the Indian mobile components manufacturing and assembly market in 2024. The state’s established electronics ecosystem in Chennai and Sriperumbudur attracts major OEMs and component suppliers. Strong infrastructure, advanced industrial parks, and a skilled labor base make Tamil Nadu a preferred location for large-scale mobile assembly. Increasing production of printed circuit boards, connectors, and flexible displays contributes to local value addition. The state’s emphasis on sustainable manufacturing practices and export-oriented policies continues to reinforce its regional strength.
Karnataka
Karnataka holds an estimated 10.2% share in the Indian mobile components manufacturing and assembly market in 2024. Bengaluru’s strong base in electronics design, semiconductor R&D, and automation technologies drives its market growth. The region supports innovation-led component development, particularly in sensors, chipsets, and precision modules. Government initiatives under the Electronics System Design and Manufacturing (ESDM) policy promote start-ups and high-tech assembly operations. With strong IT integration and a robust innovation ecosystem, Karnataka remains a key contributor to India’s advanced mobile component production segment.
Market Segmentations:
By Mobile Type
- Smartphones
- Feature Phones
- Other Phones
By Mobile Components
- Main Board and Sensor Flex
- Display/Touchscreen
- Camera (Primary/Secondary)
- Battery Pack
- Others
By Geography
- Uttar Pradesh
- Andhra Pradesh
- Telangana
- Tamil Nadu
- Karnataka
Competitive Landscape
Vivo Mobile Communications Co. Ltd., Lava International Limited, Xiaomi Corporation, Samsung Electronics Co. Ltd., Intex Technologies, Lenovo Group Ltd., Oppo Guangdong Mobile Communications Co. Ltd., Micromax Informatics Limited, and Karbonn Mobiles are among the major participants shaping the competitive landscape of the Indian mobile components manufacturing and assembly market. The market is characterized by intense competition, with global brands expanding local assembly lines and domestic firms scaling operations under government incentive programs. Players are focusing on vertical integration, component localization, and supply chain optimization to reduce import dependence. Increasing automation, R&D investments, and partnerships with component suppliers enhance production efficiency and technological capability. The shift toward high-value components, such as advanced camera modules, batteries, and display panels, drives differentiation. Moreover, strategic collaboration with semiconductor and design solution providers is fostering innovation, while sustainable manufacturing practices and energy-efficient facilities are becoming key priorities to maintain competitiveness.
Key Player Analysis
- Vivo Mobile Communications Co. Ltd.
- Lava International Limited
- Xiaomi Corporation
- Samsung Electronics Co. Ltd.
- Intex Technologies
- Lenovo Group Ltd.
- Oppo Guangdong Mobile Communications Co. Ltd.
- Micromax Informatics Limited
- Karbonn Mobiles
Recent Developments
- In 2025, Samsung significantly expanded its Indian manufacturing portfolio by beginning the production of laptops at its Greater Noida facility, which is also home to what was inaugurated in 2018 as the world's largest mobile phone manufacturing factory.
- In 2025, Micromax announced plans to invest in display and camera module manufacturing with an official announcement expected in the April-June quarter of 2025.
- In 2025, Xiaomi began local manufacturing of its tablets with the launch of the Xiaomi Pad 7.
Report Coverage
The research report offers an in-depth analysis based on Mobile Type, Mobile Components and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand rapidly with increasing domestic assembly of smartphones and electronic components.
- Rising adoption of 5G-enabled devices will boost demand for advanced semiconductor and sensor technologies.
- Local value addition will grow as India strengthens its component manufacturing ecosystem under the PLI scheme.
- Strategic collaborations between global and Indian firms will enhance technology transfer and skill development.
- Automation and smart manufacturing adoption will improve production efficiency and product quality.
- Regional manufacturing hubs will gain prominence through infrastructure modernization and policy support.
- Component diversification into displays, camera modules, and batteries will drive steady growth.
- Increasing focus on sustainable manufacturing will promote energy-efficient and recyclable materials.
- R&D investment will rise in areas such as flexible electronics and integrated circuit design.
- Strengthened export capabilities will position India as a key global hub for mobile component production.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Incentives and Localization Push
The Indian government's Production Linked Incentive (PLI) scheme and phased manufacturing programs are accelerating domestic production of mobile components, encouraging both global and local firms to establish assembly units and reduce import reliance.
Rising Smartphone Penetration and Technological Advancements
Rapid adoption of smartphones, fueled by affordable data plans and expanding digital infrastructure, is driving demand for advanced components such as 5G chipsets, high-resolution cameras, and AMOLED displays, pushing manufacturers to upgrade technologies and expand local assembly.
Foreign Investments and Strategic Partnerships
Increased foreign direct investment and collaborations between global technology brands and Indian manufacturers are enhancing local capabilities in high-value components, fostering skill development, and facilitating advanced technology transfer.
Expansion of 5G and IoT-Driven Component Demand
The rollout of 5G networks and growing integration of IoT applications are creating strong opportunities for advanced component manufacturing, with rising demand for high-performance processors, efficient antennas, and precision sensors.
Emergence of Smart Manufacturing and Automation
Adoption of automation, robotics, and Industry 4.0 practices is improving production efficiency, scalability, and quality, enabling Indian manufacturers to compete globally and meet the evolving standards of next-generation mobile devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Indian Mobile Components Manufacturing and Assembly Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Indian Mobile Components Manufacturing and Assembly Market projected to grow between 2025 and 2032?
Who are the leading players operating in the Indian mobile components manufacturing and assembly market?
What are the main categories of mobile phones and components within this market according to the Credence Research report?
Which state in India leads in the mobile components manufacturing and assembly market?
Who are the leading companies in the Indian Mobile Components Manufacturing and Assembly Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 OEMs (Original Equipment Manufacturers)
- 1.2.2 ODM/EMS (Original Design/Equipment Manufacturing Services)
- 1.2.3 Aftermarket/Repair Centers
- 1.3 By Mobile Type
- 1.3.1 Smartphones
- 1.3.2 Feature Phones
- 1.3.3 Other Phones
- 1.4 By Mobile Components
- 1.4.1 Main Board and Sensor Flex
- 1.4.2 Display/Touchscreen
- 1.4.3 Camera (Primary/Secondary)
- 1.4.4 Battery Pack
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 72 billion → 2032: USD 201.43 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Indian Mobile Components Manufacturing and Assembly Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Indian Mobile Components Manufacturing and Assembly Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Indian Mobile Components Manufacturing and Assembly Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Indian Mobile Components Manufacturing and Assembly Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Indian Mobile Components Manufacturing and Assembly Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Indian Mobile Components Manufacturing and Assembly Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Indian Mobile Components Manufacturing and Assembly Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Indian Mobile Components Manufacturing and Assembly Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 72 billion → 2032: USD 201.43 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Indian Mobile Components Manufacturing and Assembly Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 OEMs (Original Equipment Manufacturers)
- 12.3.7.2 ODM/EMS (Original Design/Equipment Manufacturing Services)
- 12.3.7.3 Aftermarket/Repair Centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Mobile Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smartphones
- 12.4.7.2 Feature Phones
- 12.4.7.3 Other Phones
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mobile Components - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Main Board and Sensor Flex
- 12.5.7.2 Display/Touchscreen
- 12.5.7.3 Camera (Primary/Secondary)
- 12.5.7.4 Battery Pack
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Indian Mobile Components Manufacturing and Assembly End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Indian Mobile Components Manufacturing and Assembly Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Indian Mobile Components Manufacturing and Assembly Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Indian Mobile Components Manufacturing and Assembly Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Electronics Co. Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Xiaomi Corporation
- 18.4 Vivo Mobile Communications Co. Ltd.
- 18.5 Oppo Guangdong Mobile Communications Co. Ltd.
- 18.6 Lenovo Group Ltd.
- 18.7 Lava International Limited
- 18.8 Micromax Informatics Limited
- 18.9 Intex Technologies
- 18.10 Karbonn Mobiles
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

