
Ammunition handling and logistics lead early adoption
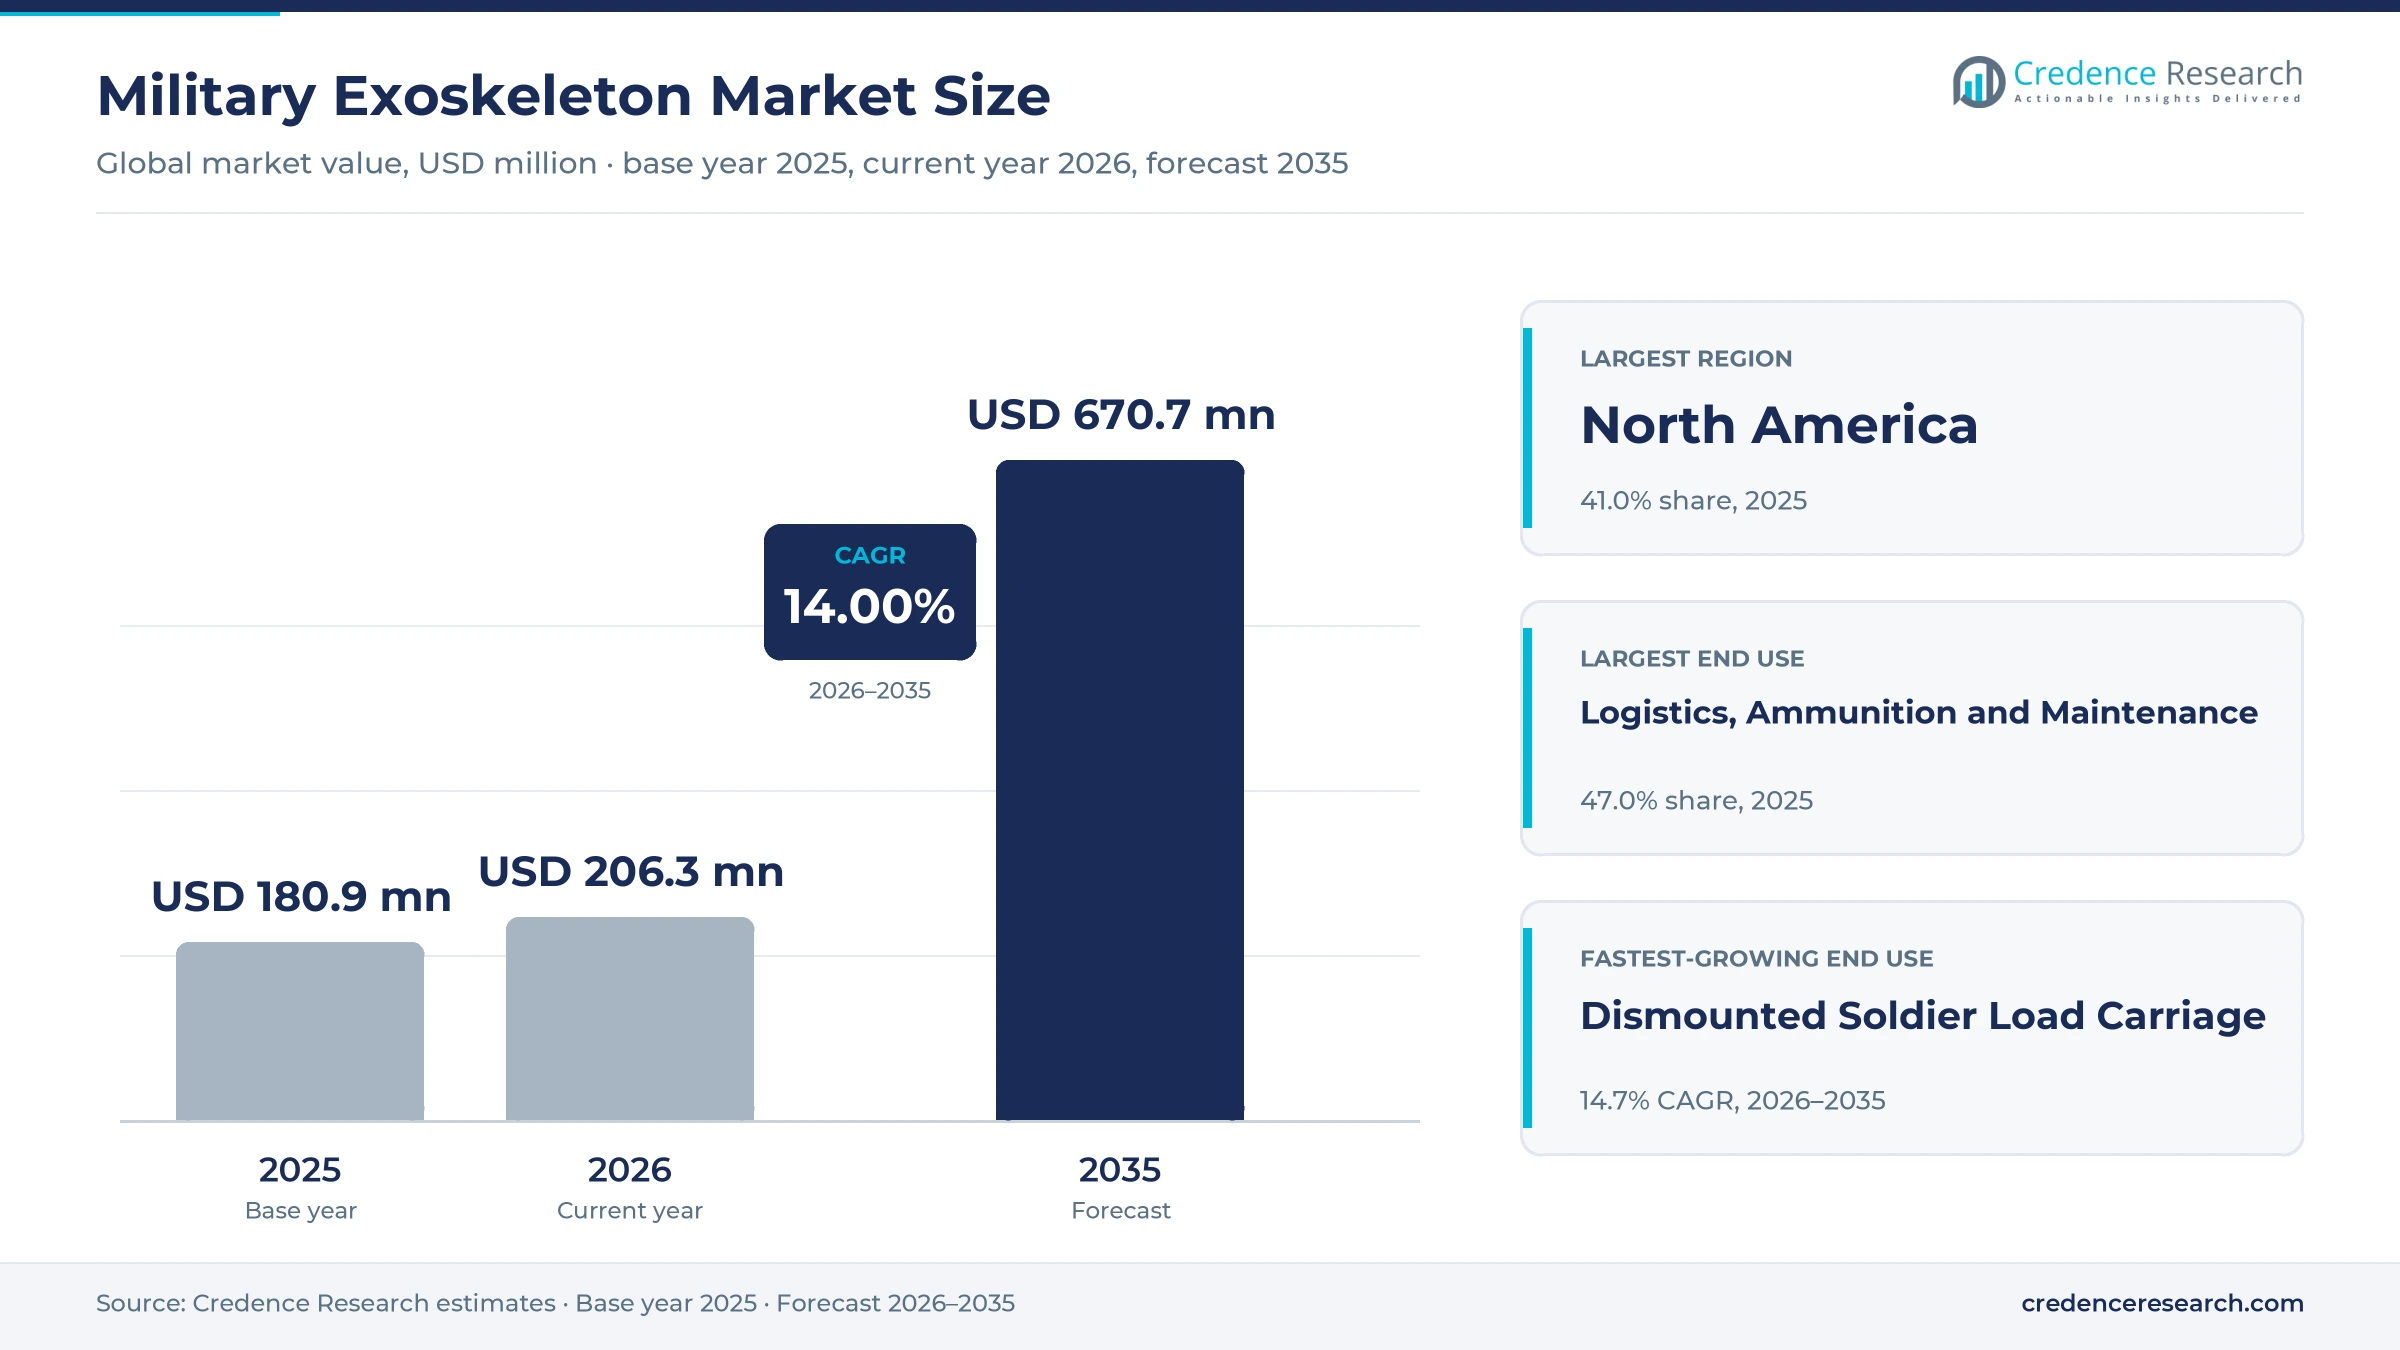
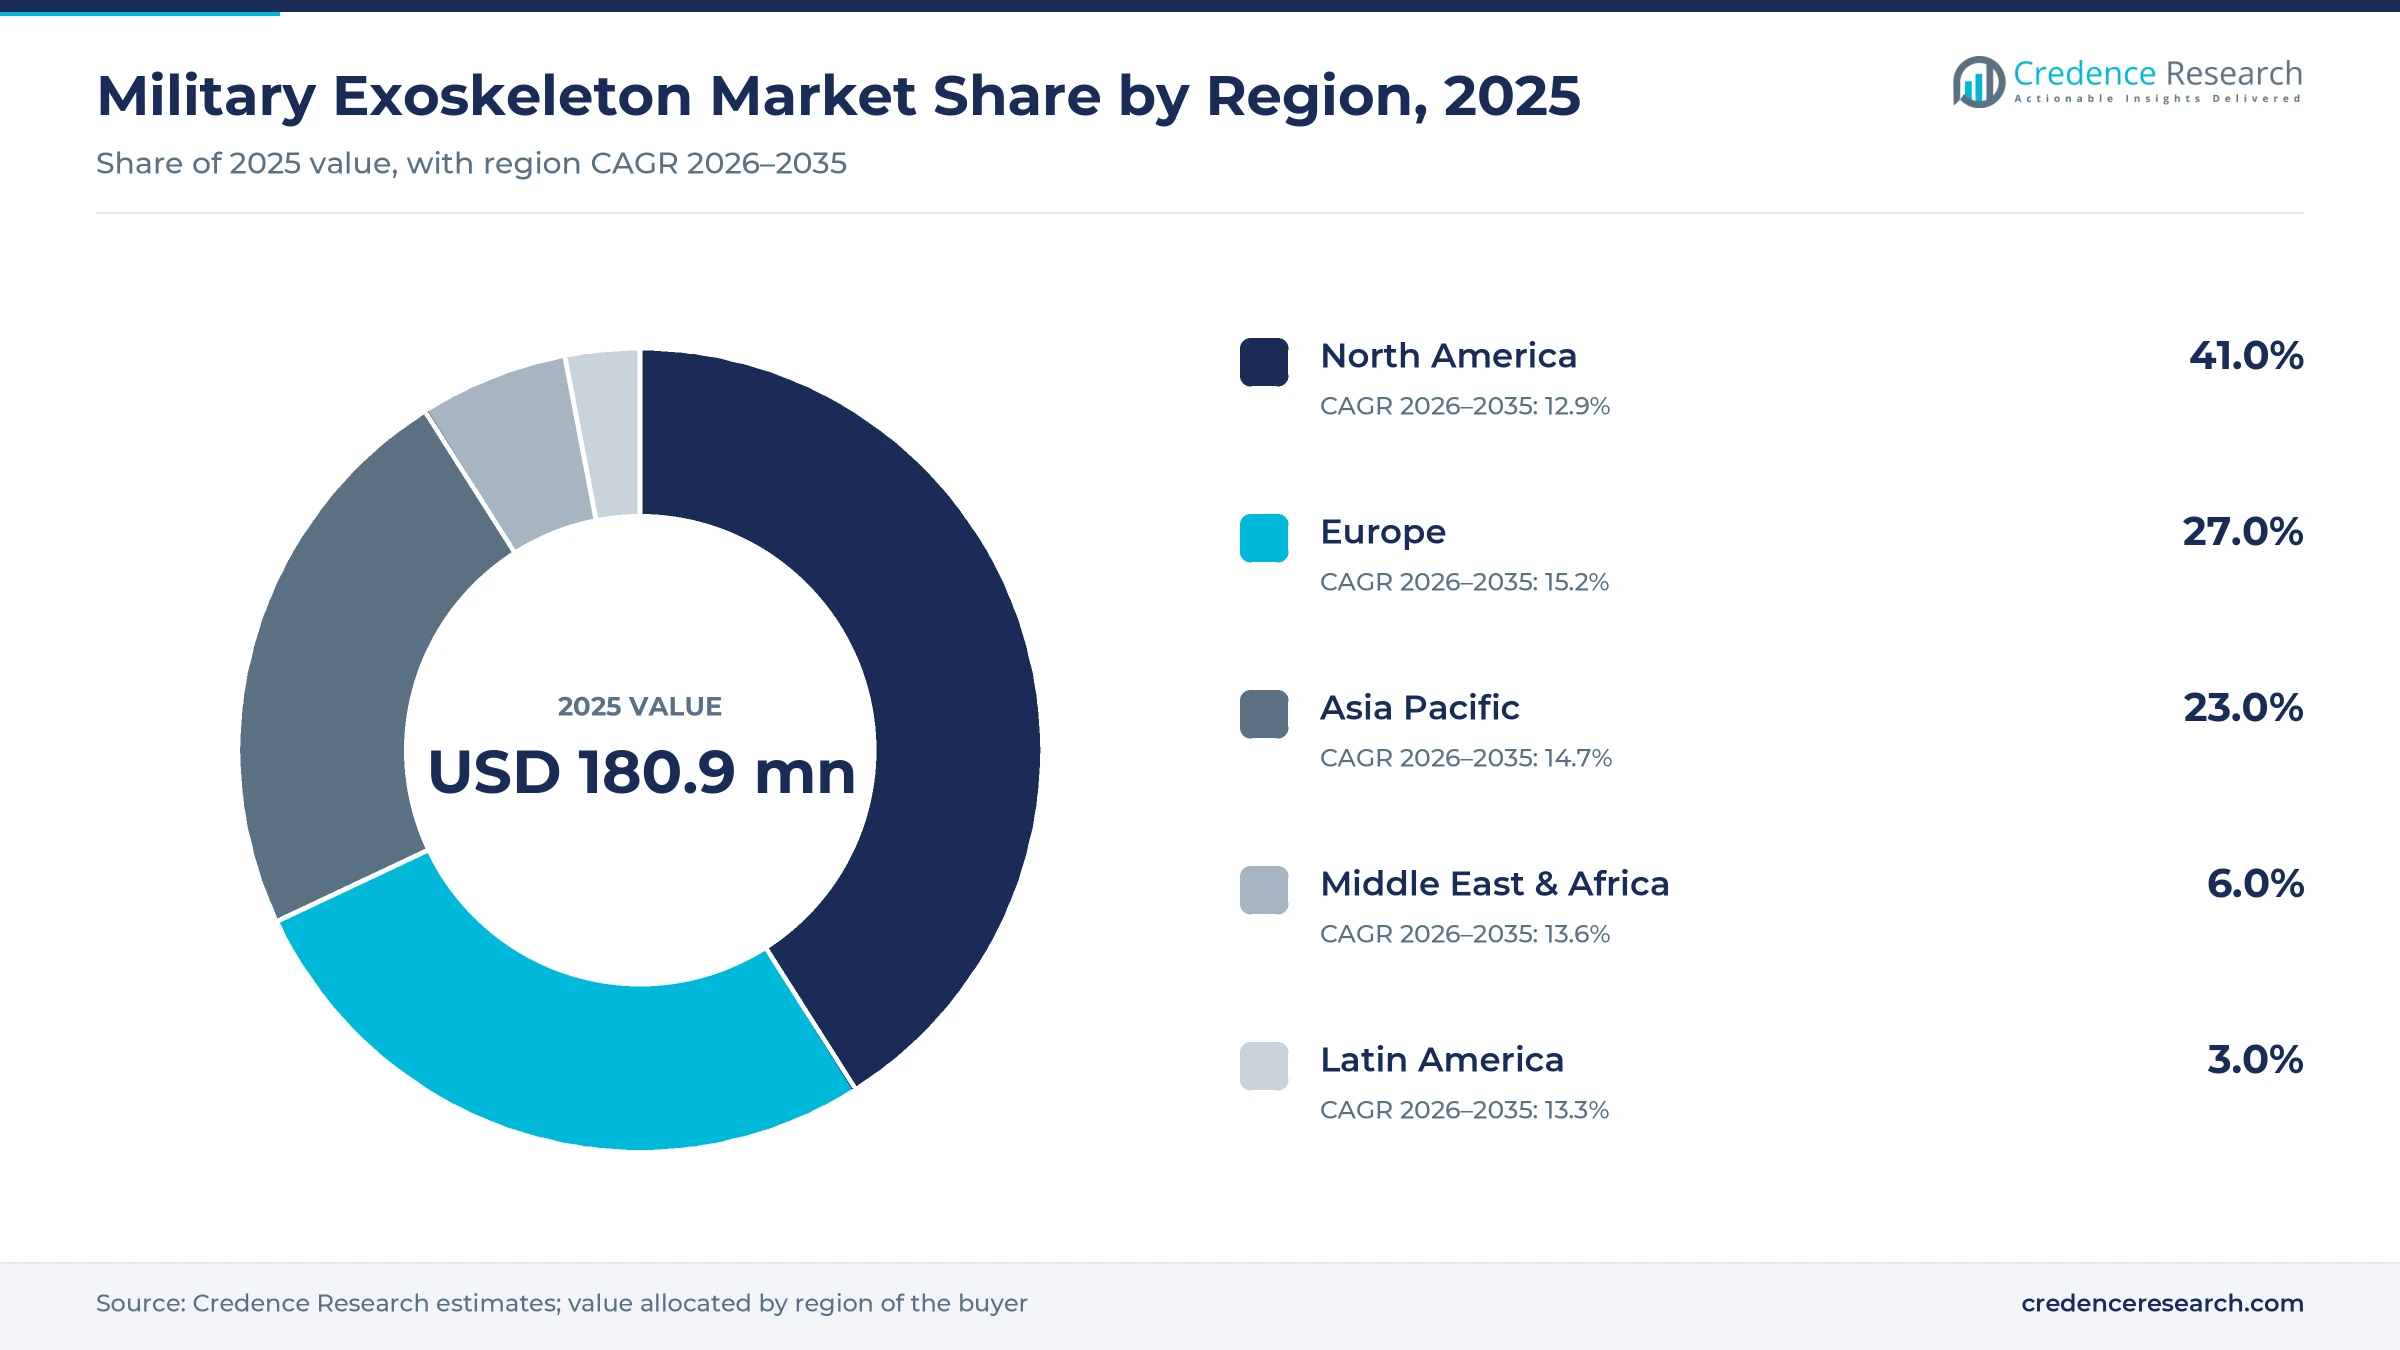
The global military exoskeleton market was valued at USD 180.9 million in 2025 and is projected to increase from USD 206.3 million in 2026 to USD 670.7 million by 2035, registering a CAGR of 14.00% during 2026–2035. Demand comes from armies and air forces that want fewer back and knee injuries among artillery crews, aerial porters, maintainers and infantry carrying heavy loads. North America held the largest regional share, 41.0% in 2025, because U.S. defense health and air force programs fund most powered device trials. Europe is the fastest-growing region at 15.2% a year, as Ukraine moves exoskeletons into frontline artillery units and French logistics brigades test powered back supports. The main commercial change is regulatory, since the United States now lists developmental exoskeletons funded by the Department of Defense on its munitions list, which tightens export rules for new military designs funded after Jan. 20, 2026, while devices already in production stay outside that control.
Armies are buying load support for crews before combat suits
The market counts the value of powered and passive exoskeletons sold to armed forces, defense agencies and military medical commands, including lower-limb, hip, back and full-body systems, together with their batteries, fitting kits and defense-funded development contracts. Most purchases today are trial lots and small field batches, so a single program decision can move regional demand within a year.
Civilian industrial and rehabilitation exoskeletons sold to factories, warehouses and hospitals are excluded, even when the same product family is offered to armed forces. Value sits with device makers that design actuators, control software and frames, with battery and motor suppliers, and with defense integrators that fit devices to soldier equipment and run field trials.
Military Exoskeleton Market Insights
- The global military exoskeleton market was valued at USD 180.9 million in 2025 and is projected to reach USD 670.7 million by 2035, growing at a 14.00% CAGR during 2026–2035.
- North America held 41.0% of 2025 value, because U.S. Army, Air Force and defense health programs fund most powered device trials.
- Logistics, ammunition and maintenance tasks held 47.0% of 2025 value, as artillery crews and aerial porters show the clearest benefit.
- The U.S. munitions list entry for developmental exoskeletons took effect on Sept. 15, 2025, which tightens exports of exoskeletons developed under DoD contracts dated after Jan. 20, 2026.
- Ukraine made combat exoskeletons a Brave1 grant priority in July 2026, after its 147th artillery brigade used leg devices near Pokrovsk.
Partial-body powered devices hold most of the value
Lower-limb and hip devices lead as full-body suits gain
Based on type, the market is categorized into partial-body exoskeletons and full-body exoskeletons. Partial-body Exoskeletons led with 74.0% of 2025 value because lower-limb and hip devices are light enough to wear with combat gear, and the leg units issued to Ukrainian artillery crews weigh about 2 kg, according to Euromaidan Press. Full-body Exoskeletons grow fastest at 14.9% a year as heavy lifting suits move from prototypes toward trials, and Blood Wing's Vanguard suit, previewed before the 2025 Shanghai defense expo, is claimed by its engineers to handle a 220 lb continuous load, according to Defense One.
Powered units hold value while passive frames scale
Based on power, the market is categorized into active (powered) and passive exoskeletons. Active (Powered) systems led with 61.0% of 2025 value because motors and control software raise the price per unit, and Roam Robotics' pneumatic Forge showed productivity gains of up to 40% with U.S. Air Force cargo crews in January 2026. Passive frames grow fastest at 14.6% a year as they need no batteries, and Tata Advanced Systems and DRDO put a spring and damper exoskeleton into Indian Army trials in May 2025 that moves up to 75% of carried load to the ground.
Ammunition and cargo handling lead while infantry use gains
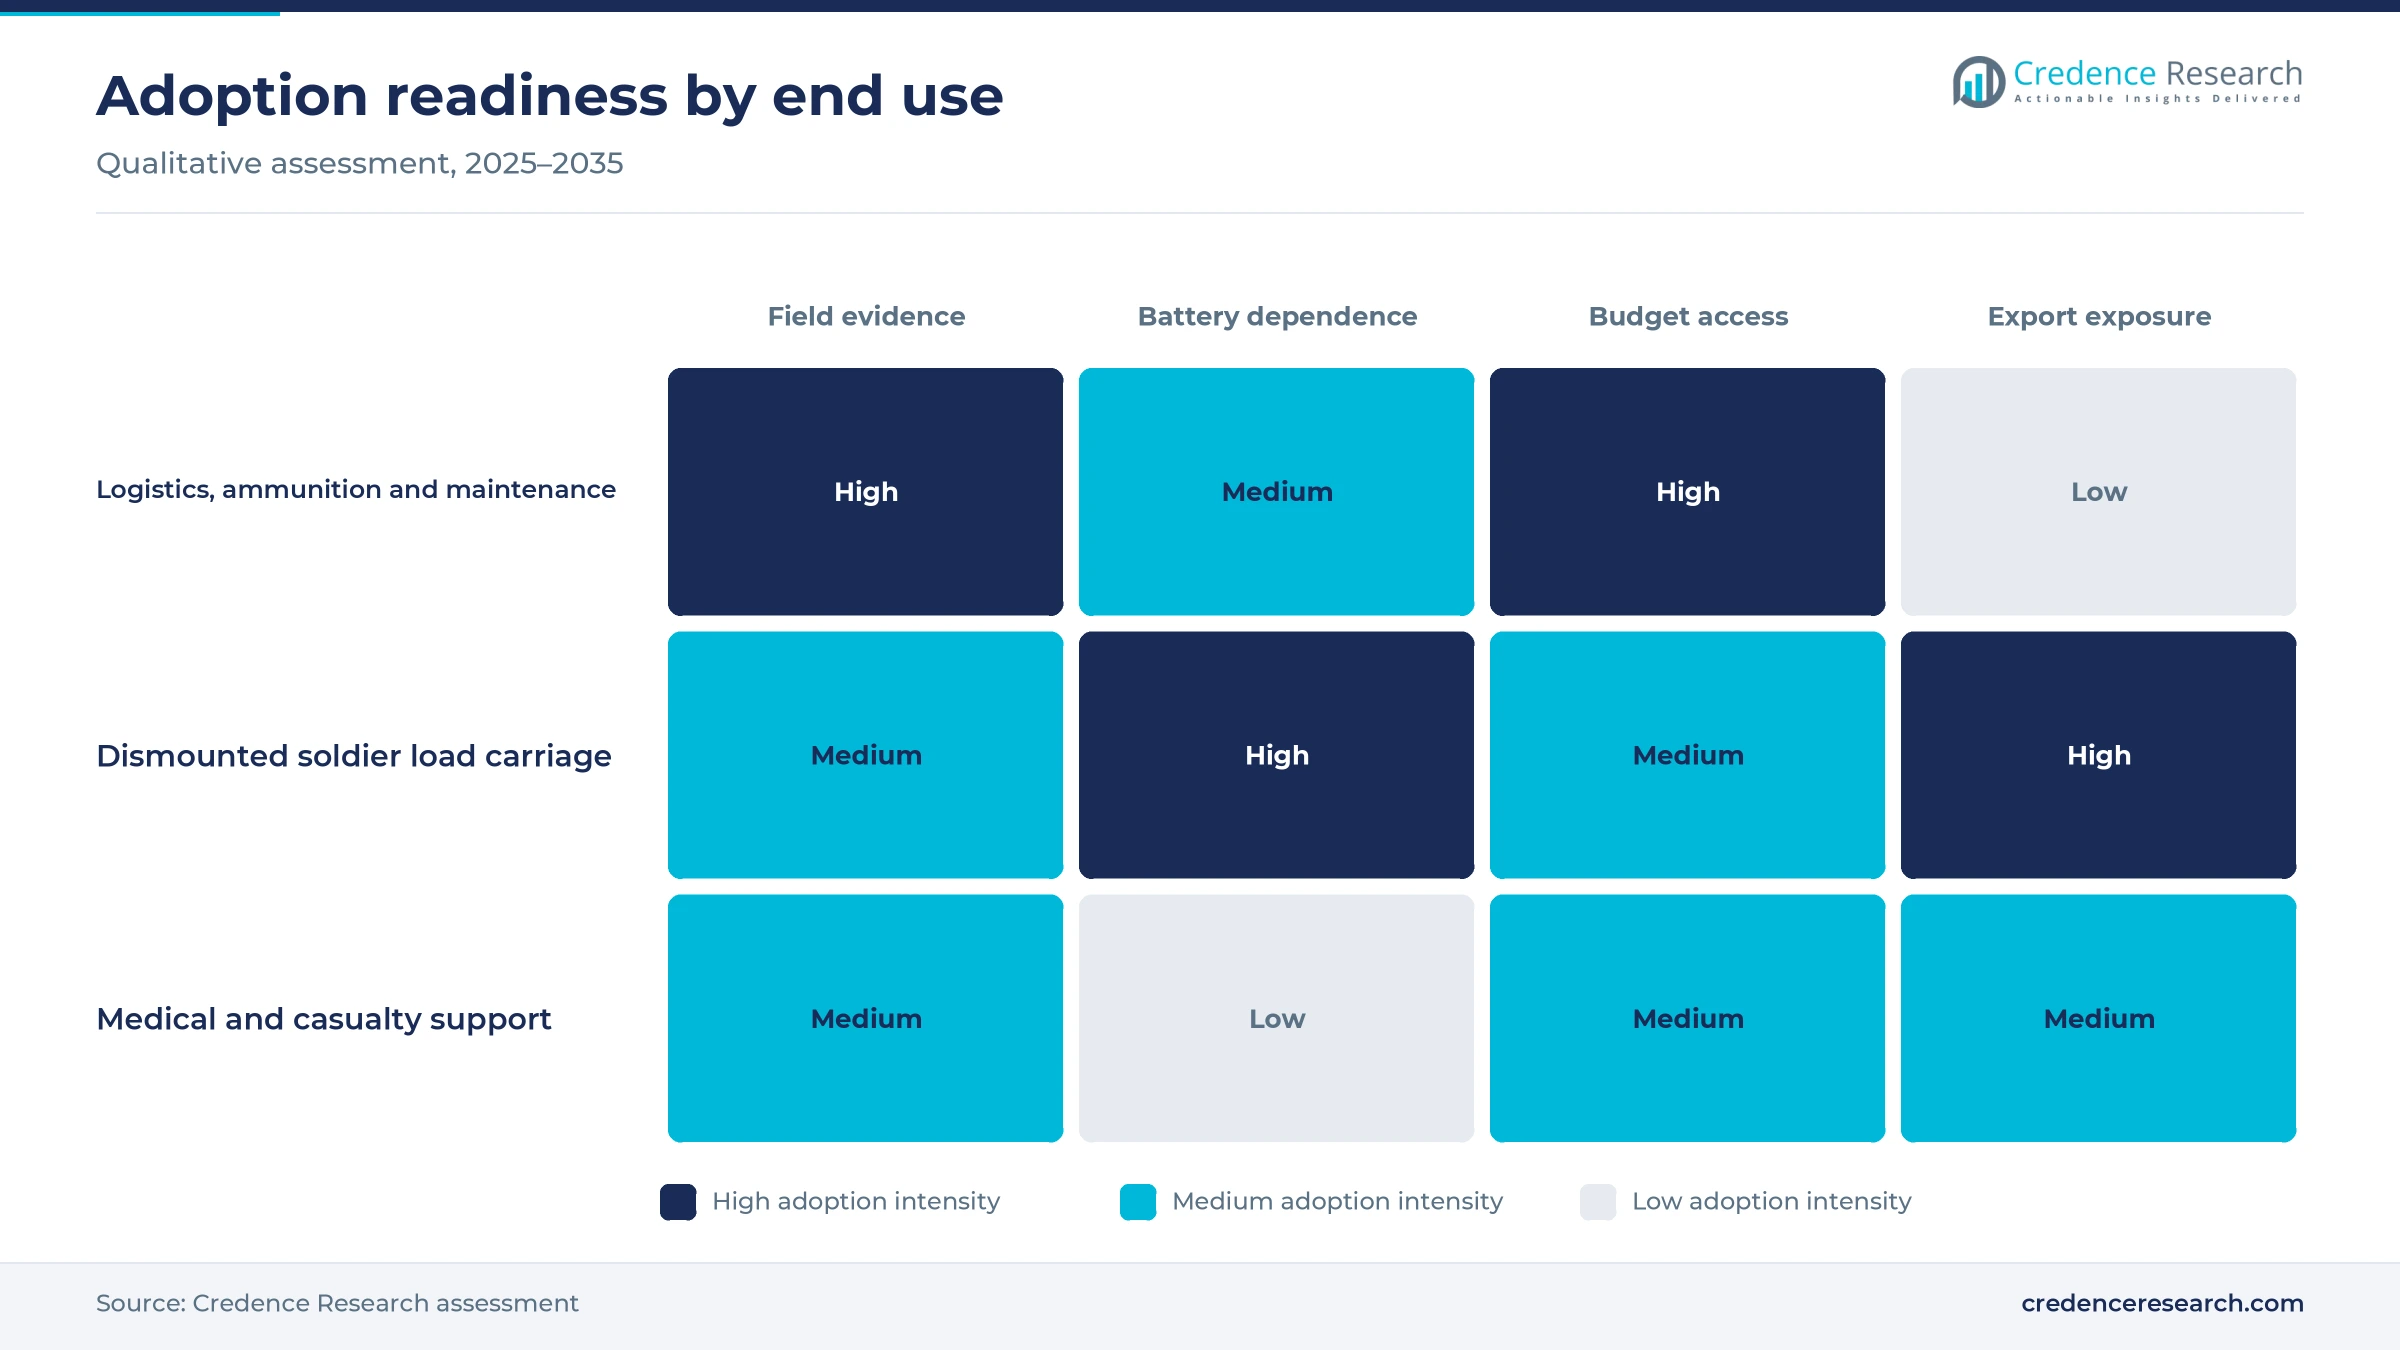
Based on end use, the market is categorized into logistics, ammunition and maintenance, dismounted soldier load carriage, and medical and casualty support. Logistics, Ammunition and Maintenance led with 47.0% of 2025 value because repeated lifting shows the clearest benefit, and Ukrainian artillery crews carry 15 to 30 shells of about 50 kg each to their guns, according to Euromaidan Press. Dismounted Soldier Load Carriage grows fastest at 14.7% a year as armies test devices on marches, and NATO mountain units evaluated a powered hip unit on loaded marches in November 2025.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Partial-body Exoskeletons | 74.0% | Full-body Exoskeletons | 14.9% |
| By Power | Active (Powered) | 61.0% | Passive | 14.6% |
| By End Use | Logistics, Ammunition and Maintenance | 47.0% | Dismounted Soldier Load Carriage | 14.7% |
Unit prices span commercial hip units to custom suits
Prices fall into three bands, because most armies buy commercial hip or back devices off the shelf, while combat-grade suits are still bought as development contracts. Hypershell lists its powered hip units at USD 999 to USD 1,999, and German Bionic priced its Apogee+ back exoskeleton at USD 9,900, according to Engadget in January 2025. Rugged housings, battery swaps, fitting to body armor and security reviews add to these list prices once a device is adapted for defense buyers. Suppliers earn the highest margins on development contracts and spare batteries, while low-cost commercial units compress hardware margins on simple hip and knee devices.
| Device or program | Typical price or fee | Basis |
|---|---|---|
| Commercial powered hip unit | USD 999 to USD 1,999 list price | Hypershell list prices, 2026 |
| Powered back exoskeleton for lifting | About USD 9,900 per unit | Engadget on German Bionic, January 2025 |
| Ukrainian development grant per project | Up to about USD 190,000 | UNITED24 Media on Brave1, July 2026 |
| Military-grade powered lower-limb system | USD 20,000 to USD 60,000 per unit | Credence Research estimate from trial and program data |
| Passive military frame | USD 1,000 to USD 5,000 per unit | Credence Research estimate from published device specifications |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Injury costs, war lessons and grants pull units into trials
Musculoskeletal injury costs push armies toward load support
Musculoskeletal injuries are the core demand mechanism, because each injured soldier removes trained manpower from duty and adds medical cost. A 2024 expert review on wearable robots in military rehabilitation notes that the U.S. services reported over 2 million musculoskeletal clinic visits in 2017, leading to about 8 million limited-duty days. The same review says these problems among service members exceed the civilian rate by more than tenfold. U.S. medical commands also count just over 22,000 non-amputated lower-leg injuries between 2001 and 2018, which keeps knee and ankle support on their research agenda. Device makers that publish injury and fatigue data from trials gain the strongest case with defense health buyers.
War in Ukraine turns trials into frontline use
Combat experience in Ukraine is converting exoskeletons from demonstrations into field equipment, because artillery and infantry units cannot rely on vehicles near the front. The 7th Rapid Reaction Corps said in March 2026 that its 147th artillery brigade was the first Ukrainian unit to use exoskeletons in combat conditions, with leg devices that reduce muscle load by up to 30%. Military Trade introduced its passive Gyurza-1 into field tests with several units in April 2026, rated for loads of up to 70 kg. Edgerun reported more than 100 field tests of its hip device in Ukraine by August 2026. These results give Western buyers combat evidence that earlier test programs never produced.
Rising defense budgets fund soldier systems and grants
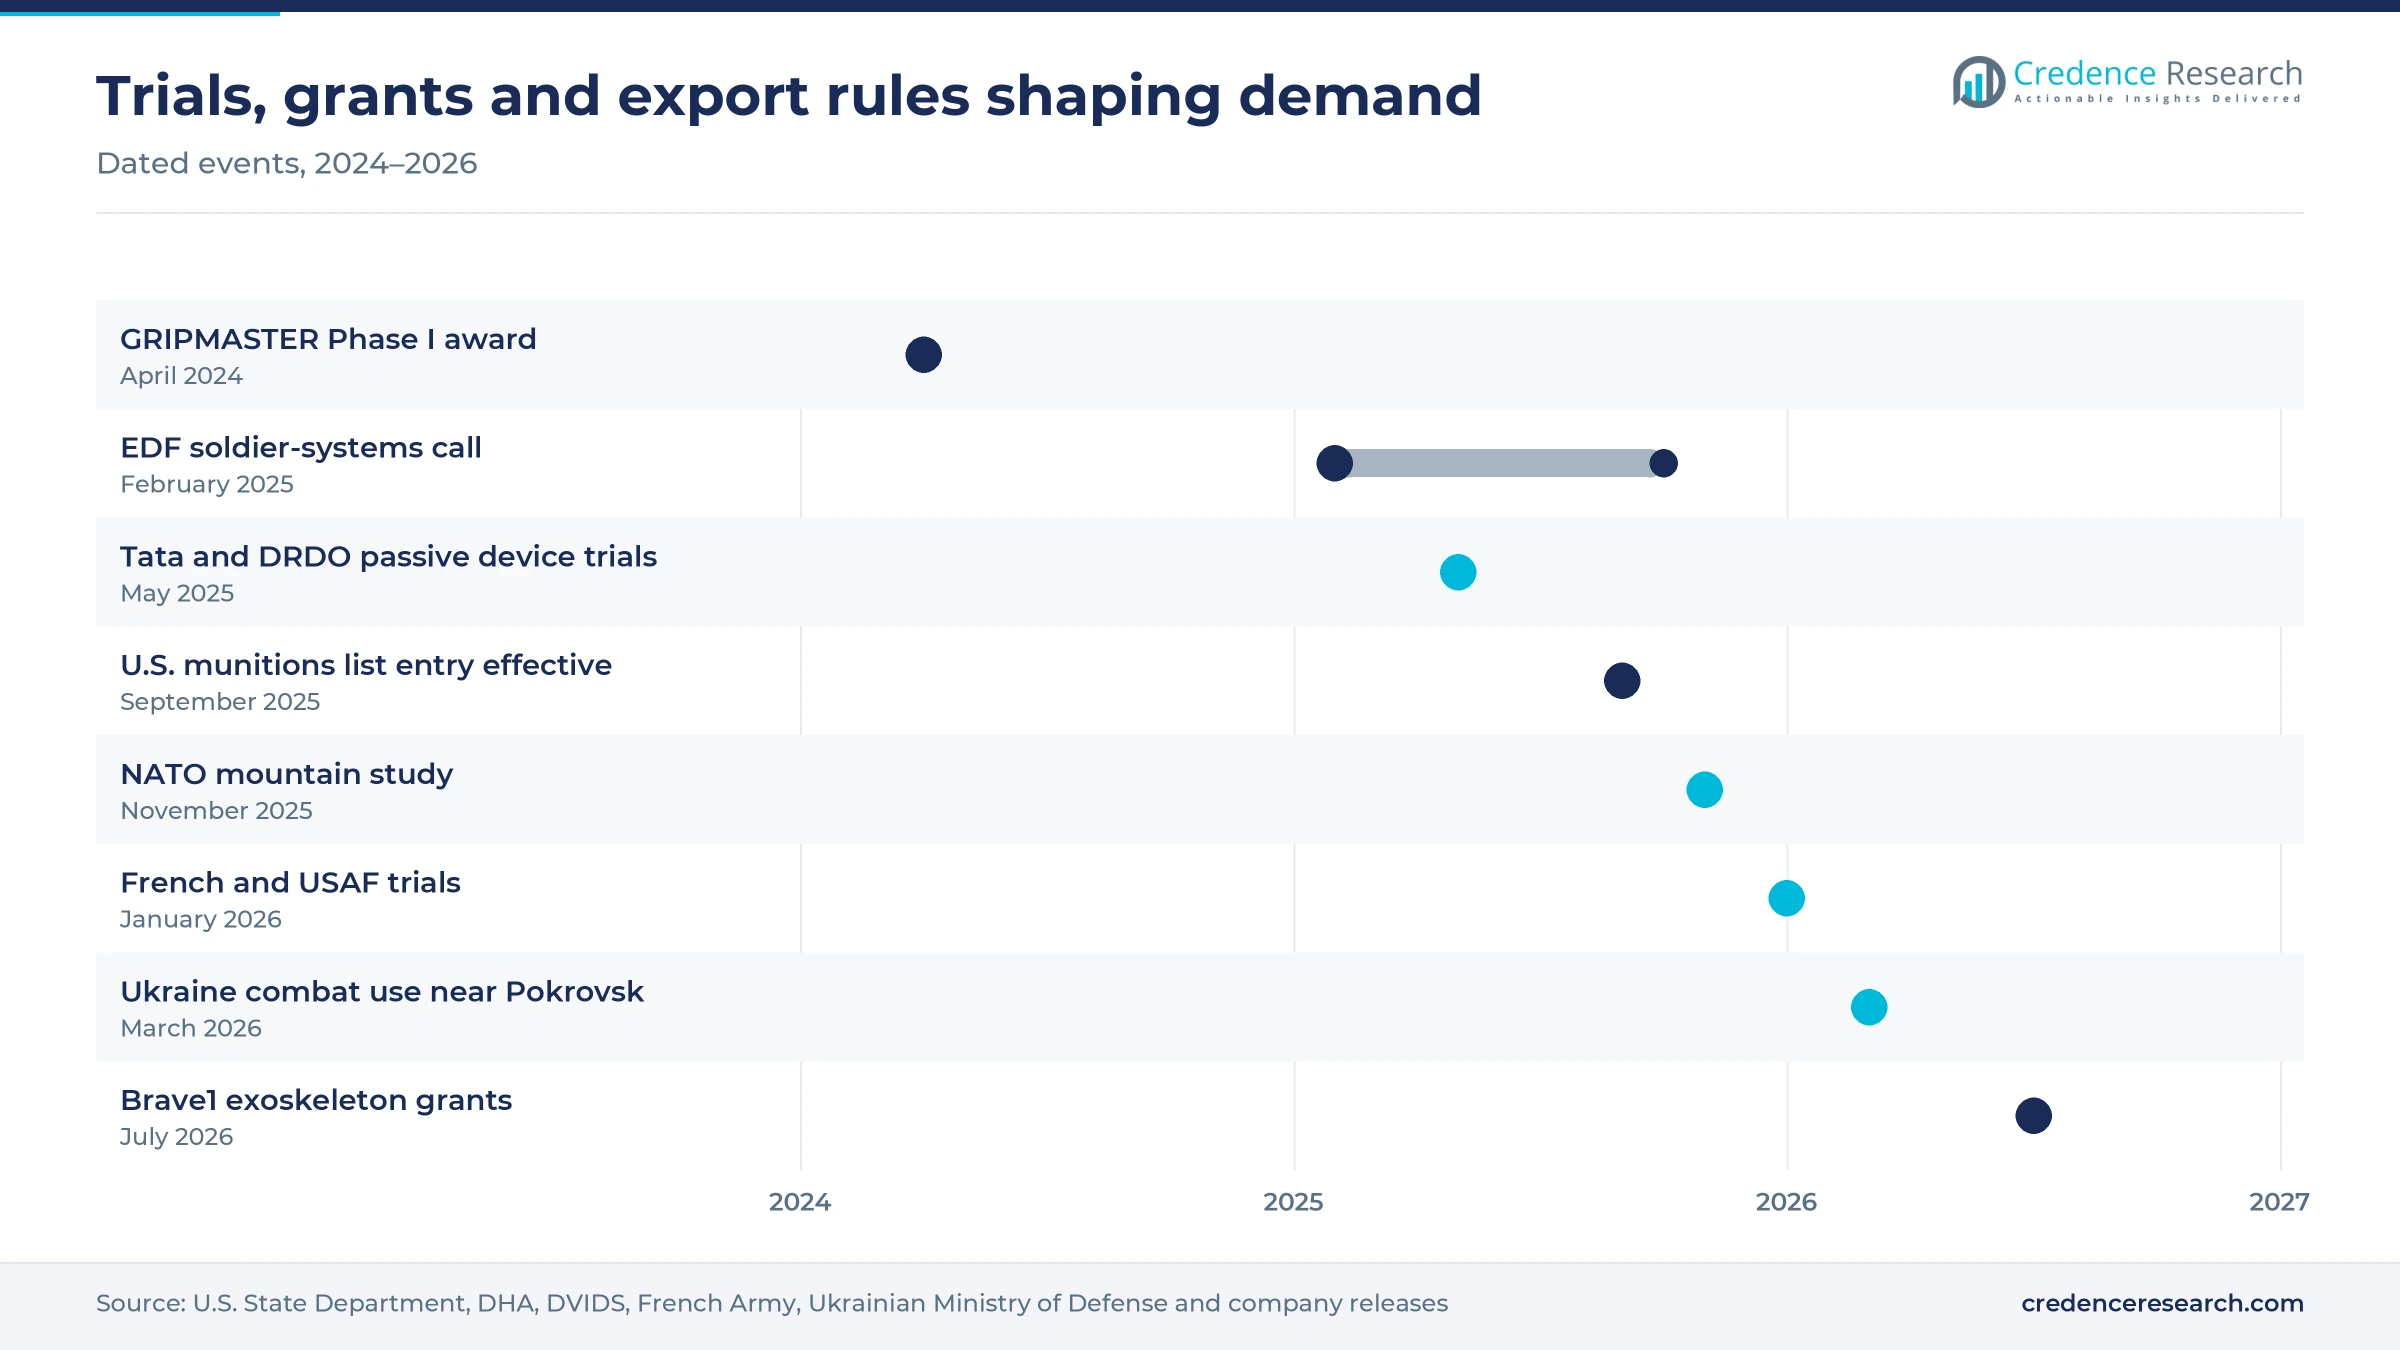
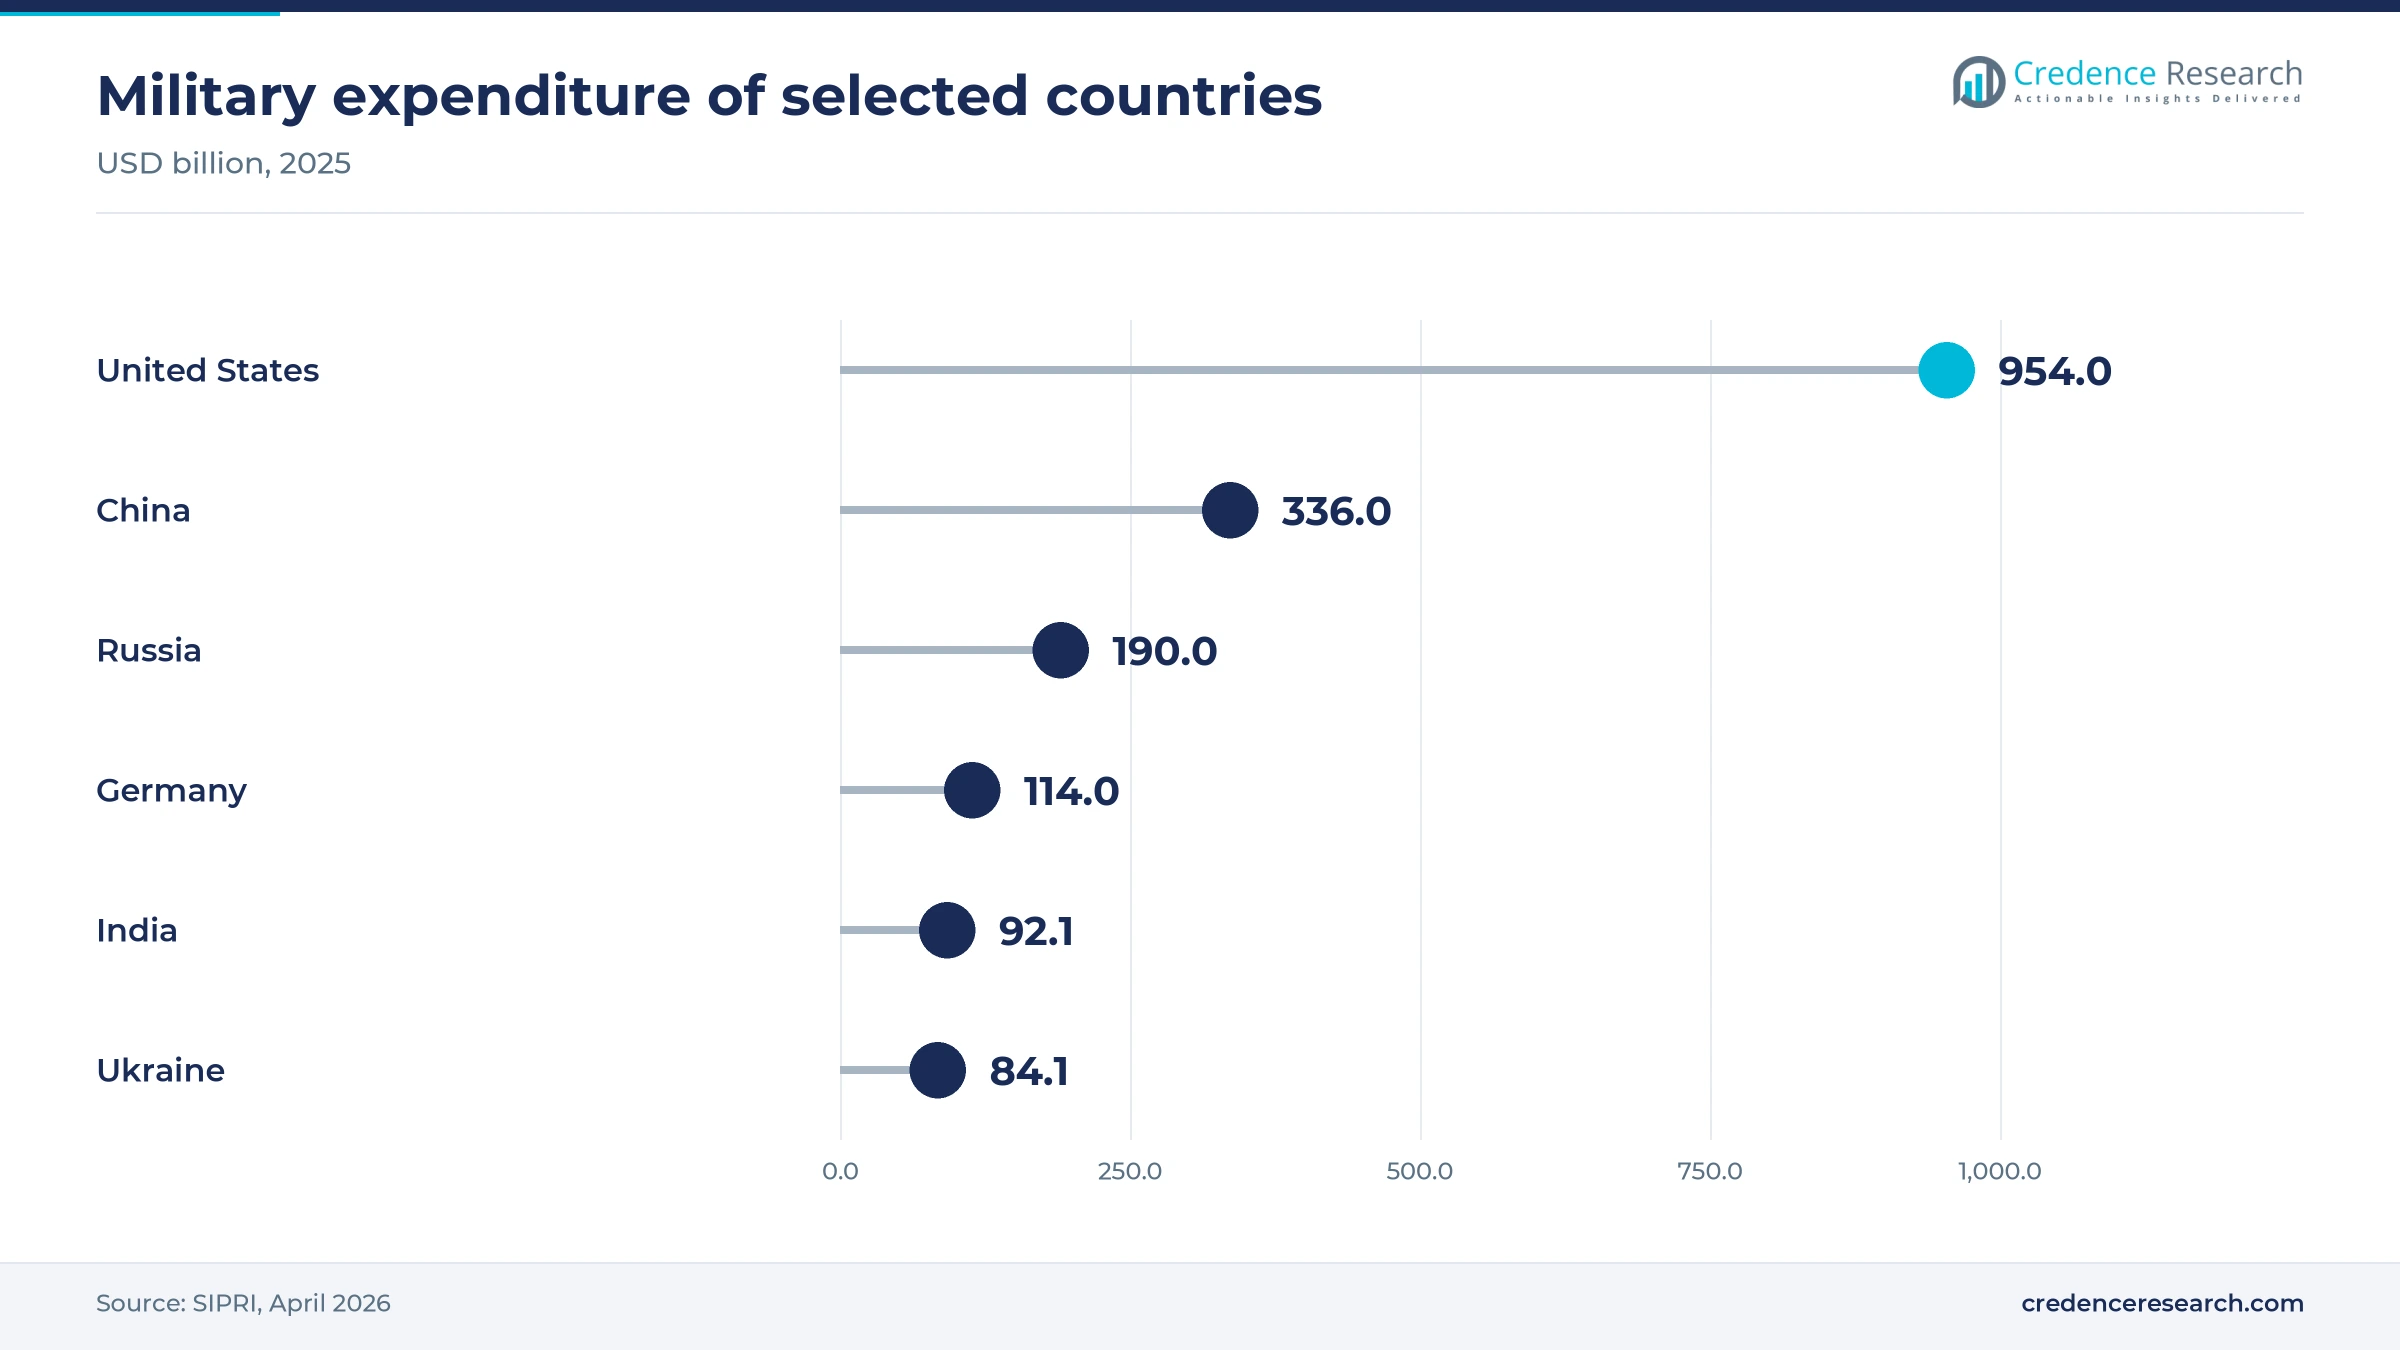
Larger defense budgets widen the funding pool for soldier equipment, since exoskeletons compete for money with protective gear, radios and night vision inside the same programs. World military spending reached USD 2,887 billion in 2025, up 2.9% in real terms, and European spending rose 14% to USD 864 billion, according to SIPRI in April 2026. The European Defence Fund launched a EUR 35 million call in February 2025 for next-generation dismounted soldier systems that names external augmentation against carried load. Ukraine also widened its Brave1 grants for exoskeleton prototypes in July 2026, which lowers development risk for national suppliers.
Air forces and maintainers need lifting help on long shifts
Air bases and maintenance units add a second demand base, because cargo loading and repair work repeat the same lifts for whole shifts. Airmen of the 386th Air Expeditionary Wing evaluated the Roam Robotics Forge for cargo and maintenance tasks in January 2026, and early results showed productivity gains of up to 40%, according to DVIDS. The French Army maintenance brigade began new trials in January 2026 with RB3D Exoviti and Exoback units and the German Bionic Exia, aimed at loads of up to 100 kg. This work suits powered back and knee devices that meet indoor and airfield conditions before they face field use.
Low-cost hip devices and logistics suits reshape buying
Armies are shifting toward low-cost commercial hip devices
Armies are shifting toward commercial hip and knee devices to address urgent load problems at low cost, creating openings for consumer-derived products across infantry and artillery units. Hypershell lists powered hip units from USD 999, far below the cost of custom defense prototypes, and a NATO mountain warfare study tested its X model with Slovenian and German mountain troops in November 2025. Edgerun launched a hip device of about 10 pounds in August 2026 that it says cuts metabolic effort by 30% to 45%. The leg devices in Ukraine also fold into a small case. This shift favors suppliers with volume production and quick repair over firms selling one-off suits.
Passive frames are emerging as a battery-free option
Defense buyers are shifting toward passive frames to address battery supply and electronic signature concerns, creating openings for spring-based devices across logistics, engineering and evacuation tasks. Gyurza-1 weighs under 2 kg, uses no electronics and is designed for loads of up to 70 kg. The Tata and DRDO passive design for the Indian Army transfers up to 75% of load to the ground and entered trials in May 2025. Norinco delivered a passive backpack-style frame to PLA troops on the Tibet border in 2020, according to Defense One. Low prices make passive frames easier to issue widely, although each unit adds less value than a powered system.
Casualty self-evacuation opens a medical opportunity
Military medical commands are an underserved customer group, because wounded soldiers often wait for evacuation when vehicles and stretcher teams are exposed. The U.S. Army Medical Research and Development Command is advancing the IBEX battlefield exoskeleton, a 7 lb device that lets a soldier with a lower-leg injury stand and walk, which has finished field trials with the Army, Navy and Marines and survived a 400-foot drop from a cargo drone. A commercial partner has already licensed the design for later manufacture. The Defense Health Agency also funded Aptima under a Phase I award in April 2024 to develop the GRIPMASTER hand device for litter carrying. Makers that pass medical and drone-delivery testing could sell into combat medic kits.
Grant programs open a supply route for smaller makers
Government grant programs give startups a route to defense buyers that once favored large primes, because grants pay for prototypes before a procurement decision. Ukraine's Ministry of Defense announced in July 2026 that combat exoskeletons are a flagship priority of its Brave1 grant program, according to UNITED24 Media, with awards from about USD 12,000 to USD 190,000 depending on technology readiness. The EDF soldier-systems call includes financial support of up to EUR 60,000 each for small firms in a six-month acceleration program. India pairs DRDO with Tata Advanced Systems, which gives a domestic supplier access to Army trials. Suppliers that can show combat or trial data are best placed when these grants turn into orders.
Battery life, fit and export controls slow fielding
Battery life and fit still limit combat use
Power and comfort remain the main technical limits, because a device that runs out or chafes is left behind on a march. A 2024 expert review estimates that demanding military tasks need about 50 to 300 W/kg of specific power, which current drives struggle to reach. The same review lists long battery life and easily replaceable batteries among the requirements for field use, which few current devices meet. Infantry units are most exposed, while logistics units with charging points can adopt devices sooner.
U.S. munitions list control tightens powered exports
The State Department added developmental exoskeletons funded by the Department of Defense to Category X of the U.S. Munitions List, with the rule effective Sept. 15, 2025. The entry covers designs funded under DoD contracts dated after Jan. 20, 2026, and it excludes devices already in production and devices that the contract identifies as developed for both civil and military use. U.S. startups that use foreign engineers, overseas test sites or shared design files are most exposed, and allied buyers may face longer waits for U.S. powered systems.
U.S. spending dip and test cycles delay orders
U.S. military spending fell 7.5% in 2025 to USD 954 billion, as no new aid for Ukraine was approved, according to SIPRI. Exoskeletons still pass through long evaluation cycles, and an Air Force Research Laboratory engineer said earlier military exoskeletons often failed to transition because no formal requirements existed, so he worked with Air Mobility Command to draft airfield logistics requirements. Small suppliers that depend on test contracts carry the cash gap, since trial lots rarely cover development costs before a program of record exists.
Uneven trial results weaken the case for wide issue
Trial results vary widely by task, so procurement officers struggle to justify issuing devices to whole units. In the NATO mountain study of 20 soldiers, the powered hip unit reduced physical effort mostly by a minor amount, and some participants reported restricted movement. Makers selling to infantry are most exposed, because small or mixed gains on marches compete with lighter loads and unmanned carriers for the same budget.
North America leads while Europe grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 74.2 | 41.0% | 12.9% |
| Europe | 48.8 | 27.0% | 15.2% |
| Asia Pacific | 41.6 | 23.0% | 14.7% |
| Middle East & Africa | 10.9 | 6.0% | 13.6% |
| Latin America | 5.4 | 3.0% | 13.3% |
North America leads on U.S. defense health and air programs
North America held 41.0% of 2025 value and grows at 12.9% a year, and the United States accounts for most of the regional total in the Credence Research estimates. The Army medical command, the Defense Health Agency and the Air Force fund IBEX, GRIPMASTER and Forge evaluations, so spending is weighted toward development contracts rather than large orders. Export controls on newly funded developmental designs may keep the next generation of U.S. powered systems at home, although devices already in production remain outside the entry.
Europe grows fastest on Ukraine and French trials
Europe held 27.0% of 2025 value and grows fastest at 15.2% a year. Ukraine supplies the strongest field demand, as artillery brigades use leg devices and Brave1 funds domestic designs such as Gyurza-1. France tests RB3D and German Bionic systems in its maintenance brigade. European military spending rose 14% in 2025, which gives soldier equipment programs more room in national budgets.
Asia Pacific grows on PLA logistics and Indian trials
Asia Pacific held 23.0% of 2025 value and grows at 14.7% a year. Chinese plateau brigades tested powered suits near the Indian border in January 2025, and a June 2025 Northern Theater exercise used exoskeletons to move munitions, according to Defense One. India adds demand through the Tata and DRDO passive design, and Asia and Oceania military spending rose 8.1% to USD 681 billion in 2025, the largest annual rise since 2009.
Middle East & Africa demand rests on a few large forces
Middle East & Africa held 6.0% of 2025 value and grows at 13.6% a year. Middle East military spending reached about USD 218 billion in 2025, only 0.1% above 2024, and Saudi Arabia spent USD 83.2 billion, while African spending rose 8.5%, according to SIPRI. No verified exoskeleton order or trial in the region was found for this edition, so the regional share rests on spending levels and import patterns rather than program evidence.
Latin America remains an early, budget-limited buyer
Latin America held 3.0% of 2025 value and grows at 13.3% a year, the smallest share among the five regions. Armies in the region buy soldier equipment in small batches, often through soldier modernization programs that put radios and protection first. No verified exoskeleton trial was found in Latin America for this edition, so this estimate carries the widest uncertainty of any region.
Trials, grants and export rules mark 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In October 2026, Wandercraft completed its acquisition of Ekso Bionics, combining the two medical exoskeleton businesses. | Completed acquisition; the deal is focused on rehabilitation and leaves fewer listed exoskeleton makers selling to defense |
| In July 2026, Ukraine's Ministry of Defense made combat exoskeletons a flagship Brave1 grant priority with awards of up to about USD 190,000. | Program announced; grants fund prototypes and testing for domestic suppliers |
| In April 2026, Military Trade began field testing the passive Gyurza-1 exoskeleton with several Ukrainian units. | Testing milestone; feedback is being collected before any procurement decision |
| In March 2026, Ukraine's 147th Separate Artillery Brigade used leg exoskeletons to carry shells near Pokrovsk. | Operational use in combat conditions, the first reported by a Ukrainian unit |
| In January 2026, the French Army maintenance brigade began trials of RB3D and German Bionic exoskeletons. | Testing under way in two regiments, supervised by military schools in Bourges |
Actuation, power and control set field usefulness
- Electric hip and knee actuation adds torque at the joints during walking and climbing, which suits marches and stair work but depends on battery supply.
- Pneumatic actuation uses air pressure to support the knees and back, as in the Roam Robotics Forge evaluated with cargo crews on air bases.
- Passive spring and damper frames store and release energy without electronics, which keeps weight under about 2 kg and removes charging needs.
- Power and control systems use lithium-ion battery packs and gait-sensing software that adapts assistance to each wearer and task.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Startups and state groups compete on field evidence
Competition splits between commercial startups that win trials on price and quick delivery, European logistics specialists and state groups or national partners that serve their own armed forces. Roam Robotics competes on pneumatic knee and back support proven with U.S. Air Force cargo crews. German Bionic and RB3D compete in lifting support for maintenance units, starting with the French Army. Hypershell and Edgerun compete on low-cost powered hip devices tested by NATO and Ukrainian troops, while Military Trade offers a passive design built for Ukrainian conditions. Norinco and CASIC supply the PLA, and Tata Advanced Systems works with DRDO for the Indian Army. Products sit close to the wider market for wearable robots, so civilian volume helps suppliers cut unit costs.
A fragmented field of startups and state groups
The supply side is fragmented, because no army has yet bought exoskeletons at program-of-record scale. Earlier entrants such as Lockheed Martin ran Army development agreements for ONYX in 2018 and 2019, yet no current military sale was verified for this edition, and Sarcos and Ekso Bionics have moved away from defense hardware. Startups such as Roam Robotics, Hypershell and Edgerun now compete with Chinese state groups and national partners such as Tata Advanced Systems. Entry barriers are field evidence, fit with body armor and export clearance, and margins are likely highest on development contracts and batteries.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Roam Robotics | Specialist | Pneumatic Forge knee and back exoskeleton evaluated by U.S. Air Force cargo crews |
| German Bionic | Specialist | Powered back exoskeletons, including Exia trialed by the French Army |
| RB3D | Specialist | Exoviti and Exoback lifting exoskeletons in French Army maintenance trials |
| Tata Advanced Systems Limited | Defense manufacturer | Passive exoskeleton developed with DRDO for Indian Army trials |
| China North Industries Group (Norinco) | State defense group | Passive backpack-style frames delivered to PLA border troops |
| China Aerospace Science and Industry Corporation (CASIC) | State defense group | Powered ammunition support suit for PLA logistics tasks |
| Hypershell | Commercial device maker | Powered hip exoskeletons tested by NATO mountain troops |
| Military Trade | Local manufacturer | Passive Gyurza-1 exoskeleton in field tests with Ukrainian units |
| Edgerun Industries | Specialist | Powered hip exoskeleton field tested with Ukrainian soldiers |
Logistics use will pay before combat suits do
Credence Research's view is that logistics and ammunition handling will pay back before combat suits do. Artillery crews, aerial porters and maintainers repeat heavy lifts near charging points, so devices show a measurable benefit there, while marches still expose weak batteries and poor fit. Logistics tasks held 47.0% of 2025 value, and Ukraine's combat use gives European buyers the evidence they lacked. Suppliers with cheap, rugged devices and field data are best placed, while U.S. powered designs face export controls that may slow their sale to allies.
Unit prices and program counts anchor the model
The report uses 2025 as the base year and 2026–2035 as the forecast period, and it replaces an earlier edition built on a 2024 base year with an older forecast. Market values come from the Credence Research model, built from published device prices, trial and program counts in government and company releases, and defense spending data. Regional, type, power and end-use splits are Credence Research estimates. Sources include SIPRI, the U.S. Army Medical Research and Development Command, DVIDS, the European Defence Fund, peer-reviewed research and company releases. Public data on quantities fielded are thin, especially for China, the Middle East and Latin America. No interviews or surveys were conducted for this edition of the report.
Field evidence from Ukraine shapes demand to 2035
Through 2035, growth comes from logistics and ammunition work, cheaper hip devices and medical uses rather than from full combat suits. Ukraine is likely to be the first army to buy at scale, and European budgets give allied forces room to follow. North America remains the largest region, although export controls may keep U.S. powered designs at home. Integration with body armor and load-bearing equipment, battery weight and trial results on marches are the main uncertainties, since they decide whether devices move from trial lots to unit issue.
Program-of-record decisions set the range
The range depends mostly on whether any large army turns trials into a program of record and buys devices for whole units. Ukrainian procurement after Brave1 testing is the most likely first case, followed by U.S. Air Force logistics units. Slow results on marches, battery limits and export licensing would keep buying at trial-lot scale. The base case assumes steady trial funding with small field batches in Europe and Asia.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 11.0% | USD 527.6 million | Trials stall on comfort and battery limits and budgets move to unmanned carriers |
| Base | 14.00% | USD 670.7 million | Trial funding continues and Ukraine and allied logistics units buy small field batches |
| Upside | 17.0% | USD 847.4 million | Ukraine or the U.S. Air Force adopts a program of record for whole units |
Frequently Asked Questions
How big is the military exoskeleton market?
How large is the U.S. military exoskeleton market?
Does the U.S. Army use exoskeletons?
What is a military powered exoskeleton?
Which armies use exoskeletons in combat?
How much does a military exoskeleton cost?
Which end use grows fastest?
How do U.S. export controls affect exoskeletons?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Partial-body Exoskeletons
- 1.2.2 Full-body Exoskeletons
- 1.3 By Power
- 1.3.1 Active (Powered)
- 1.3.2 Passive
- 1.4 By End Use
- 1.4.1 Logistics, Ammunition and Maintenance
- 1.4.2 Dismounted Soldier Load Carriage
- 1.4.3 Medical and Casualty Support
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 180.9 million → 2035: USD 670.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Military Exoskeleton Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Military Exoskeleton Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Military Exoskeleton Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Military Exoskeleton Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Military Exoskeleton Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Military Exoskeleton Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Military Exoskeleton Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Military Exoskeleton Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 180.9 million → 2035: USD 670.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Military Exoskeleton Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Partial-body Exoskeletons
- 12.3.7.2 Full-body Exoskeletons
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Power - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Active (Powered)
- 12.4.7.2 Passive
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Logistics, Ammunition and Maintenance
- 12.5.7.2 Dismounted Soldier Load Carriage
- 12.5.7.3 Medical and Casualty Support
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Military Exoskeleton End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Military Exoskeleton Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Military Exoskeleton Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Military Exoskeleton Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Roam Robotics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 German Bionic
- 18.4 RB3D
- 18.5 Tata Advanced Systems Limited
- 18.6 China North Industries Group (Norinco)
- 18.7 China Aerospace Science and Industry Corporation (CASIC)
- 18.8 Hypershell
- 18.9 Military Trade
- 18.10 Edgerun Industries
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

