
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Military Land Vehicles Market Size 2024 | USD 23,800 million |
| Military Land Vehicles Market, CAGR | 2.7% |
| Military Land Vehicles Market Size 2032 | USD 29453 million |
Market Overview:
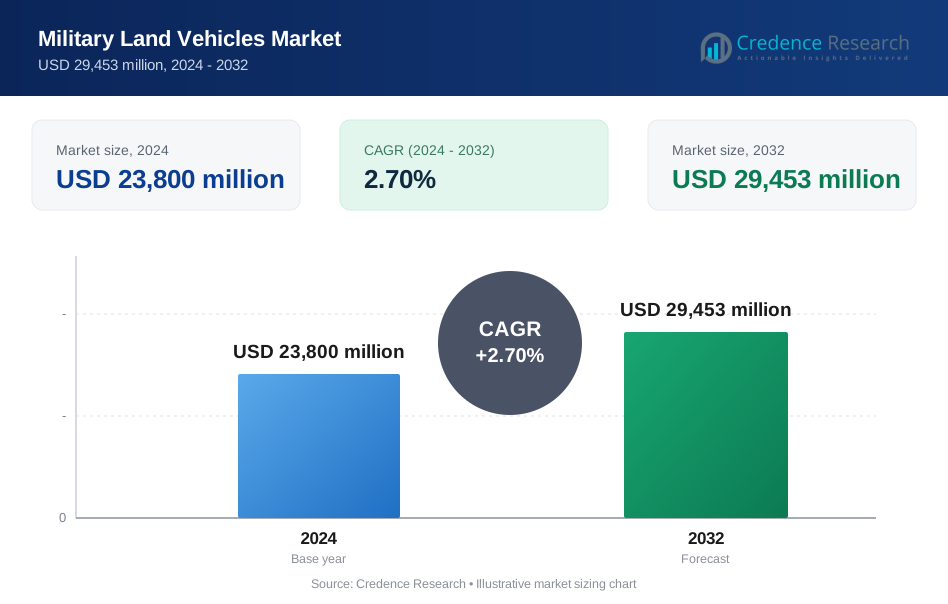
Military Land Vehicles Market size was valued at USD 23,800 million in 2024 and is anticipated to reach USD 29453 million by 2032, at a CAGR of 2.7% during the forecast period (2024-2032).
Key drivers fueling the Military Land Vehicles Market include the ongoing need for force mobility, the evolution of asymmetric warfare, and the increasing importance of cross-border security. Modern warfare demands versatile and adaptable platforms that can operate in diverse terrains and combat conditions. Technological advancements—such as integration of artificial intelligence (AI), remote weapon stations, and active protection systems—are accelerating the replacement of legacy fleets with modern, modular systems. Governments are also investing heavily in unmanned ground vehicles (UGVs) for reconnaissance, logistics, and combat roles, contributing to market expansion. Moreover, partnerships between defense contractors and armed forces for long-term procurement and maintenance programs are fostering sustained demand. The emphasis on rapid deployment and network-centric warfare is reshaping land combat strategies. Rising cyber-threat concerns have also led to the integration of secure communication and electronic warfare systems in vehicle designs.
Regionally, North America dominates the Military Land Vehicles Market, driven by substantial investments from the U.S. Department of Defense and a focus on modernization programs like the Next Generation Combat Vehicle (NGCV). Europe follows closely, with countries such as France, Germany, and the UK enhancing their armored capabilities in response to evolving security dynamics. The Asia-Pacific region is witnessing rapid growth, particularly due to increased defense spending by China, India, and South Korea. Meanwhile, the Middle East continues to invest in armored fleets due to persistent regional conflicts and border protection initiatives. Latin America and Africa are also showing gradual progress, supported by border patrol needs and anti-insurgency efforts. Growing demand for local manufacturing and technology transfer is fostering new defense collaborations in emerging markets.
Market Insights:
- The Military Land Vehicles Market was valued at USD 23,800 million in 2024 and is expected to reach USD 29,453 million by 2032, growing at a CAGR of 2.7% during the forecast period.
- Rising demand for force mobility and tactical versatility is driving global investments in next-generation armored and utility vehicles capable of operating across varied terrains.
- Integration of artificial intelligence, remote weapon systems, and active protection technologies is transforming traditional vehicle platforms into networked, digital combat assets.
- Unmanned Ground Vehicles (UGVs) are gaining traction for roles in reconnaissance, logistics, and frontline support, driven by the need to reduce risk and enhance mission flexibility.
- North America leads the market with 39% share, backed by U.S. defense programs such as the Next Generation Combat Vehicle and JLTV modernization initiatives.
- Europe holds a 29% share, with countries like Germany, France, and the UK upgrading armored fleets and pursuing collaborative programs to enhance interoperability and industrial capacity.
- Asia-Pacific captures 22% of the market and is the fastest-growing region, supported by rising defense budgets, domestic manufacturing efforts, and security-driven modernization across China, India, and South Korea.
Market Drivers:
Rising Demand for Force Mobility and Tactical Superiority
The Military Land Vehicles Market is experiencing strong momentum due to the growing emphasis on rapid troop deployment and mobility in conflict zones. Military forces are prioritizing vehicles that can operate in diverse and harsh terrains with increased agility. Forces require platforms that offer high endurance, speed, and flexibility in responding to evolving battlefield dynamics. Armored vehicles with multi-terrain capabilities are enabling enhanced maneuverability and operational reach. It is driving investments in wheeled and tracked vehicles that meet mission-specific requirements. Governments are focusing on fleet modernization to maintain a tactical edge in active and potential conflict areas.
Integration of Advanced Combat and Surveillance Technologies
Technological innovation remains a core driver of the Military Land Vehicles Market. Armed forces are integrating artificial intelligence, real-time surveillance, and autonomous navigation systems into combat vehicles. The need for enhanced situational awareness and decision-making underlines the adoption of network-centric warfare capabilities. Smart sensors, active protection systems, and remote weapon stations are transforming traditional vehicle roles. It is encouraging the development of modular designs that allow easy integration of future upgrades. Defense agencies are also pursuing platforms compatible with drone coordination and battlefield data-sharing systems.
- For instance, in March 2023, the U.S. Army selected Northrop Grumman Corporation and Shield AI to compete in the Future Tactical Unmanned Aircraft System (FTUAS) Increment 2 program, aimed at replacing the long-serving RQ-7B Shadow tactical unmanned aerial system (UAS).
Growing Adoption of Unmanned Ground Vehicles (UGVs)
Unmanned ground vehicles are gaining traction for their ability to support reconnaissance, explosive ordnance disposal, and combat missions without risking human lives. Governments are expanding R&D programs to develop tactical UGVs with scalable payloads and autonomous capabilities. It is influencing the strategic shift towards hybrid fleet structures that include both manned and unmanned assets. Militaries are investing in AI-powered systems that enable autonomous decision-making in complex environments. These platforms reduce response time and increase mission efficiency across urban and hostile landscapes. Demand for UGVs is also linked to labor force constraints and high-risk operational demands.
- For instance, Milrem Robotics has integrated its THeMIS UGV with MBDA’s IMPACT system, enhancing precision attack capabilities.
Defense Modernization Programs and Budget Allocations
Increased defense budgets across major economies are propelling demand for next-generation military land vehicles. Modernization programs aim to replace aging fleets with vehicles that support joint operations and digital battlefield frameworks. The Military Land Vehicles Market is benefiting from long-term procurement plans and multi-national collaboration efforts. It reflects a global shift toward standardization, interoperability, and logistical efficiency. Key contracts awarded to major OEMs include lifecycle maintenance and technology insertion services. Sustained funding is allowing defense contractors to accelerate innovation and scale production capabilities.
Market Trends:
Emphasis on Modular Design and Platform Flexibility
Modular vehicle design has become a prominent trend shaping the Military Land Vehicles Market. Armed forces seek adaptable platforms that can accommodate multiple roles, from troop transport to reconnaissance and combat support. It allows militaries to reduce procurement and maintenance costs by using a common chassis across different variants. The focus on platform flexibility is driving demand for vehicles that support interchangeable mission modules and scalable armor. Manufacturers are responding with integrated solutions that align with changing tactical requirements and joint-force interoperability. The trend supports rapid upgrades in the field without extensive logistical disruptions.
- For instance, the Patria AMV XP is designed to be equipped with different firearms and turrets without altering its core platform structure, making it highly adaptable for various missions where mobility, survivability, and firepower are essential.
Rise of Electrification and Hybrid Propulsion Technologies
Electrification is emerging as a key trend as defense organizations seek to reduce fuel dependency and enhance stealth capabilities. Hybrid-electric and fully electric propulsion systems offer lower thermal and acoustic signatures, improving survivability in contested zones. The Military Land Vehicles Market is witnessing increased prototype testing of hybrid combat vehicles by leading defense manufacturers. It reflects broader efforts to align military sustainability goals with operational efficiency. Advanced battery systems and energy management technologies are enabling longer operational ranges and reduced heat emissions. Governments are funding pilot projects to evaluate the feasibility of electric drive systems in tactical and support vehicles.
- For instance, the Fuel Efficiency Demonstrator-Alpha (FED-A) vehicle, developed by the U.S. Army’s Ground Vehicle Systems Center (GVSC) and Ricardo Inc., exemplifies this trend by directly addressing the Army’s need for more fuel-efficient battlefield vehicles and supporting its sustainability initiatives.
Market Challenges Analysis:
High Development Costs and Budget Constraints
The high cost of research, development, and integration of advanced technologies poses a major challenge in the Military Land Vehicles Market. Modern vehicles require sophisticated systems, including AI-enabled targeting, advanced armor, and electronic warfare capabilities. These features significantly increase the overall cost of procurement and lifecycle maintenance. Budget constraints in several countries limit the scale of modernization programs, especially for developing economies. It restricts the ability of armed forces to adopt next-generation vehicles at the desired pace. Delays in funding approvals and shifting defense priorities further impact project timelines.
- For instance, the United States Army has demonstrated proactive investment by projecting a steady acquisition budget for ground combat vehicles, ensuring ongoing modernization and technological advancement despite fiscal pressures.
Supply Chain Disruptions and Component Shortages
Global supply chain disruptions have affected the timely production and delivery of military land vehicles. Shortages of electronic components, specialty metals, and armored materials have led to production delays and cost escalations. The Military Land Vehicles Market faces risks from geopolitical tensions and trade restrictions that impact cross-border supply flows. It makes manufacturers vulnerable to sourcing challenges and fluctuating raw material prices. Ensuring quality and consistency across international suppliers remains a critical concern. Delays in component availability also hinder upgrade cycles and field readiness of active fleets.
Market Opportunities:
Expansion of Unmanned and Autonomous Vehicle Programs
The growing interest in unmanned and autonomous military vehicles presents a significant opportunity for the Military Land Vehicles Market. Defense agencies are investing in robotic systems for logistics, reconnaissance, and combat operations to reduce personnel exposure in high-risk zones. It creates a demand for new platforms designed specifically for autonomous mobility, AI integration, and remote operation. Companies that develop scalable, interoperable solutions are well-positioned to benefit from this trend. Governments are also initiating joint development programs with private sector innovators to accelerate the deployment of autonomous land systems. The shift toward unmanned capabilities opens new revenue streams for established and emerging defense manufacturers.
Modernization Initiatives in Emerging Economies
Emerging economies are actively pursuing defense modernization to strengthen border protection and national security infrastructure. Countries in Asia, the Middle East, and Latin America are upgrading outdated fleets with technologically advanced military land vehicles. The Military Land Vehicles Market can leverage these investments by offering cost-effective, modular platforms tailored to regional needs. It creates opportunities for partnerships, technology transfers, and local manufacturing. OEMs that align with government objectives such as industrial participation and capability building can secure long-term contracts. Expanding defense budgets and strategic alliances with global suppliers support a favorable environment for market growth in these regions
Market Segmentation Analysis:
By Type
The Military Land Vehicles Market includes a diverse range of vehicle types such as armored personnel carriers (APCs), infantry fighting vehicles (IFVs), main battle tanks (MBTs), light protected vehicles (LPVs), and tactical trucks. Main battle tanks and IFVs dominate demand due to their central role in frontline combat. APCs and LPVs support safe troop transport and maneuverability in conflict zones. Tactical trucks remain essential for logistics and equipment transport across operational terrains. It reflects a balanced requirement for both offensive and support vehicle capabilities across armed forces.
By Weight Class
Weight classification in the market comprises light, medium, and heavy vehicles, each suited to different mission needs. Light vehicles are preferred for high-speed, agile operations such as reconnaissance and patrols. Medium-weight vehicles offer a combination of protection and mobility, often used in versatile combat situations. Heavy vehicles are deployed in high-threat environments where armor and firepower are prioritized. It supports strategic deployment planning by enabling forces to adapt to varying levels of threat and terrain.
By Application
Military land vehicles serve a range of applications, including combat operations, intelligence, surveillance and reconnaissance (ISR), logistics support, and engineering roles. Combat vehicles hold the largest market share, reflecting the continued need for firepower and frontline strength. ISR applications are expanding with increased demand for situational awareness and battlefield intelligence. Logistics and engineering vehicles ensure operational continuity through transport and infrastructure support. It underscores the importance of a well-rounded fleet capable of multi-domain functionality.
Segmentations:
By Type
- Armored Personnel Carriers (APCs)
- Infantry Fighting Vehicles (IFVs)
- Main Battle Tanks (MBTs)
- Light Protected Vehicles (LPVs)
- Tactical Trucks
- Self-Propelled Artillery
- Command and Control Vehicles
By Weight Class
- Light
- Medium
- Heavy
By Application
- Combat Operations
- Logistics and Supply Support
- Intelligence, Surveillance, and Reconnaissance (ISR)
- Engineering and Construction
- Medical Evacuation
- Training and Simulation
By Mobility
- Wheeled
- Tracked
- Hybrid
By Engine Power
- Less than 250 HP
- 250–500 HP
- 500–750 HP
- Above 750 HP
By Technology
- Manned
- Unmanned
- Autonomous
- Hybrid-Electric
By Armament
- Machine Guns
- Automatic Cannons
- Anti-Tank Guided Missiles (ATGMs)
- Mortars
- Non-Lethal Systems
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leads with Modernization and Defense Investments
North America holds 39% share of the global Military Land Vehicles Market, making it the leading regional segment. The region’s dominance is driven by large-scale procurement and fleet modernization initiatives led by the U.S. Department of Defense. Extensive investments in main battle tanks, armored personnel carriers, and tactical vehicles support operational readiness across multiple theaters. Programs such as the Next Generation Combat Vehicle (NGCV) and Joint Light Tactical Vehicle (JLTV) reflect a strong focus on mobility, protection, and digitization. It underscores the U.S. Army’s push for future-ready capabilities and integration with advanced communication networks. Canada also contributes through upgrades and strategic partnerships under NATO commitments. The presence of established defense manufacturers and R&D infrastructure reinforces sustained market leadership.
Europe Advances Strategic Readiness Through Collaborative Programs
Europe accounts for 29% of the global Military Land Vehicles Market, ranking as the second-largest regional contributor. The region continues to invest in land vehicle capabilities to strengthen strategic readiness and address evolving defense challenges. Countries such as Germany, France, the UK, and Poland are replacing outdated fleets with modern platforms that offer modularity, protection, and digital integration. Joint development initiatives, including the European Main Battle Tank (EMBT), support regional interoperability and production scale. It benefits from strong political alignment on collective security under NATO frameworks. European manufacturers are leveraging domestic demand and international exports to enhance technological leadership. Ongoing tensions in Eastern Europe are accelerating deployment and procurement timelines.
Asia-Pacific Emerges as a High-Growth Market with Strategic Priorities
Asia-Pacific holds 22% share of the Military Land Vehicles Market, placing it third globally while showing the fastest growth momentum. Regional defense spending continues to rise in response to geopolitical tensions and modernization goals. China, India, South Korea, and Japan are actively expanding domestic manufacturing and investing in indigenous land vehicle programs. It reflects national priorities to enhance mobility, border protection, and technological self-reliance. Initiatives such as India’s Make in India and South Korea’s K2 Black Panther project aim to boost local production and export capabilities. ASEAN countries are also scaling procurement efforts to address internal security and peacekeeping needs. The region supports sustained demand for advanced, terrain-adaptable, and cost-efficient platforms.
Key Player Analysis:
- BAE Systems
- Rhenmetall
- General Dynamics
- Iveco
- Otokar
- Oshkosh Corporation
- Lockheed Martin Corporation
- Thales Group
- ST Engineering
- Achleitner
- Ashok Leyland
- Krauss-Maffei Wegmann
- John Deere
Competitive Analysis:
The Military Land Vehicles Market features strong competition among global defense contractors focused on innovation, modularity, and long-term defense partnerships. Leading players include General Dynamics Corporation, BAE Systems, Rheinmetall AG, Oshkosh Defense, and Hanwha Defense. These companies invest heavily in R&D to develop advanced platforms with improved survivability, firepower, and mobility. The market also sees increased collaboration between governments and manufacturers through multi-year procurement programs and offset agreements. It encourages the development of region-specific solutions, joint ventures, and technology transfers to meet evolving operational requirements. Players compete on product performance, integration capabilities, lifecycle support, and cost-efficiency. The Military Land Vehicles Market rewards firms that offer scalable solutions and respond quickly to shifting defense priorities. Competitive dynamics are further shaped by rising demand for unmanned systems and hybrid propulsion technologies, prompting firms to diversify offerings and expand production footprints. Emerging players gain ground by aligning with national manufacturing goals and offering localized support.
Recent Developments:
- In March 2024, BAE Systems launched a $4.8 billion multi-tranche bond deal to finance the Ball Aerospace acquisition and refinance existing debt.
- In April 2024, Achleitner entered a strategic partnership with Dutch manufacturer Defenture to deliver GRF (Ground Force) vehicles to the Austrian Ministry of Defence.
Market Concentration & Characteristics:
The Military Land Vehicles Market is moderately concentrated, with a mix of global defense giants and regional manufacturers competing for contracts. It features high entry barriers due to strict regulatory requirements, complex procurement cycles, and the need for advanced technological capabilities. The market is characterized by long development timelines, multi-year contracts, and strong government influence. Key players maintain their position through strategic alliances, R&D investments, and integration of next-generation systems. It demands continuous innovation in mobility, survivability, and digital connectivity to meet evolving military doctrines. Customization, interoperability, and aftersales support remain critical differentiators. The market supports a combination of legacy fleet upgrades and new vehicle development across varied operational environments.
Report Coverage:
The research report offers an in-depth analysis based on Type, Weight Class, Application, Mobility, Engine Power, Technology, Armament and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Defense agencies are prioritizing modular vehicle designs to enhance operational flexibility and reduce lifecycle costs.
- The integration of artificial intelligence and autonomous systems is advancing, enabling improved decision-making and mission adaptability.
- Electrification efforts, including hybrid and fully electric propulsion systems, are gaining traction to meet sustainability goals and reduce logistical burdens.
- Unmanned ground vehicles are being developed for reconnaissance, logistics, and combat support roles, expanding operational capabilities.
- Enhanced survivability features, such as active protection systems and advanced armor, are being incorporated to counter emerging threats.
- Digitalization of command and control systems is improving situational awareness and interoperability among allied forces.
- Investments in indigenous manufacturing and technology transfer are strengthening domestic defense industries in various regions.
- The focus on rapid deployment and expeditionary capabilities is influencing the development of lighter, more mobile platforms.
- Collaborative international programs are fostering standardization and interoperability across different military forces.
- Continuous modernization initiatives are driving the replacement of aging fleets with advanced, multi-role military land vehicles.Bottom of Form
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected size of the Military Land Vehicles Market?
What is driving the growth of the Military Land Vehicles Market?
Which region leads the Military Land Vehicles Market?
Why are unmanned ground vehicles (UGVs) gaining importance?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Military Land Vehicles Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Military Land Vehicles Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 23,800 million → 2032: USD 29,453 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Military Land Vehicles Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Military Land Vehicles Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Military Land Vehicles Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Military Land Vehicles Market Drivers
- 3.3 Military Land Vehicles Market Restraints & Challenges
- 3.4 Military Land Vehicles Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Military Land Vehicles Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Military Land Vehicles Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Military Land Vehicles category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Military Land Vehicles Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Military Land Vehicles Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Military Land Vehicles market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Military Land Vehicles Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Military Land Vehicles Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Military Land Vehicles Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Military Land Vehicles (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Military Land Vehicles Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Military Land Vehicles Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Military Land Vehicles Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Military Land Vehicles Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Military Land Vehicles Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Military Land Vehicles Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Military Land Vehicles Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Military Land Vehicles Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Military Land Vehicles Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
