
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Military Surveillance Drones Market Size 2024 | USD 4223 million |
| Military Surveillance Drones Market, CAGR | 11.7% |
| Military Surveillance Drones Market Size 2032 | USD 10234.02 million |
Market Overview:
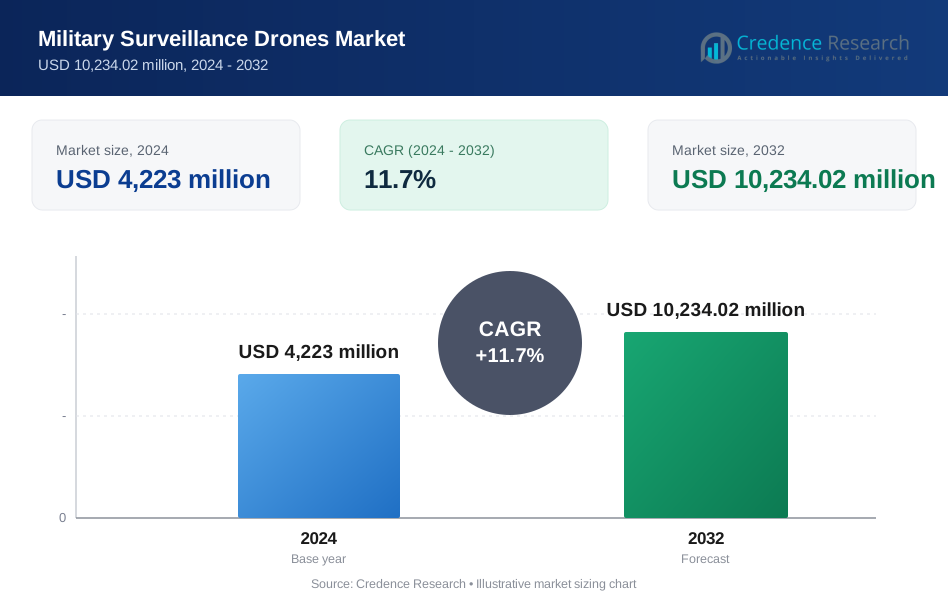
The Military Surveillance Drones Market is projected to grow from USD 4223 million in 2024 to an estimated USD 10234.02 million by 2032, with a compound annual growth rate (CAGR) of 11.7% from 2024 to 2032.
The military surveillance drones market is gaining momentum due to a combination of strategic, technological, and operational drivers. One of the primary growth catalysts is the increasing need for real-time intelligence, surveillance, and reconnaissance (ISR) across volatile geopolitical zones. Armed forces worldwide are leveraging drones to enhance situational awareness and support mission-critical operations without endangering personnel. Rapid advancements in drone technologies, including the integration of artificial intelligence (AI), advanced optics, thermal imaging, and autonomous navigation systems, are significantly boosting the operational capabilities of these platforms. Moreover, increased defense budgets across developed and developing nations are enabling large-scale procurement of next-generation unmanned aerial systems. Countries such as the United States, China, India, and Israel are heavily investing in indigenous drone development programs to strengthen their military capabilities.
North America dominates the military surveillance drones market, accounting for the largest share due to sustained investments in defense technology and the presence of major drone manufacturers such as Northrop Grumman, General Atomics, and Lockheed Martin. The U.S. Department of Defense continues to prioritize ISR capabilities, contributing significantly to the region’s market leadership. In the Asia-Pacific region, the market is witnessing the fastest growth, fueled by rising defense expenditures and security concerns in countries like China, India, South Korea, and Japan. India, in particular, is investing in drone acquisition and joint development initiatives as part of its defense modernization efforts. Europe follows closely, with countries like the United Kingdom, France, and Germany enhancing their surveillance infrastructure and participating in joint defense collaborations under the European Union framework. The Middle East and Africa (MEA) region is also emerging as a key growth area, driven by the need for surveillance solutions in response to regional conflicts, terrorism, and border control.
Market Insights:
- The Military Surveillance Drones Market is projected to grow from USD 4,223 million in 2024 to USD 10,234.02 million by 2032, registering a CAGR of 11.7%.
- Rising demand for real-time ISR capabilities in conflict-prone zones is accelerating drone deployment by global armed forces.
- Advancements in AI, thermal imaging, and autonomous flight systems are transforming drones into intelligent surveillance assets.
- Increased defense budgets in countries like the U.S., China, and India are fueling large-scale procurement and domestic drone development.
- Heightened geopolitical tensions and evolving security threats are pushing nations to expand drone-based border and territorial surveillance.
- Regulatory complexities and cybersecurity risks remain major challenges, requiring investment in secure communications and compliance systems.
- North America leads with the largest market share, while Asia-Pacific emerges as the fastest-growing region due to rapid defense modernization.
Market Drivers:
Growing Demand for Real-Time Intelligence and Surveillance
Modern warfare requires real-time situational awareness, prompting defense forces to rely on unmanned aerial systems for persistent intelligence, surveillance, and reconnaissance (ISR). Military surveillance drones offer unmatched aerial visibility, enabling forces to track movements, detect threats, and respond quickly to battlefield dynamics. Their ability to operate in high-risk or hostile environments without endangering personnel significantly enhances mission safety and effectiveness. The growing emphasis on border monitoring, counter-insurgency operations, and homeland security further drives the demand for ISR capabilities. Governments are deploying drones to patrol critical infrastructures, detect illegal activities, and improve tactical decision-making. The Military Surveillance Drones Market is benefiting from this rising operational dependence, positioning ISR capabilities as central to modern defense strategy.
- For example, the Ukrainian military has publicly stated its goal of deploying up to 200,000 drones for reconnaissance and tactical purposes, reflecting a massive scale-up in operational drone use for real-time battlefield intelligence.
Technological Advancements Enhancing Drone Capabilities
Rapid innovations in drone technology are transforming military surveillance platforms into highly autonomous and intelligent systems. Integration of artificial intelligence (AI), machine learning algorithms, and advanced sensors has improved target detection, data processing, and autonomous flight. It allows drones to interpret vast datasets in real time and support missions with minimal human intervention. Enhanced features such as thermal imaging, high-resolution cameras, and stealth designs are expanding their roles in various terrains and mission types. Increased payload capacities and endurance further allow for extended surveillance missions, improving operational reach. These advancements continue to attract defense investments, reinforcing the position of drone technology in modern warfare.
- For instance, modern drones feature miniaturized high-resolution cameras, multispectral sensors, and encrypted data feeds, allowing even small UAVs to deliver detailed surveillance imagery in real time.
Rising Defense Expenditure and Strategic Procurement Programs
Increased global defense budgets are enabling military organizations to invest in unmanned systems for surveillance, reconnaissance, and combat support. Countries such as the United States, China, India, and Russia are actively modernizing their armed forces through large-scale procurement of surveillance drones. Many governments are implementing long-term defense modernization plans that prioritize unmanned aerial platforms to enhance border security and tactical intelligence. These programs also include international collaborations, joint ventures, and technology transfer initiatives aimed at boosting local drone manufacturing capabilities. It supports market growth by creating robust procurement pipelines and reducing reliance on legacy systems. The rising defense spending underscores a strong institutional commitment to integrating drones into strategic operations.
Heightened Geopolitical Tensions and Border Security Concerns
Escalating tensions in regions such as Eastern Europe, the South China Sea, and the Middle East are amplifying the need for advanced surveillance solutions. Military surveillance drones provide a low-risk and cost-effective method to monitor disputed territories and critical border zones. Governments are increasingly deploying drones to deter infiltration, conduct reconnaissance, and enforce no-fly zones. It helps nations respond to real-time threats without escalating conflict or exposing troops to direct harm. The ability to conduct continuous, unmanned monitoring gives defense forces a tactical advantage in volatile regions. This geopolitical climate is reinforcing the importance of drone-based surveillance systems in national defense architectures.
Market Trends:
Shift Toward Autonomous and AI-Enabled Surveillance Drones
Global defense agencies are increasingly prioritizing autonomous and AI-powered drones to enhance surveillance efficiency and minimize operator intervention. These advanced systems can process large volumes of visual and sensor data in real time, enabling faster decision-making during tactical operations. AI integration supports object recognition, behavioral pattern analysis, and mission adaptability under dynamic combat conditions. The shift reduces the cognitive load on personnel while expanding operational scalability. It empowers military units to conduct long-endurance missions with minimal ground control involvement. The Military Surveillance Drones Market is witnessing steady integration of AI to meet the evolving demands of real-time situational awareness.
- For example, U.S. defense startup Anduril has delivered its AI-powered Bolt drones to the U.S. Marine Corps as part of the Force Design modernization program. These man-packable drones feature vertical takeoff and landing (VTOL) capabilities and are equipped with advanced AI for precision firepower, enabling real-time data processing and decision-making during tactical operations.
Increased Investment in Swarm Drone Capabilities
Swarm technology is emerging as a key trend, enabling multiple drones to coordinate simultaneously across vast areas. Defense forces are experimenting with swarm algorithms to enhance battlefield intelligence and create adaptive surveillance networks. These systems can conduct reconnaissance, map terrains, and track targets with high redundancy and resilience against jamming or interception. Swarm drones also enable low-cost, distributed surveillance that can overwhelm enemy detection systems. The military sector views swarm capabilities as a critical force multiplier, especially for missions in contested environments. It supports the development of next-generation drone fleets that offer both flexibility and operational depth.
- For instance, in 2022, the U.S. Defense Advanced Research Projects Agency (DARPA) demonstrated a swarm of over 150 drones controlled by a single operator, with projections that AI-enabled swarms could scale to 1,000 drones within five years
Growing Preference for High-Altitude Long-Endurance (HALE) and Medium-Altitude Long-Endurance (MALE) Drones
Defense organizations are increasingly favoring HALE and MALE drones for their extended endurance and wide-area surveillance capabilities. These drones can operate for more than 24 hours at high altitudes, providing persistent ISR coverage over strategic zones. Their large payload capacity supports multiple sensor integrations, including radar, infrared, and communication relays. HALE and MALE platforms are now replacing manned aircraft for long-duration surveillance missions due to their lower operational costs and reduced risk to human life. It is driving military procurement programs focused on endurance, precision, and data acquisition. The Military Surveillance Drones Market reflects a growing shift toward these platforms for strategic advantage.
Expansion of Indigenous Drone Development and Export Programs
Countries are increasing investments in local drone development programs to reduce import dependency and strengthen defense self-reliance. Governments are launching national initiatives to boost indigenous manufacturing, supported by defense partnerships and joint research efforts. These initiatives aim to build domestic supply chains and create export-ready surveillance drone platforms. Defense exporters are also expanding their portfolios to meet international demand for cost-effective and technologically advanced drones. It positions locally developed drones as competitive alternatives to U.S. or Israeli systems. The trend strengthens regional defense ecosystems and fosters market competition at a global scale.
Market Challenges Analysis:
Regulatory Restrictions and Airspace Management Complexity
The integration of military surveillance drones into national and international airspace presents significant regulatory and logistical challenges. Many countries lack standardized frameworks governing the operation of unmanned systems in controlled airspace, creating legal and operational uncertainties. The risk of mid-air collisions, interference with civilian aviation, and breach of airspace sovereignty requires stringent coordination and compliance. Regulatory fragmentation across regions complicates cross-border drone deployment and limits operational scalability. Defense agencies must also invest in secure communication links and collision avoidance systems to meet evolving safety standards. The Military Surveillance Drones Market faces pressure to align with diverse and dynamic air traffic control regulations to ensure safe and lawful operations.
- For instance, the U.S. Federal Aviation Administration (FAA) has implemented strict requirements for military and civilian drone operations, mandating that all unmanned aircraft operating in controlled airspace must be equipped with Automatic Dependent Surveillance–Broadcast (ADS-B) Out technology and comply with specific flight restrictions.
Cybersecurity Threats and Data Integrity Concerns
The increasing reliance on digital systems and wireless communication makes military drones vulnerable to cyberattacks and electronic warfare. Adversaries may attempt to intercept, jam, or manipulate drone communications, potentially compromising mission-critical data or control systems. Ensuring the integrity, confidentiality, and availability of surveillance data requires robust encryption, secure protocols, and redundant systems. Development and maintenance of such cybersecurity measures add cost and complexity to drone programs. It creates challenges for both established manufacturers and emerging defense startups seeking to meet strict military-grade security requirements. The Military Surveillance Drones Market must continuously adapt to evolving cyber threats to protect national security interests and maintain operational reliability.
Market Opportunities:
Expansion of Tactical ISR Missions in Conflict Zones
Rising global conflicts and border tensions are creating strong demand for agile and tactical ISR capabilities. Military surveillance drones offer low-risk, high-reward solutions for real-time monitoring in active war zones and contested territories. Armed forces are prioritizing rapid deployment of small to medium-sized UAVs that can support infantry and special operations units. The Military Surveillance Drones Market benefits from the increasing shift toward decentralized surveillance models. It enables defense agencies to maintain persistent situational awareness without relying solely on satellite or manned aircraft support. Emerging drone variants optimized for stealth and mobility present new avenues for tactical applications.
Government-Led Defense Modernization and Export Incentives
Many nations are launching strategic initiatives to develop indigenous drone capabilities and strengthen local defense manufacturing. These efforts include government funding, policy support, and export facilitation to boost the competitiveness of domestic drone programs. Countries like India, Turkey, and South Korea are building scalable platforms designed for both national use and international defense markets. It opens new growth opportunities for partnerships, licensing, and supply chain integration across regions. The Military Surveillance Drones Market stands to benefit from this global push toward self-reliant defense ecosystems and expanded access to new procurement channels. Rising exports of cost-effective, combat-tested drones offer long-term market traction.
Market Segmentation Analysis:
The Military Surveillance Drones Market is segmented by type, technology, application, and payload, each reflecting specific operational demands and technological advancements.
By type, Fixed-wing drones dominate in long-range missions due to their endurance and high-altitude capability, making them ideal for strategic ISR operations. Rotary-wing drones provide vertical take-off and landing features suited for urban and confined areas, while hybrid drones combine flexibility and range, gaining traction in tactical environments.
By technology, hardware leads the market share due to the critical role of sensors, airframes, and communication systems. Software is gaining prominence with the rise of AI-driven analytics, autonomous flight control, and real-time data processing, enhancing operational efficiency.
By application, border surveillance and battlefield monitoring are the leading segments, driven by rising geopolitical tensions and regional conflicts. Target acquisition and reconnaissance missions continue to expand with the need for precision strikes and real-time intelligence. Maritime surveillance and search and rescue are niche but growing areas, supported by coastal security initiatives.
By Payload segmentation shows strong demand for EO/IR sensors and radar systems, essential for all-weather, day-night operations. LiDAR and communication relay systems support situational awareness and secure command connectivity, reinforcing their importance across modern deployments.
Segmentation:
By Type:
- Fixed-Wing Drones
- Rotary-Wing Drones
- Hybrid Drones
By Technology;
- Hardware,
By Application:
- Border Surveillance
- Battlefield Monitoring
- Target Acquisition
- Reconnaissance & Intelligence Gathering
- Search and Rescue Operations
- Maritime Surveillance
By Payload:
- Electro-Optical/Infrared (EO/IR) Sensors
- Radar Systems
- LiDAR
- Cameras
- Communication Relay Systems
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America dominates the Military Surveillance Drones Market with a market share of 41%. The United States leads regional growth due to extensive defense budgets, advanced R&D infrastructure, and the presence of key manufacturers such as Northrop Grumman, General Atomics, and Lockheed Martin. The Department of Defense continues to prioritize unmanned systems across all branches of the military, accelerating procurement and innovation. Integration of AI, long-endurance platforms, and advanced ISR payloads supports the operational versatility of drones in the U.S. armed forces. Canada also contributes to regional expansion through cross-border collaborations and surveillance modernization programs. It maintains a strong focus on homeland security and strategic deterrence, which supports the region’s technological leadership.
Asia Pacific holds the second-largest market share at 29%, driven by escalating geopolitical tensions and rising defense expenditures across China, India, South Korea, and Japan. China is heavily investing in UAV technology through its military-industrial complex, focusing on both development and global export. India is accelerating procurement under defense modernization programs, emphasizing surveillance capabilities for border security. Regional conflicts and territorial disputes in the South China Sea and along national boundaries have intensified ISR deployment across Asia. Domestic drone production is gaining momentum with policy support and joint ventures. The Military Surveillance Drones Market in this region is expanding rapidly due to the increasing adoption of tactical and strategic UAV platforms.
Europe accounts for 18% of the market share, supported by rising defense integration under the European Union and national-level investments in unmanned surveillance. Countries such as France, Germany, and the United Kingdom are advancing ISR capabilities through joint programs and indigenous drone platforms. The European Defence Fund (EDF) and Permanent Structured Cooperation (PESCO) are fueling collaborative R&D efforts. Demand for surveillance drones is growing due to increased focus on border protection, NATO-led operations, and hybrid warfare preparedness. Governments are also pushing for cybersecurity and airspace regulatory frameworks to support drone operations. It reflects a broader push for operational autonomy and defense resilience across the European continent.
Key Player Analysis:
- AeroVironment, Inc.
- Airbus SAS
- Boeing
- Elbit Systems Ltd.
- General Atomics
- Israel Aerospace Industries Ltd.
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- Saab AB
- Thales Group
Competitive Analysis:
The Military Surveillance Drones Market is highly competitive, with major defense contractors and emerging firms vying for technological leadership and global contracts. Key players include Northrop Grumman Corporation, General Atomics Aeronautical Systems, Lockheed Martin Corporation, Elbit Systems Ltd., Israel Aerospace Industries, and AeroVironment Inc. These companies focus on enhancing drone endurance, stealth, payload capacity, and autonomous capabilities to meet evolving defense requirements. Strategic collaborations, defense tenders, and export agreements strengthen their global presence. It remains driven by innovation in AI-based ISR systems, sensor fusion, and real-time data analytics. Regional manufacturers from countries like China and Turkey are expanding their footprint through cost-effective, combat-tested platforms. The market continues to evolve with rapid prototyping, government-backed R&D programs, and a rising emphasis on localized drone production. Competitive intensity is expected to increase with growing demand for tactical and long-endurance UAVs across multiple defense theatres.
Recent Developments:
- In May 2025, AeroVironment signed a contract with the Dutch Ministry of Defence to modernize the Netherlands’ Puma UAS fleet and deploy scalable long-endurance systems. The agreement includes upgrades to the Puma 3 AE drones, such as enhanced survivability, improved communications, and support for vertical take-off and landing (VTOL) capabilities, as well as the acquisition of the Puma LE for extended endurance and range.
- In April 2025, General Atomics Aeronautical Systems, Inc. (GA-ASI) made headlines for two significant developments. First, on April 7, 2025, GA-ASI announced expanded targeting capabilities for its MQ-9B SeaGuardian drone through new software that enables in-flight target updates, validated in a systems integration lab and set for live-fire demonstration.
- In late May 2025, Lockheed Martin announced a partnership with Red Hat to accelerate the autonomy of uncrewed aerial vehicles by enabling rapid deployment of swarm autonomy technologies. This collaboration aims to enhance the real-time responsiveness and mission flexibility of drone swarms, particularly through the Skunk Works’ Indago 4 UAS platform.
Market Concentration & Characteristics:
The Military Surveillance Drones Market exhibits a moderately high level of concentration, with a few dominant players accounting for a significant share of global sales and technology leadership. It is characterized by high entry barriers due to regulatory compliance, complex integration requirements, and extensive capital investment. Leading companies leverage government contracts, proprietary technologies, and long-standing defense relationships to maintain their positions. The market favors innovation in ISR systems, secure communication, and endurance capabilities, with procurement cycles often spanning several years. It is driven by mission-specific customization and regional defense priorities, making flexibility and scalability critical attributes. Competitive dynamics are influenced by geopolitical alliances, national security strategies, and evolving warfare doctrines.
Report Coverage:
The research report offers an in-depth analysis based on type, technology, application, and payload. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Global demand will rise as nations prioritize real-time intelligence and border security modernization.
- AI and machine learning integration will enable autonomous target recognition and data analysis.
- Tactical drones will gain traction for short-range ISR missions in urban and contested environments.
- Swarm drone technology will advance, supporting coordinated surveillance and battlefield awareness.
- Defense export programs will expand, with emerging economies entering the global UAV supply chain.
- Long-endurance drones will replace manned aircraft in persistent surveillance operations.
- Cybersecurity and anti-jamming capabilities will become essential in procurement decisions.
- Governments will invest in indigenous manufacturing to reduce foreign dependency and ensure operational sovereignty.
- NATO and allied countries will increase joint development efforts to standardize ISR platforms.
- Regulatory frameworks will evolve to support cross-border drone operations and shared airspace usage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Military Surveillance Drones Market?
What factors are driving the growth of the Military Surveillance Drones Market?
What are some challenges faced by the Military Surveillance Drones Market
Who are the major players in the Military Surveillance Drones Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Military Surveillance Drones Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Military Surveillance Drones Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,223 million → 2032: USD 10,234.02 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Military Surveillance Drones Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Military Surveillance Drones Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Military Surveillance Drones Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Military Surveillance Drones Market Drivers
- 3.3 Military Surveillance Drones Market Restraints & Challenges
- 3.4 Military Surveillance Drones Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Military Surveillance Drones Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Military Surveillance Drones Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Military Surveillance Drones category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Military Surveillance Drones Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Military Surveillance Drones Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Military Surveillance Drones market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Military Surveillance Drones Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Military Surveillance Drones Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Military Surveillance Drones Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Military Surveillance Drones (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Military Surveillance Drones Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Military Surveillance Drones Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Military Surveillance Drones Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Military Surveillance Drones Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Military Surveillance Drones Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Military Surveillance Drones Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Military Surveillance Drones Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Military Surveillance Drones Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Military Surveillance Drones Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
